Aug 312026
 
 August 31, 2026  Posted by at 10:05 am Finance Tagged with: , , , , ,  38 Responses »


J.M.W. Turner Old London Bridge 1794


• No, Iran Is Not Winning: It’s Losing Its Leverage In Hormuz (CNN)
• Pentagon Strikes Iran Island Target, In First US Military Action In Weeks (ZH)
• Moscow and Kiev Exchange Attacks, But Only One Side Feels Impact (CTH)
• Renaming a Lake: A Surefire Way to Expose the Corrupt (Florack)
• CIA Director Pushed Trump-Putin-Zelensky Summit During Moscow Visit (ZH)
• U.S. Visa Restrictions, Reviews and Applicant Suspensions (CTH)
• Trump Nukes NBC’s Kristen Welker Again (Matt Margolis)
• Trump Advises Corporations to Depart Canada for Stability in USA (CTH)
• James Clyburn Basically Says Clarence Thomas ‘Ain’t Black’ (Matt Margolis)
• California Lawmakers Keep Giving Businesses Reasons to Leave (David Manney)
• Michelle Obama Proves Again She’s a Horrible Person (Matt Margolis)


https://twitter.com/CaseyKrol/status/2093661891960742319?s=20 https://twitter.com/BasilTheGreat/status/2093980276099539329?s=20 https://twitter.com/nicksortor/status/2094133199970443534?s=20 https://twitter.com/BoLoudon/status/2093788594448007295?s=20


Must have taken some pain at CNN to admit this.

Brett McGurk is a CNN global affairs analyst who served in senior national security positions under Presidents George W. Bush, Barack Obama, Donald Trump and Joe Biden.

“..this new fourth act — a military embargo — is something that Iran has never confronted before.

He does maintain it’s a recent development. It’s not. Iran was never winning.

• No, Iran Is Not Winning: It’s Losing Its Leverage In Hormuz (CNN)
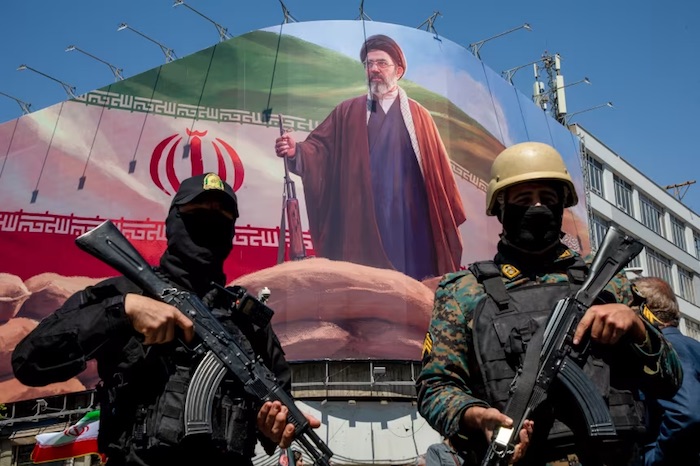
A conventional wisdom has begun to settle over the war with Iran: Iran won. The argument is straightforward. The US and Israel bombed Iran for weeks, inflicted enormous damage, and demanded major concessions. Iran refused to surrender. Its government remains in power. Its missiles remain a threat across the region. And most important, Tehran still has the ability to disrupt shipping through the Strait of Hormuz, imposing higher energy costs on the US and much of the world. Over the summer, Trump warned of a global depression if the Strait remained shut.


The fourth act
That’s a strong argument. But it may have proved premature. Wars are contests of leverage and endurance. And the contest now looks very different from even a few months ago. The arc of this six-month conflict has proceeded in four acts. Act One began with intensive airstrikes on February 28 and lasted through six weeks of high-intensity military operations. Act Two began with the April 7 ceasefire and negotiations, culminating with the June 17 MOU signed by Trump and Iran’s president, Masoud Pezeshkian. Act Three began weeks later when Iran chose once again to target commercial ships in the Strait of Hormuz, leading to another tit-for-tat military exchange.

That was the moment calls rose for the US effectively to give up and cede control of the Strait to Iran. The United States appeared to be out of options. Not so fast.

Since mid-July, the US has reimposed its military blockade on Iranian ports and sanctions on Iran’s oil trade. In parallel, the U.S. military has worked tirelessly to clear shipping lanes and help protect commercial ships transiting the Strait. The result has been an effective blockade on Iranian oil shipments, with global shipments recovering and energy prices remaining remarkably stable. Bloomberg reported this week that oil flows through the Strait have recovered to 2/3 of pre-war levels. That means pressure is now compounding on Iran, and not the US. And if Iran loses its ability to hold the Strait hostage, its leverage dissipates rapidly.

A better US strategy
Iran entered the war weakened by years of sanctions and economic mismanagement. Its position today is considerably worse.mAccording to the International Monetary Fund, Iran’s economy is expected to contract by more than 5% this year, with inflation approaching 70%. The value of Iran’s currency has fallen sharply. Prices for basic goods have soared. An Iranian Labor Ministry official recently estimated that more than one million jobs disappeared during the first three months of the war alone.

These statistics matter because Iran’s ability to sustain the conflict ultimately depends on more than its remaining missile arsenal. Before the war, the Iranian regime confronted unprecedented public pressure against its repressive rule and failing economy. Thousands of Iranians were reportedly killed in the streets.A better American strategy from the start may have been an economic campaign to support the Iranian people demanding change. The first act of the war — removing most of Iran’s leaders — resulted in consolidation by the Revolutionary Guards and further crackdowns against the majority of Iranians that oppose their rule.

But the Guards require resources to rule by force, and this new fourth act — a military embargo — is something that Iran has never confronted before. Indeed, this is the first time since the 1979 Revolution that Iran has faced a quarantine on its economic lifeline through Hormuz. Their way out is to stop threatening ships in the Strait and abandon what’s left of its mostly destroyed enrichment program. That’s a deal Trump would accept. Doing either, however, from the vantage point of the Guards would show weakness and threaten their rule.

Iran’s cards
Tehran may seek to fight its way out of this noose. Its strategy through the first three acts was clear: threaten commerce in the Strait, raise energy prices globally and gasoline prices in the US, increase global economic pressure and ultimately force Trump to back down, particularly with midterm elections approaching. Iran has also targeted the energy infrastructure of the Gulf states and could do so again. Its proxy force in Yemen, the Houthis, have threatened to shut down commerce through the Red Sea with Iranian missiles and drones.

All that would mean resorting to the same tactics from the early acts of the war. Strategically, it has not worked for Iran. The Gulf states are not happy with the war, but most do not support giving in to Iran’s extortionist demands in the Strait. Iran’s attempts to close the Strait with drones and mines are also now — for the first time — failing.So, I would not discount the risk of an Iranian escalation as the economic pressure builds. But it may not be enough at this stage to reduce that pressure. Trump appears far more committed than Iranian leaders apparently presumed.

Breaking point
Iranian leaders and many Western analysts project immunity to pressure. Iran will never surrender its nuclear program or the Strait of Hormuz. Or its terrorist proxies around the region. That’s something we all must accept as a fact of life in the Middle East, according to Tehran.Foreign Minister Abbas Araghchi argued last week that the blockade and sanctions pressure are “bound to fail” just as all other campaigns, he said, had failed to change Iranian policy. I used to hear the same thing from experts about ISIS, when I was leading the campaign to defeat the group. And Hamas, when negotiating to free the hostages held in Gaza.

Not the last act
In fact, everyone has a breaking point. Iran thought it had found Trump’s. Trump may yet find theirs. It’s too early to call. This contest in some form may last through the end of Trump’s presidency and beyond. It’s been ongoing for nearly five decades. The earlier acts in this war were mired from the US side by shifting and ill-defined objectives, widely careening positions, and inconsistent statements.

But Act Four seems different. The US military has a clear objective as outlined this week by the commander of CENTCOM, Admiral Brad Cooper. It is enforcing the blockade on Iran and facilitating the movement of commercial traffic. The objective for the US should be similarly well-defined. Iran must abandon claims on the Strait and give up the nuclear enrichment program. Until then, this will be the new status quo. And that status quo — perhaps for the first time since the war began — now favors Washington, not Tehran.

Read more …

“It’s not enough for the regime to survive if the economy they oversee dies.”:”

• Pentagon Strikes Iran Island Target, In First US Military Action In Weeks (ZH)

Things have been quiet for many days and weeks on the military front when it comes to the Iran war, but on Sunday there are some emerging reports of new but limited US strikes. According to the latest late Sunday from Axios:


Senior American official: Earlier today, American forces attacked two Iranian launchers on Larzac Island. Revolutionary Guard forces were observed preparing to launch rockets carrying sea mines toward the Strait of Hormuz. So despite the White House signaling a move away from military action and toward the economic warfare front, it’s also clear that more sporadic tit-for-tat blows could follow. But Trump has lately made clear that military options are still on the table, and strikes will be utilized as needed.

* * *

Propaganda has always been a problem when it comes to the fog of war. The internet and social media add a new dimension to the confusion as conflicting information is allowed to spread like wildfire using civilians and media outlets as tools for propagation. The lack of confirmation is exploited, often by both sides, and the truth becomes lost in the mire. That said, the facts on the ground will eventually see the light regardless of spin. In the case of the war in Iran, the facts on the ground do not bode well for the Islamic Regime.

Iranian leaders now openly admit that the US blockade has crippled around 35% of the nation’s exports and imports while domestic prices continue to skyrocket by 60% or more. This, however, is not the most immediate problem for the regime. It would appear that initial reports of gasoline shortages across Iran did not convey the true scope of the crisis. In the past week alone more evidence from within Iran has hit social media, showing mass lines at gas stations and panic among citizens as rationing is introduced.

Energy officials have acknowledged a gasoline deficit of roughly 15 million liters every day, warning that strategic reserves have reached “dark red” territory. Iran has ten main operating oil refineries plus the large Persian Gulf Star condensate refinery, which is the country’s biggest gasoline producer, meaning, they do have the capability to produce their own domestic gasoline supply. So, why the shortages?

Some refined products are shipped into Iran from foreign sources and the US blockade is stifling that supply. However, there is also the possibility that the blockade has forced Iran to shut down a number of oil wells due to lack of storage. Depending on the type of well, a shutdown can cause extensive damage and prevent new production for years to come. It’s likely that Iran’s crisis is rooted in an oil supply problem as much as a refining problem.

The Iranians have recently called for a return to the standards set by the MOU agreement with the US, and they have also accused the US of committing “war crimes”, arguing that the blockade is causing a humanitarian crisis.

The recent admissions of economic damage, the fuel shortages and the assertions of humanitarian crisis are a sharp tone shift from Iran’s posture only a month ago. Couple this with the 400% surge in ships traversing the Strait of Hormuz and it would seem that Iran is losing the war outright. If the blockade continues for another few months the financial damage could be irreversible and repairing resource flows could take years.

It’s not enough for the regime to survive if the economy they oversee dies.

Read more …

“.. about 90% of the food-logistics infrastructure used by major retail chains [..] has been destroyed.”

Russia’s economy is much less centralized. Bread comes from the baker on the corner, not some factory 100 miles away.

• Moscow and Kiev Exchange Attacks, But Only One Side Feels Impact (CTH)
I mentioned this last night, and now more solid reports have emerged. Basically, Ukraine and Russia are taking turns striking each other’s warehouses and distribution centers with missiles and drones. However, the brunt of the damage and chaos is being felt only by one side—Ukraine. Zero Hedge has a solid article explaining the dynamics:


“A Russian drone struck a Ukrainian Defense Forces ammunition storage site in the village of Myla Friday evening, just west of Kiev. The resulting fire and hours of secondary detonations killed at least 37 people, injured dozens more, damaged around 50 residential buildings and a care home for the elderly and disabled, and forced the evacuation of hundreds. Among the dead was the local community head who had gone to help.

In response, Ukrainian President Volodymyr Zelensky said the placement of a weapons depot next to civilians was “terrible negligence.” The first impact, he said, hit a depot storing shells, mines, other munitions, and drones that “definitely shouldn’t have been there” – while prosecutors in Kiev opened a criminal investigation into the legality of storing explosives next to civilian housing. This is the second such incident in two months. A July strike on a depot in nearby Vyshneve produced similar secondary blasts, deaths, and later detentions of state defense-company executives.

Russia’s Defense Ministry said the Myla site held components and launch boosters for long-range drones. It also claimed strikes on Flamingo cruise-missile related facilities in the Kiev region and on the ports of Mykolaiv and Izmail. Social-media claims that Patriots were stored there remain unconfirmed by official Ukrainian statements.” Here comes the fact that few in the west understand:

Friday night’s blast came amid a multi-day Russian campaign of jet-powered drones and missiles that has produced near-continuous air-raid alerts over Kiev and hit warehouses belonging to supermarket chains, postal operators, retailers, and logistics firms. Ukraine Agriculture Minister Taras Vysotskyi told reporters that, “roughly speaking,” about 90% of the food-logistics infrastructure used by major retail chains (large distribution centers serving networks such as Fora, Silpo, NOVUS, and Varus) has been destroyed.

[…] Both sides have been systematically striking each other’s logistics and dual-use commercial infrastructure. […] Zelensky’s government has framed its own long-range strikes as a way to force Russia to negotiate. You can hit centralized Russian distribution centers and not accomplish any material impact to the people of Russia. However, if you hit centralized Ukraine distribution centers, chaos and crisis quickly surfaces for Kiev residents. The why is not complicated.

Metropolitan Russia, home to more than 75% of the population, was set up around the concept of govt planned precincts. Each few buildings you will find a generally useful grocery store, a bakery, a coffee shop, a pharmacy, a utility store, tobacco, produce shop etc. all within immediate walking distance. EX. Bread is made in each bakery; made, not just taken out of a box. Actually made. They set it up that way a long time ago during the Soviet era. Now, over time stores are different, but the planning never changed. The people of Russia also operate Dacha Gardens all over the urban sprawl and suburban areas.

“Gardening as provided food for the people of Russia for over 1,000 years, starting as mainly subsistence or survival gardening and evolving into an independent, self-provisioning model between the Bolshevik Revolution and World War II and continues into today.” Ukraine, we are told – even by former Defense Minister Fedorov, was convinced by western intelligence analysis that destroying the roughly 200 online Wildberries distribution centers it would cripple the Russian consumer economy. Increased strikes did not yield the desired results.

Who in their right mind thought destroying regional Russian online warehouses would have some great impact? Russia is analog in a digital world. However, conversely in our westernized, centralized, corporate consumer structures and logistics, we built distribution economies on centralized production and cost-efficient distribution, vis-a-vis Kyiv or Brussels etc. Ex. The western bread for a hundred locations is made in one centralized or regional facility. Boxed, shipped and distributed for maximum efficiency and profit.

Bombing Russian distribution centers doesn’t have any impact on the precinct level operation. But taking out westernized regional hubs and distribution centers in Kiev can create immediate chaos. That’s what we are seeing now. Honestly, this is not complicated to analyze. These are two completely different economic and logistic models. One is centralized (Ukraine) and one is decentralized (Russia). Attacking the logistics of a decentralized system creates no substantive impact. Attacking the logistics of a centralized system creates major impact. I think part of the reason the western news doesn’t make sense is because western media doesn’t understand Russia or pretend not to know things. Apparently, the same applies to Western intelligence.
Read more …

“Carney rode into power in 2025 on a wave of manufactured Canadian nationalism, casting himself as the last line of defense against American economic influence — “elbows up,”

• Renaming a Lake: A Surefire Way to Expose the Corrupt (Florack)

Watching the tussle between Canadian Prime Minister Mark Carney and President Donald Trump unfold — the former “Lake Ontario”/”Lake America,” ya know… Well, I’ve decided it’s about time I waded into this fight.


Carney rode into power in 2025 on a wave of manufactured Canadian nationalism, casting himself as the last line of defense against American economic influence — “elbows up,” as the slogan goes. Strip away the branding, though, and you find a man deeply, personally enmeshed in the very country he’s built his entire political persona around opposing. Grade-one hypocrisy, dressed up in a maple leaf.

Start with his kids. Half of Carney’s children have lived and studied in the United States, at Harvard and Yale — the exact institutions you’d expect a man warning Canadians nightly about “American unreliability” to steer his family well clear of. Instead, he sent them straight into the belly of the beast. I don’t know. Perhaps there are no institutions that are blue-blooded enough in Canada to make Carney happy.

Then there’s the money, and this is where it gets genuinely rich, pun intended. An independent review of Carney’s own ethics-commissioner disclosure counted 515 American-headquartered companies among 567 total holdings — a staggering 90.8%, typically rounded to 91%. Canadian holdings amounted to just four companies, roughly 0.71%. Rebel News narrows it further: of his eight controlled assets, only three are Canadian — Canadian Natural Resources, Canadian Pacific Kansas City, and, amusingly, Lululemon.

The rest read like a highlight reel of American capitalism: Tesla, Alphabet, Amazon, Apple, Meta, Microsoft, Netflix, Bank of America, Morgan Stanley, Exxon Mobil, Chevron, Boeing, Lockheed Martin, Ford, and Walmart, according to Global News’s reporting on the disclosure. A man who built his brand warning Canadians away from American entanglement somehow forgot to warn his own portfolio manager.

Then there’s Brookfield, where this stops being merely embarrassing and starts looking like an actual conflict of interest. The Conservative Party of Canada points out Carney has actively championed Westinghouse, a nuclear firm his old employer, Brookfield Asset Management, helped acquire during his tenure. Brookfield manages over $1 trillion in assets and, unlike a typical bank, directly owns and operates real assets and businesses — real estate, power grids, renewable energy, and private equity investments. Canadian Conservatives have also flagged that Carney’s answer to the housing crisis leans on prefabricated housing, a sector dominated by Modulaire — another company tied directly to his old Brookfield portfolio.

The controversy around Carney’s blind trust stems from exactly this overlap: Brookfield is an active owner-operator across nuclear energy, housing infrastructure, and AI data centers — precisely the sectors Carney now subsidizes and deregulates as prime minister. Funny how that keeps lining up.

His defense, when pressed, is standard-issue: it’s all in a blind trust, so he can’t possibly know what’s in it. Sorry, no sale, Mark. A trust doesn’t erase ownership — it just moves it out of the spotlight. Democracy Watch’s Duff Conacher has called Canada’s blind trust laws effectively meaningless, riddled with loopholes wide enough to drive a transport truck through.

In fairness, that 91% figure describes the count of companies in the disclosed account, not the dollar value of Carney’s wealth and not a live snapshot of current holdings, since a third party now controls the trades. It’s an honest count of a real 2025 disclosure, not a measure of his net worth. That distinction doesn’t let him off the hook — it just means the sharpest version of this argument is the accurate one: the documented record shows a man whose investment instincts point overwhelmingly south of the border, whose signature company built its empire on the exact sectors he now legislates, and whose own family chose American classrooms over Canadian ones.

Carney wants Canadians to believe he’s fiercely guarding their national interests against American encroachment. Yet every bet he’s personally placed, with his own money and his own children’s futures, runs straight through the United States. Easy to play the nationalist from behind a podium when your actual wealth is anchored on the other side of the border — and there’s still Canadian tax revenue left over to toss around in the meantime. Now let’s talk about Ontario Premier Doug Ford.

Ontario’s premier stood up just yesterday, unveiling a sign insisting it would always be “Lake Ontario,” as though he’s got any actual say in the matter.

But as you might expect from one of Carney’s staunchest defenders, Ford’s own history is no shortage of scandal. I live within earshot of enough Canadian radio to have been entertained by most of it firsthand. A few highlights from my own notes:

His 2019 overhaul of the Ontario Autism Program was meant to clear a long waitlist but instead threatened to cut off access entirely for many families, sparking widespread protests before the government partially reversed course. That same year, his chief of staff, Dean French, resigned in a patronage scandal after lucrative foreign government postings — including one to a 26-year-old whose chief qualification was playing lacrosse with French’s son, at a $165,000 salary — went to people personally connected to French. Ford revoked the appointments but drew criticism for brushing off reporters’ follow-up questions.

Around the same time, Ford appointed longtime friend Ron Taverner, a Toronto police superintendent, to head the Ontario Provincial Police, only for it to emerge that the job’s qualifications had been quietly lowered specifically to make Taverner eligible; he eventually stepped down under pressure. Separately, retroactive public health funding cuts stripped roughly $177 million a year from Toronto Public Health and Paramedic Services, totaling close to $1 billion over a decade.

The biggest scandal by far is the Greenbelt affair. Video surfaced of Ford, before even winning office in 2018, promising to “open up a ‘big chunk'” of protected Greenbelt land to developers. Once in office, he did exactly that. Ontario’s own auditor general and integrity commissioner both investigated and found evidence pointing to corruption in how the land was selected and released. The RCMP opened a criminal investigation. Two staffers and two cabinet ministers resigned. Ford’s approval rating hit record lows, with a majority of poll respondents calling the deal outright corrupt — and after weeks of defending it publicly, he ultimately reversed course and canceled the whole plan.

There’s more. Breaking Ontario’s exclusive Beer Store contract to allow alcohol sales in convenience and grocery stores cost $225 million in compensation, with the province’s own Financial Accountability Office projecting total losses could reach $1.4 billion to $1.9 billion by 2030.

The Ontario Science Centre closure drew scrutiny after developers with ties to Ford’s family bought land adjacent to the site shortly before Ford announced a subway stop there that boosted nearby land values — the closure itself later justified by a disputed structural report.

Read more …

Well, nobody seems to know what he did there.

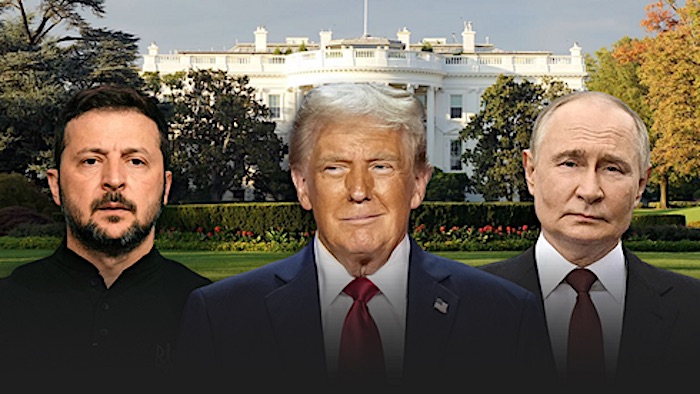
• CIA Director Pushed Trump-Putin-Zelensky Summit During Moscow Visit (ZH)
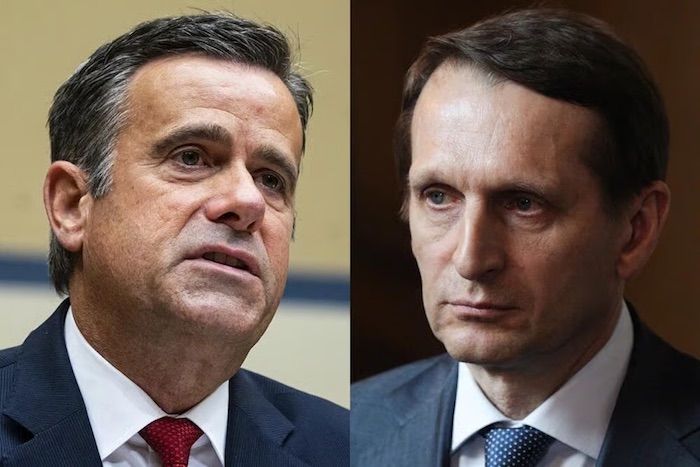
CIA Director John Ratcliffe, left, held talks in Moscow with Russia’s foreign intelligence chief, Sergey Naryshkin

Yet another take has been issued, and more alleged details, on CIA Director John Ratcliffe’s Tuesday trip to Moscow, which took place amid great secrecy and still even days later has only been subject of immense speculation. Axios is reporting over the weekend that the CIA chief proposed a trilateral meeting between Russian President Vladimir Putin, US President Donald Trump and Ukrainian President Volodymyr Zelensky – when he met with top Kremlin intelligence officials but was not granted a direct meeting with Putin himself.


“Of course, President Putin is immediately briefed on everything,” Kremlin spokesman Dmitry Peskov said, calling the meeting “a positive phenomenon” while not giving additional details. The war has quite obviously ramped up this summer, with tit-for-tat strikes expanding beyond just military and energy targets, to include food and retailing companies, and increasingly even civilian neighborhoods.

According to some details via Axios:
• Ratcliffe’s visit was partly aimed at determining whether Russia’s heads of intelligence services could help convince Putin to move toward resuming U.S.-mediated negotiations with Ukraine, the sources said.
• On Friday, U.S. officials briefed Zelensky on Ratcliffe’s talks in Moscow and the proposal for a trilateral summit.
• The Trump administration has raised the idea in the past. Zelensky has been on board, but Putin has rejected it.

Over in the Middle East, the Iran war has not gone well for Washington, and so the White House has recently pivoted back to seeking a war forward toward peace in Ukraine, needing a foreign conflict ‘win’. However, US admin officials have signaled they are not ready to force Ukraine into a ‘bad’ peace deal. Also according to Axios, “Zelensky’s chief of staff, Kyrylo Budanov, told local media on Thursday that U.S.-mediated talks with Russia could resume in September.”

As for Trump, on Wednesday he told Glenn Beck in an interview: “We would like to see the Ukraine war end,” adding that his administration was “working very hard to get that war ended.” [..] Concerning the CIA chief’s visit to Moscow, some have said that it may have been focused on Iran, amid Washington warnings for Russia to cease helping Tehran, following prior widespread allegations that Russian intelligence provided targeting information of US bases and troops across the Mideast region.

Read more …

Use visas to lower your labor costs. Some business model.

• U.S. Visa Restrictions, Reviews and Applicant Suspensions (CTH)
As noted by Amanda Louise on X: “[NASSCOM’s] concern wasn’t that jobs would go unfilled because America lacked skilled workers. It was that companies like Infosys would have to “hire many more local Americans, which would be expensive.” “Americans weren’t described as unavailable. Americans were described as the more expensive alternative. And they acknowledged the other half of the problem.. companies with a “strong local American presence” would have a competitive advantage if visa-dependent companies lost easy access to that labor.


That tells Americans exactly what this business model does. Use visa labor to lower costs. Compete against companies that hire more Americans. Win their contracts. And now those American-employing companies have fewer jobs to offer too.

The American worker loses twice.
So why are we still debating what these visa programs are being used for? Their statements tell us the incentive. The immigration filings show us the scale. The layoffs show us who pays the price. How much more evidence does Congress need before it answers why U.S. immigration policy gives companies a competitive advantage for hiring visa workers instead of Americans?”

Read more …

“Unpopular ‘Hostess'” of Meet the Fake Press..”

• Trump Nukes NBC’s Kristen Welker Again (Matt Margolis)
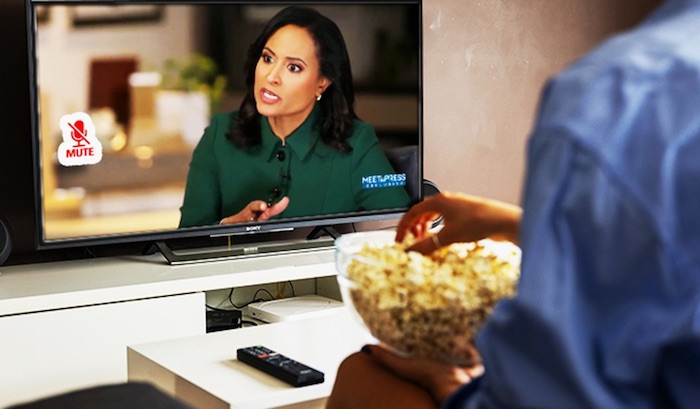
President Donald Trump has a history with NBC Meet the Press host Kristen Welker, and it isn’t a friendly one. Back in June, he sat down with her for an interview that fell apart before it even ended, with the president walking out mid-conversation. On Sunday morning, he went after her again, this time on Truth Social, and this time he wants the Federal Communications Commission involved.


The trigger was a simple line from Welker describing Trump’s 2026 midterm endorsement record as producing “mixed results.” He opened by mocking her outright, branding Welker the “Unpopular ‘Hostess'” of Meet the Fake Press. From there, Trump laid out his case.

He pointed to two recent Republican wins as proof that his endorsement carries weight: Darline Graham winning the South Carolina Senate primary, and Mike Mazzei winning the Oklahoma governor’s race, both after Trump backed them. He pointed out that his overall endorsement success rate is roughly 99%, including 100% in Senate races and about 98% in House races. Those are not the numbers of a politician with “mixed results,” and Trump made sure everyone knew it.

“How can anyone be allowed to say this, working for freely given Public Airwaves?” Trump asked, before announcing his next move. “Because of this purposeful inaccuracy, she will be reported to the FCC for rebuke or punishment.”

He wasn’t finished with the media at large, either. “Unfortunately, she is not the only one. The Radical Left News is going out of their way to harass, demean, and libel anything ‘TRUMP,'” Trump wrote, framing Welker’s comment as part of a broader pattern rather than an isolated slight.

Trump went on to argue that his critics have settled on a new line of attack: recasting a historic winning streak as unremarkable. “Their new weapon is to say that my 99% SUCCESS Rate on Endorsements, 100% on Senatorial Endorsements (Many of whom were not even given a shot of winning until I Endorsed!), is either a mixed result, or not very good,” he wrote. He wasn’t buying it. “In actuality, it is, without question, the strongest Endorsement in the History of Politics,” he continued. “If it were not, I would be the first to admit it.”

He then made his case with specifics. Graham’s Senate run, Trump wrote, “was the biggest story in all of Politics” because she wasn’t expected to win, but once he endorsed her and she cruised to victory, “the story of her Victory was hardly covered by anybody.” He said much the same thing happened in Oklahoma, where Mazzei “was behind in every Poll” before Trump’s endorsement, and after Mazzei won, “the story was barely covered.”

Trump closed by referring the matter directly to FCC Chairman Brendan Carr, writing that he hoped Carr “and the fine people of his Commission” would “take this Threat to our Country very seriously.” He signed off by calling the press “a Disgrace to our Nation” and thanking his followers for their “attention to this very important matter of Fake Polls and Commentary.”

Read more …

“Alberta will never secede from Canada because Premier Danielle Smith is a gaslighting fibber and structurally in alignment with Mark Carney. “

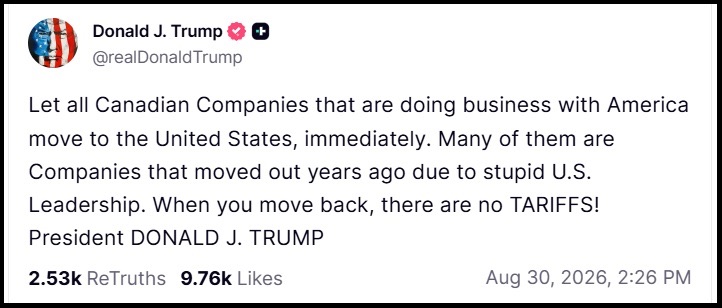
• Trump Advises Corporations to Depart Canada for Stability in USA (CTH)
I think we have finally figured out President Trump’s long-term strategy here. Essentially, we have been flummoxed over why President Trump has not yet triggered the 6-month USMCA (CUSMA) termination notice yet. However, he appears to be intentionally drawing this out.


For the deniers, I simply request you to think about it in very simple and logical terms. Do you really foresee any possibility of President Trump or USTR Jamieson Greer renegotiating a USMCA agreement amid the divide Canada is creating? There’s no way terms will ever be discussed. Therefore, with an all-in perspective on termination, the moves President Trump is making now are all just to prolong economic pain and block investment while retaining the termination notice as the hidden ace. [VIA TRUTH SOCIAL]


Why this approach? Well, right now American communists and those with TPS status changes are fleeing to Canada; a human sedimentation tank. Bring back the corporations who set up shop in Canada and swap them for outbound, dependent leftists.

Alberta will never secede from Canada because Premier Danielle Smith is a gaslighting fibber and structurally in alignment with Mark Carney. Additionally, if you look up “battered conservative syndrome” in the geopolitical library you will note that Alberta is the birthplace of the mindset, and Pierre Poilievre is their mascot. Alberta will never leave Canada.

Those who understand the pretense of the UniParty in the United States, likely understand that in Canada the pretending is exponentially more entrenched.
Read more …

Black Biden?!

• James Clyburn Basically Says Clarence Thomas ‘Ain’t Black’ (Matt Margolis)
Rep. James Clyburn (D-S.C.) sat down with Kristen Welker on Meet the Press Sunday, and the segment on the Supreme Court went about as you’d expect from a Democrat these days. He’s on board with Kamala Harris’s push to expand the Court to 13 justices, because of course he is. I don’t care how many times Democrats swear this isn’t about seizing permanent power. Packing the bench only becomes a priority whenever they’re the ones stuck losing decisions, and something tells me Clyburn’s enthusiasm for a bigger bench is entirely dependent on which party gets to fill those seats.


But that’s not even the part of the interview that made me sit up. Welker brought up something I had no idea about: Clyburn testified in favor of Clarence Thomas’s Supreme Court confirmation back in 1991. Welker even played the tape. “It’s a pleasure for me to be here today to present testimony in favor of my good friend, Clarence Thomas,” Clyburn said in the old clip. “I have known Clarence for ten years and I consider him to be a personal and professional friend, in spite of the fact that he shares a conservative Republican philosophy.”

I looked up his entire testimony, and I was floored. Clyburn praised him as “zealous in his pursuit of the facts and intellectually honest and objective.” Most significantly, Clyburn said civil-rights officials who worked with Thomas found him “highly compassionate, sensitive, judicious” and possessed of the “intellectual honesty that is required in this field.” Despite their disagreements, Clyburn said he had “never found anything in his philosophy of a nature to deny him this Supreme Court confirmation.” He concluded that Thomas was “deeply committed to an even-handed system of justice” and possessed “the integrity, the conscientious spirit, and the basic sense of fairness” required of a Supreme Court justice.

Welker asked the obvious follow-up. “Do you stand by your decision to make the case for Clarence Thomas’s confirmation?” Welker asked. “

Absolutely not,” Clyburn said. He explained that he had trusted Thomas’s background and life experience to guide him on the bench, and that he had expected Thomas to uphold precedents like Brown v. Board of Education and the Voting Rights Act. Then came the line that got my attention. “I had no idea that Clarence Thomas would rebel the way he has against his own background and experiences,” Clyburn said. He added that Thomas’s grandfather raised him in Pin Point, Ga., and accused Thomas of showing “very little sensitivity” to that upbringing.

“Rebelled against his own background.”

Sit with that phrase for a second. Clyburn frames Thomas’s judicial record as a betrayal of an obligation tied to where he came from, as if the Constitution should take a backseat to his childhood ZIP code. As far as I’m concerned, Clyburn accused Thomas of forgetting his roots… more specifically, his experience growing up poor and black.

From where I sit, there’s something familiar about Clyburn’s accusations. They remind me of Joe Biden, while campaigning in 2020, telling host Charlamagne that any black voters still deciding between him and Donald Trump “ain’t black.” The backlash was immediate, and rightly so, because the implication was that authentic blackness requires voting a certain way. Clyburn is making the same argument about Thomas, just dressed up in the language of a Sunday show instead of a campaign bus.

The question isn’t whether Clyburn respects Clarence Thomas’s legal record. It’s whether Clyburn believes black conservatives are allowed to exist at all without being accused of betraying themselves. Thomas has since spent three decades ruling as an actual constitutional originalist instead of the reliable liberal vote Clyburn apparently hoped he would be. Clyburn’s real complaint has nothing to do with constitutional interpretation. He expected Thomas to be a loyal black vote on the Court… which, in his view, means voting with the leftists.

Read more …

“Gov. Gavin Newsom (D-Calif.) may soon receive a bill requiring major companies to swear, under penalty of perjury, that they searched generations of corporate records for ties to slavery.”

• California Lawmakers Keep Giving Businesses Reasons to Leave (David Manney)
Gov. Gavin Newsom (D-Calif.) may soon receive a bill requiring major companies to swear, under penalty of perjury, that they searched generations of corporate records for ties to slavery.


“This bill, upon appropriation by the Legislature, would require any business or enterprise that is doing business in the state that was in existence or whose predecessor company was in existence on or before December 31, 1964 and has annual worldwide gross receipts that exceed $100,000,000 to complete an affidavit, under penalty of perjury, verifying that it has searched through any and all records in its and its related entities, as defined, possession, control, and knowledge for records that the in-state covered entity or its related entities bought or sold persons subjected to slavery, used persons subjected to slavery as collateral, provided loans to purchase persons subjected to slavery, insured such transactions or the persons subjected to slavery, or provided related or other services to aid or otherwise facilitate those transactions. The bill would set forth the contents of the affidavit, the timeline and manner of submission, and reporting requirements.

This bill would require the Civil Rights Department to create a public, digital platform by January 3, 2028, within one year after an appropriation is made, that would make available affidavits and reports records made pursuant to the bill and disaggregated data, as described. The bill would additionally require the above-described business or entity, that submits a bid or proposal to, or otherwise proposes to enter into or renew a contract with, a state agency, as described above, to additionally certify, under penalty of perjury, that they have submitted the affidavit in compliance with the above-described provisions. By requiring an affidavit and to certify under penalty of perjury regarding compliance with the above-described affidavit requirements, and thus expanding the crime of perjury, the bill would impose a state-mandated local program.”

The California Constitution requires the state to reimburse local agencies and school districts for certain costs mandated by the state. Statutory provisions establish procedures for making that reimbursement. This bill would provide that no reimbursement is required by this act for a specified reason. Welcome to doing business in California in 2026.

Assemblyman Isaac Bryan’s AB 2599 has cleared both chambers of the California Legislature. If Newsom signs it and lawmakers provide funding, businesses operating in California with more than $100 million in worldwide annual revenue would fall under the mandate if they, or a predecessor company, existed on or before December 31, 1964.

Those companies would have to search their records and those of related entities for evidence involving the purchase or sale of enslaved people, use of slaves as collateral, loans financing their purchase, insurance transactions, or other business connected to slavery. The affidavit would be submitted under penalty of perjury, and California’s Civil Rights Department would eventually make the records publicly available.

Of course, slavery is evil; its history deserves to be preserved, studied, and truthfully taught. But California lawmakers have decided corporate compliance departments in 2026 should search records reaching back to 1849 for actions taken generations before anyone now running those companies was born. If Sacramento wants more historical research, California has universities, archives, historians, and an enormous state government. Lawmakers chose to put the burden on private businesses.

Meanwhile, Assemblyman Matt Haney’s AB 2017 is headed toward another Senate vote after being amended again on Aug. 27. It would add Eid al-Fitr and Eid al-Adha to California’s list of state holidays. Courts would remain open, and private businesses wouldn’t be required to close. Muslim Californians should be free to celebrate their holy days, just as every American should be free to practice their faith. AB 2017 carries far less economic weight than Bryan’s corporate mandate. Its relevance is Sacramento’s endless appetite for another designation, requirement, program, or government instruction.

Employers already have reasons to question whether California is worth the trouble. A corrected Public Policy Institute of California study found annual headquarters departures climbed from about 240 in 2011 to more than 400 in 2021. California lost 1,250 headquarters on net during the period studied. The researchers properly noted that relocations remained a small share of overall headquarters activity, but they also found departing companies tended to choose states with lower taxes and less regulation.

More recent data aren’t comforting. A 2026 analysis found California’s largest metro areas, including Los Angeles and the San Francisco-San Jose region, continuing to suffer net headquarters losses. High taxes, labor regulation, and the cost of living remain major pressures. California’s own Employment Development Department reported the state lost 20,500 nonfarm payroll jobs in July, even as unemployment improved to 5.1%. Meanwhile, the nonpartisan Legislative Analyst’s Office calculates an $18.5 billion operating deficit for the 2026-27 budget year.

California remains an economic giant with extraordinary workers, capital, technology, agriculture, ports, and universities. Sacramento seems determined to discover how many unnecessary burdens those advantages can carry. Companies don’t need another reason to leave. California lawmakers keep volunteering them.

Read more …

I don’t really like playing on the man.

• Michelle Obama Proves Again She’s a Horrible Person (Matt Margolis)
Barack Obama’s wife, Michelle Obama, has spent years cultivating an image as America’s most relatable first lady, the warm, down-to-earth mom everybody loves. Yet, it seems like every time she opens her mouth, she proves what a horrible person she is. We’re talking Hillary Clinton-level bad.


Last month, we learned that Barack Obama’s wife reportedly made sure Cheryl Hines never got a role in Larry David’s new HBO series, Life, Larry and the Pursuit of Unhappiness: An Almost History of America, because Hines is married to Robert F. Kennedy Jr., President Donald Trump’s secretary of health and human services. Hines played Larry David’s wife on Curb Your Enthusiasm for years. Talk about going low.

I’ve written about some of the lowlights of her post-White House life, from blatantly racist comments to complaining about the luxurious life she lived in the White House like it was a burden. Has anyone so privileged ever complained so much about her own life? Barack Obama’s wife might be the closest thing America has to an answer. But, perhaps even worse, she’s been joyful about not having to parent her own kids. That last one reared its ugly head again last week, on the latest episode of IMO, the podcast Barack Obama’s wife co-hosts with her brother, which aired Wednesday. She told guest Jon Stewart she’s thrilled that raising her children is finally behind her.

Stewart tried to give her a graceful opening, telling her, “You obviously miss the energy and excitement of the kids being around.” Barack Obama’s wife shot that down fast. “I don’t! I love them. I’m going to see them tonight for dinner. I love them. But Barack cried when they went to college. I was like, ‘Bye, goodbye!'” she said.

Stewart tried again, describing what he misses about his own daily grind. “The thing I miss, though, is the job. It gave meaning and a pattern to my life,” he said. Barack Obama’s wife simply replied, “I’m good…” She went on to gush about how “Friday nights aren’t wracked with terror and fear about, ‘Where are you, where are you?'” and said she’s enjoyed watching Malia and Sasha’s “growth” following their “emancipation.”

Emancipation. That’s the word a mother chose for her daughters growing up, as if raising kids is like being condemned to slavery. She insisted she’s still close with her girls, saying, “I’ve had so much quality time with my children, so much, I know them inside and out.” Then she delivered the real punchline: “I love my schedule,” and “I have a great schedule, and it’s all mine.”

Once again, it’s all about me, me, me, me.

Now, let’s think about this for a minute. Malia was ten years old when Barack Obama took office and 18 when he left. Sasha went from seven to 15. That entire stretch of childhood happened inside the White House, where a full-time staff of roughly 90 people cooked, cleaned, and ran the household. Her mother, Marian Robinson, moved in and handled much of the actual parenting. Barack Obama’s wife was too busy jetting around the world with the largest entourage of any first lady in history to be bothered with carpool duty, parent-teacher meetings, booster clubs, etc., etc.

So why is she acting like she just wrapped up a decade of exhausting, hands-on motherhood? Parenthood isn’t easy; no one is saying it is. But her attitude about it is probably the worst I’ve heard from a parent. She sounds more like a childless person boasting about why not having kids is so liberating than an actual parent.

“There is a difference between a mother expressing exhaustion from the demands of motherhood — which is real and relatable — and expressing resentment,” California Republican Party delegate and mother Elizabeth Barcohana told Fox News Digital. “Resentment is what appears to come through in Michelle Obama’s remarks, and it is especially painful to hear amid the national conversation surrounding the Lindsay Clancy trial.” She added, “She seems happy that her daughters’ childhoods are over. That is not a relatable feeling for most mothers at all.”

Barack Obama’s wife doesn’t miss her daughters’ childhoods for a simple reason. She barely showed up for them in the first place.
Read more …


https://twitter.com/herbertong/status/2093770659528949805?s=20 https://twitter.com/MAGAVoice/status/2094027463865364487?s=20


Support the Automatic Earth in wartime with Paypal, Bitcoin and Patreon.


Feb 062018
 
 February 6, 2018  Posted by at 9:53 am Finance Tagged with: , , , , , , , , , , , ,  19 Responses »


• Dow Jones Hit By Biggest Single-Day Points Drop Ever (Ind.)
• Stocks Crumble In Vicious Sell-off As ‘Goldilocks’ Trade Unravels (R.)
• Europe Joins Global Stock Selloff With Biggest Drop in 20 Months (BBG)
• ‘Short-Volatility Armageddon’ Craters Two Of Wall Street’s Favorite Trades (MW)
• Volatility Spike Boosts US Options Hedging Activity (R.)
• Traders Panic As XIV Disintegrates -90% After The Close (ZH)
• Machines Had Their Fingerprints All Over a Dow Rout for the Ages (BBG)
• Commodities Dragged Into Global Selloff as Oil to Copper Get Hit (BBG)
• Bitcoin Tumbles Almost 20% as Crypto Backlash Accelerates (BBG)
• The Fed’s Dependence On Stability (Roberts)
• A Quandary (Jim Kunstler)
• 21st Century Plague (MarkGB)
• UK Court To Rule On Lifting Assange Arrest Warrant (AFP)
• Robots Will Care For 80% Of Elderly Japanese By 2020 (G.)
• Berlusconi Pledges To Deport 600,000 Illegal Immigrants From Italy (G.)


4% is nothing.

• Dow Jones Hit By Biggest Single-Day Points Drop Ever (Ind.)

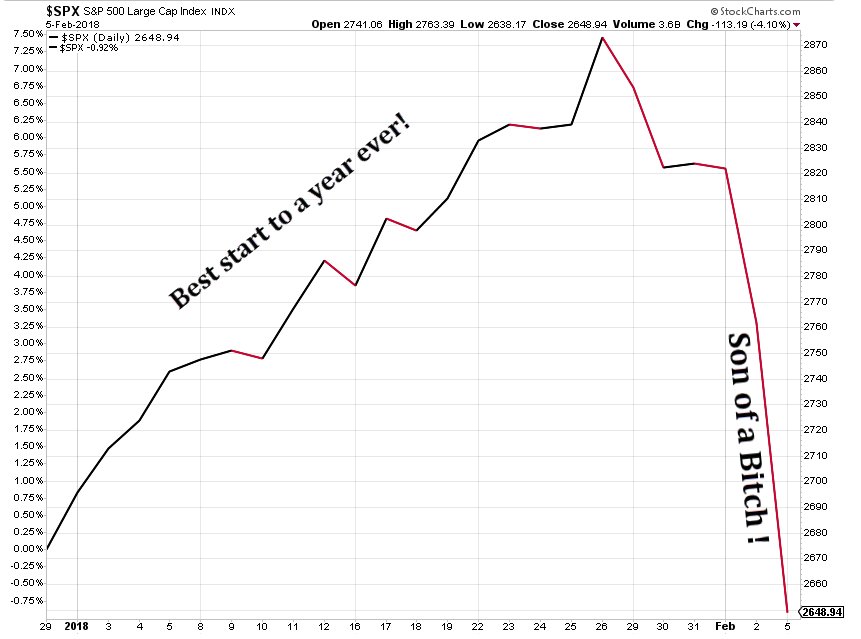
Newfound market volatility has shattered what had been a long period of stability and mounting value. The Dow’s dive erased gains for the year so far and extended a multi-day slump that saw the Dow drop by some 600 points on Friday. In addition setting a new record for number of points dropped in a day, the Dow’s 4.6% decline in value was the most substantial since 2011. It was still less severe than declines during market-rocking events like the 2008 financial crisis, when the Dow shed 7% of its value in its worst single-day hit. Earlier in the day the Dow had plummeted by nearly 1,600 points before recovering much of that value. It has swung some 2,100 points in the last week of trading, a slide approaching 8%.

In addition to the Dow shedding value, the S&P 500 index and the Nasdaq both saw declines of around 4%. The S&P 500 declined to about 7.8% below its all-time high. With thriving markets toppling records in recent months, some analysts said the pullback was all but inevitable. After cresting to a record high in January, the Dow has retreated by 8.5% from that apex. “It’s like a kid at a child’s party who, after an afternoon of cake and ice cream, eats one more cookie and that puts them over the edge,” David Kelly, the chief global strategist for JPMorgan Asset Management, told the Associated Press.

Read more …

Worldwide.

• Stocks Crumble In Vicious Sell-off As ‘Goldilocks’ Trade Unravels (R.)

A rout in global equities deepened in Asia on Tuesday as inflation worries gripped financial markets, sending U.S. stock futures sinking further into the red after Wall Street suffered its biggest decline since 2011 in a vicious sell-off. S&P mini futures fell as much as 3.0% to four-month lows in Asia, extending their losses from the record peak hit just over a week ago to 12%. MSCI’s broadest index of Asia-Pacific shares outside Japan slid 4.3%, which would be its biggest fall since the yuan devaluation shock in August 2015, turning red on the year for the first time in 2018. Japan’s Nikkei dived 6.8% to near four-month lows while Taiwan shares lost 5.5% and Hong Kong’s Hang Seng Index dropped 4.9%.

Monday’s stock market rout left two of the most popular exchange-traded products that investors use to benefit from calm rather than volatile conditions facing potential liquidation, market participants said. The ructions in markets come after investors have ridden a nearly nine-year bull run, with low global rates sparking a revival in economic growth and bright corporate earnings. That good times may be nearing at end if Wall Street is anything to go by. U.S. stocks plunged in highly volatile trading on Monday, with the Dow industrials falling nearly 1,600 points during the session, its biggest intraday decline in history, as investors grappled with rising bond yields and potentially higher inflation.

Read more …

They’ll all keep claiming that fundamentals are solid.

• Europe Joins Global Stock Selloff With Biggest Drop in 20 Months (BBG)

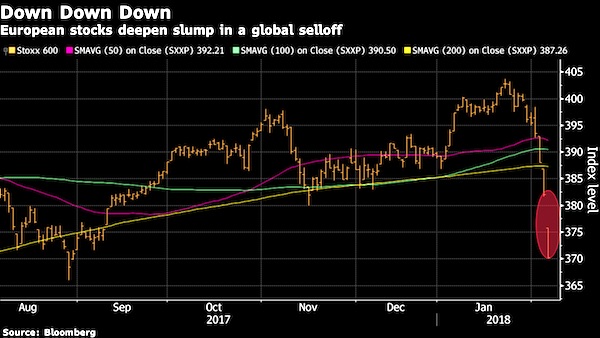
European stocks headed for their worst drop since the aftermath of the Brexit referendum as traders in the region caught up with an overnight selloff in the U.S. and Asia. The Stoxx Europe 600 Index fell 2.6% as of 8:16 a.m. in London, with all industry groups firmly in the red. After a strong start to 2018, most European stock benchmarks have wiped out gains for the year in a rout that is extending into a seventh day for the broader regional benchmark. Sentiment has been hurt by worries over rising government bond yields and the outlook for the trajectory of interest rates. “There is a sense out there that this is, in a way, a release of some of the pent-up low volatility we’ve seen over the past year,” said Ben Kumar, an investment manager at Seven Investment Management in London, which oversees about 12 billion pounds.

“We have been sitting on quite a large cash pile for some time and at some point, we will look to invest that. There may be a bit more pain to come before we start seeing a real dip to buy.” Cyclicals including automakers, technology and basic resources were among the worst sector performers. Still, data on Monday showed economic momentum in the euro-area climbed to the fastest pace in almost 12 years, and German factory orders surged in the last month of 2017. That’s leading some fund managers and traders to bet that equities are experiencing an overdue pullback rather than a deeper correction. “Market tops have probably been set for a pretty long time now on many equity indexes,” Stephane Barbier de la Serre, a strategist at Makor Capital Markets, said by phone.

Read more …

They’ll have a hard time accepting the demise of easy money.

• ‘Short-Volatility Armageddon’ Craters Two Of Wall Street’s Favorite Trades (MW)

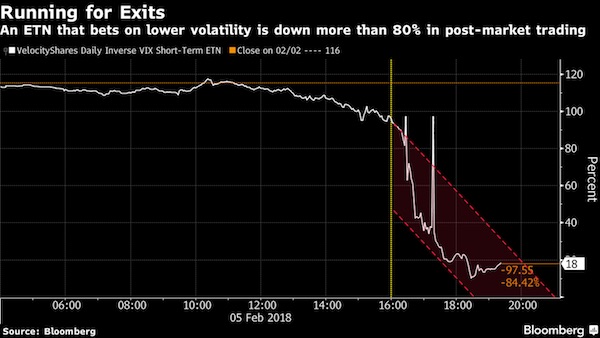
One of the most popular trades in the market, betting a period of unnatural calm would continue, may have amplified selling pressure in the stock market on Monday market participants said. At least two products tied to volatility bets were severely whacked with the hemorrhaging that could pose challenges to the exchange-traded notes. One popular product, the VelocityShares Daily Inverse VIX Short Term ETN, was down 90% in after-hours trade on Monday, following a session in which the Dow Jones Industrial plunged by 1,175 points, or 4.6%, while the S&P 500 index tumbled 4.1%—both benchmarks coughed up all of their gains for 2018.

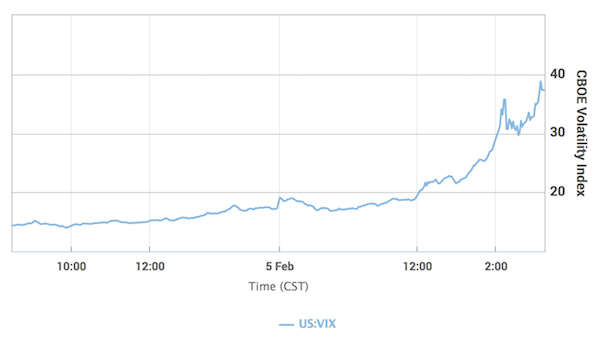
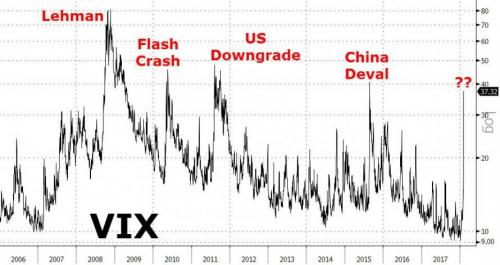
The Cboe Volatility Index, meanwhile, skyrocketed by about 118%, marking its sharpest daily rise on record. The VIX uses bullish and bearish option bets on the S&P 500 to reflect expected volatility over the coming 30 days, and it typically rises as stocks fall. The XIV, meanwhile, was designed to allow investors to bet against a rise in volatility and such bets had been a winning proposition until recently, when equities accelerated a multisession unraveling fueled by fears that the Federal Reserve will be forced to raise borrowing costs faster than anticipated due to a potential resurgence in inflation, which had pushed Treasury yields higher. Monday’s stock-market drop may have been amplified because those making bets that volatility, as measured by the VIX, would remain relatively subdued, were caught wrong-footed.

Read more …

Ultra low volatility is purely artificial.

• Volatility Spike Boosts US Options Hedging Activity (R.)

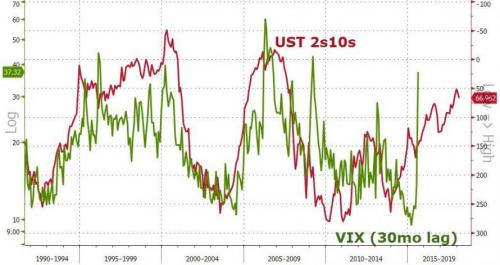
Wall Street’s “fear gauge” notched its biggest one-day jump on Monday in over two years, as U.S. stocks slumped and investors took to the options market in search of protection against a further slide in equities prices. Stocks slid in highly volatile trading on Monday, with the benchmark S&P 500 index and the Dow Jones Industrials suffering their biggest respective%age drops since August 2011 as a long-awaited pullback from record highs deepened. For the Dow, the fall at one point of nearly 1,600 points was the biggest intraday point loss in Wall Street history. The CBOE Volatility Index, better known as the VIX, is the most widely followed barometer of expected near-term volatility for the S&P 500 Index. On Monday, the index ended up 20.01 points at 37.32, its highest close since August 2015.

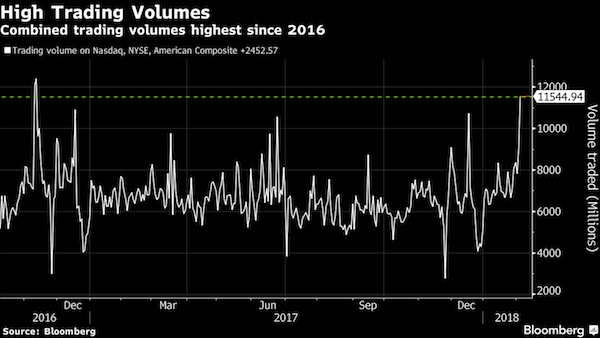
“The day started out fairly orderly, but somehow it took a turn for a worse, and then panic set in,” Randy Frederick, vice president of trading and derivatives for Charles Schwab. “There may have been some pretty sizeable program trades that were clicked in. It just looks like some institutional program selling,” he said. The intensity of the selloff drove traders to the options market and trading volume surged to 35.5 million contracts – the third busiest day ever and the busiest day since Aug. 21, 2015, according to options analytics firm Trade Alert. VIX call options, primarily used to protect against a spike in volatility, accounted for nine of Monday’s 10 most heavily-traded contracts. Overall VIX options volume hit 3.6 million contracts, or about three times its average daily volume.

Read more …

VIX can trigger some pretty dramatic events.

• Traders Panic As XIV Disintegrates -90% After The Close (ZH)

Today’s market turmoil has left more questions than answers. “What was frightening was the speed at which the market tanked,” said Walter “Bucky” Hellwig, Birmingham, Alabama-based senior vice president at BB&T Wealth Management, who helps oversee about $17 billion. “The drop in the morning was caused by humans, but the free-fall in the afternoon was caused by the machines. It brought back the same reaction that we had in 2010, which was ‘What the heck is going on here?” Some tried to blame it on a fat-finger or ‘machines’, but in this case it was not the normal cuprits per se… “There was not a single self-help; there were no outs; there were no fat fingers that we saw,” Doug Cifu, CEO of high-speed trading firm Virtu, told CNBC. “There were no busted trades, no repricing. It was just an avalanche of orders around 3 o’clock-ish.”

But while we noted earlier that US equity futures were extending losses after the close, but the real panic action is in the volatility complex. Putting today’s VIX move in context, this is among the biggest ever… And it appears Morgan Stanley was right to bet on VIX hitting 30…

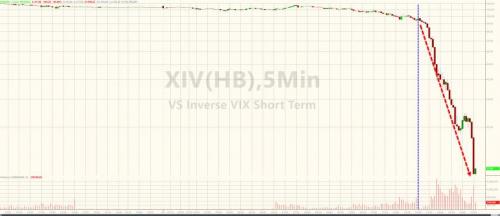
But the real action is in the super-crowded short-vol space. XIV – The Short VIX ETF – after its relentless diagonal move higher as one after another Target manager sold vol for a living… just disintegrated after-hours, down a stunning 90% to $10.00.

Which is a problem because as we explained last summer, the threshold for an XIV termination event is a -80% drop. What does this mean? Well, in previewing today’s events last July, Fasanara Capital explained precisely what is going on last July:

“Additional risks arise as ‘liquidity gates’ may be imposed, even in the absence of a spike in volatility. In 2012, for example, the price of TVIX ETN fell 60% in two days, despite relatively benign trading conditions elsewhere in the market. The reason was that the promoter of the volatility-linked note announced that it temporarily suspended further issuances of the ETN due to “internal limits” reached on the size of the ETNs. Furthermore, for some of the volatility-linked notes, the prospectus foresee the possibility of ‘termination events’: for example, for XIV ETF a termination event is triggered if the daily percentage drop exceeds 80%. Then a full wipe-out is avoided insofar as it is preceded by a game-over event.” The reaction of the investor base at play – often retail – holds the potential to create cascading effects and to send shockwaves to the market at large. This likely is a blind spot for markets.

Read more …

Algorithms rule what is left.

• Machines Had Their Fingerprints All Over a Dow Rout for the Ages (BBG)

Risk parity funds. Volatility-targeting programs. Statistical arbitrage. Sometimes the U.S. stock market seems like a giant science project, one that can quickly turn hazardous for its human inhabitants. You didn’t need an engineering degree to tell something was amiss Monday. While it’s impossible to say for sure what was at work when the Dow Jones Industrial Average fell as much as 1,597 points, the worst part of the downdraft felt to many like the machines run amok. For 15 harrowing minutes just after 3 p.m. in New York a deluge of sell orders came so fast that it seemed like nothing breathing could’ve been responsible. The result was a gut check of epic proportion for investors, who before last week had been riding one of the most peaceful market advances ever seen. The S&P 500, which last week capped a record streak of never falling more than 3% from any past point, ended the day down 4.1%, bringing its loss since last Monday to 7.8%.

“We are proactively calling up our clients and discussing that a 1,600-point intraday drop is due more to algorithms and high-frequency quant trading than macro events or humans running swiftly to the nearest fire exit,” said Jon Ulin, of Ulin & Co. in an email. To be sure, not all of the rout requires inhuman agency to explain. Markets are jittery. Bond yields had been surging and stock valuations are approaching levels last seen in the internet bubble. Much of today’s selloff was perfectly rational, if harrowing – particularly coming after last week’s plunge in which the Dow fell 666 points on Friday. Observers looking for an electronic villain trained most of their attention on the roughest part of the tumble, a 15-minute stretch starting about an hour before the close. That’s when an orderly selloff snowballed, taking the Dow from down about 700 points to down a whopping 1,600. It quickly recovered.

Read more …

When commodities trade is separated from what industries actually use, and they become financial tools only, inevitable.

• Commodities Dragged Into Global Selloff as Oil to Copper Get Hit (BBG)

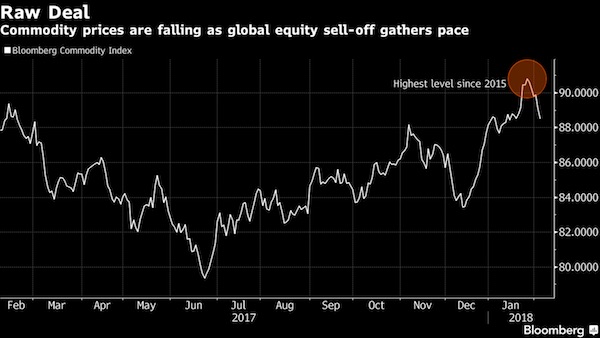
Commodities from crude oil to metals and iron ore dropped as the global equity rout and surge in market volatility spurred investors to pare risk, cutting positions in raw materials even as banks and analysts stood by the asset class given the backdrop of solid global growth. Brent crude slid as much as 1.2% to $66.82 a barrel, heading for a third daily drop and the longest losing run since November. On the London Metal Exchange, copper sank as much as 2% to $7,025 a metric ton as zinc, lead and nickel declined. Iron ore futures fell 1.2% in Singapore. Global equity markets are in retreat after Wall Street losses that began in the final session of last week worsened on Monday, with the Dow Jones Industrial Average posting its biggest intraday point drop in history.

The selloff – triggered in part by an initial rise in bond yields and concerns about the pace at which the Federal Reserve will raise interest rates – is spilling into commodities, which rallied in late January to the highest level since 2015. Still, Citigroup said now’s the time for investors to add positions in metals. “Clearly there is a risk off tone in the markets that will weigh on the sector,” said Daniel Hynes at Australia & New Zealand Banking. “But there is no fundamental reason for this selloff to change our view of commodity markets.” Miners and energy companies fell as share benchmarks spiraled downward. In the U.S. on Monday, Exxon Mobil and Chevron were among the worst performers in the Dow. In Sydney, BHP Billiton, the world’s largest mining company, dropped 2.7% as Rio Tinto traded lower. Oil producer PetroChina lost as much as 7.3% in Hong Kong.

Read more …

6,100 as I write this.

• Bitcoin Tumbles Almost 20% as Crypto Backlash Accelerates (BBG)

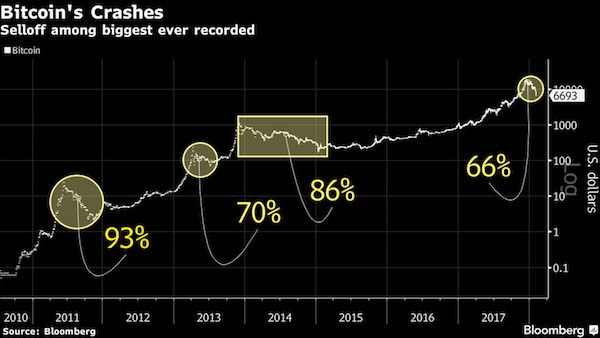
Bitcoin tumbled for a fifth day, dropping below $7,000 for the first time since November and leading other digital tokens lower, as a backlash by banks and government regulators against the speculative frenzy that drove cryptocurrencies to dizzying heights last year picks up steam. The biggest digital currency sank as much as 22% to $6,579, before trading at $7,054 as of 4:08 p.m. in New York. It has erased about 65% of its value from a record high $19,511 in December. Rival coins also retreated on Monday, with Ripple losing as much as 21% and Ethereum and Litecoin also weaker. “Although no fundamental change triggered this crash, the parabolic growth this market has experienced had to slow down at some point,” Lucas Nuzzi, a senior analyst at Digital Asset Research, wrote in an email. “All that it took this time was a large lot of sell orders.”

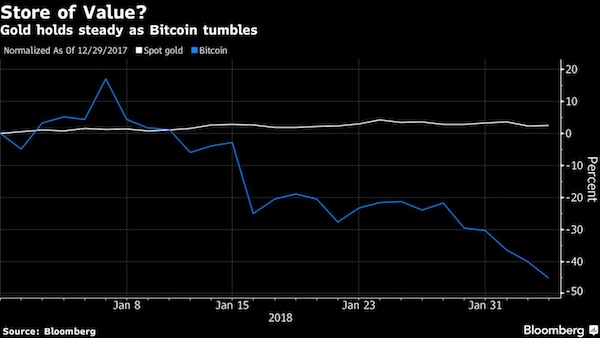
Weeks of negative news and commercial setbacks have buffeted digital tokens. Lloyds joined a growing number of big credit-card issuers have said they’re halting purchases of cryptocurrencies on their cards, including JPMorgan and Bank of America. Several cited risk aversion and a desire to protect their customers. SEC Chairman Jay Clayton said he supports efforts to bring clarity to cryptocurrency issues and that existing rules weren’t designed with such trading in mind, according to prepared remarks for a Senate Banking Committee hearing Tuesday on virtual currencies. Bitcoin’s longest run of losses since Christmas day has coincided with investors exiting risky assets across the board, with stocks retreating globally. Bitcoin so far seems to be struggling to live up to any comparison with gold as a store of value, which is an argument made by some of its supporters. Bullion edged higher as other safe havens – the yen, Swiss franc and bonds – also gained.

Read more …

Stability breeds instability. Minsky.

• The Fed’s Dependence On Stability (Roberts)

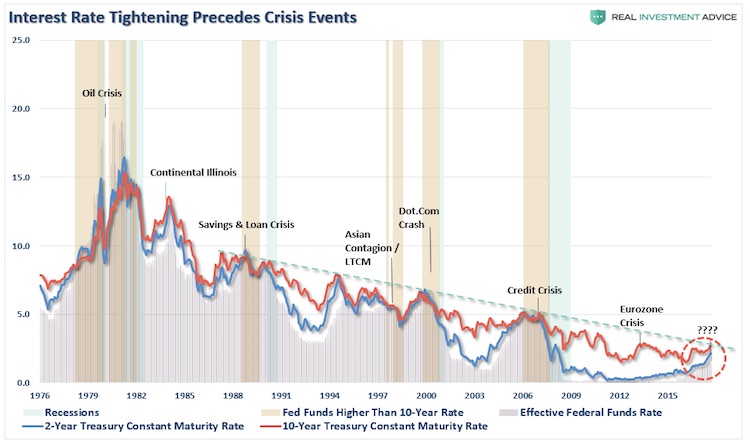
Last week, I discussed how the Federal Reserve will likely be the culprits of whatever sparks the next major financial crisis. To wit: “In the U.S., the Federal Reserve has been the catalyst behind every preceding financial event since they became ‘active,’ monetarily policy-wise, in the late 70’s. As shown in the chart below, when the Fed has lifted the short-term lending rates to a level higher than the 10-year rate, bad ‘stuff’ has historically followed.” This past week, as Ms. Yellen relinquished her control over the Federal Reserve to Jerome Powell, the Fed stood by its position they intend to hike rates 3-more times in 2018.

With the entirety of the financial ecosystem now more heavily levered than ever, due to the Fed’s profligate measures of suppressing interest rates and flooding the system with excessive levels of liquidity, the “instability of stability” is now the biggest risk. The “stability/instability paradox” assumes that all players are rational and such rationality implies avoidance of complete destruction. In other words, all players will act rationally and no one will push “the big red button.” The Fed is highly dependent on this assumption. After more than 9-years of the most unprecedented monetary policy program in human history, they are now trying to extricate themselves from it. The Fed is dependent on “everyone acting rationally,” particularly as they try to reduce their balance sheet. The first attempt was seen in January. Well…sort of…but not really.

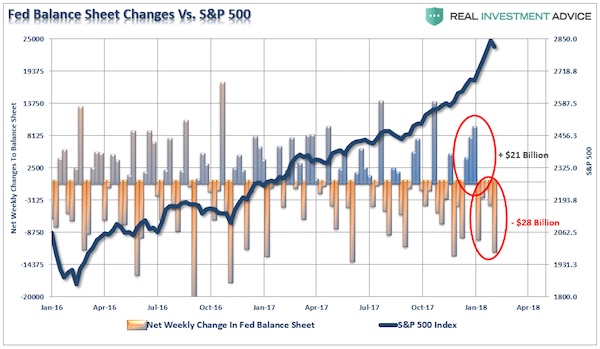
While the Fed did “reduce” their holding by $28 billion in January, it followed an increase of $21 billion in December. Which brings up several questions? Was the ramp up/run down just a test of the market’s stability? (Seems likely.) With the market throwing a “conniption fit” last week, will the Fed rethink their balance sheet reduction program? (Probably) More importantly, with the government on the verge of another “shut down” this coming week due to the expiration of the “continuing resolution” from three weeks ago, will the Fed continue its current path in the face of an event that could lead to fiscal instability? (Probably not) We will soon find out.

Read more …

There will be a second Special Counsel.

• A Quandary (Jim Kunstler)

The Resistance pulled out all the stops last week in its shrieking denunciation of the Nunes Memo, and the various complaints had one thing in common: a complete lack of interest in the facts of the matter, in particular the shenanigans in the upper ranks of the FBI. Give a listen, for instance, to last Thursday’s Slate’s Political Gabfest with David Plotz, John Dickerson, and Emily Bazelon, the three honey-badgers of Resistance Radio (like the fabled honey-badgers of the veldt, they don’t give a shit about any obstacles in pursuit of their quarry: Trump). They’ve even been able to one-up Nassim Taleb’s defined category of “intellectuals-yet-idiots” to intellectuals-yet-useful-idiots.

The New York Times, with its termite-mound of casuistry artists, managed to concoct a completely inside-out “story” alleging that the disclosure in the Nunes memo of official impropriety at the FBI was in itself an “obstruction of justice,” since making the FBI look bad might impede their ability to give Trump the much wished-for bum’s rush from the White House. There was already enough dishonesty in our national life before the Left side of the political transect decided to ally itself with the worst instincts of the permanent Washington bureaucracy: the faction devoted to ass-covering. The misconduct at the FBI and DOJ around the 2016 election is really quite startling.

How is it not disturbing that Associate Deputy Attorney General Bruce Ohr brokered the Steele Dossier between the Fusion GPS psy-ops company and the FBI, when Fusion GPS was employed by the Clinton campaign, and Ohr’s wife worked for Fusion GPS? How is it okay that this janky dossier was put over on a FISA court judge to get warrants to surveil US citizens in an election campaign? How was it okay for Deputy FBI Director Andrew McCabe’s wife to accept $700,000 from the Clinton family’s long-time bag-man, Terry McAuliffe, when she ran for a Virginia State Senate seat, a few months before McCabe assumed command of the Hillary email investigation? How was it not fishy that FBI Deputy Assistant Director of the Counterintelligence Division, Peter Strock, and his workplace girlfriend, FBI lawyer (for Andrew McCabe), Lisa Page appeared to plot against Trump in their many cell-phone text exchanges?

Read more …

Deceit as the big killer.

• 21st Century Plague (MarkGB)

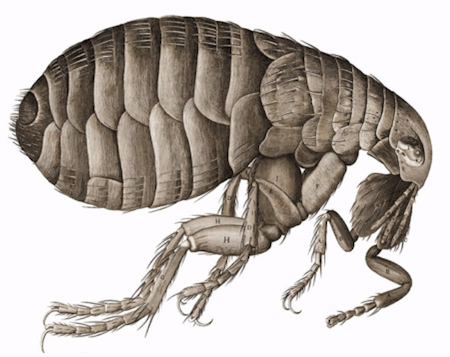
The Black Death was a medieval pandemic which swept through the ‘old world’ in the 14th Century. It arrived in Europe from Asia in the 1340s and killed an estimated 25 million people, about 50% of the population. The social and economic consequences of this were ‘permanent’: it created a labour shortage which ended the medieval institution of serfdom. In short: Increased demand for labour + reduced supply of labour + chaos = collapse of status quo. What emerged from the chaos was a rudimentary ‘free market’ in labour and goods. The age of capitalism had begun…the unforeseen consequence of a plague, borne on a creature that looked like this:

The pandemic we face in the 21st Century is a psychological phenomenon rather than a biological one, but in my view, it is equally parasitic. Its name is ‘deceit’, and our political & economic institutions are riddled with it. The majority of people I speak to know that something is badly wrong with our societies and our economies – they feel it when they pick up a newspaper, turn on the TV or engage with the internet. Some of us try to disconnect from the drama and the constant stream of claim and counterclaim, in order to try to ‘get on with normal lives’ – but we feel something is badly wrong nevertheless. Some of us gather ourselves into political parties, protest movements, and/or intellectual cliques in order to discuss how to ‘fix’ what ails us.

And every 4 or 5 years, the majority of us go out and vote for an individual or a group of people that we hope will bring change…and then…we get more of the same. We just got, for example, the 3rd president in a row who ran on a promise of peace, and then immediately went looking for war. What the majority of people have not yet realised is that the politician’s ‘promise’ is part of the deceit – it’s what keeps you coming back for more, hoping this time will be different. It never is – it’s just a new coat of paint on a crumbling wall. What the majority of people have not yet realised is that the politician’s ‘promise’ is part of the deceit – it’s what keeps you coming back for more

It matters little whether you believe an individual candidate is a ‘good’ person, or a ‘bad’ person. Once in office he or she becomes a tool for the maintenance of the status quo – evidently. Why is this? Because the system is not run for your benefit. Its primary function is the concentration of power and wealth within the system itself, to serve the vested interests of a relatively tiny group of people. These are the manifestations of the 21st-century plague – the institutions of deceit: 1) A monetary system rigged for the banks and globalised corporations. 2) A military-industrial complex that requires endless war. 3) Politicians that are controlled by 1 & 2. 4) A mainstream media that is complicit with 1 to 3.

Read more …

Expect appeal after appeal.

• UK Court To Rule On Lifting Assange Arrest Warrant (AFP)

A British court is to decide Tuesday whether to lift a UK arrest warrant for Julian Assange, potentially paving the way for the WikiLeaks founder to leave the Ecuadorian embassy in London where he has spent the last five years. If the court rules in Assange’s favour, allowing him to leave the embassy in the British capital without fear of arrest, it would be the first time that he has stepped outside embassy grounds since seeking asylum there in June 2012. Assange entered the Ecuadoran embassy to dodge a European arrest warrant and extradition to Sweden over a 2010 probe in the Scandinavian country into rape and sexual assault allegations.

Sweden dropped its investigation last year, but British police are still seeking to arrest Assange for failing to surrender to a court after violating bail terms during his unsuccessful battle against extradition. Assange’s lawyer Mark Summers told a London court last week that the warrant had “lost its purpose and its function”. He said Assange had been living in conditions “akin to imprisonment” and his “psychological health” has deteriorated and was “in serious peril”. The court heard that the 46-year-old was suffering from a bad tooth, a frozen shoulder and depression. But prosecutor Aaron Watkins called Assange’s court bid “absurd”. “The proper approach is that when a discrete, standalone offence of failing to surrender occurs, it always remains open to this court to secure the arrest,” Watkins said.

Read more …

You like this future? It’s all yours. Who needs people?

• Robots Will Care For 80% Of Elderly Japanese By 2020 (G.)

Japan’s elderly are being told to get used to being looked after by robots. With Japan’s ageing society facing a predicted shortfall of 370,000 caregivers by 2025, the government wants to increase community acceptance of technology that could help fill the gap in the nursing workforce. Developers have focused their efforts on producing simple robotic devices that help frail residents get out of their bed and into a wheelchair, or that can ease senior citizens into bathtubs. But the government sees a wider range of potential applications and recently revised its list of priorities to include robots that can predict when patients might need to use the toilet. Dr Hirohisa Hirukawa, director of robot innovation research at Japan’s National Institute of Advanced Industrial Science and Technology, said the aims included easing the burden on nursing staff and boosting the autonomy of people still living at home.

“Robotics cannot solve all of these issues; however, robotics will be able to make a contribution to some of these difficulties,” he said. Hirukawa said lifting robotics had so far been deployed in only about 8% of nursing homes in Japan, partly because of the cost and partly because of the “the mindset by the people on the frontline of caregiving that after all it must be human beings who provide this kind of care”. He added: “On the side of those who receive care, of course initially there will be psychological resistance.” Hirukawa’s research centre has worked on a government-backed project to help 98 manufacturers test nursing-care robotic devices over the past five years, 15 of which have been developed into commercial products.

Read more …

This is what Brussels and Berlin invite by ignoring the issue.

• Berlusconi Pledges To Deport 600,000 Illegal Immigrants From Italy (G.)

Silvio Berlusconi has pledged to deport 600,000 illegal immigrants from Italy should his centre-right coalition enter government after elections on 4 March, as tensions simmer over the shooting of six Africans by a far-right extremist on Saturday. The 81-year-old rightwing former prime minister said in a TV interview that immigration was a “social bomb ready to explode in Italy” and that the shooting in Macerata posed a security problem. “Immigration has become an urgent question, because after years with a leftwing government, there are 600,000 migrants who don’t have the right to stay,” said Berlusconi. “We consider it to be an absolute priority to regain control over the situation.” Berlusconi’s Forza Italia has forged an alliance with two far-right parties, the Northern League and the smaller Brothers of Italy, for the elections.

The three-time former prime minister is banned from running for office after being convicted of tax fraud, but could still end up pulling the strings of power should the coalition gain enough of a majority to govern. “When we’re in government we will invest many resources in security,” he said. “We will boost police presence and reintroduce the ‘Safe Streets’ initiative … Our soldiers will patrol the streets alongside police officers.” Berlusconi took a swipe at the EU for failing to share the burden of Italy’s migrant arrivals, saying: “Today, Italy counts for nothing in Brussels and the world. We will make it count again.” Italy is a favoured landing point on Europe’s southern coastline for people making the perilous journey across the Mediterranean, often on board unseaworthy boats, to enter the continent. However, 2017 was a turning point for Italy: the country went from large-scale arrivals in the first six months to a sharp drop-off, thanks to a controversial agreement between the EU and Libya.

Read more …

Jun 052015
 
 June 5, 2015  Posted by at 12:49 pm Finance Tagged with: , , , , , , , , ,  1 Response »


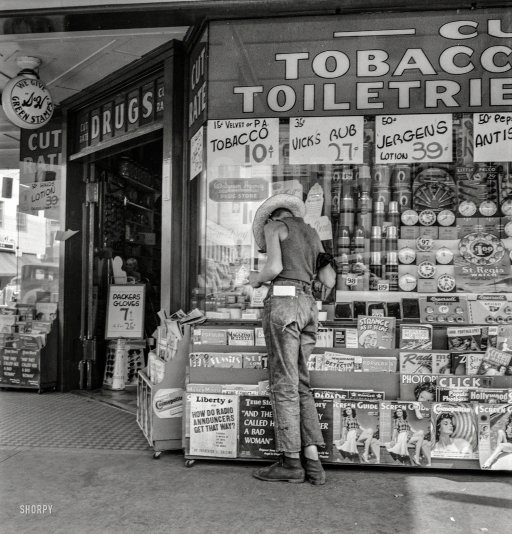
Dorothea Lange Farm boy at main drugstore, Medford, Oregon 1939

Central bankers have promised ad nauseum to keep rates low for long periods of time. And they have delivered. Their claim is that this helps the economy recover, but that is just a silly idea.

What it does do is help create the illusion of a recovering economy. But that is mostly achieved by making price discovery impossible, not by increasing productivity or wages or innovation or anything like that. What we have is the financial system posing as the economy. And a vast majority of people falling for that sleight of hand.

Now the central bankers come face to face with Hyman Minsky’s credo that ‘Stability Breeds Instability’. Ultra low rates (ZIRP) are not a natural phenomenon, and that must of necessity mean that they distort economies in ways that are inherently unpredictable. For central bankers, investors, politicians, everyone.

That is the essence of what is being consistently denied, all the time. That is why QE policies, certainly in the theater they’re presently being executed in, will always fail. That is why they should never have been considered to begin with. The entire premise is false.

Ultra low rates are today starting to bite central bankers in the ass. The illusion of control is not the same as control. But Mario and Janet and Haruhiko, like their predecessors before them, are way past even contemplating the limits of their powers. They think pulling levers and and turning switches is enough to make economies do what they want.

Nobody talks anymore about how guys like Bernanke stated when the crisis truly hit that they were entering ‘uncharted territory’. That’s intriguing, if only because they’re way deeper into that territory now than they were back then. Presumably, that may have something to do with the perception that there actually is a recovery ongoing.

But the lack of scrutiny should still puzzle. How central bankers managed to pull off the move from admitting they had no idea what they were doing, to being seen as virtually unquestioned maestros, rulers of, if not the world, then surely the economy. Is that all that hard, though, if and when you can push trillions of dollars into an economy?

Isn’t that something your aunt Edna could do just as well? The main difference between your aunt and Janet Yellen may well be that Yellen knows who to hand all that money to: Wall Street. Aunt Edna might have some reservations about that. Other than that, how could we possibly tell them apart, other than from the language they use?

The entire thing is a charade based on perception and propaganda. Politicians, bankers, media, the lot of them have a vested interest in making you think things are improving, and will continue to do so. And they are the only ones who actually get through to you, other than a bunch of websites such as The Automatic Earth.

But for every single person who reads our point of view, there are at least 1000 who read or view or hear Maro Draghi or Janet Yellen’s. That in itself doesn’t make any of the two more true, but it does lend one more credibility.

Draghi this week warned of increasing volatility in the markets. He didn’t mention that he himself created this volatility with his latest QE scheme. Nor did anyone else.

And sure enough, bond markets all over the world started a sequence of violent moves. Many blame this on illiquidity. We would say, instead, that it’s a natural consequence of the infusion of fake zombie liquidity and ZIRP rates.

The longer you fake it, the more the perception will grow that you can’t keep up the illusion, that you’re going to be found out. Ultra low rates may be useful for a short period of time, but if they last for many years (fake stability) they will themselves create the instability Minsky talked about.

And since we’re very much still in uncharted territory even if no-one talks about it, that instability will take on forms that are uncharted too. And leave Draghi and Yellen caught like deer in the headlights with their pants down their ankles.

The best definition perhaps came from Jim Bianco, president of Bianco Research in Chicago, who told Bloomberg: “You want to shove rates down to zero, people are going to make big bets because they don’t think it can last; Every move becomes a massive short squeeze or an epic collapse – which is what we seem to be in the middle of right now.”

With long term ultra low rates, investors sense less volatility, which means they want to increase their holdings. As Tyler Durden put it: ‘investors who target a stable Value-at-Risk, which is the size of their positions times volatility, tend to take larger positions as volatility collapses. The same investors are forced to cut their positions when hit by a shock, triggering self- reinforcing volatility-induced selling. This is how QE increases the likelihood of VaR shocks.’

QE+ZIRP have many perverse consequences. That is inevitable, because they are all fake from beginning to end. They create a huge increase in inequality, which hampers a recovery instead of aiding it. They are deflationary.

They distort asset values, blowing up prices for stocks and bonds and houses, while crushing the disposable incomes in the real economy that are the no. 1 dead certain indispensable element of a recovery.

You would think that the central bankers look at global bond markets today, see the swings and think ‘I better tone this down before it explodes in my face’. But don’t count on it.

They see themselves as masters of the universe, and besides, their paymasters are still making off like bandits. They will first have to be hit by the full brunt of Minsky’s insight, and then it’ll be too late.

Jun 042014
 
 June 4, 2014  Posted by at 4:07 pm Finance Tagged with: , , , ,  9 Responses »


Barbara Wright Damaged Lives, Knoxville, Tenn., 1941

The Fed itself has stated many times over the past years that it intends to keep interest rates low. And now it starts complaining about low volatility. It looks like Yellen et al want to have their cake and eat it too. Perhaps they should have paid a little more attention to Hyman Minsky. Who long ago wrote – paraphrased – that if and when markets are perceived as being stable, it’s that very perception will make them unstable, because stability, i.e. low volatility, will drive investors into riskier asset purchases. The Fed’s manipulation-induced ultra-low rates have achieved just that, and now they’re surprised?

They are the ones who pushed down rates and threw trillions in QE on top of those low rates, and they had no idea that could create asset bubbles and increase risk-taking? Some of this stuff is simply wanting in credibility. But then, any and all manipulations of markets are poised to end badly, and certainly when the manipulators claim to represent, and function in, a free market.

Now they want more volatility, something that could be achieved by raising rates, especially if it’s done without all the forward guidance, but that would put the housing sector – or the housing bubble really – at risk, as well the “recovery” no-one is yet prepared to let go of. So all the Eccles occupants have left is words. They can try forward misguidance, leave the option open of surprise moves in oder to catch investors off guard. Sort of like a poker game.

The problem with that is no-one would believe that Yellen is a better poker player than even the average investor. Another problem is such intentional insecurity would hit the housing market, and stocks, anyway. You can coerce the most gullible American into buying a property if (s)he thinks rates will remain low, but not if you take away that belief.

The essence of what Minsky said is deceptively simple, and perhaps that’s why it’s so poorly understood: it’s not possible to “create” a stable market, because the very moment you try, you create its opposite, instability. Minsky’s financial instability hypothesis is quite clear, and frankly, if you don’t believe him you should first prove him wrong before trying to do what he says can’t be done anyway. If you feel you need to provide forward guidance because markets are weak and you think they’ll strengthen if you say you’ll keep rates at a certain level, you need to realize that the stability you’ve trying to convey will of necessity be self destructive.

Markets need uncertainty to be able to function properly. That’s what Minsky said. And trying to take away that uncertainty with forward guidance and trillions of dollars is a move that cannot end well. Markets are populated with people, and if you take uncertainty out of people’s individual lives, there’s no telling what they’ll do either, other than it’s certain they’ll increase the risks they take. And why not, if they think nothing can happen to them? If you’re young and feel invincible, why not down 20 shots of tequila in an hour or jump off a cliff? It’s a matter of risk assessment.

But we don’t need to get into psychology here, it’s very easy to see why Minsky was dead on. And it’s equally easy to understand why what follows from that is that the Fed, or any central bank or government, should stay away from manipulating the free markets they so favor but which are no longer free the moment the manipulation starts. If and when investors, be they pension fund managers or just people looking to buy their first home, are barred though central bank manipulation from discovering what an asset, any asset, is actually worth, and that’s where we find ourselves at the moment, a world of uncertainty is waiting for us. There is no other option.

We live in a control economy today, and we have no reasons to do that other than the Fed seeking to protect their banker friends from revealing their losses and their balance sheets. Because that’s what at stake here: if Yellen takes her fingers of the keyboard, and so does the Treasury, we’ll see a truth finding process that will wipe out some of the big players, and lots of small ones, like recent mortgage borrowers who‘ve bought in on artificially elevated price levels.

That will be hurtful, but we should understand that it’s inevitable that one day the truth shall be told. Maybe not about who shot JFK, but certainly about what your home is truly worth. The longer we postpone that day, the poorer our poor will be and the more of us will be among the poor. And that in turn will tear our societies apart, which won’t benefit anyone, not even those who escaped with the loot. Tell me again, what other purpose does the Fed serve but manipulating markets?

I don’t see any, and if I’m right, and so is Minsky – and he is – , we have ourselves a situation on our hands. I am certain there are people inside the Fed who have read, and understood, Minsky’s financial instability hypothesis. What kind of light does that shine on them, as they continue to be accessories to current policies?

Wait a minute. What about my recovery?

• First Quarter Corporate Profits Tumble Most Since Lehman (Zero Hedge)

As SocGen’s Albert Edwards conveniently points out, during the excitement of the downward revision of Q1 US GDP from +0.1% to -1.0% investors seem not to have noticed a $213bn, 10% annualized slump in the US Bureau of Economic Analysis’s (BEA) favored measure of whole economy profits, defined as profits from current production. Also known as economic profits, the BEA makes adjustments to remove inventory profits (IVA) and to put depreciation on an economic instead of a tax basis (CCAdj). Edwards shows the stark difference between the BEA’s calculation for post-tax headline profits (up 5.3% yoy) and economic profits (down 6.8% yoy) in the chart below. In short: the plunge in actual corporate profits in Q1 was the biggest since Lehman!

Read more …

Look beyond the S&P and it’s like a bomb went off.

• The Average Russell 2000 Stock Is Down 22% From Its Highs (Zero Hedge)

It’s hard to “fully commit” to this rally given “corroded internals,” warns FBN Securities technical analyst JC O’Hara in note. As we previously noted, new highs are extremely negatively divergent from the index strength, as are smarket money flows, but what has O’Hara “very disturbed” is the fact that the average Russell 2000 stock is over 22% below its 52-week highs. As O’Hara notes, investors are ignoring “technical signals that have historically forewarned” of a drop; they’re “jumping onto a plane where only one of the two engines is working. The plane does not necessarily have to crash but the risk of an accident is much higher when the plane is not firing on all cylinders.”

“Smart money” Flow is decidely the wrong way…

Read more …

I had no idea …

• Fed Officials Growing Wary of Market Complacency (WSJ)

Federal Reserve officials are starting to wonder whether a tranquillity that has descended on financial markets is a sign that investors have become unafraid of the type of risk that could lead to bubbles and volatility. The Dow Jones Industrial Average, up a steady if unspectacular 1% since the beginning of the year, has consolidated big gains registered last year. The VIX, a measure of expected stock-market fluctuations based on options trading, has gone 74 straight weeks below its long-run average—a string of steadiness not seen since 2006 and 2007, before the financial crisis and recession. Moreover, the extra return that bond investors demand on investment-grade corporate debt over low-risk Treasury bonds, at one%age point, hasn’t been this low since July 2007. The lower this “spread,” the less risk-averse are bond investors.

The Fed’s growing worry—which could influence future interest rate decisions—is that if investors start taking undue risk it could lead to economic turbulence down the road. “Volatility in the markets is unusually low,” William Dudley, president of the Federal Reserve Bank of New York and a member of chairwoman Janet Yellen’s inner circle, said after a speech last week. “I am a little bit nervous that people are taking too much comfort in this low-volatility period. As a consequence, they’ll take more risk than really what’s appropriate.” One example of increased risk taking: Issuance of low-rated U.S. dollar-denominated junk bonds last year hit a record $366 billion, more than twice the level reached in the years before the 2008 financial crisis, according to financial-data provider Dealogic.

Richard Fisher, president of the Federal Reserve Bank of Dallas, added to the chorus of concern over complacency in an interview Tuesday. “Low volatility I don’t think is healthy,” he said. “This indicates to me a little bit too much complacency that [interest] rates are going to stay at abnormally low levels forever.” Many officials appear more inclined to talk about market risks than act to pre-empt them given the worry about cutting off a fragile recovery with early interest-rate hikes. Though risk-taking is on an upswing, they don’t see a buildup of serious threats to the broader stability of the financial system. Fed officials are expected at their June meeting to keep gradually scaling back their purchases of mortgage and Treasury bonds and stick to the plan to keep short-term interest rates near zero, where they have been since the height of the financial crisis in late 2008.

Read more …

Payment-in-kind notes are a silly risk raising “product” that offers a bit more yield in exchange for crazy risks: “We call it the yield-hunger games … ”

• Sales Of Boom-Era ‘PIK’ Debt Soar (FT)

The sale of complex debt products popular in the pre-crisis boom years has soared in 2014 as investors have embraced riskier assets in exchange for higher returns. Issuance of US-marketed payment-in-kind notes – which give a company the option to pay lenders with more debt rather than cash in times of crisis – has almost doubled so far this year to reach $4.2bn, according to Dealogic. That is the highest amount since the same period of 2007, when a record $5.6bn in PIK notes were sold. The esoteric debt structures were a popular way for companies to finance big leverage buyouts during the boom era that defined the 2006-2007 credit bubble. More recently, investors in PIK notes have been encouraged by low corporate default rates and the chance to earn some additional returns.

“We call it the yield-hunger games,” said Matt Toms, head of US public fixed income for Voya Investment Management. “In this environment of very low yields and very low volatility, any extra yield that products such as these may offer already helps.” On average, PIK notes yield 50 basis points more than comparable high-yield bonds. Average yields on junk-rated bonds stood at 4.99 per cent on Tuesday, according to Barclays indices. A wave of junk-rated borrowers, including Wise Metals, a producer of metal containers, Infor, a software company and Interface Security have included PIK structures as part of new bond deals this year. This week, Jack Cooper, which transports new and pre-owned passenger vehicles, is expected to offer $150m in five-year senior PIK notes.

Read more …

I think we all know where QE goes. It’s not us.

• Where $1 Of QE Goes: The Untold Story (Cyniconomics)

Sometimes the most interesting results are the ones you didn’t see coming. We recently picked through financial flows data looking for clues about where a dollar of quantitative easing (QE) ends up. For example, we wondered who parts with the bonds that find new homes on the Fed’s balance sheet. Dealers sometimes pass bonds straight from the Treasury to the Fed, but are they buying other QE-ready bonds mostly from households, pension funds, foreigners or other financial institutions? Also, can financial flows help us to guess at how much (if any) a dollar of QE adds to spending? We didn’t expect clear answers and were surprised to stumble across this:

Needless to say, the chart raises a bunch of new questions, such as: • Didn’t the Fed expect QE to complement other types of bank credit? • What do they think of data suggesting it only displaced private sources of credit? • Do they have any other explanations for the results in the chart? Unfortunately, our direct line to the Eccles Building isn’t working this week, which prevents us from answering these questions.

We’re left to form our own conclusions. What to make of the “argyle effect”? Our main takeaway is that the extra reserves created by QE aren’t so much an addition to bank balance sheets as a substitution. The addition story is the one we normally hear. It often leads to confused commentary, such as the mistaken ideas that banks “multiply up” or can “lend out” reserves. (We discussed these fallacies here.) But even without the confused commentary, the addition story doesn’t, well, add up. According to financial flows data, it’s more accurate to say that QE’s extra reserves merely replaced other forms of balance sheet expansion. That’s a substitution story. It’s consistent with the fact that banks can neutralize QE’s effects with derivatives overlays and other portfolio adjustments. They can rearrange exposures to mimic a balance sheet of equal size and risk that’s not stuffed with reserves. (See this related discussion by blogger Tyler Durden.)

Think of it this way: Your banker already knows how many slices of meat he wants in his sandwich. When the Fed shows up with a thick package straight from the deli, it saves him a trip of his own. He still makes the same sized sandwich, but it’s filled mostly by central bankers, and he adjusts it to his liking by varying the condiments. Now, the full picture is more complicated than that, mainly because reserves move from bank to bank. For example, data shows a large amount of QE reserves accumulating at U.S. offices of foreign banks, where they appear to be funded by foreign lenders. You can think of these reserves as a means of recycling America’s current account deficits back into U.S. dollar assets. In other words, QE seems to encourage foreigners to swap other types of dollar assets for reserves at the Fed, supporting the substitution story.

Read more …

• Trading To Influence Gold Price Fix Was ‘Routine’ (FT)

When the UK’s financial regulator slapped a £26m fine on Barclays for lax controls related to the gold fix, it offered more ammunition to critics of the near-century-old benchmark. But it also gave precious metal traders in the City of London plenty to think about. While the Financial Conduct Authority says the case appears to be a one off – the work of a single trader – some market professionals have a different view. They claim the practice of nudging a tradeable benchmark in order to protect a “digital” derivatives contract – as a Barclays employee did – was routine in the industry. As a result, customers of Barclays and other market-making banks may be looking to see if they too have cause for complaint, according to one hedge fund manager active in the gold market.

“If I was at the FCA I would be looking at all banks trading digitals. This could be the tip of the iceberg – there’s a massive issue with exotic derivatives and barriers.” In the City, digital options are common in the precious metals sector and, especially, in forex trading. A payout is triggered if a predetermined price – or “barrier” – is breached at expiry date. If it is not, the option holder gets nothing. One former precious metals manager at a big investment bank says there has long been an understanding among market participants that sellers and buyers of digitals would try to protect their positions if the benchmark price and barrier were close together near expiry. “These are not Ma and Pa products, they are for super-professionals,” says the former manager. “There’s a fundamental belief that both parties can aggress or defend their book, and I would have expected my traders to do so.”

In the case of gold, this means trying to move the benchmark price, which is set during the twice daily auction “fixing” process run by four banks, including Barclays. That is what the Barclays trader, Daniel Plunkett, did on June 28, 2012. Exactly a year earlier, the bank had sold an options contract to an unnamed customer stating that if after 12 months the gold price were above $1,558.96 a troy ounce, the client would receive $3.9m. By placing a large sell order on the fix, Mr Plunkett pushed the gold price beneath the barrier, thus avoiding the payout. After the counterparty complained, the FCA became involved. Barclays paid the client the $3.9m, and was fined. Mr Plunkett was also fined – £95,600 – and banned from working in the City.

Read more …

Now that’s a surprise!

• Over Half Of Americans Can’t Afford Their Houses (MarketWatch)

As the housing market slowly recovers, a majority of homeowners and renters are finding it hard to meet rising rents and mortgage payments, new research finds. Over half of Americans (52%) have had to make at least one major sacrifice in order to cover their rent or mortgage over the last three years, according to the “How Housing Matters Survey,” which was commissioned by the nonprofit John D. and Catherine T. MacArthur Foundation and carried out by Hart Research Associates. These sacrifices include getting a second job, deferring saving for retirement, cutting back on health care, running up credit card debt, or even moving to a less safe neighborhood or one with worse schools.

[..] … at least 15% of American homeowners (or residents of 78 counties across the country) were living in housing markets where the monthly mortgage payment on a median-priced home requires more than 30% of the monthly median household income – long considered the maximum for rent/mortgage repayments. Housing costs above that threshold are “unaffordable by historic standards,” says Daren Blomquist, vice president at real estate data firm RealtyTrac. In New York county/Manhattan, mortgage payments represent 77% of the median income and in San Francisco County represents 70%. Although mortgage rates are still quite low, down payments, poor credit and tighter lending standards remain three of the biggest hurdles for buying a home, especially among young people, Blomquist says.

“The slow jobs recovery for young adults has made it harder for them to save and to get a mortgage.” Some 84% of young people are delaying major life decisions due to the poor economy, according to a 2013 survey by Generation Opportunity, a nonprofit think tank based in Arlington, Va. About 43% of respondents in the “How Housing Matters Survey” say owning a home is no longer “an excellent long-term investment and one of the best ways for people to build wealth and assets,” and over half say buying a home has become less appealing. Although 70% of renters aspire to own a home, some 58% believe that “renters can be just as successful as owners at achieving the American dream.”

Read more …

Too late.

• The Only Way To Fairness In Housing Is To Tax Property (Monbiot)

You can judge the extent to which ours has become a rentier economy by the furious response to Ed Miliband’s timid proposals to regulate letting. “Venezuelan-style rent controls,” said the Conservative party chairman, Grant Shapps. “The most stupid and counter-productive policy that we have seen from a mainstream party leader for many years,” stomped Stephen Pollard for the Daily Mail. While Miliband’s proposals would be of some use, they ignore the underlying problem: a consistent failure to tax property progressively and strategically. The United Kingdom is remarkable in that it imposes no land value tax and no capital gains tax on principal residences; and charges council taxes that appear to be the most regressive major levies of any kind anywhere in western Europe.

The only capital tax on first homes is stamp duty, but that recoups a tiny proportion of their value when averaged across the years of ownership. Remarkably, it is imposed on the buyer, not the seller. Why should capital gains tax not apply to first homes, when they are the country’s primary source of unearned income? Why should council tax banding ensure that the owners of cheap houses are charged at a far greater relative rate than the owners of expensive houses? Why should Rinat Akhmetov pay less council tax for his £136m flat in London than the owners of a £200,000 house in Blackburn? Why should second, third and fourth homes not be charged punitive rates of council tax, rather than qualifying, in many boroughs, for discounts?

The answer, of course, is power: the power of those who benefit from the iniquities of our property market. But think of what fairer taxes would deliver. House prices have risen so much partly because all the increment accrues to the owner. Were the state to harvest a significant part of this unearned income, it would hold prices down and dampen speculative booms. A land value tax would penalise the owners of empty homes: the resulting rise in supply would also help to suppress prices. The money the state recouped could be used to build affordable housing.

Read more …

13 months of falling prices. What does that mean again?

• Discounts Drive British Retail To 13th Month Of Deflation (Guardian)

Discounts on clothing and bank holiday offers on DIY and gardening products resulted in prices in British shops continuing to fall last month, according to the British Retail Consortium. With prices across stores falling 1.4% on the year, it was the 13th straight month of deflation, the trade association said. It was, as usual, non-food items that drove the deflation, with their prices falling for a 14th month running. There was some let-up on food too, where inflation held at 0.7%, the lowest on record for the BRC-Nielsen Shop Price Index. “Food inflation is still low, many supermarkets are price-cutting and non-food prices remain deflationary, so the high street continues to generate little inflationary pressure,” said Mike Watkins, head of retailer and business insight at Nielsen.

“Little in the way of immediate seasonal or weather-related price increases is anticipated, so the outlook for the next three months is for relatively stable shop price inflation.” The latest news of benign price pressures on the high street will bring reassurance to Bank of England policymakers as they meet this week to debate how much longer they can leave interest rates at their record low of 0.5%. City economists do not expect any action at this meeting of the monetary policy committee, but some predict an interest rate rise before the end of the year. The latest official data showed consumer price inflation came in at 1.8% in April. That was up from 1.6% the month before, but was still below the Bank’s 2% target.

Read more …

Well, they can blame Lidl and Aldi for now.

• UK Supermarket Chain Tesco Reports Steep Fall in Sales (CNBC)

U.K. supermarket chain Tesco on Wednesday reported a sharp fall in first-quarter sales, hurt by price cuts and subdued consumer spending. First quarter same-store sales, excluding fuel, fell 3.7%. In a news release, Tesco, which is the grocery market leader in Britain, described the results as “in line with last year’s exit rate, despite the significant reduction in untargeted promotions and deflationary impact of investment in lower prices.” Industry price cuts have driven lower growth in recent months for the U.K. “big four” supermarkets—Tesco, Asda, Sainsbury’s and Morrisons. The latest supermarket share figures from Kantar Worldpanel, published on Tuesday for the 12 weeks ending May 25, 2014, show a slowdown in grocery market growth to 1.7%—the lowest level for at least 11 years.

“To date, it is unclear whether these price cuts are part of normal industry price investment or something more material and the fact that the food commodity price index supports lower food inflation has not helped clarify the issue,” Deutsche Bank analysts said in a report on Tuesday. Tesco Chief Executive Philip Clarke said on Wednesday that Tesco sales had been hit by the supermarket’s own price cuts. He warned investors in a news call not to count on sales improvements in the next few quarters. “Since February, we have cut prices on the products that matter most, cut home delivery charges and made Grocery Click & Collect free,” Clarke said in the news release. “As expected, the acceleration of our plans is impacting our near-term sales performance. The first quarter has also seen a continuation of the challenging consumer trends in the U.K., reflecting still subdued levels of spending in addition to the more structural changes taking place across the retail industry.”

Read more …

What a mess Britain is.

• RBS Clamps Down On Large Mortgages As Property Bubble Fears Grow (Guardian)

Royal Bank of Scotland has become the second major lender to clamp down on large mortgages, announcing it will restrict lending on loans above £500,000 as fears grow that the London property market is entering bubble territory. The move came as figures from Nationwide building society showed UK house prices hit a new peak in May – breaking the previous high reached before the financial crisis – to hit an average of £186,512. The announcement by the state-backed RBS, which accounts for one in 10 of all UK mortgages, follows a similar decision by the industry leader, Lloyds Banking Group, which is also part-owned by the taxpayer. Like Lloyds, RBS will limit mortgages under its RBS and Natwest brands to four times the applicant’s income if more than £500,000 is being borrowed.

It will also restrict these loans to a maximum 30-year term, in order to prevent borrowers taking out larger mortgages by spreading out repayment over a longer period.A spokesperson for RBS said: “We are focused on looking after the interests of our customers and ensuring that they only take on mortgage lending that they can afford.” The move is likely to increase pressure on other lenders to follow suit so they do not become overexposed to the London property market, where prices have increased by 17% during the past year. According to the Office for National Statistics, the average house price in the capital is £459,000. Andrew Montlake, director at Coreco Mortgage Brokers, said: “There seems to be no coincidence that the two partly state owned banks are the first ones to act in this manner.”

Read more …

Denial is easier.

• Tories Dismiss EU Advice To Cool UK Housing Market (Guardian)

Senior Conservatives have dismissed advice from European officials that the UK needs to rein back its booming property market, saying George Osborne does not require help from Brussels to help run the economy. Boris Johnson, the London mayor, told Brussels officials “to take a running jump” while Chris Grayling, the justice secretary, rejected the European Commission analysis suggesting the UK should limit the Help to Buy scheme, build more houses and reform property taxes. Speaking on the byelection trail in Newark, he said the EU’s executive body was welcome to offer its view but it “doesn’t mean we’re going to change what we do”. Johnson told London’s Evening Standard: “The eurocrats should take a running jump into the ornamental pond of the Square Marie-Louise [in Brussels].” He added: “A tax on higher-value properties in London would have a detrimental effect on Londoners who are cash-poor but live in appreciating assets. They should butt out.”

The commission rushed out a clarification on Tuesday, saying that its paper did not represent a diktat, before insisting nonetheless that “there is a limit to how much fiscal consolidation can be achieved through spending cuts alone”. The commission warned in its 2014 economic policy proposals for the UK, published on Monday, that more must be done to stop a housing bubble. It said the government should consider changes to Help to Buy to help cool the housing market, along with reforms to the council tax system because it imposes relatively higher taxes on low-value homes. Asked about the intervention, Grayling said: “We’ve got a strategy we think is working in the UK as the fastest-growing economy in western Europe. I don’t think the chancellor needs help from other people to get our economy right. Europe has still got a number of deep-rooted problems … which should be a priority for those people.”

Read more …

Nothing at all is being done about the youth jobless problem.

• Europe Remains A Jobless Swamp, Despite The Spanish ‘Miracle’ (AEP)

Congratulations to Spain. King Phillip VI will take over a country that created 198,000 jobs in April, the best single month since the glory days of the property boom in 2005. There is a very long way to go. The jobless rate is still 25.1%, rising to 53.5% for youth. Yet if this jobs miracle continues for a few more months it will be one of the great turnaround stories of modern times. (I am assuming that the data is true, a necessary caveat given the stream of articles recently in Le Confidencial accusing the government of cooking figures). Unfortunately, the apparent recovery in jobs in the rest of southern Europe and Holland is largely a mirage, while in Finland it is getting steadily worse. Pan-EMU unemployment fell to 11.7% in April but that is largely because workers are still dropping out of the workforce or fleeing as EMU refugees to reflationary economies.

Italy lost 68,000 jobs in April, according to the country’s data agency ISTAT. The total employed fell to 22,295,000. Italian unemployment rose to 13.6%. For youth it has climbed to a modern-era high of 43.3%, implying very serious damage to Italy’s long-term economic dynamism due to labour hysteresis. The employment rate dropped to 55.2%. Ageing workers are giving up the search for jobs – chiefly in the Mezzogiorno – and returning to their patches of land in impoverished early retirement. Yet all this was recorded as stabilisation in the Italian part of the Eurostat’s release today. You might conclude that the country was starting to claw its way out the crisis. In fact it remains trapped in a hopeless situation inside EMU, with an exchange rate overvalued by 20% to 30% against Germany. France saw a rise in its key jobless gauge by 14,800 in April. INSEE says the number who want to work but are not included in the jobless figures has jumped to 1.3m. This is known as the “unemployment halo”

Read more …

Take Weber with a pinch of – political – salt.

• Prepare For The Tremors As Europe And America Drift Apart (Axel Weber/FT)

When the governing council of the European Central Bank meets in Frankfurt on Thursday, it is widely expected to announce a loosening in policy, most likely a cut in both the refinancing and deposit rates. Two weeks later, the US Federal Reserve will probably respond to strengthening economic data by moving in the opposite direction, tapering the pace of quantitative easing for the fifth consecutive meeting. This is another sign of how monetary policy is diverging in the two largest economies, a trend that is set to shape funding markets for years to come. In the US, output is set to rebound in the second quarter after having been disrupted by dismal weather in the first. And while price rises have been subdued so far, employment surveys suggest an emerging skills shortage and thus the potential for wage cost growth that could help lift inflation close to the Fed’s 2% target.

By any measure the labour market is tighter in America than in Europe, where the recovery remains weak and uneven despite buoyant financial markets. The gap between actual and potential output will barely shrink in the eurozone this year, and unemployment will remain close to a record high. Before long, these divergent fortunes are bound to lead to large differences in policy. In the US, interest rates could begin to rise in 2015. In Europe, they are likely to stay low for much longer. One might expect that movements in financial markets would reflect these expectations. [..] To my mind, investors should prepare for more volatility this year. The degree of easing of US monetary policy has been exceptional. The tightening, when it begins, will also be unprecedented. The tightening has not yet begun – the Fed’s balance sheet is still expanding. I see significant potential for volatility and setbacks on financial markets over the next few quarters.

In particular, the story is not over for emerging-market countries that rely on cheap dollar funding. The recovery of their stock markets and currencies in the past months does not reflect improved economic fundamentals, but a better mood among investors. These countries are still vulnerable. When US interest rates begin to rise, these borrowers may be able to turn to euro-denominated debt as an alternative source of cheap financing. However, this at best delays adjustment; improving fundamentals remains urgent. The Fed’s balance sheet, which was about half the size of the Eurosystem’s going into the crisis, has now overtaken its European counterpart as a proportion of output. Emerging markets will not be the only ones to suffer when this trend goes into reverse. A tightening in US monetary policy always causes fallout. This time will be no different. In fact, it may be worse, since the tightening starts from extremely expansionary territory.

Read more …

Bad.

• Japan Base Wages Decline 23 Months In A Row (Zero Hedge)

Proving once again that you can’t print your way to general economic prosperity, Abenomics took another shot to the chest last night as Japan’s base wages failed to rise month-over-month for the 24th month in a row (the longest streak in history). Even after all the promises and hope of the spring wage negotiations, Abe’s ‘plan’ to guilt employers into raising wages is not working; which is especialy problematic given the surge in inflation (as the ‘real’ wage slumped 3.1% in April) As Goldman warns, we caution against excessive expectations for sustained wage growth.

Via Goldman Sachs: “Basic wages still falling even after spring wage negotiations; total wages lifted by special wages/overtime: April total cash wages rose 0.9% yoy, accelerating from March (+0.7%). Special wages increased 20.5% yoy (March: +10.3%), pushing up the total by 0.6 pp. Overtime pay has underpinned wages as a whole recently but is beginning to peak out, although it still rose 5.1% in April (March: +5.8%) and contributed +0.4pp to overall wage growth. Meanwhile, basic wages (80% of the total) remained on a yoy downtrend (April: -0.2%; March: -0.3%). While wage hikes resulting from the spring negotiations (shunto) will be largely reflected in basic wages, the April figure indicates no major change in basic wages since the start of the new fiscal year. Next month’s May data should shed more light, as many companies will include the shunto wage hike portion in salaries from May.”

Read more …

Oz has become China’s bitch.

• Is Trouble In Store For The Australian Economy? (CNBC)

Australia’s economy appears to be slowing and some economists argue that a more subdued outlook could lead to further monetary easing from the country’s central bank. Australia is due to report first quarter economic growth on Wednesday. While economists polled by Reuters expect robust growth of 3.2% on-year, up from 2.8% in the previous quarter, and 0.9% on-quarter, a marginal increase on 0.8% last quarter, analysts say the economy will take a turn for the worse in the second quarter. “I think the second quarter is where we’ll see a huge disturbance as there’s been a huge change or shift back in [Australia] that will certainly affect that number,” said Evan Lucas, market strategist at IG. “All of a sudden come April things weren’t as rosy coming out of China, people were talking about the budget which was perceived as being quite tough – and as taking 0.3% of GDP out of the economy according to most economists. All of that stuff is going to filter through,” he said.

Lucas expects second quarter growth to slow to 0.4% on-quarter from 0.7-0.8% in the first quarter and sees this pull back prompting the Reserve Bank of Australia (RBA) to take a more dovish stance. “The effects of the budget, the slowdown they’ve finally seen in housing prices, the real under-performance in commodity prices and the consequential effect on the mining space may finally see their neutral status going back to slightly dovish,” he added. Other economists shared this view. Analysts at Goldman Sachs also expect a more dovish tone from the RBA ahead of Tuesday’s policy meeting due to a number of factors. “Commodity prices have fallen sharply, global growth faltered somewhat in early 2014, inflation printed relatively benignly and business and consumer surveys moved lower. In response the RBA incrementally has sounded more dovish,” Goldman analysts said in a note.

Read more …

Nice twist.

• Singapore Joins China With Dangerous Debt Level (Bloomberg)

Singapore companies’ indebtedness has swelled to the most in Asia after China and India as the city-state’s economic growth slows, according to GMT Research Ltd. Leverage among the Southeast Asian nation’s corporates is following counterparts in the two larger economies to a level considered a “danger threshold,” Gillem Tulloch, founder of the Hong Kong-based researcher, said in an interview yesterday. Debt rose to six times the amount of operating cash flow in 2013 for non-financial Singaporean companies, from 5.1 times in 2012, a report by GMT Research shows.

“It’s a bit surprising that Singaporean companies seem to have leveraged up significantly over the past few years,” said Tulloch, 43, a former analyst at CLSA Asia-Pacific Markets. “There’s been a slight loss of discipline, or it could be that the growth has not come in as expected.” Singapore’s government said last month its export-led economy will experience “modest” expansion in 2014 amid a labor-market crunch. It’s likely that growth is headed for a slowdown, since it can’t be sustained without more stimulus or reckless bank lending, GMT Research said. The leverage ratio in China rose to 7.5 times from 6.8 times last year, while the measure in India grew to 8.1 times from 7 times, the May 28 report showed.

Read more …

HA! Where is ”the world” going to get that kind of dough? Borrow from each other?

• World Needs to Invest $50 Trillion to Meet Its Energy Needs: IEA (IB Times)

Tens of trillions of dollars in global energy investments will have to be made over the next two decades in order to ensure that the world has enough energy supplies, according to the International Energy Agency, an intergovernmental organization based in Paris. In a special report released Monday, the agency said that nearly $50 trillion of cumulative investment is needed through 2035. More than half of that amount will be spent on extracting, transporting and refining fossil fuels like oil and natural gas. Another $8 trillion is needed to invest in energy efficiency. Upgrades in the electricity sector, including replacing aging power plants and installing new infrastructure, could require $16.4 trillion in investments. Europe alone needs to spend $2 trillion over the years to develop its power industry and fix its broken energy markets, or else risk major blackouts in the coming years, CNN noted.

The IEA stressed the need for oil-producing countries like Saudi Arabia to ramp up investment in new sources of fuel supplies. Although the surge in North American oil and gas production from shale rock has reduced the leverage of Middle East producers in recent years, the shale boom will likely “run out of steam in the 2020s.” If total supplies don’t recover, world oil markets will be tighter and more volatile and oil prices could rise by $15 a barrel in 2025, the report said, according to Platts in London. “Many of our hopes and our worries about the future of the global energy system boil down to questions about investment,” Maria van der Hoeven, the IEA’s executive director, said at the report’s launch.

“Will policies and market conditions create enough investment opportunities in the regions and sectors where they are needed? … And will policymakers succeed in steering investments toward a cleaner, more secure energy system—or are we locking in technologies and patterns of consumption that store up trouble in the future?” Global energy investments totaled more than $1.6 trillion in 2013, a figure that has more than doubled in real terms since 2000, Platts said. According to the IEA, the investment needed every year to supply the world’s energy needs rises steadily towards $2 trillion over the period to 2035.

Read more …

The EU is doomed because of this feature. Why would anyone want to be part of it if it only takes away self determination, and charges a price for that too?

• The Democracy Deficit: Europeans Vote, Merkel Decides (Spiegel)

Before the European Parliament election last month, voters were told the poll would also determine the next Commission president. In a silent putsch against the electorate, German Chancellor Angela Merkel is now impeding the process. She fears a loss of power and Britain’s EU exit. Merkel had hardly begun her speech last Friday before she got right to the point. With her hands set on the podium in front of her in the Regensburg University auditorium, she said: “I am engaging in all discussions in the spirit that Jean-Claude Juncker should become president of the European Commission.” German news agency DPA immediately sent out a headline reading: “Merkel: Juncker To Be EU Commission President.” And yet, if that is what she really wanted, it’s a goal she could have achieved as early as last Tuesday. Instead, she opted against it. One can, of course, choose to believe the words Merkel delivered last Friday in Regensburg. Or one can focus more on her actions.

Thus far, her actions have spoken a different language. It is the language of one for whom the voters are secondary. The European Union election at the end of May has led to an unprecedented power struggle between the European Parliament and the European Council, made up of the 28 EU heads of state and government. It is a vote that could change the EU more than any past European election. The next several weeks will determine just how democratic the EU wants to be, whether the balance of power in Brussels will have to be readjusted and whether Merkel is really the leader of Europe. With European Social Democrats set to play a key role in the EU struggle, the immediate future could also determine the stability of Merkel’s own governing coalition in Berlin, which pairs her conservatives with the SPD. Should the European Parliament get its way in naming the next European Commission president, it would mark a significant shift of power away from EU leaders, and they likely wouldn’t get it back. It is a development that would make the European Union more democratic and more like a nation-state. But that is exactly what Britain wants to avoid, and any such development could drive the country out of the EU.

Read more …

Must read.

• The Minsky Moment Meme (Ben Hunt)

Today you can’t go 10 minutes without tripping over an investment manager using the phrase “Minsky Moment” as shorthand for some Emperor’s New Clothes event, where all of a sudden we come to our senses and realize that the Emperor is naked, central bankers don’t rule the world, and financial assets have been artificially inflated by monetary policy largesse. Please. That’s not how it works. That’s not how any of this works. Just to be clear, I am a huge fan of Minsky. I believe in his financial instability hypothesis. I cut my teeth in graduate school on authors like Charles Kindleberger, who incorporated Minsky’s work and communicated it far better than Minsky ever did. Today I read everything that Paul McCulley and John Mauldin and Jeremy Grantham write, because (among other qualities) they similarly incorporate and communicate Minsky’s ideas in really smart ways.

But I’m also a huge fan of calling things by their proper names, and “Minsky Moment” is being bandied about so willy-nilly these days as a name for so many different things that it greatly diminishes the very real value of Minsky’s insights. So here’s the Classics Comic Book version of Minsky’s financial instability hypothesis. Speculative private debt bubbles develop as part and parcel of a business/credit cycle. This is driven by innate human greed (or as McCulley puts it, humans are naturally “pro-cyclical”), and tends to be exacerbated by deregulation or laissez-faire government policy. Ultimately the debt burdens created during these periods of market euphoria cannot by met by the cash flows of the stuff that the borrowers bought with their debt, which causes the banks and shadow banks to withdraw credit in a spasm of sudden fear.

Because there’s no more credit to be had for more buying and everyone is levered to the hilt anyway, stuff either has to be sold at fire-sale prices or debts must be defaulted, either of which just makes the banks withdraw credit even more fiercely. The Minsky Moment is this spasm of private credit contraction and the forced sale of even non-speculative assets into the abyss of a falling market. Here’s the kicker. Minsky believed that central banks were the solution to financial instability, not the cause. Minsky was very much in favor of an aggressively accommodationist Fed, a buyer of last resort that would step in to flood the markets with credit and liquidity when private banks wigged out. In Minsky’s theory, you don’t get financial instability from the Fed massively expanding its balance sheet, you get financial stability. Now can this monetary policy backstop create the conditions for the next binge in speculative private debt? Absolutely. In fact, it’s almost guaranteed to set up the next bubble.

Read more …