Apr 192015
 
 April 19, 2015  Posted by at 8:38 am Finance Tagged with: , , , , , , , , , , ,  3 Responses »


DPC Peanut stand, New York 1900


At Global Economic Gathering, US Primacy Is Seen as Ebbing (NY Times)
IMF Credibility Faces Tipping Point Over Greece (USA Today)
‘Bernanke To Go Down As One Of The Most Vilified People Of The Century’ (CNBC)
Markets Face New Threat As US Fed Ponders Interest Rate Rise (Guardian)
Most Americans Think College Is Out of Reach (Bloomberg)
Record Drop In House Prices Suggests China Is Already In A Recession (Zero Hedge)
Germany FinMin Schaeuble Worried About China’s Debt And Shadow Banking (BIA)
Europe Ready For Grexit Contagion As Athens Gets Closer To Russian Cash (AEP)
ECB’s Draghi Says Urgent That Greece Strikes Deal With Creditors (Bloomberg)
Draghi Warns Of Uncharted Waters If Greece Crisis Deteriorates (FT)
Greece Wants EU/IMF Deal But Impasse Could Bring Referendum (Reuters)
Moscow Denies Planning Multibillion Credit To Greece (RT)
Finns Set to Topple Government as Vote Focuses on Economic Pain (Bloomberg)
How Sleepy Finland Could Tear The Euro Apart (Telegraph)
Australia, The Latest Country With Negative Interest Rates (Simon Black)
California’s New Drought Rules Would Require Cuts of Up to 36% (Bloomberg)
Pope Francis Urges EU To Do More To Help Italy With Flood Of Migrants (CT)
Australia Government In Secret Bid To Hand Back Asylum Seekers To Vietnam (SMH)
Air-Pocalypse: Breathing Poison In The World’s Most Polluted City (BBC)

But wait, didn’t Obama say the US has to set the rules for the entire world?

At Global Economic Gathering, US Primacy Is Seen as Ebbing (NY Times)

As world leaders converge [in Washington] for their semiannual trek to the capital of what is still the world’s most powerful economy, concern is rising in many quarters that the United States is retreating from global economic leadership just when it is needed most. The spring meetings of the IMF and World Bank have filled Washington with motorcades and traffic jams and loaded the schedules of President Obama and Treasury Secretary Jacob J. Lew. But they have also highlighted what some in Washington and around the world see as a United States government so bitterly divided that it is on the verge of ceding the global economic stage it built at the end of World War II and has largely directed ever since. “It’s almost handing over legitimacy to the rising powers,” Arvind Subramanian, chief economic adviser to the government of India, said of the United States.

“People can’t be too public about these things, but I would argue this is the single most important issue of these spring meetings.” Other officials attending the meetings this week, speaking on the condition of anonymity, agreed that the role of the United States around the world was at the top of their concerns. Washington’s retreat is not so much by intent, Mr. Subramanian said, but a result of dysfunction and a lack of resources to project economic power the way it once did. Because of tight budgets and competing financial demands, the United States is less able to maintain its economic power, and because of political infighting, it has been unable to formally share it either.

Experts say that is giving rise to a more chaotic global shift, especially toward China, which even Obama administration officials worry is extending its economic influence in Asia and elsewhere without following the higher standards for environmental protection, worker rights and business transparency that have become the norms among Western institutions. President Obama, while trying to hold the stage, clearly recognizes the challenge. Pitching his efforts to secure a major trade accord with 11 other Pacific nations, he told reporters on Friday: “The fastest-growing markets, the most populous markets, are going to be in Asia, and if we do not help to shape the rules so that our businesses and our workers can compete in those markets, then China will set up the rules that advantage Chinese workers and Chinese businesses.”

In an interview on Friday, Mr. Lew, while conceding the growing unease, hotly contested the notion of any diminution of the American position. “There is always a lot of noise in Washington; I’m not going to pretend this is an exception,” he said. “But the United States’ voice is heard quite clearly in gatherings like this.”

Read more …

All managing directors are eventually arrested.

IMF Credibility Faces Tipping Point Over Greece (USA Today)

It was perhaps inevitable that the Greek crisis would hijack the spring meeting of International Monetary Fund this week, but the damage to the international lending agency could grow much worse as the situation in Europe becomes increasingly acute. The standoff between a new Greek government seeking debt relief after five years of grinding recession and authorities at the IMF and European Union, who were unbending in their demands to follow through on further austerity measures to get more bailout money, dominated discussions at the meeting that brings economic policymakers from around the world.

The Greek imbroglio overshadowed other messages from IMF officials this week regarding new sources of financial instability in the world, the need to stimulate economies to more vigorous growth and even discussion about other financial and geopolitical hot spots, such as Ukraine. But the unwillingness of IMF Managing Director Christine Lagarde and her staff to countenance any relief for Greece stands to make the agency an accessory to the potential turmoil that could spread well beyond Greece as the chances for a reasonable, agreed solution to the crisis grow slim. A debacle in Greece would further tarnish the reputation of an agency that has already seen its credibility and influence diminished.

It was perhaps a fitting sideshow to the drama in Washington that a former IMF managing director, Rodrigo Rato, was briefly detained Thursday in Spain as part of a money-laundering investigation and may be charged in the case, even as he is being investigated for other infractions. Rato led the IMF from 2004 to 2007, and was succeeded by Dominique Strauss-Kahn, a political heavyweight who aspired to the presidency of France but who had to leave the IMF post under a cloud of scandal in 2011 over charges of sexual assault against a New York hotel maid. Lagarde, then French finance minister, was parachuted in to take his place, though she herself is involved in a long-running judicial probe over an arbitration process she approved that awarded half a billion dollars to a businessman with ties to her center-right political party.

The legal travails of a succession of IMF leaders have diminished its ability to take the moral high ground in forcing lenders to implement the difficult policy measures that are the conditions for its loans. But that is not the only problem. The neoliberal economic principles enshrined in the IMF economic prescription — which generally call for a reduction in government spending and higher taxes even in the midst of recession — are part of a so-called “Washington consensus” that is finding very little consensus in other parts of the world.

Former IMF economist Peter Doyle, a 20-year veteran who left the agency in anger in 2012 saying he was “ashamed” he had ever worked there, this week urged his fellow economists “to turn on the IMF in public.” Citing several leading economists by name, Doyle noted they had expressed support of the Greek position sotto voce. He called upon these economists to “shout, together, right now,” to be on the record against the IMF stance before the “Euro-tinder box” explodes.

Read more …

Along with Monti, Draghi, Kuroda and Yellen.

‘Bernanke To Go Down As One Of The Most Vilified People Of The Century’ (CNBC)

Former Federal Reserve Chair Ben Bernanke is heading down a well-beaten path: shuffling through the revolving door between Washington’s policy circles and Wall Street’s big money institutions. In a move announced on Thursday, he’s going from his former position at the Federal Reserve to Wall Street as a senior adviser at Citadel. The latter is what has “Fast Money” trader Guy Adami—and a number of other Street watchers—outraged. The $25 billion hedge fund, Citadel, in a statement said, “Dr. Bernanke will consult with Citadel teams on developments in monetary policy, financial markets and the global economy.” Adding a note from its founder and CEO Ken Griffin, “He has extraordinary knowledge of the global economy and his insights on monetary policy and the capital markets will be extremely valuable to our team and to our investors.”

Adami, however, said this week on Thursday’s Fast Money of Bernanke’s new role: “It’s wrong. It’s wrong on so many levels.” Bernanke “was a hero for a month, [and now] he’s going to go down as one of the most vilified people of the 21st century. Mark my words,” the trader added. In an interview with Andrew Ross Sorkin, co-anchor of CNBC’s “Squawk Box” and a columnist for the New York Times, Bernanke said he understood the concerns about going from Washington to Wall Street. He said he decided in Citadel because the hedge fund “is not regulated by the Federal Reserve and I won’t be doing lobbying of any sort.” He also said banks had approached him about jobs but he declined because “wanted to avoid the appearance of a conflict of interest” by working for an institution the Fed does regulate.

Bernanke is not the first and likely won’t be the last federal worker to jump to Wall Street. In 2008 after handing over the reins to Ben Bernanke, Alan Greenspan joined hedge fund Paulson & Co. as an adviser. And just last month, Ex-Fed Governor Jeremy Stein joined hedge fund Blue Mountain Capital Management. “He shouldn’t have been allowed to leave the Fed, number one,” Adami stated. “He should have saw [quantitative easing] through, in my opinion, and for him to go to a place that can take advantage of the information that he has privy to, it’s just wrong.” Indeed, Wall Street observers were broadly critical of Bernanke’s move into the world of big money hedge funds. The Washington Post said this week that the former Fed chief “deserves a seven figure sinecure” based on hisHerculean efforts to save the world economy from another Great Depression.

Read more …

There are no markets left, only casinos.

Markets Face New Threat As US Fed Ponders Interest Rate Rise (Guardian)

The moment US central bank chief Janet Yellen presses the button will be a massive economic event. The prospect that higher interest rates in the world’s largest economy could come this year has already sent the dollar surging against the pound and euro. It has also fuelled fears of a meltdown in countries that have borrowed heavily in the US currency. Borrowing is inherently risky, all the more so when the interest rate can change at short notice. Higher costs for those that have borrowed in dollars could cripple companies in Brazil and Turkey that were enticed by cheap credit to fund a new factory or office building, or just to pay the wages. At the IMF’s spring meeting last week, chief economist Olivier Blanchard dismissed these concerns, arguing that companies may have hedged their position, while investors and finance ministers were well prepared.

But a succession of market shocks in the last two years has convinced many in the financial community that a bigger crash is coming. There have been violent movements in currencies, bonds and commodity prices, especially crude oil and metals. A rise in US interest rates could add to this already volatile situation and drag stock markets towards another sudden crash. The IMF discussed the context in which another financial crash could occur in its latest financial stability report. It highlighted how any shock can send investors fleeing; with only sellers in the market, the price keeps plunging until someone believes it has gone far enough and starts buying. The nervous state of markets these days means there is generally either a surplus of buyers or a surplus of sellers; only rarely have we seen periods of calm with roughly equal numbers.

Last January, for instance, the Swiss franc soared an unprecedented 30% after the central bank conceded that tracking the ailing euro was no longer possible. The previous year, markets had been rocked by the first hint from the US that it would end the era of ultra-cheap credit. It happened after former Fed boss Ben Bernanke let slip that he might stop pumping funds into the US economy through quantitative easing. The “taper tantrum” – referring to the premature “tapering” of QE – sent shock waves through world markets and forced a clarification from the Fed to steady the ship. The IMF’s financial stability report discussed the potential for Taper Tantrum II. The scenario was worse, yet the warning was described by Larry Fink, boss of BlackRock, the world’s biggest private investment fund, as too optimistic.

He is concerned about the European insurance industry, which must pay returns on pensions and other products at a time when the European Central Bank has been driving interest rates in much short-term government debt below zero; in other words, rather than earning interest on government bonds, insurers are paying to park their money in such assets. How could they survive for long under this regime, he asked. The IMF posed the same question, but again expected everything to work out for the best, somehow.

Read more …

Young people can’t afford a home, can’t afford an education. What a sad country it has become. And there‘s much worse to come yet.

Most Americans Think College Is Out of Reach (Bloomberg)

Most Americans believe people who want to go to college can get in somewhere—they just don’t think they’d be able to afford it, according to a new Gallup-Lumina Foundation poll. While 61% of adults believe education beyond high school is available to anyone who needs it, only 21% agree that it’s affordable, according to the poll results, released on Thursday. Some racial groups were much more optimistic than others. 51% of Hispanic adults said higher education is still affordable, Gallup found. Just 19% of black adults and 17% of white adults agreed. The results, based on a survey of 1,533 adults who were contacted from November through December 2014, show there’s a sizable gap between the share of Americans who believe people can merely access college and those who believe people can still afford it.

“If a bachelor’s degree is one important way for today’s young adults to achieve the American dream, affordability in particular could jeopardize that dream,” the report said. Tuition at public colleges has risen more than 250% over the last 30 years, the two organizations noted. At the same time, financial aid hasn’t kept up. Students have been leaving school with record amounts of debt: In a separate study, Gallup and Purdue University found more than a third of students who graduated college from 2000 to 2014 were saddled with more than $25,000 in loans. Even if Americans believe anyone, in theory, could find their way to a college classroom, they’re not optimistic anyone could pay to stay there.

Read more …

And still many keep claiming China will be just fine.

Record Drop In House Prices Suggests China Is Already In A Recession (Zero Hedge)

Another month, and another confirmation that China’s hard landing is if not here, then likely mere months away. Overnight, the NBS reported that in March, Chinese house prices dropped in 69 of 70 cities compared to a year ago. According to Goldman’s seasonal adjustments, in March home prices dropped another 0.5% from February, the same as the prior month’s decline, suggesting that the February 28 rate cut hasn’t done much to boost housing spirits. However, it is the annual data that truly stands out, because with a drop of 6.1% this was the biggest drop in Chinese house prices in history.
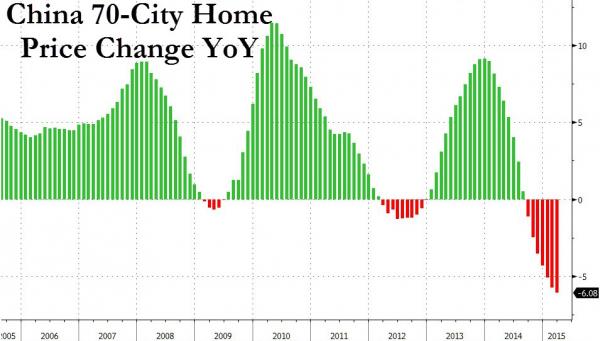
To be sure, the PBOC is now scrambling to halt what, unless it is stopped, will become a full-blown hard landing in months, if it isn’t already. As a result, as shown in the chart below it has recently engaged in several easing steps, with many more to come according to the sell-side consensus. So far these have failed to stimulate the overall economy, which continues to be pressured by a deflation-importing world, but have certainly lead to a massive surge in the Chinese stock market. Incidentally, the ongoing collapse in Chinese home prices is precisely why the PBOC and the Politburo have both done everything in their power to substitute the burst housing bubble with another: that of stocks, by pushing everyone to invest as much as possible in the stock market, leading to the biggest and fastest liquidity and margin debt-driven bubble in history.

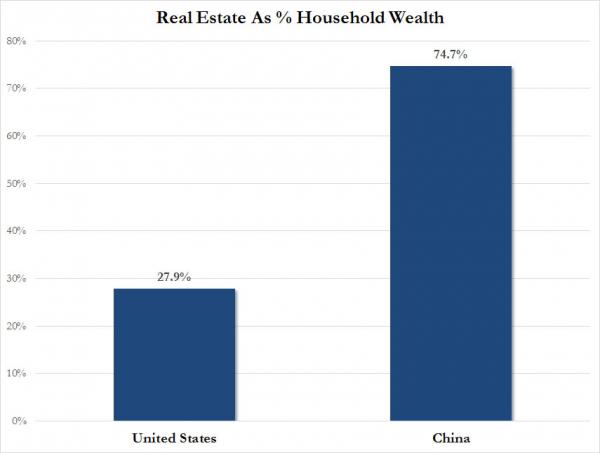
Unfortunately for China, as we have shown before, all Chinese attempts to do what every self-respecting Keynesian would do, i.e., replace one bubble with another, are doomed to fail for the simple reason that unlike in the US, where the bulk of assets are in financial form, in China 75% of all household wealth is in real estate. [..]
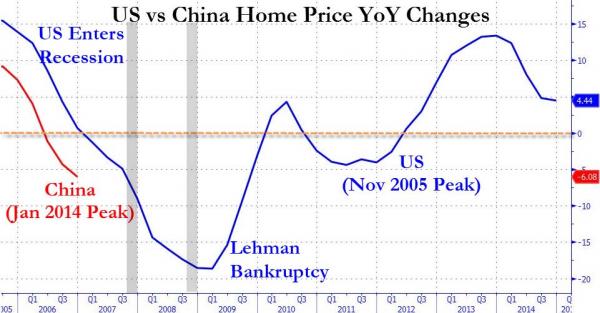
And this is where things get scarier, because if one compares the history of the Chinese and US housing bubbles, one observes that it was when US housing had dropped by about 6% following their all time highs in November 2005, that the US entered a recession. This is precisely where China is now: a 6.1% drop following the all time high peak in January of 2014. If the last US recession is any indication, the Chinese economy is now contracting! So much for hopes of 7% GDP growth this year. The good news, if any, is that Chinese home prices have another 12% to drop before China, which may or may not be in a recession, suffer the US equivalent of the Lehman bankruptcy.
Read more …

All you need to know: “..debt has nearly quadrupled since 2007”.

Germany FinMin Schaeuble Worried About China’s Debt And Shadow Banking (BIA)

Should we concerned about growing debt levels around the world? Wolfgang Schaeuble, Germany’s finance minister, certainly seems to thinks so, stating overnight that debt levels in the global economy continue to give cause for concern. Singling out China in particular, Schaeuble noted that debt has nearly quadrupled since 2007, adding that its growth appears to be built on debt, driven by a real estate boom and shadow banks. Certainly, according to McKinsey’s research, total outstanding debt in China increased from $US7.4 trillion in 2007 to $US28.2 trillion in 2014. That figure, expressed as a percentage of GDP, equates to 282% of total output, higher than the likes of other G20 nations such as the US, Canada, Germany, South Korea and Australia. With China slowing and expectations for further monetary and fiscal easing growing by the day, the concerns raised by Schaeuble may well amplify from here.

Read more …

“There will not be the slightest privatisation in the country, particularly of strategic sectors of the economy.”

Europe Ready For Grexit Contagion As Athens Gets Closer To Russian Cash (AEP)

The ECB has warned that a rupture of monetary union and Greek exit from the euro could have dramatic consequences, but insisted that it has enough powerful weapons to avert contagion. Mario Draghi, the ECB’s president, said it would be far better for everybody if Greece recovers within EMU but made it clear that the currency bloc is no longer vulnerable to the immediate chain-reaction seen in earlier phases of the debt crisis. This sends an implicit message to the radical-Left Syriza government that it cannot hope to secure better terms from EMU creditors by threatening to unleash mayhem. “We have enough instruments at this point of time, the OMT (bond-buying plan), QE, and so on, which though designed for other purposes could certainly be used in a crisis if needed,” said Mr Draghi, speaking after a series of tense meetings at the IMF.

“We are better equipped than we were in 2012, 2011.” In effect, the ECB now has the license to act as a full lender-of-last-resort and mop up the bond markets of Portugal, Spain, or Italy, preventing yields from rising. Yet Syriza appears to be countering such pressure with its own foreign policy gambits as events move with electrifying speed in Athens. Greek sources have told The Telegraph that Syriza may sign a deal with Russia for Gazprom’s “Turkish Stream” pipeline project as soon as next week, unlocking as much as €3bn to €5bn in advance funding. This confirms a report in Germany’s Spiegel magazine, initially denied by both the Russian and Greek governments. It is understood that the deal is being managed by Panagiotis Lafazanis, Greece’s energy minister and head of Syriza’s militant Left Platform, a figure with long-standing ties to Moscow.

Mr Lafazanis warned defiantly on Saturday that Syriza would not “betray the people’s mandate” even if this means a full-blown clash with the creditor powers. “There can’t be a deal with neo-liberal, neo-colonial powers that rule the EU and the IMF unless Greece really threatens their deep economic and geo-strategic interests. We still do not know our own strength,” he told Greek television. Mr Tsipras visited the Kremlin last month insisting he would pursue an independent foreign policy “Several of the so-called partners and certainly some in the IMF want to denigrate and humiliate our government, blackmailing us to implement measures against the working classes,” added Mr Lafazanis. “There will not be the slightest privatisation in the country, particularly of strategic sectors of the economy.”

Read more …

Draghi’s way out of his league.

ECB’s Draghi Says Urgent That Greece Strikes Deal With Creditors (Bloomberg)

European Central Bank President Mario Draghi said it is urgent that Greece strikes a deal with creditors, although its banks continue to meet the requirements for Emergency Liquidity Assistance. “ELA will continue to be given to the banks if they’re judged to be solvent and if they have adequate collateral which is the case now,” Draghi told reporters on Saturday at the International Monetary Fund’s meetings in Washington. The Frankfurt-based ECB decides on Greece’s financial lifeline on a weekly basis. The funding has so far helped defer a financial meltdown as euro-area governments hold back bailout money, complaining that Prime Minister Alexis Tsipras must do more to revamp his country’s economy.

Draghi said “much more work is needed now and it’s urgent” if Greece and its creditors are to strike a deal to release aid. He said any package of policies should produce “growth, fairness, fiscal sustainability and financial stability.” “We all want Greece to succeed,” he said. “The answer is in the hands of the Greek government.” While Europe is better equipped to deal with any fallout in financial markets if Greek negotiations fail than it was when it first fell into crisis, Draghi said the region is still in “uncharted waters.” Draghi said the euro zone economy is strengthening after the ECB began a €1.1 trillion bond-buying program last month. Still, he warned an extended period of low interest rates could prove “fertile ground” for instability in financial markets. “We should be alert to these risks,” Draghi said, adding the risk was not currently a reason to tighten monetary policy.

Read more …

And here he admits he doesn’t have a clue.

Draghi Warns Of Uncharted Waters If Greece Crisis Deteriorates (FT)

Mario Draghi said the euro area was better equipped than it had been in the past to deal with a new Greek crisis but warned of uncharted waters if the situation were to deteriorate badly. The ECB president called for the resumption of detailed discussions aimed at resolving the country’s debt woes and urged the Greek authorities to bring forward proposals that ensured fairness, growth, fiscal stability, financial stability. Asked about the risks of contagion from a new flare-up in Greece, he said: we have enough instruments at this point in time … which although they have been designed for other purposes would certainly be used at a crisis time if needed. The two tools he referred to were the ECB’s so-called outright monetary transactions, which have never been used, and Quantitative Easing, which the ECB launched in January.

He added: we are better equipped than we were in 2012, 2011 and 2010. However Mr Draghi added: Having said that, we are certainly entering into uncharted waters if the crisis were to precipitate, and it is very premature to make any speculation about it. The ECB president was speaking following meetings in Washington that have been overshadowed by renewed fears about the risk of a Greek debt default and possible exit from the euro. US Treasury secretary Jack Lew warned on Friday that a full-blown crisis in Greece would cast a new shadow of uncertainty over the European and global economies, as he put pressure on Athens to come forward urgently with detailed reforms to its economy. Mr Lew said that while financial exposures to Greece had changed significantly since the turmoil of 2012, it was impossible to know how markets would respond to a default.

Read more …

“In the back of our minds these are possibilities of finding a way out, if there is a dead end.”

Greece Wants EU/IMF Deal But Impasse Could Bring Referendum (Reuters)

Greece aims for a deal with its creditors over a reforms package but will not retreat from its red lines, the country’s deputy prime minister told the Sunday newspaper To Vima, not ruling out a referendum or early polls if talks reach an impasse. Athens is stuck in negotiations with its euro zone partners and the International Monetary Fund over economic reforms required by the lenders to unlock remaining bailout aid. Ongoing talks are not expected to produce a deal for the approval of euro zone finance ministers at their next meeting in Riga on April 24 as progress is painfully slow. “Our objective is a viable solution inside the euro,” Yanis Dragasakis told the paper. “We will not back off from the red lines we have set.”

Asked whether the government had thought of calling a referendum or even going to the polls if talks become deadlocked, Dragasakis said this could be a possibility, although the government’s goal was to reach an agreement. “In the back of our minds these are possibilities of finding a way out, if there is a dead end. The aim is (to reach) an agreement.” Greece is quickly running out of cash and in the next few weeks may face a choice of either paying salaries and pensions or paying back loans from the International Monetary Fund. Shut out of bond markets, Athens could get more loans from both the IMF and euro zone governments, but it would first have to implement reforms, agreed with the creditors, to make its finances sustainable and its economy more competitive. The leftist-led government does not want to implement measures including cuts in pensions as it won elections in late January on pledges to end austerity.

Read more …

A credit is not the same as an advance payment.

Moscow Denies Planning Multibillion Credit To Greece (RT)

Russia denied media reports that it is going to give Greece a loan of up to $5 billion as advance payment for future transit profits from a future gas pipeline. The sum was mooted by the German magazine Spiegel. Greece is expected to shortly join a joint Russian-Turkish pipeline project that will pump Russian gas to Europe via Turkey. The magazine cited a senior source in the Greek government as saying that the country would get from $3 billion to $5 billion in credit as part of the deal. It was reportedly agreed during Greek Prime Minister Alexis Tsipras’ visit to Moscow last week. But on Saturday, the Russian president’s spokesman Dmitry Peskov said no such loan is planned.

“[Russian President Vladimir] Putin said himself during the media conference that nobody asked for our help. Naturally energy cooperation was discussed. Naturally, the parties of the high level talks agreed to work out all details of these issues at an expert level. Russia didn’t offer financial help because it was not asked,” the spokesman told the Russian radio station Business FM. Earlier Greek and Russian officials said an energy deal that would have Greece join the Turkish stream project would be inked in a matter of days, but no exact date or particular terms were given. If Russia did loan money to Greece, it would help it deal with a looming national default. The new Greek government is in difficult negotiations with Germany and the IMF to secure further loans to help its economy.

Read more …

Anti-euro gets a foot in the door.

Finns Set to Topple Government as Vote Focuses on Economic Pain (Bloomberg)

Finns look set to vote out a government marred by political infighting and elect a party led by a self-made millionaire promising a business-driven recovery. After three years of economic decline, Finland’s next government will need to fix chronic budget deficits, a debt load that’s set to breach European Union limits, rising unemployment and economic growth that’s about half the average of the euro zone. Juha Sipila, who leads the opposition Center Party, has promised business-friendly policies he says will create 200,000 private-sector jobs. His party is polling about 6% ahead of the next-biggest groups, according to newspaper Helsingin Sanomat. If he wins Sunday’s vote, Sipila will probably try to form a majority coalition that’s likely to include the euro-skeptic The Finns party.

“Putting together a new, workable government that can turn around Finland’s public finances is the most important economic policy step,” Anssi Rantala, chief economist at Aktia Bank Oyj, said by phone. “The government has to take seriously the gigantic deficits we have in state and municipal budgets, and it has to change the way it implements austerity: most has been through tax increases.” Austerity isn’t what splits Finland’s political parties. All major groups have pledged some combination of belt-tightening and growth policies. The Finance Ministry estimates €6 billion euros of austerity measures are needed by 2019 to prevent debt reaching 70% of gross domestic product. It also says there’s no scope to raise taxes without stifling economic growth.

Read more …

Lovely prospect.

How Sleepy Finland Could Tear The Euro Apart (Telegraph)

Finland is the unlikely stage for the latest turn in Greece’s interminable eurozone drama this weekend. With events having decamped temporarily to Washington DC, Athens will be keeping half an eye on developments in Helsinki, where the Nordic state of just 5.4m people heads for the polls on Sunday. In the five years since Greece’s financial woes were revealed to the world, it has been sleepy Finland which has emerged as the most trenchant critic of EU largesse to the indebted Mediterranean. The outcome of the country’s general election could now determine Greece’s future in the monetary union. In a leaked memo seen last month, it was revealed that the Finns had already drawn up contingency plans for a Greek exit from the euro.

Although ostensibly a sensible measure for any finance ministry to contemplate, the document confirmed the Finns’ position as the most uncompromising of the EU’s creditor nations. The reputation is well-deserved. At the height of Greece’s bail-out drama in 2011, Helsinki negotiated an unprecedented bilateral agreement with Athens, receiving €1bn in collateral in return for supporting a rescue deal. A year later, the Finns were prime candidates to become the first dissenters to voluntarily break the sanctity of the monetary union. “We have to be prepared,” the country’s then foreign minister told the Telegraph three years ago. Greece’s current impasse is also partly a result of Finnish obstinacy.

Helsinki was one of the main obstacles to securing a long-term extension to Greece’s bail-out programme under the previous Athens government late last year. The eventual compromise of a three-month, rather than six-month reprieve, has seen the new Leftist regime scramble desperately for cash since February. With the situation in Athens deteriorating by the day, both Finland’s prime minsiter and central bank governor have eschewed high-minded rhetoric about European unity, to insist creditors should be ready to pull the plug on Greece. But unlike its fellow creditor giant Germany, Finland is more economic laggard than European powerhouse. Having been mired in a three-year recession, the country heads to the polls with economic output still 5pc below its pre-crisis levels.

Finland has suffered an economic downturn of almost Greek proportions. The boon from falling oil prices and launch of eurozone QE will still only see the economy expand at a paltry 0.8pc this year, worse only to Italy and Cyprus. Stagnating growth saw Finland stripped of its much coveted Triple-A sovereign debt rating last year. The IMF now recommends a cocktail of structural reforms and fiscal consolidation that would make officials in Athens bristle. “There is no sympathy for Greece any more, especially because our own economy is struggling,” says Jan von Gerich, strategist at Nordea bank in Helsinki.

Read more …

“Everyone believed that it would all work out OK. Then one day it didn’t.”

Australia, The Latest Country With Negative Interest Rates (Simon Black)

Let’s talk about idiots. Somewhere out there, some absurdly well-paid banker just placed his investors’ capital in yet another financial instrument which is guaranteed to lose money: Australian government debt. 47 investors participated in the Australian government’s $200 million bond tender; the participants typically bid the amount they’re willing to pay, and the highest bids win the auction. In this case, and for the first time in Australia, every single one of the 47 bidders offered a price so high that it implies a negative interest rate. Even the lowest bid in the auction, for example, implied a net loss… or an effective yield of NEGATIVE 0.015%. The highest price implied a yield of negative 0.085%. What’s really bizarre is that this particular issue was for ‘inflation-linked’ bonds.

Which means that if the government’s official monkey math shows that inflation is falling, the yield could actually become even MORE NEGATIVE. Insane? Of course. But here’s the thing. These bankers aren’t investing their own money. It’s not like some guy is taking his million dollar bonus and saying, “Hey I think I’ll go buy some government debt that guarantees I’ll lose money.” No. He buys a Maserati. Then he picks up this garbage debt with his customers’ money. Not only is this idiotic, it’s borderline criminal. At a minimum it’s seriously unethical. Banks and other money managers have a solemn obligation… a fiduciary responsibility that comes with the sacred charge of safeguarding other people’s money. Just like the golden rule, this obligation is very simple: take care for other people’s money even more than you care for their own.

But that went out the window a long time ago. Back in the 1500s, Renaissance-era merchant bankers risked their own capital alongside their customers, doing meaningful deals that financed exploration and the expansion of world trade. Now it’s all about commissions, obtuse regulations, and following the latest banking fad. This is officially now the latest banking fad—buying government bonds at negative yields. You’ll remember a few years ago when the latest banking fad was handing out no-money-down mortgages to dead people and unemployed bus drivers… or buying “AAA-rated” bonds which pooled these subprime loans together. That didn’t exactly work out so well. Neither will this. In fact there are plenty of similarities between today’s negative interest rates and the early 2000s housing bubble.

Back then, banks were essentially paying people to borrow money. They offered the least creditworthy borrowers absurd amounts of money which sometimes even exceeded the purchase price of the home they were buying. 102% loans were not uncommon back then, which financed the entire purchase along with the extra closing costs. We even saw 105% loans which allowed a little bit extra to make home improvements. It doesn’t take a rocket scientist to figure out that it’s criminally stupid to pay someone to borrow money. Yet that’s exactly what’s happening now. Instead of people, though, it’s governments who are effectively being paid to borrow. We all remember last time how much this impacted the global financial system. Everyone believed that it would all work out OK. Then one day it didn’t. Lehman Brothers went bust, and the entire banking system started to collapse.

Read more …

High time to pack up and go.

California’s New Drought Rules Would Require Cuts of Up to 36% (Bloomberg)

California issued proposed rules calling for mandatory reductions in water use by municipal agencies as a historic drought drags into a fourth year. The state’s 411 urban water suppliers would have to cut use by as much as 36%, with those that conserved less facing tougher restrictions and a daily penalty of as much as $500 for not complying, the California State Water Resources Control Board said in the proposed rules released Saturday. The board will meet May 5 and 6 to finalize the rules, which would take effect by June 1. “Some of these communities have achieved remarkable results with residential water use now hovering around the statewide target for indoor water use, while others are using many times more,” the Sacramento-based agency said in its proposal.

The emergency rules would be in effect for 270 days. The regulations are based on an executive order Governor Jerry Brown, a 77-year-old Democrat, issued April 1 calling for a mandatory 25% reduction in water use compared with 2013 levels and requiring 50 million square feet of lawns to be replaced by drought-tolerant landscaping. California, the most-populous U.S. state, and its $43 billion agriculture industry are experiencing the worst of the arid conditions moving across the western U.S., with 67% of the state in an extreme drought, according to the U.S. Drought Monitor.

The agency this week released nearly 300 comment letters from the public, businesses, water agencies and cities on an initial proposal. The planned 35% reduction in water use for Beverly Hills would “place a significant burden on our small permanent customer base” of 42,157 residents, Mahdi Aluzri, interim city manager, said in the letter. Beverly Hills’ daytime population, including commuters who work in the city, shoppers and visitors, can rise to more than 250,000 water users, Aluzri said. California’s residents in February reduced water use by 2.8% below 2013 levels, the worst monthly performance since June, the water board said.

Read more …

For this alone, the EU should be dismantled. “A new policy will be presented in May”. May? You should be out there on the water! Another boat with 650 people just capsized as I’m writing this.

Pope Francis Urges EU To Do More To Help Italy With Flood Of Migrants (CT)

Pope Francis on Saturday joined Italy in pressing the European Union to do more to help the country cope with rapidly mounting numbers of desperate people rescued in the Mediterranean during journeys on smugglers’ boats to flee war, persecution or poverty. While hundreds of migrants took their first steps on land in Sicilian ports, dozens more were rescued at sea. Sicilian towns were running out of places to shelter the arrivals, including more than 10,000 this week. The Coast Guard said 74 migrants were saved from a sailboat shortly before it sank Saturday about 100 miles east of the coast of Calabria in southern Italy. A Coast Guard plane and a Dutch aircraft, part of an EU patrol mission, spotted the boat. Passengers included 10 children and three pregnant women.

With his wide popularity and deep concern for social issues, the pope’s moral authority gives Italy a boost in its lobbying for Brussels and northern EU countries to do more. Since the start of 2014, nearly 200,000 people have been rescued at sea by Italy. “I express my gratitude for the commitment that Italy is making to welcome the many migrants who, risking their life, ask to be taken in,” said Francis, flanked by Italian President Sergio Mattarella. “It’s evident that the proportions of the phenomenon require much broader involvement.” “We must never tire of appealing for a more extensive commitment on the European and international level,” Francis said.

Italy says it will continue rescuing migrants but demands that the European Union increase assistance to shelter and rescue them. Since most of the migrants want to reach family or other members of their community in northern Europe, Italian governments have pushed for those countries to do more, particularly by taking in the migrants while their requests for asylum or refugee status are examined. “For some time, Italy has called on the EU for decisive intervention to stop this continuous loss of human life in the Mediterranean, the cradle of our civilization,” Mattarella said. The EU’s commissioner for migration, Dmitris Avramopoulos, says a new policy will be presented in May. Meanwhile, he has also called for member states to help.

Read more …

But it can get worse, believe it or not. The Abbott government quite literally has no shame. They send people back to countries they’re fleeing.

Australia Government In Secret Bid To Hand Back Asylum Seekers To Vietnam (SMH)

Vietnamese Australians and human rights activists have blasted the Abbott Government over a secret Navy-led mission to return a group of asylum seekers back to the Communist government of Vietnam. In a new milestone for the Coalition’s hard-line border policy, an Australian Navy ship was entering Vietnamese waters on Friday after what is believed to be a week-long journey to prevent boats reaching Australia. HMAS Choules was close to the the southern port city of Vung Tau, south of Ho Chi Minh City, Defence sources confirmed to Fairfax Media. The vessel was expected to hand over detainees to the Communist government some time after arriving late Friday or in the early hours of Saturday.

The vessel is carrying asylum seekers intercepted by customs and navy vessels earlier this month, north of Australia, the West Australian newspaper reported on Friday. Immigration Minister Peter Dutton’s office said no comment would be made on “operational matters” but human rights activists lashed the Coalition for another on-water action cloaked in secrecy. Daniel Webb, director of the Human Rights Law Centre, said: “Australia should never return a refugee to persecution. All governments – whatever their policy position – should respect democracy and should respect the rule of law. Continually operating behind a veil of secrecy is a deliberate subversion of both. “If the government truly believed its actions were humane, justified and legal, it wouldn’t go to such extraordinary lengths to hide them from view.” [..]

The Vietnamese community, many of whom arrived in Australia by boat after the fall of Saigon in 1975 as the Communist regime of Hanoi took control of the country, expressed horror at asylum seekers being handed back. Thang Ha, president of the Vietnamese Community in Australia, NSW Chapter, said the government should be aware it could be “throwing people back into hell”. He said returnees would likely be left alone initially but would be followed by party operatives and eventually harassed and likely jailed. “Human rights activists, democracy activists, Christians, Buddhists, artists and singers, they have all been harassed. Some people have been hunted down, their family members have been harassed. Some have been thrown in jail and never heard from again,” he said. “They are throwing them back into hell.”

Read more …

Yes, we are a smart animal.

Air-Pocalypse: Breathing Poison In The World’s Most Polluted City (BBC)

Saharan dust, traffic fumes and smog from Europe may be clogging up London’s air at present – and causing alarm in the newspapers – but in the world’s most polluted city London’s air would be considered unusually refreshing. That city is Delhi, the Indian capital, where air quality reports now make essential reading for anxious residents. In London last week, the most dangerous particles – PM 2.5 – hit a high of 57; that’s nearly six times recommended limits. Here in Delhi, we can only dream of such clean air. Our reading for these minute, carcinogenic particles, which penetrate the lungs, entering straight into the blood stream – is a staggering 215 – 21 times recommended limits. And that’s better than it’s been all winter. Until a few weeks ago, PM 2.5 levels rarely dipped below 300, which some here have described as an “air-pocalypse”.

Like the rest of the world, those of us in Delhi believed for years that Beijing was the world’s most polluted city. But last May, the World Health Organization announced that our own air is nearly twice as toxic. The result, we’re told, is permanent lung damage, and 1.3 million deaths annually. That makes air pollution, after heart disease, India’s second biggest killer. And yet, it’s only in the past two months as India’s newspapers and television stations have begun to report the situation in detail that we’ve been gripped, like many others, with a sense of acute panic. It’s a little bit like being told you’re living next to an active volcano that might erupt at any moment. At first, we simply shut all our doors and windows and sealed up numerous gaps. No more seductively cool Delhi breezes could be allowed in.

We began checking the air quality index obsessively. Then, we rushed out to buy pollution masks, riding around in our car looking like highway robbers. But our three-year-old wouldn’t allow one anywhere near her face. Our son only wore his for a day, and only because I told him he looked like Spider-Man. Despite our alarm, many Delhi-ites reacted with disdain. “It’s just dust from the desert,” some insisted. “Nothing a little homeopathy can’t solve,” others said. But we weren’t convinced. When we heard that certain potted plants improve indoor air quality, we rushed to the nursery to snap up areca palms, and a rather ugly, spiky plant with the unappealing moniker, mother-in-law’s tongue. But on arrival, the bemused proprietor informed us that the American embassy had already purchased every last one. In any case, we calculated that to make a difference, we needed a minimum of 50 plants. “We could get rid of the sofa to make room for them,” my husband offered.
Read more …

Apr 162015


NPC Sidney Lust Leader Theater, Washington, DC 1920

Greece In ‘Slow-Death Scenario’ Amid Defaults Fears (CNBC)
IMF Knocks Greek Debt Rescheduling Hopes (FT)
The Endgame For Greece Has Arrived (Zero Hedge)
Why The Grexit Is Inevitable – How About May 9th? (Raas Consulting)
UBS Says Europe Risks Bank Runs On Grexit (Zero Hedge)
Fed’s Bullard Says Rate Hikes Are Needed For Coming ‘Boom’ (MarketWatch)
Warren Says Auto Lending Reminds Her Of Pre-Crisis Housing Days (MarketWatch)
27% Of US Students Are Over A Month Behind On Their Loan Payments (Zero Hedge)
China’s True Economic Growth Rate: 1.6% (Zero Hedge)
The South (China) Sea Bubble (Corrigan)
Don’t Invest In ‘Unsustainable’ China: Professor (CNBC)
The Major Paradox at the Heart of the Chinese Economy (Bloomberg)
China Seen Expanding Mortgage Bonds to Revive Housing (Bloomberg)
Bonds Beware As Money Catches Fire In The US And Europe (AEP)
ECB’s Mario Draghi Says Stimulus Is Working (WSJ)
Schaeuble Says Greece Must Ditch False Hopes, Commit to Reform (Bloomberg)
Schaeuble Criticizes Greece for Backsliding as Time Runs Out (Bloomberg)
Australia’s Economy: Is The Lucky Country Running Out Of Luck? (Guardian)
US Military Lands in Ukraine (Ron Paul Inst.)
Greece In Talks With Russia To Buy Missiles For S-300 Systems (Reuters)
Putin to Netanyahu: Iran S-300 Air Defense System is .. Defensive (Juan Cole)
Vatican Announces Major Summit On Climate Change (ThinkProgress)

“It would be a slow-death scenario and in a way we are in this scenario. Something needs to change in order to avoid an accident..”

Greece In ‘Slow-Death Scenario’ Amid Defaults Fears (CNBC)

Greece faces a “slow-death scenario”—including a default and messy exit from the euro zone—one analyst warned Thursday, as the country’s economic crisis took another turn for the worse following a credit rating downgrade. BofA’s Thanos Vamvakidis warned Thursday that if Greece fails to reach a deal with its European partners, a Grexit—or Greek exit from the euro zone becomes inevitable. His comments come after Greece’s unresolved negotiations with its international creditors prompted ratings agency Standard & Poor’s to cut its credit rating to “CCC+” from “B-” with a negative outlook.

“Without an agreement (with creditors over reforms), without official funding, there is a very high probability that Greece will default sometime in May and this could lead to a very negative scenario,” Vamvakidis told CNBC Thursday. He said that although nobody wants that, “the more they delay the higher the risks.” “(A Grexit) is not going to be overnight. It would be a slow-death scenario and in a way we are in this scenario. Something needs to change in order to avoid an accident,” he added. Reform discussions between Greece and the bodies overseeing its bailout program—the EC, ECB and IMF—have been unsuccessful over recent weeks. The country’s creditors agreed to extend its bailout program by four months in February in order to give Greece’s new leftwing government more time to enact reforms.

Lack of progress on reforms means Greece’s last tranche of aid—needed in order to make loan repayments to the IMF and ECB in the coming weeks and months—has not been released. [..] Despite growing fears of a euro zone exit, some euro zone officials have refused to countenance such a scenario, which could bring with it significant upheaval and potentially disastrous consequences for the euro zone. Not only could a default and Grexit prompt capital controls to prevent bank runs, international financial isolation and the introduction of a new currency in Greece, it could threaten the future of the 19-country single currency bloc.

Knowing that any such talk could spark international panic over Greece and the intergrity of the euro zone and its currency, the European Central Bank’s President Mario Draghi dismissed fears of a Greek default Wednesday, saying he was not ready to even “contemplate” such a scenario. Officials in the U.S. have openly warned over the risks posed by Greece, however. Greek Finance Minister, Yanis Varoufakis, is due to meet U.S. President Barack Obama on Thursday, and U.S. Treasury Secretary Jacob Lew on Friday (along with the ECB’s Draghi and IMF officials).

Read more …

Time for some US pressure?

IMF Knocks Greek Debt Rescheduling Hopes (FT)

Greek officials have made an informal approach to the IMF to delay repayments of loans to the international lender, highlighting the parlous state of Greek finances, but were told that no rescheduling was possible. According to officials briefed on the talks by both sides, Athens was persuaded not to make a specific request for a delay to the Fund, which is owed almost a €1bn in two separate payments due in May. Although Athens was rebuffed, the discussions, which occurred in private earlier this month, are a sign that the Greek government is finding it increasingly difficult to scrape together enough money to continue to pay wages and pensions while meeting its debt payments to external lenders.

Officials representing Greece’s creditors are unsure whether Athens will be able to make the payments in May. Even if they do, they are certain that the matter will come to a head by June, before much larger payments on bonds held by the ECB start coming due.
IMF officials have repeatedly said that a rescheduling of repayments can only come as part of a completely renegotiated new bailout programme. Were it to miss a payment, Greece would become the first developed economy to go into arrears at the Fund, something only counties like Zaire and Zimbabwe have done in the past.

Greece informally raised the precedent of delaying IMF payments by at least one other developing country a generation ago in the 1980s. But IMF officials stuck to their guns saying that none of the underlying problems had been solved by payment delays. One source briefed on the approach said the proposal was to “reshuffle the repayment schedule for the IMF loan over the coming months,” allowing the new Greek government led by Alexis Tsipras to have the money to pay bills for pensions and public sector salaries while negotiating with European creditors over payment of the next tranche of bailout loans.

Read more …

“..the Greek Finance Minister “will on Friday meet with infamous sovereign debt lawyer Lee Buchheit, who has helped numerous countries restructure their debt.”

The Endgame For Greece Has Arrived (Zero Hedge)

To think it was just recently in September of last year when the S&P, seemingly unaware of the tragic reality facing Greece in just a few months (by reality we meen democratic elections which overthrew the previous regime which was merely a group of Troika picked technocrats), upgraded Greece to B and said “The upgrade reflects our view that risks to fiscal consolidation in Greece have abated.” Well, the risks have unabated, and two months after S&P flip-flopped and downgraded Greece back to B- on February 6, moments ago it downgraded it again, this time to triple hooks, aka the dreaded CCC+. S&P said that without deep economic reform or further relief, S&P expects Greece’s debt, other financial commitments to be unsustainable. S&P views that Greece increasingly depends on favorable business, financial, and economic conditions to meet its financial commitments.

The rater adds that “conditions have worsened due to the uncertainty stemming from the prolonged negotiations between the Greek govt and its official creditors” and that economic prospects could deteriorate further unless talks between Greece and its creditors conclude soon.” In short: Greece is about to default and/or exit the Eurozone so this time at least S&P is prepared. Ironically this comes a day before Varoufakis is set to meet with Obama. It will be followed by meetings with European Central Bank head Mario Draghi on Friday, Secretary of the Treasury Jack Lew, Italy’s finance minister Pier Carlo Padoan and IMF officials. But, as City AM reports, the biggest news is that the Greek Finance Minister “will on Friday meet with infamous sovereign debt lawyer Lee Buchheit, who has helped numerous countries restructure their debt. Buchheit is a partner at top US law firm Cleary Gottlieb.”

It comes just a week before a vital meeting of Eurozone finance ministers on 24 April which could be the last chance Greece has of gaining extra funds before hefty repayments are due to its creditors in May.

As a reminder, “Lee Buchheit, a leading sovereign-debt attorney and the man who managed the eventual Greek debt restructuring in 2012, was harshly critical of the authorities’ failure to face up to reality. As he put it, “I find it hard to imagine they will now man up to the proposition that they delayed – at appalling cost to Greece, its creditors, and its official-sector sponsors – an essential debt restructuring.” The endgame for Greece has arrived.

Read more …

One kind of logic.

Why The Grexit Is Inevitable – How About May 9th? (Raas Consulting)

One thing in common for almost all of my Pinewood International Schools (TiHi to some) class of ’78 is that we left. Many still live in Greece and in Thessaloniki or have returned, and they are closest to the pain. The real pain of the past decade, that has destroyed wealth and hope. Unemployment is running at levels not see in Europe since after the war, and at levels that encouraged the socialist – fascist civil wars of the 1930s. Those did not end well.

But that does not explain why the Grexit is inevitable, and why it will happen very soon.
1) This is what the Greek people voted for. No, they did not vote to stay in the Euro, they voted for the party that said it would reduce the debt and meet pension obligations. The Greek people and voters are not stupid. They knew this could only happen by either the rest of Europe bailing out Greece again, or by leaving the Euro.
2) The Greek people know perfectly well that Europe is not going to bail them out, because to do so will only set everyone up for the next bailout.
3) The Greek people, and the rest of Europe, know full well that the debt will never be repaid, and that the Troika are now acting as nothing better than the enforcers of loan sharks.
4) Syriza knows that it had six months before the voters would throw them out, and once out, Syriza would never come back.
5) The Greeks needed to show “good faith” in actually attempting to negotiate a resolution with the Troika. This has now been done, and is failing.
6) The demand for reparations from Germany is designed not to actually extract the reparations, but to anger the Germans to the point that they will block any compromise that Syriza would have been required to accept.

The Greek government, elected by a battered and exploited Greek people, has been establishing the conditions that will give them the moral high ground (in the eyes of their voters) needed to actually leave the Euro. Having set the conditions, when will it happen? I’m still guessing May 9th. Why? Greece will leave the Euro, and they will do it sooner than later. They’ve made the April payment, but simply do not have the money for the May or June payments, and they cannot pass the legislation required by Europe and the Germans and stay in power. That gives us a late May or June date. So why earlier?

Capital flight. Imposing currency controls will be a fundamental element of any Grexit. Accounts will be frozen, and any money in accounts will be re-denominated in New Drachmas. Once the bank accounts are unfrozen, the residual, former Euros will now be worth whatever the New Drachma has dropped to, and the drop will be significant, over–correcting to the downside. Once it is accepted that the Grexit is coming and there will be no last minute deal, and with memories of Cyprus too fresh in every Greek’s mind, the money will flow out of the country. Not just corporate money (most of which is probably off-share already) but any remaining personal money in bank accounts. So Greece has to move before the coming Grexit is perceived as inevitable, and the money starts to flow out.

Weekend event. When the Grexit happens, it will be on a weekend. The banks will be closed, parliament will be called into emergency session, and a packet of laws will be passed. As this needs to be on a Saturday to avoid wholesale capital flight the moment that parliament is called into session, were it a weekday. This leaves only a few possible dates. And where there are few possible dates, I’m punting on the earlier date, so earlier in May. And looking at the calendar, that leaves us with May 2nd, 9th or 16th. My own guess is that the 2nd is too soon, and the 16th is too late. That leaves me guessing May 9th.

Read more …

It is pretty silly that anyone would doubt this. Or believe reassurances to the contrary.

UBS Says Europe Risks Bank Runs On Grexit (Zero Hedge)

UBS: When examining the risk of contagion from any possible Greek exit from the Euro we come back again and again to the fact that in every monetary union collapse of the last century, the trigger for breakup was not the bond markets, current account positions, or political will, but banks. If ordinary bank depositors lose faith in the integrity of a monetary union they will hasten its demise by shifting their money out of their banks – either into physical cash, or into banks domiciled in areas of the monetary union that are perceived as “stronger”. Both of these traits were evident in the US monetary union breakup, and have been in evidence in more recent events this century.

The contagion risk after a possible Greek exit arises if bank depositors elsewhere in the Euro area believe that a physical euro note held “under the mattress” at home today is worth more than a euro in a bank – because a euro in a bank might be forcibly converted into a national currency tomorrow. In a breakup scenario it is more likely that retail bank deposits withdrawn will end up as physical cash, owing to the difficulties of opening and using a bank account in a different country. This is not a question of banking system solvency. Highly solvent banks will be subject to deposit flight if it is the value of the currency in that country that is uncertain…

The contagion story is serious. Even if a depositor thinks that there is only a 1% chance their country will exit the Euro, why take a 1% chance that your life savings are forcibly converted into a perceived worthless currency if by acting quickly (and withdrawing deposits) one can have 100% certainty that your life savings remain in Euros? If Greece were to walk away from the Euro, then the policy makers of the Euro area would have to convince bank depositors across the Euro area that a Euro in their local banking system was worth the same as a Euro in another country’s banking system, and that the possibility of any other country exiting the Euro was nil. If that double guarantee was not utterly credible, then the risk of other countries joining Greece in exiting the Euro would be high.

This suggests that financial markets are treating the risks around Greek exit with too little regard for the probable dangers.

Read more …

Like before the recovery gets out of hand.

Fed’s Bullard Says Rate Hikes Are Needed For Coming ‘Boom’ (MarketWatch)

A leading hawk on the Federal Reserve on Wednesday made a case for raising interest rates soon, arguing the level needs to be appropriate for the coming “boom” for the U.S. economy. St. Louis Fed President James Bullard, speaking at the annual Hyman Minsky conference here, acknowledged a boom by current standards might not be the same as the growth in the late 1990s. He pointed out that even if gross domestic product expanded just 1.5% in the first quarter, the four-quarter growth rate would be about 3.3%.With the current potential growth around 2%, growth in the low 3% range “represents growth well above trend,” he said. The first reading on first-quarter GDP is due April 29. Unlike his colleagues, Bullard expects the unemployment rate to fall below 5% from a current level of 5.5%. Bullard said jobless rates in the 4% range are consistent with a boom.

In his remarks, he notably did not specify a month to lift interest rates, and asked by reporters afterwards, he said, “I’m being deliberately vague.” The June meeting is considered the first in which the Federal Open Market Committee will give serious consideration to lifting interest rates. His biggest fear from keeping low rates — they have been near zero for 6.5 years — is that they could lead to financial-stability problems later. He said asset valuations currently look fairly valued, with the notable exception of bonds which Fed policy influences. “So it’s hard to know what that really means.” But he pointed out that Fed policy typically impacts the economy with a lag. “Boom times ahead, plus us already charting out low interest rates, sounds like risky from a bubble perspective,” he said.

Read more …

She’s not the only one. But perhaps she should have said this a year ago.

Warren Says Auto Lending Reminds Her Of Pre-Crisis Housing Days (MarketWatch)

Senator Elizabeth Warren on Wednesday used a major address on financial regulation to chide automobile lending practices as she continued her criticism of the country’s largest banks. Warren was speaking on the topic of the unfinished business of financial reform, and looking at the financial sector five years after the passage of the Dodd-Frank reform law. Warren, the leading contender to block a Hillary Clinton presidential nomination on the Democratic side if she were to step into the race, took particular aim at the fast-growing automobile lending category. “Right now, the auto loan market looks increasingly like the pre-crisis housing market, with good actors and bad actors mixed together,” the Massachusetts Democrat said.

“The market is now thick with loose underwriting standards, predatory and discriminatory lending practices, and increasing repossessions.” Warren pointed out that car dealers got a specific exemption from the Consumer Financial Protection Bureau, the agency which Warren all but singlehandedly brought to life. “It is no coincidence that auto loans are now the most troubled consumer financial product. Congress should give the CFPB the authority it needs to supervise car loans – and keep that $26 billion a year in the pockets of consumers where it belongs,” she said, referring to an estimate of dealer markups.

The CFPB has taken some steps in the area of automobile loans and has proposed a rule that would bring larger auto lenders that are not already banks under its jurisdiction. Warren was on more familiar ground with her call to break up the nation’s banks. She pointed out that last summer the Federal Reserve and the Federal Deposit Insurance Corp. said 11 banks were risky enough to bring down the U.S. economy if they were to fail. She also blasted the Justice Department, the Federal Reserve and the Securities and Exchange Commission for timidity in going after major banks. “The DOJ and SEC sit by while the same giant financial institutions keep breaking the law — and, time after time, the government just says, ‘Please don’t do it again.’ ”

Read more …

How much further must this go before something is done?

27% Of US Students Are Over A Month Behind On Their Loan Payments (Zero Hedge)

As we’ve documented exhaustively in the past, the country is laboring under around $1.3 trillion in non-dischargeable loans to students which isn’t a good thing, especially in a country where the jobs driving the economic “recovery” have, until last month, been created in the food service industry and where wage growth is a concept reserved for only 20% of the workforce. It would seem that this could make it increasingly difficult for students to repay their debt, especially considering how quickly tuition costs have risen. In other words, tuition is going up, wages aren’t, and the latter point there is only relevant in the event you find a job that pays you a wage in the first place (i.e. where your compensation isn’t determined by the generosity of the “supervisory” Americans who can still afford to eat out).

The severity of the problem has been partially masked at times by the tendency to inflate the denominator when one goes to calculate delinquency rates. That is, if you include all student debt outstanding, even that in deferment or forbearance in the denominator, then clearly the delinquency rate will be biased to the downside because the numerator will by necessity only include those students who are currently in repayment. That’s really convenient if you want to make things look less bleak than they actually are.

Of course you can’t be delinquent when you aren’t yet required to make payments, so the more accurate way to calculate the figure would be to include only those students in repayment in the denominator. This apples-to-apples comparison is likely to paint much more accurate picture and sure enough, a new St. Louis Fed (who recently documented the shrinking American Middle Class) study finds that the delinquency rate for students in repayment is 27.3%, well above the 17% figure for all student borrowers. Here’s more:

[..] if we adjust the delinquency rate to consider that only a fraction of the borrowers have payments due, this level of delinquency is very concerning: A delinquency rate of 15% for all student loan borrowers implies a delinquency rate of 27.3% for borrowers with loans in repayment. This level of delinquency is much higher than for any other type of debt (credit cards, auto loans, mortgages, and so on).

Read more …

That feels more like it. Over 70% of capital invested in housing, which fell 6%…

China’s True Economic Growth Rate: 1.6% (Zero Hedge)

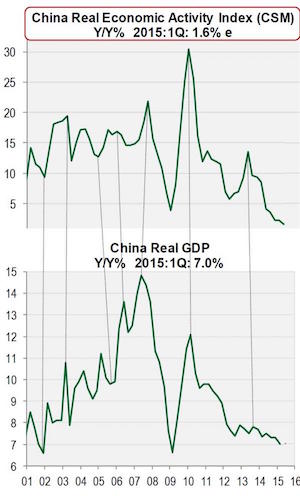
Cornerstone Macro reports, “Our China Real Economic Activity Index Slowed To Just 1.6% YY In 1Q.” The indicator in question looks at many of the components shown above, such as retail sales, car sales, rail freight, industrial production, and several others, to determine an accurate indicator of the true state of China’s economy. It finds that not only is China’s economic growth rate not rising at a 7.0% Y/Y rate, but is in fact the lowest it has been in modern history! And a 1.6% growth rate by what was formerly the world’s most rapidly growing (and largest according to the IMF) economy explains perfectly what happened with the US economy over the past 6 months. Hint: it has nothing to do with the winter, and everything to do with China hard landing into a brick wall.

Read more …

“China is currently enjoying the somewhat dubious fruits of one of the all-time great stock manias.”

The South (China) Sea Bubble (Corrigan)

The first hard data release of the month for China was hardly guaranteed to reassure. Two-way trade in USD terms dropped 6.3% in the first quarter from its level of a year ago, the second most severe setback since the Crash and only the third such instance in the whole era of ‘Opening Up’. From a strictly local perspective, the bad news was mitigated by the fact that exports managed to eke out a modest YOY gain of 4.7% (though that still means they were effectively unchanged from 2013 levels) and so the trade surplus was left at a record seasonal high. For the rest of us, however, anxious as we are to sell more of our wares to China, there was no such comfort. Imports plunged by more than a sixth to a four-year low, registering a drop which, if nowhere near as large in percentage terms, was, when measured in numbers of dollars, equal to that suffered in the global freeze which ensued in the aftermath of the Lehman collapse.

Though it always does to await the full data release for the first quarter – given the inordinate impact on comparisons of that highly moveable feast, the Lunar New Year – these numbers are fully consonant with the evidence presented during the first two months which showed flat non-residential electricity use and rail freight volumes down to seven year seasonal lows. It is undoubtedly the case that the bulk of the pain being felt is concentrated where it should be – up in the dirty, surplus capacity-plagued end of heavy industry and extraction – but, nevertheless, Chinese data show that 12-month running profits have dwindled to zero (if we strip out companies’ non-core – qua speculative – activities) and that for the last three months for which we have numbers they had actually declined in a manner not seen since the world stood still in late 2008/early 2009.

Revenue growth was also sickly, while balance sheets continue to swell with debt and receivables. Granted, private joint-stock companies continue to outperform their state-owned peers – or so the NBS would have us believe – but, even here, core profit growth over the whole of 2014 was a mere 4.2% with turnover up 9.2% (suggesting that margins simultaneously contracted). In such an environment, you might think that investor spirits would be dampened but, as anyone who has opened a paper in recent days will be aware, that is very much far from being the case.

Indeed, China is currently enjoying the somewhat dubious fruits of one of the all-time great stock manias. The CSI300 composite of Shanghai and Shenzhen equities has double since last July, with the seven-eighths of those gains coming in the last six months and almost a third of them in the past six weeks. With first Y1 trillion then Y1.5 trillion trading days being recorded and with 1.6 million [sic] new trading accounts being opened in the latest week for which we have the numbers, it is easy to see that this has rapidly degenerated into an indiscriminate free-for-all.

Read more …

“..a Keynesian-on-steroids stimulus that occurs at the municipal level by building all sorts of public infrastructure that requires stealing land from farmers..”

Don’t Invest In ‘Unsustainable’ China: Professor (CNBC)

China bear Peter Navarro is telling investors not to put their money in the country because its economic model is unsustainable. “What you got is a mercantilist export-driven model for China coupled with a Keynesian-on-steroids stimulus that occurs at the municipal level by building all sorts of public infrastructure that requires stealing land from farmers,” the University of California, Irvine economics professor told CNBC’s “Power Lunch” on Wednesday. Navarro, who co-wrote “Death By China,” attributes China’s slowing growth to less demand coming from the U.S. and Europe for Chinese exports.

“The problem is simply that Europe and the U.S., which provided the 10% growth year after year for three decades, are now too weak to sustain that,” he said. In addition, China is facing rising wages, labor issues, water shortages and a stock market and real estate bubble, Navarro said. On Wednesday, China’s statistics bureau announced that GDP grew an annual 7% in the first quarter, slowing from 7.3% in the previous quarter. That was the country’s slowest pace of growth in six years, suggesting the world’s second-largest economy was still losing momentum.

Read more …

“..every investment-led growth miracle in the last 100 years has broken down.”

The Major Paradox at the Heart of the Chinese Economy (Bloomberg)

“The latest GDP report underscores offsets coming from China’s services-led transformation — a key underpinning of consumer demand,” said Stephen Roach… “I suspect the economy is close to bottoming and could well begin to pick up over the balance of this year.” Chinese officialdom has little choice but to tap on the brakes of the old-line economy. Years of politically driven investment with diminishing returns led to too much debt and industrial overcapacity, as well as ghost towns with unfinished hotels and unoccupied residential towers. Bad debt piled up at a faster pace at China’s big state banks in the fourth quarter. Meanwhile, the country’s total debt — government, corporate and household — rose to about $28 trillion by mid-2014, according to an estimate by McKinsey, or about 282% of GDP.

Xi and Premier Li Keqiang are trying to defuse that debt bomb, rein in banks and local governments and promote the nation’s stock markets as a primary way for innovative and smaller companies to raise capital. Both leaders say they’ve mapped out more than 300 reforms that over time will reduce state intervention in the economy. Among the initiatives is scaling back energy-price controls that favor manufacturers. The changes are also designed to improve the social safety net and encourage market-driven deposit rates to get Chinese families saving less and spending more.

Few countries with the scale of China’s credit boom have escaped unscathed without experiencing some sort of banking crisis. Research by Michael Pettis, a finance professor at Peking University, shows that “every investment-led growth miracle in the last 100 years has broken down.” Avoiding that fate requires a high-wire balancing act for the government. It needs to wind down the torrent of investment – 49% of China’s GDP from 2010 to 2014 – without cratering the economy and worsening the situation for indebted local governments or the bad-debt burden of Chinese banks.

Read more …

Anything goes by now?!

China Seen Expanding Mortgage Bonds to Revive Housing (Bloomberg)

China is poised to expand mortgage bonds to lift its slumping real estate market that accounts for a third of the economy. Officials will likely allow banks to sell commercial mortgage-backed notes for the first time by the end of the year after reviving securities tied to home loans in 2014, according to China Merchants Securities Co. and China Chengxin International Credit Rating Co. The offerings, which help banks boost mortgage lending by freeing space on balance sheets, will grow “substantially” this year, China Credit Rating Co. said. The government of Premier Li Keqiang eased home-purchase rules after new housing prices slid in many cities across China in February.

Authorities, who halted securitization in 2009 after subprime mortgage bonds triggered the global financial crisis, are returning to such offerings to spur an economy growing at the slowest pace since 1990. “The launch of commercial mortgage-backed securities may send a strong policy signal because it will give banks more space to lend money directly to property developers,” said Zuo Fei, a Shenzhen-based director of structured finance at China Merchants Securities, underwriter of the first RMBS deal this year. “The regulators are trying to improve property purchases in a gradual and an appropriate way.”

The People’s Bank of China on March 30 cut the required down payment for some second homes to 40% from 60% and has reduced benchmark interest rates twice since November. The central bank and the China Banking Regulatory Commission said on Sept. 30 that they will encourage lenders to issue mortgage-backed securities. The government is trying balance efforts to provide new financing with steps to rein in unprecedented borrowing. Real estate companies sold a record $44.4 billion-equivalent of bonds in 2014, data compiled by Bloomberg show. In the latest sign of industry stress, Kaisa Group Holdings Ltd., based in the southern city of Shenzhen, is seeking a restructuring that would impose noteholder losses, fueling speculation that builder defaults may spread.

Read more …

Is Ambrose seeking to offset the bleak views he posted lately?

Bonds Beware As Money Catches Fire In The US And Europe (AEP)

Be thankful for small mercies. The world economy is no longer in a liquidity trap. The slide into deflation has, for now, run its course. The broad M3 money supply in the US has been soaring at an annual rate of 8.2pc over the past six months, harbinger of a reflationary boomlet by year’s end. Europe is catching up fast. A dynamic measure of eurozone M3 known as Divisia – tracked by the Bruegel Institute in Brussels – is back to growth levels last seen in 2007. History may judge that the ECB launched quantitative easing when the cycle was already turning, but Italy’s debt trajectory needs all the help it can get. The full force of monetary expansion – not to be confused with liquidity, which can move in the opposite direction – will kick in just as the one-off effects of cheap oil are washed out of the price data.

“Forecasters ignore broad money at their peril,” says Gabriel Stein, at Oxford Economics. Inflation will soon be flirting with 2pc across the Atlantic world. Within a year, the global economic landscape will look entirely different, with an emphasis on the word “look”. In my view this will prove to be mini-cyclical in a world of “secular stagnation” and deficient demand, but mini-cycles can be powerful. Mr Stein said total loans in the US are now growing at a faster rate (six-month annualised) than during the five-year build-up to the Lehman crisis. “The risk is that the Fed will have to raise rates much more quickly than the markets expect. This is what happened in 1994,” he said. That episode set off a bond rout. Yields on 10-year US Treasuries rose 260 basis points over 15 months, resetting the global price of money. It detonated Mexico’s Tequila crisis.

Bonds are even more vulnerable to a reflation shock today. You need a very strong nerve to buy German 10-year Bunds at the current yield of 0.16pc, or French bonds at 0.43pc, at time when EMU money data no longer look remotely “Japanese”. Granted, there may be tactical reasons for buying Bunds, even at negative yields out to eight years maturity. Supply is drying up. Berlin is pursuing a budget surplus with religious zeal, paying down €18bn of debt over the past year. It has left the Bundesbank little to buy as it launches its share of QE. Yet this is collecting pfennigs on the rails of a high-speed train. The German property market is on the cusp of a boom. David Roberts, of Kames Capital, warns of a “poisonous cocktail” of resurgent inflation and rising wages. “If you look at Bunds in anything other than the shortest possible timescale, the risk becomes very clear.”

Read more …

Dick Tator. Mr. Dick Tator.

ECB’s Mario Draghi Says Stimulus Is Working (WSJ)

European Central Bank President Mario Draghi said the bank’s stimulus efforts are beginning to take hold in the European economy and batted away concerns in financial markets that the bank may have to end its more than €1 trillion ($1.1 trillion) asset purchase program early. Mr. Draghi’s Wednesday news conference, held after the ECB decided to keep interest rates and other policies unchanged, was briefly interrupted by a confetti-throwing protester who jumped on the table where Mr. Draghi was seated and shouted “end the ECB dictatorship” as he began his opening remarks.

Mr. Draghi, who appeared unfazed by the ruckus after being whisked away by his bodyguards to a side room for a few minutes, said the bank’s stimulus drive is “finally finding its root” in the economy through easier credit conditions and lower inflation-adjusted interest rates. “The euro area economy has gained further momentum since the end of 2014,” said Mr. Draghi. “We expect the economic recovery to broaden and strengthen gradually.” Still, Mr. Draghi said the region’s recovery depends on full implementation of the ECB’s policies. Those include a record-low lending rate that the ECB kept unchanged Wednesday; cheap four-year loans to banks; and a €60 billion-a-month program to buy mostly government bonds that the ECB launched last month and intends to continue through September 2016.

On Tuesday, the IMF raised its forecast for eurozone growth this year to 1.5% from 1.2%. Though well below the levels of growth the U.S. has achieved during its recovery, it was a welcome development for a region that last year narrowly escaped its third recession in six years. Mr. Draghi cited a long list of reasons why this recovery should continue whereas previous ones have faltered. Lower oil prices, which cut costs for businesses and households, are joining the ECB’s stimulus in boosting the economy, Mr. Draghi said, noting that business and consumer confidence is up and that there should be fewer headwinds from fiscal policy.

[..] Mr. Draghi also played down concerns that the superlow interest rates brought on by the ECB’s policies could fuel bubbles in financial markets. “So far we have not seen evidence of any bubble,” he said, adding that regulatory policies, known as macroprudential tools, would be “the first line of defense” if imbalances started to form. He sidestepped questions about how the ECB would react in the event Greece isn’t able to reach agreement with its international creditors to unlock bailout funds, saying developments are “entirely in the hands of the Greek government.”

Read more …

Schaeuble needs to stop telling Greece what to do.

Schaeuble Says Greece Must Ditch False Hopes, Commit to Reform (Bloomberg)

German Finance Minister Wolfgang Schaeuble ruled out further concessions to Greece, saying it’s up to the Greek government to commit to the reforms needed to release aid rather than give false hopes to its people. Schaeuble, speaking in a Bloomberg Television interview in New York on Wednesday, said that another debt restructuring wasn’t up for discussion now, and that Greek demands for war reparations from Germany were “completely unrealistic.” “It’s entirely down to Greece,” said Schaeuble, 72. While some kind of restructuring might be on the agenda in 10 years, “today the issue for Greece is reforming its economy in such a way that it becomes competitive at some point.”

Greece’s plight is deepening with no end in sight to the standoff with creditors over releasing the final installment of bailout aid that has been stalled since the January election of Prime Minister Alexis Tsipras’s anti-austerity government. Greek 10-year bond yields surged and bank stocks plunged to their lowest level in at least 20 years on Wednesday after a report in Die Zeit newspaper the German government was working on a plan to keep Greece in the euro area if the country defaulted, triggering a halt to European Central Bank funding. “We don’t have such plans, and if we were working on them – because ministry staff are taking just about everything into consideration – then we would definitely not talk about it,” said Schaeuble. “It makes no sense to speculate about it.”

With a monthly bill of about €1.5 billion for pensions and salaries and repayments to its international creditors looming, Greece is targeting next week’s meeting of euro-area finance ministers in Riga, Latvia, as a deadline for unlocking the funds. While Schaeuble said earlier Wednesday that “no one” in the euro region expects a resolution of the standoff by the Riga meeting on April 24, he softened his tone in the interview, saying that the end of the program on June 30 was the only deadline that mattered. “If Greece wants support, we will give this support as in recent years, but of course within the framework of what we agreed,” he said. While the decisions ultimately lie with Greece, “whatever happens: we know that Greece is part of the European Union and that we also have a responsibility for Greece and we will never disregard this solidarity.”

Read more …

“..Tsipras’s government had “destroyed” progress made by previous administrations..” That’s the progress that led to hungry children?!

Schaeuble Criticizes Greece for Backsliding as Time Runs Out (Bloomberg)

German Finance Minister Wolfgang Schaeuble criticized Greece for backsliding on reforms, saying that “no one” expects a resolution next week of the standoff with Alexis Tsipras’s government over untapped bailout funds. Schaeuble, in his first comments on the matter since before the Easter holidays, said Tsipras’s government had “destroyed” progress made by previous administrations in overhauling the Greek economy. “It’s a tragedy,” he said Wednesday at the Council on Foreign Relations in New York, adding that the country needed to become competitive to stop being a “bottomless pit.” The comments by the finance chief of the region’s biggest economy underscored the rising concern in European capitals that Greece is running out of time to unfreeze the aid needed to keep the country afloat.

Standard & Poor’s cut Greece’s rating Wednesday, citing the country’s deteriorating outlook. Schaeuble is among European officials who are skeptical that there’s enough time to work out a deal ahead of a meeting of euro-area finance ministers at the end of next week in Riga, Latvia, to assess whether Greece has made enough progress to warrant a disbursement from its €240 billion bailout fund. Leaders are pressuring Greece to submit specific reforms as the country runs out of cash and faces debt payments and monthly salary obligations in the coming weeks.

Germany said Wednesday that an aid payment from the bailout fund won’t happen this month, and that Greece’s negotiations with creditors have failed to move forward. “I said last time that there has been progress, but that really there is still a considerable need for negotiations,” Friederike von Tiesenhausen, a German Finance Ministry spokeswoman, said. “Things have not really changed.” Greece’s credit rating was lowered one level to CCC+, with a negative outlook, by S&P, which estimated that the country’s economy contracted close to 1% in the past six months. The downgrade leaves the nation’s rating seven steps into junk territory.

Read more …

“..taxes might have to go up to cover a $25bn budget black hole caused by falling commodity prices..” “..BHP Billiton and Rio Tinto launched a huge expansion which saw mining investment as a percentage of the Australian economy peak at a whopping 7% in 2012. ”

Australia’s Economy: Is The Lucky Country Running Out Of Luck? (Guardian)

After 24 years of uninterrupted economic growth, Australia is entering the kind of difficult waters experienced by every other major developed country in the past decade. Even if Thursday’s unemployment figures show more jobs were added last month, the Coalition is set to go into the next election with an unusually gloomy outlook. Australians are finding it harder to get a job than at any time in more than decade and those who are in work are seeing the weakest wage growth for two decades. There are even fears that taxes might have to go up to cover a $25bn budget black hole caused by falling commodity prices. As one leading economist put it, the lucky country is running out of luck. Growth is still on target for a healthy at 2.8% for this year, according to the IMF, the kind of number that would send European leaders scrambling for the tweet button.

But the question of whether Australia loses its remarkable record of continuous growth depends, as with almost everything else in the economy, on what happens in China. “Australia has gone 24 years without a recession thanks to good management and good luck,” said Saul Eslake at BoA in Sydney. “Up to the early 2000s it was managed well and then it wasn’t. But then the luck improved because of China’s huge stimulus after the global financial crisis. Now the luck is running out.” The slowdown in the world’s second biggest economy is now well and truly underway. Demand for Australia’s iron ore and coal has plummeted from a decade ago as Beijing seeks to scale back its huge building schemes and create a more consumer-led economy. The price of the steel-making commodity, Australia’s biggest export, has fallen from $130 at the start of 2014 to around $50. Coal has halved in price in the past four years.

Buoyed by the good times, resource companies led by BHP Billiton and Rio Tinto launched a huge expansion which saw mining investment as a percentage of the Australian economy peak at a whopping 7% in 2012. The new output from their giant mines in Western Australia is now hitting the market, making export figures look healthy but adding to the pressure on prices and leaving Australia with a potentially wretched hangover.

Read more …

How does this not violate the Minsk agreement?

US Military Lands in Ukraine (Ron Paul Inst.)

Paratroopers from the US Army’s 173rd Airborne Brigade have arrived in Ukraine to begin training that country’s national guard and provide it with new military equipment. The Ukrainian government took power in a US-backed coup in early 2014 and has waged war on eastern provinces that wish to breakaway from what they see as an illegitimate government. The US military action, dubbed “Operation Fearless Guardian,” will improve the Washington-backed faction’s ability to wage war against the breakaway regions, but at least in spirit will violate the “Minsk II” ceasefire agreement which mandates a “pullout of all foreign armed formations, military equipment.”

The US military involvement on behalf of the US-backed government in Kiev comes at a key time in the shaky ceasefire. The Organization for Security and Cooperation in Europe (OSCE) has noted a serious increase in fighting in the breakaway eastern regions of Ukraine and OSCE monitors have pointed the finger at US-backed Kiev as the instigator of these new attacks. The relevant OSCE report finds:

…that the Ukrainian side (assessed to be the Right Sector volunteer battalion) earlier had made an offensive push through the line of contact towards Zhabunki (“DPR”-controlled, 14km west-north-west of Donetsk…

The US military’s “Operation Fearless Guardian” will ultimately involve some 300 US Army personnel “training three battalions of Ukrainian troops in a range of infantry tactics.” With Ukraine’s US-backed president promising to “retake” the breakaway regions in the east despite having signed the ceasefire, it is clear that US training constitutes the beginning of direct US military involvement in the Ukrainian conflict. As such it is undeniably an escalation.

Read more …

Well, they sure have no money to buy entirely new systems.

Greece In Talks With Russia To Buy Missiles For S-300 Systems (Reuters)

Greece is negotiating with Russia for the purchase of missiles for its S-300 anti-missile systems and for their maintenance, Russia’s RIA news agency quoted Greek Defense Minister Panos Kammenos as saying on Wednesday. The report followed a visit by Greek Prime Minister Alexis Tsipras last week to Moscow, where he won pledges of Russian moral support and long-term cooperation but no fresh funds to help avert bankruptcy for his heavily indebted nation. NATO member Greece has been in possession of the Russian-made S-300 air defense systems since the late 1990s.

“We are limiting ourselves to replacement of missiles (for the systems),” RIA quoted Kammenos, who is in Moscow for a security conference, as saying. “There are negotiations between Russia and Greece on the maintenance of the systems … as well as for the purchase of new missiles for the S-300 systems,” he said. The Greek defense ministry in Athens later issued a statement quoting Kammenos as saying: “The existing defense cooperation programs will continue. There will be maintenance for the existing programs.”

Read more …

Paid for years ago.

Putin to Netanyahu: Iran S-300 Air Defense System is .. Defensive (Juan Cole)

Russian President Vladimir Putin spoke by phone with Israeli Prime Minister Binyamin Netanyahu Tuesday with regard to the Russian Federation’s decision to go ahead with the sale to Iran of S-300 anti-aircraft batteries. Iran bought the batteries several years ago, but delivery was delayed by Moscow because of US and international pressure. The US has led the imposition of severe economic sanctions on Iran, perhaps the most severe ever applied to any country in modern history, including having Iran kicked off the SWIFT bank exchange. In deference to US wishes, Russia did not ship the system.

Two things have now changed. First, Russia and the US are not getting along nearly as well in the wake of the Russian annexation (or reclaiming, from Moscow’s point of view) of Crimea from Ukraine and its support for ethnically Russian fighters in Ukraine’s east. In fact, the US has begun imposing sanctions on Russia. In turn, Russia no longer has great regard for US wishes. Second, the five permanent members of the UN Security Council plus Germany have concluded a framework agreement permitting Iran’s civilian nuclear enrichment program, which is aimed at imposing inspections and equipment restrictions that would make it very difficult if not impossible for Iran to break out and create a nuclear weapon.

Russia and China have been the least supportive of severe sanctions on Iran, and Russia appears to have decided that since the negotiations have reached a serious phase, it is time to go ahead with this deal, concluded some time ago. The announcement alarmed Israeli Prime Minister Binyamin Netanyahu, whose government has often hinted around that it might bomb Iran. The Putin government issued a communique that “gave a detailed explanation of the logic behind Russia’s decision…emphasizing the fact that the tactical and technical specifications of the S-300 system make it a purely defensive weapon; therefore, it would not pose any threat to the security of Israel or other countries in the Middle East.”

Read more …

“..safeguard Creation … Because if we destroy Creation, Creation will destroy us!”

Vatican Announces Major Summit On Climate Change (ThinkProgress)

Catholic officials announced on Tuesday plans for a landmark climate change-themed conference to be hosted at Vatican later this month, the latest in Pope Francis’ faith-rooted campaign to raise awareness about global warming. The summit, which is scheduled for April 28 and entitled “Protect the Earth, Dignify Humanity. The Moral Dimensions of Climate Change and Sustainable Development,” will draw together a combination of scientists, global faith leaders, and influential conservation advocates. UN Secretary General Ban Ki-moon is slotted to offer the opening address, and organizers say the goal of the conference is to “build a consensus that the values of sustainable development cohere with values of the leading religious traditions, with a special focus on the most vulnerable.”

“[The conference hopes to] help build a global movement across all religions for sustainable development and climate change throughout 2015 and beyond,” read a statement posted on several Vatican-run websites. According to a preliminary schedule of events for the convening, attendees hope to offer a joint statement highlighting the “intrinsic connection” between caring for the earth and caring for fellow human beings, “especially the poor, the excluded, victims of human trafficking and modern slavery, children, and future generations.” The gathering will undoubtedly build momentum for the pope’s forthcoming encyclical on the environment, an influential papal document expected to be released in June or July.

The Catholic Church has a long history of championing conservation and green initiatives, but Francis has made the climate change a fixture of his papacy: he directly addressed the issue during his inaugural mass in 2013, and told a crowd in Rome last May that mistreating the environment is a sin, insisting that believers “safeguard Creation … Because if we destroy Creation, Creation will destroy us! Never forget this!” The Vatican also held a five-day summit on sustainability in 2014, calling together microbiologists, economists, legal scholars, and other experts to discuss ways to address climate change.

Read more …

Apr 112015
 
 April 11, 2015  Posted by at 7:08 pm Finance Tagged with: , , , , , ,  2 Responses »


G. G. Bain Goose Creek, houses on the water, Jamaica Bay, Long Island 1910

Euro’s Reserve Status Jeopardized As Central Banks Dump Holdings (Blooomberg)
Why The Euro Could Fall Even Further (CNBC)
Putin’s New Problem Is The Strong Ruble (Bloomberg)
Greece: The Next Deadline Approaches (CNBC)
Greek Finance Minister Steers Debt Talk His Way (NY Times)
100,000 Italians Sign Petition For Eurozone Exit Referendum (RT)
PetroChina Overtakes Exxon Mobil To Become World’s Biggest Energy Company (RT)
China Bears on Wrong End of $4 Trillion Rally Refuse to Go Away (Bloomberg)
WWII Reparations: Rare Footage From Greece’s Occupation By The Nazis (KTG)
EU Leaders Snub Moscow World War II Commemorations (Spiegel)
Obama Says ‘Days Of Meddling’ In Latin America Are Past (BBC)
Sneak Peek At Pope’s Crusade (Paul B. Farrell)
Agriculture Poses Immense Threat To Environment (EurActiv)
California’s New Era of Heat Destroys All Previous Records (Bloomberg)

“As a reserve currency, the euro is falling apart..”

Euro’s Reserve Status Jeopardized As Central Banks Dump Holdings (Blooomberg)

Quantitative easing may be helping Europe achieve its economic targets, but it’s also undermining the long-term viability of the euro by tarnishing its allure as a global reserve currency. Central banks cut their euro holdings by the most on record last year in anticipation of losses tied to unprecedented stimulus. The euro now accounts for just 22% of worldwide reserves, down from 28% before the region’s debt crisis five years ago, while dollar and yen holdings have both climbed, the latest data from the IMF show. “As a reserve currency, the euro is falling apart,” said Daniel Fermon, a strategist at SocGen. “As long as you have full quantitative easing, there’s no need to invest. The problem for the moment is we don’t see a floor for the currency. Money’s flowing out.”

ECB President Mario Draghi has in the past welcomed the drop-off in reserve managers’ holdings because a weaker exchange rate makes the continent more competitive. Yet firms including Mizuho Bank Ltd. warn the currency’s waning popularity reflects a more lasting loss of confidence in an economy that shrank in two of the past three years. “Global reserve managers may be thinking the euro is going to sink economically if it continues this way,” said Daisuke Karakama, the Tokyo-based chief market economist at Mizuho and a former European Commission official. With yen allocations rising, “they may be expecting Japan’s positive economic growth to continue as a result of” that nation’s record stimulus, Karakama said.

The decline in euro reserves suggests other central banks consider the ECB’s €1.1 trillion of QE bond purchases, which started a month ago, to be the biggest threat to the currency’s global status since its 1999 debut. Greece’s debt woes aren’t helping, either. The ECB ramped up the emergency funding available to Greek banks Thursday to alleviate the country’s worsening liquidity issues amid drawn- out negotiations over its bailout. All this is prompting banks from Citigroup, the world’s biggest foreign-exchange trader, to Goldman Sachs to predict the euro will fall below parity with the dollar this year, from a 12-year low of $1.0458 last month and $1.0617 Friday.

Read more …

Plenty reasons.

Why The Euro Could Fall Even Further (CNBC)

It’s been a one-way euro trip lower. The common currency has fallen every day this week, and is now near the lowest levels in 12 years. Now, currency traders are keenly watching American economic data, as better news about the economy could lead the euro drop to intensify. It all comes down to expectations about the Federal Reserve’s next move. Most market participants believe the Fed will raise short-term rate targets this year. That should help the U.S. dollar and hurt the euro, as it means that holding dollars will produce greater returns than holding euros, increasing demand for the greenback.

Expectations about a June Fed move have been tamped down due to a bevy of soft economic readings, most conspicuously the March jobs number. But this week, the Fed minutes and hawkish words from William Dudley have told investors that a June hike is still on the table, according to Boris Schlossberg of BK Asset Management. Dudley, the generally dovish New York Fed president, told Reuters on Wednesday that depending on how the data develops, a June move could be “still in play.” In the week ahead, Schlossberg says the biggest data point he will watch is Tuesday’s retail sales report. If it indicates that “the U.S. consumer finally started to spend, then dollar bulls run wild, and we may see 1.0500 break” on the euro, which is currently a bit below 1.0600 per dollar.

That’s because better data could serve to convince traders that the much-awaited Fed move will come sooner than previously anticipated. However, some traders say the move is overdone. “This short-term move is technical, so I expect to see the euro bounce and the dollar pull back off of the recent move,” said David Seaburg at Cowen.

Read more …

Not that big a problem. It allows for the interest rate to come down further.

Putin’s New Problem Is The Strong Ruble (Bloomberg)

Vladimir Putin is facing a problem few could have anticipated: The ruble is becoming too strong. Last year’s worst-performing major currency is this year’s best and while that’s buoying the nation’s bonds, driving yields to the lowest in four months, it’s also crimping Russia’s export revenue. Even though oil is little changed in dollars this year, the price when converted to rubles has plunged to the lowest since 2011. The currency rout in 2014 helped Russia to keep its budget deficit within 1% of GDP as the ruble weakened in lockstep with a 50% slump in oil. Now, with the cease-fire in Ukraine and the allure of higher-yielding assets attracting investors to ruble debt, the government is seeing the opposite effect.

“The current ruble level is already uncomfortable for the budget considering the oil price in rubles is already low,” Vladimir Bragin, head of research at Alfa Capital in Moscow, said by phone on Thursday. “In order to reach macroeconomic stability, Russia needs to limit its budget deficit and a weaker ruble is an easy way to do that.” The ruble’s 14% gain this month is making it easier for central bank Governor Elvira Nabiullina to push ahead with rate cuts this year after she hoisted the benchmark to 17% in December to stem the currency’s slide. Nabiullina lowered the rate by 3 percentage points so far in 2015.

Read more …

“The prospect of a negotiated exit within a month is now close to 40%..”

Greece: The Next Deadline Approaches (CNBC)

Greece repaid one of its key loans on Thursday, but with the country’s coffers still close to empty, the government may merely have earned short-term respite. As the holiday of the Orthodox Easter Weekend approaches, newly minted Prime Minister Alexis Tsipras and Finance Minister Yanis Varoufakis are unlikely to be unwinding for the long weekend. Greece has been given six working days by the euro zone technical staff of the Euro Working Group to come up with proposals for a reform agenda—on which further financial aid is conditional—ahead of a key meeting of euro zone finance ministers on April 24 in Riga, Latvia. The struggling Greek economy still needs financial support. It faces two redemptions of bills for a total of €2.4 billion as soon as April 14 and 17.

“Euro area finance ministers are probably at the end of their tether, after ten weeks of the new government’s foot-dragging and game-playing, and any sympathy for the Greek position has long disappeared,” the economic research team at Daiwa wrote in a research note. Tsipras is barely off the plane from a trip to Russia, which seemed on the surface to have achieved little in terms of concrete promises from Russia to assist Greece in the event of it defaulting on its debt repayments, leaving the euro or losing financial support from its creditors.

Economists are now increasingly taking the possibility of a “Grexit”, deemed incredibly unlikely by many just a couple of years ago. The risk of Greece defaulting on its debt repayments is now 50-50%, according to UBS, although its analysts argue that default does not necessarily mean euro zone exit. The prospect of a negotiated exit within a month is now close to 40%, according to Gabriel Sterne, head of global macro research at Oxford Economics. And capital controls – limits on the amount of money that can be taken out of the country—usually a sign of severe economic distress—are just “one more turn of the financial screw away” he added.

Read more …

“After five years of austerity imposed by creditors, “the word ‘reform’ resonates in Greece like the word ‘democracy’ in Iraq,” he said. “It’s a dirty word.”

Greek Finance Minister Steers Debt Talk His Way (NY Times)

You would never know from his demeanor that Yanis Varoufakis, the celebrity Greek finance minister, was carrying the weight of a nation on his shoulders. In fact, you could be forgiven for thinking that it was his country’s uncompromising creditors who were on the defensive. On Thursday, at a conference of economic luminaries, Mr. Varoufakis was working hard to divert the discussion from Greece’s shrinking financial freedom and fears that it might default. (He had a bit of wind at his back with news that Greece on this same day had just met its deadline for repaying a €460 million, or $491 million, loan installment to the IMF. Rather than concede any Greek missteps, Mr. Varoufakis wanted to assess the flaws of the eurozone that he said had been revealed by the 2008 global meltdown and its aftermath.

“There is no doubt that if we had a federal republic, if we had a United States of Europe, we would not be here discussing the Greek crisis, the eurozone crisis, banking union or anything of the sort,” he said in an onstage conversation with the Nobel laureate Joseph E. Stiglitz, at a conference of the Institute for New Economic Thinking. “Unfortunately,” he added, “the way we designed the eurozone, it was crying out for a crisis.” Mr. Varoufakis, as is now well known, became finance minister in January as part of the Syriza-led leftist government of Prime Minister Alexis Tsipras, which came to power promising voters to renegotiate the €240 billion international bailout, whose terms Athens blames for sending the economy into a tailspin and leaving more than 50% of Greek youth jobless.

When Mr. Stiglitz asked him how Greece’s creditors could have repeatedly overestimated the country’s ability to grow under the terms of the bailout, Mr. Varoufakis replied, “I think it’s the politics of denial.” Even making Thursday’s payment to the I.M.F. required scraping together money from the government’s dwindling resources. It staved off a default for now, but did nothing to solve the bigger problem: that the government is running out of cash to meet obligations like paying pensions and the wages of public employees. To obtain another tranche of desperately needed bailout funds, Greece still has to persuade its highly skeptical creditors — which also include the ECB and the European Commission — that Athens has a credible economic overhaul plan. [..]

Mr. Varoufakis, 54, comes across as a sort of debonair Mr. Spock, a financial Vulcan of the eurozone. Dressed in a dark jacket with his trademark casual, open-collared shirt, he speaks clearly about the currency bloc’s awkward truths, avoiding the jargon and evasiveness that normally characterizes the region’s dreary politics. Appearing on a separate panel with Mr. Varoufakis on Thursday, the Irish central bank chief, Patrick Honohan, referred to the “glass being half full” after Ireland’s bailout and tentative recovery. “I don’t like the metaphor,” Mr. Varoufakis said. “In the case of my country, the glass is broken.”

Read more …

“..Italy’s debt increased dramatically after the introduction of the euro..”

100,000 Italians Sign Petition For Eurozone Exit Referendum (RT)

Italy’s Five Star Movement (M5S) party has collected more than 100,000 signatures on a petition calling for a law that would allow a referendum on withdrawal from the eurozone. M5S MP Carlo Sibila says he expects a referendum to take place at the start of next year. Though the petition has already surpassed the required amount of signatures needed for the initiative, Sibila said that he hopes it will gather another 50,000 by early May in order to highlight the issue. “Who wants to stay in euro? This is the main question,” Sibila told RT. “But we don’t want to get out just like this – we want a program and a discussion, and then let the citizens decide. It’s really necessary today as the situation in Italy is going from bad to worse where jobs and economy are concerned.” The Italian constitution, however, does not provide for the cancellation of international agreements through referenda.

According to Sibila, Italy’s debt increased dramatically after the introduction of the euro. He also noted that Italy’s unemployment rate hovers around 12.7%, the sixth highest in the EU. “We can’t have our own fiscal policy, but without the euro it is possible in Italy,” Sibila said. The Five Star Movement, formed in 2009 by comedian and activist Beppe Grillo, finished second in the 2014 European Parliament election with 21% of the vote. Sibila stressed that M5S does not seek to leave the European Union, but merely to leave the currency union. “Italian citizens need to have the right to decide if they want to stay inside or outside the monetary union,” Sibila told RT. “We are not questioning the EU, it is only the monetary union.” Italy joined the Eurozone in 1999, and the currency was introduced into circulation three years later.

Read more …

“..the Chinese company’s Class-A shares have gained 61% since last April..”

PetroChina Overtakes Exxon Mobil To Become World’s Biggest Energy Company (RT)

The capitalization of China’s biggest oil producer PetroChina reached $352.8 billion during Thursday trading in Shanghai, surpassing ExxonMobil as the world’s most valuable energy company for the first time since 2010. The market cap of America’s Exxon reached $352.6 billion in Shanghai Thursday trading, Bloomberg reports. PetroChina’s market cap has gone up 13.81% in the last 12 months while Exxon’s market value has fallen by 14%, following the slump in oil prices. Moreover, the Chinese company’s Class-A shares have gained 61% since last April. The last time PetroChina was more valuable than Exxon was at the close of trading on June 25, 2010, according to Bloomberg.

“PetroChina has multiple positives at the moment: it’s got a reform story, it’s also listed in Hong Kong, and China has more freedom for mainland fund managers in the works,” said Mark Matthews head of Asia research at Bank Julius Baer & Co. in Singapore. “China is also planning to transfer stakes in state-owned enterprises away from their regulator, which will on the whole be positive for SOEs,” he added. Oil companies across the world have been facing difficult times since crude prices started to plunge last summer. ExxonMobil’s adjusted net income of $6.3 billion in the fourth quarter was the lowest since a loss in the final three months of 2009, according to Bloomberg data. PetroChina’s net profit was $1.8 billion in the same period.

The Shanghai Composite closed at its highest level in seven years on Thursday gaining about 88% over the past year as the best performer among major indexes. Meanwhile, the Chinese yuan has declined 0.1% versus the dollar in the past year. PetroChina is the listed arm of state-owned China National Petroleum Corporation (CNPC), with almost all of its operating profit coming from the exploration and production sector along with a small contribution from its natural gas and pipeline unit.

Read more …

Some bubbles these days take on grotesque proportions.

China Bears on Wrong End of $4 Trillion Rally Refuse to Go Away (Bloomberg)

Bull markets are always tough on short sellers. This one in China right now, though, is proving downright brutal. Bearish wagers on the Shanghai Stock Exchange have climbed threefold in the past nine months and reached a record 6.09 billion yuan ($981 million) on Wednesday, a period in which the benchmark equity index jumped 94%. Across the border in Hong Kong, where the Hang Seng Composite Index has surged 7.6% in just the past two days, the gauge’s 20 most-shorted stocks surged 18% on average. The gains show the dangers of betting against a Chinese market where new investors are flocking to stocks at a record pace and traders have taken out an unprecedented 1.06 trillion yuan of debt in Shanghai to amplify their buying power.

While technical indicators show shares in both the mainland and Hong Kong are more vulnerable to a reversal than any other market, Marco Polo Pure Asset Management says bears may be setting themselves up for more losses if China’s stimulus efforts produce an economic recovery later this year. “It’s not a market you want to bet against,” said Aaron Boesky, who oversees about $125 million as the chief executive officer of Marco Polo in Hong Kong. The firm’s Pure China fund was the top performer in the second half of 2014 among China-focused hedge funds tracked by AsiaHedge Intelligence. “I can respect people who might want to stay out of it, because it is a very volatile market, even for local Chinese,” he said. “Staying out is respectable. Shorting it could be suicidal.”

Read more …

“Greece lost 13% of its population during WWII..”

WWII Reparations: Rare Footage From Greece’s Occupation By The Nazis (KTG)

Greek Defense Ministry has published a video with rare footage from the occupation of Greece by the Nazis during the World War II. Among others, the footage shows children suffering from malnutrition and emaciated adults, victims of the Great Famine during the Nazi occupation. The video should be seen in the context of the Greek claim of €278.7 billion in WWII reparations from Germany. According to the video voice-over, the Enforced Loan by the Nazis was to blame for the mass starvation of estimated 300,000 people in Athens alone. “The agreement of 14 March 1942 foresaw that Greece paid to its occupiers 1.5 billion drachmas per month, a total of 3.5 billion USD, according to the Dollar value of 1938.

The current value of the enforced loan is 54 billion euro without the interest. The agreement had to be implemented retrospectively as of 1.1. 1942. The agreement was signed by Germany and Italy and Greece was notified later. Two agreement modifications were added on 2. December 1942, with the effect that Germany had to start repaying the loan by April 1943. Germany paid back two installments only. In the Peace Paris Treaties (1947) Greece claimed 14 billion USD in war reparations, but the allies reduced the Greek claim down to 7.1 billion USD.” According to the video “Greece lost 13% of its population during the WWII. One part was lost in the battlefield, but the largest part due to Famine and the Nazis’ atrocities.”

The Great Famine, the period of mass starvation during the occupation of Greece by the powers of Axis – the fascist Italy and the Nazi Germany – hit especially the urban areas and some islands. The Great Famine was initiated by a large scale plunder by the Axis forces and as soon as the German army entered Athens 0n 27. April 1941. The Nazis confiscated fuel and all means of transportation, including fishing boats, preventing any transfer of food and other supplies and seized strategic industries. They proceeded with the wholesale and food looting , unemployment and hyperinflation skyrocketed, the black market flourished. The price of bread was increased 89-fold from April 1941 to June 1942.

Read more …

“Since it was declared an official holiday in 1965, May 9, with its spontaneous gatherings of veterans in the streets, public festivals and gun salutes in the evening, has in fact become Russia’s most moving holiday..”

EU Leaders Snub Moscow World War II Commemorations (Spiegel)

This Monday, Russia President Vladimir Putin visited the cemetery in the village of Marfino, not far from the old western Russian city of Staraya Russa, where he placed a bouquet of red roses. Then he met with veterans of the “Great Patriotic War,” the term Russians use to describe their battle against Hitler. It would be hard to find another part of Russia that is as saturated with the blood of that war than the earth around Staraya Russa. Officially, 850,000 soldiers died there during the two-and-a-half-year German occupation. The real figure is probably higher, because the Red Army long attempted, albeit unsuccessfully, to fend off repeated attacks by the enemy along the northwestern front.

The encounter near Marfino was one of the events with which the Russian president is preparing his country for May 9, which marks the anniversary of the end of the war with Hitler’s Germany. It is “our country’s most important and most honest holiday,” Putin said in Staraya Russa. “It is the day of the great victory.” The end of the war will be commemorated in Russia for the 70th time this year. Since it was declared an official holiday in 1965, May 9, with its spontaneous gatherings of veterans in the streets, public festivals and gun salutes in the evening, has in fact become Russia’s most moving holiday — and perhaps the only one that has truly united the people. The victory over Hitler happened three generations ago.

Still, during Putin’s visit to Staraya Russa, the veterans reminded him of the words of military commander Alexander Suvorov, who said that a war is not over “until the last soldier has been buried.” Last year, search teams recovered the remains of 12,900 fallen soldiers from swamps near Novgorod, the forests of Smolensk and the region around St. Petersburg.

Read more …

Right. Sure.

Obama Says ‘Days Of Meddling’ In Latin America Are Past (BBC)

US President Barack Obama has told Latin American leaders that the days when his country could freely interfere in regional affairs are past. He was speaking just before the seventh Summit of the Americas was due to kick off in Panama City. Mr Obama and Cuban leader Raul Castro will meet face-to-face for the first time since a December detente. But their much-anticipated meeting could be overshadowed by tensions between the US and Venezuela. Mr Obama told a forum of civil society leaders in Panama City that “the days in which our agenda in this hemisphere presumed that the United States could meddle with impunity, those days are past”.

At past Summits of the Americas, which bring together the leaders of North, Central and South America, the US has come in for criticism for its embargo against Cuba and its objection to having Cuba participate in the gatherings. This seventh summit is the first which Cuba will attend and much of the attention will be focussed on the body language between the former foes. The meeting will the be first formal encounter between the leaders of the US and Communist-run Cuba in more than five decades. Mr Obama stressed that he hoped the thaw in relations would improve the lives of the Cuban people. “Not because it’s imposed by us, the United States, but through the talent and ingenuity and aspiration and the conversation among Cubans, among all walks of life. So they can decide what is the best course of prosperity.”

Read more …

“If we destroy Creation … Creation will destroy us..”

Sneak Peek At Pope’s Crusade (Paul B. Farrell)

Here’s a sneak peak of Pope Francis’s historic “Climate Change Encyclical,” soon to be released, complete with talking points for his upcoming address to the joint session of Congress. We’ll analyze them: The encyclical’s likely headline: “Safeguard Creation … We are the custodians of Creation … If we destroy Creation … Creation will destroy us,” a public warning often repeated by the pontiff this past year, a message certain to intensify the anger of GOP climate-science deniers, Big Oil, Koch Bros, Exxon Mobil and most fossil-fuel firms, as well as their banks, investors owning their stocks and capitalists everywhere. Here’s why: Pope Francis’s much-anticipated encyclical will be broadcast worldwide to billions, including 5,000 bishops, 400,000 priests and 1.2 billion members of the Roman Catholic Church.

He will be encouraging his army of the faithful to take strong action, fight climate change and global warming threats to the environment. The encyclical will also be translated into hundreds of languages and broadcast worldwide. At the same time, Pope Francis will be lobbying heads of state and religious leaders, and inspiring billions of people worldwide, encouraging them to join this revolution. This historic encyclical will also set the stage for everything else Pope Francis has planned in 2015. He’s a man with a mission to save the world from the accelerating threats to the planet’s natural resources. More immediate, the encyclical will serve as major talking points for his address to the joint session of Congress in September, his address to the United Nations General Assembly in New York and his December message to the historic UN Climate Conference in Paris. Many of his points on the environment are already well known.

Read more …

“.. instead of realising initial plans to stop and reverse the trend of species loss by 2010, more and more species are disappearing from the agrarian landscape..”

Agriculture Poses Immense Threat To Environment (EurActiv)

Conventional agriculture is causing enormous environmental damage in Germany, warns a study by the country’s Federal Environment Agency, saying a transition to organic farming and stricter regulation is urgently needed. EurActiv Germany reports. Spanning over 50% of the country, agriculture takes up by far the biggest amount of land in the country, and is one of its most important economic sectors. But intensive farming still harms the environment to an alarming extent, according to a study conducted by the Federal Environment Agency (UBA). The use of pesticides and fertilisers as well as intensive animal husbandry, have a negative impact on humans and nature, the 40-page document indicates. “Over the last 30 years, innovation and technical progress in most sectors has led to great successes in reducing the amount of substance that reaches the environment.

But agriculture emissions show only marginal improvements,” the study’s authors write. One of the most controversial issues concerns greenhouse gas emissions. According to the researchers, the use of moors and clear-cutting for agriculture, as well as fertilisers, soil cultivation and animal husbandry produce a high level of emissions that impact the climate. In 2012, agriculture-related emissions were around 70 million tonnes of CO2 equivalent – about 7.5% of the year’s total greenhouse gas emissions. This means that after industry, which made up 84%, agriculture was the second largest emitter in Germany. Biodiversity is also threatened by intensive farming. Agriculture burdens the environment with nitrogen, phosphorus and heavy metals. Broad-spectrum pesticides not only wipe out parasites, but also kill other beneficial insects.

As a result, this has adverse effects on birds and other mammals, who lose their food resources. The unfortunate result is that instead of realising initial plans to stop and reverse the trend of species loss by 2010, more and more species are disappearing from the agrarian landscape. The authors write that excessive nitrogen emissions are still alarmingly high, with 60% of nitrogen emissions originating from agriculture. Still, the country’s nitrogen surplus has been stagnating at a high level for years. At an average of 97 kg per hectare, it exceeds the German government’s target value within the sustainability strategy by almost 20 kg per hectare. As a result, agriculture, with a share of 57%, is the nation’s largest source of nitrogen emissions into the environment.

Read more …

A lot more serious than people seem to think.

California’s New Era of Heat Destroys All Previous Records (Bloomberg)

The California heat of the past 12 months is like nothing ever seen in records going back to 1895. The 12 months before that were similarly without precedent. And the 12 months before that? A freakishly hot year, too. What’s happening in California right now is shattering modern temperature measurements—as well as tree-ring records that stretch back more than 1,000 years. It’s no longer just a record-hot month or a record-hot year that California faces. It’s a stack of broken records leading to the worst drought that’s ever beset the Golden State. The last 12 months were a full 4.5 degrees Fahrenheit (2.5 Celsius) above the 20th century average. Doesn’t sound like much? When measuring average temperatures, day and night, over extended periods of time, it’s extraordinary.

On a planetary scale, just 2.2 degrees Fahrenheit is what separates the hottest year ever recorded (2014) from the coldest (1911). California’s drought has already withered pastures and forced farmers to uproot orchards and fallow farmland. It’s costing the state billions each year that it goes on. Governor Jerry Brown issued an executive order this month for the first mandatory statewide water restrictions in U.S. history, with $10,000-a-day penalties against water agencies that fail to reduce water use by 25%. California has seen droughts before with less rainfall, but it’s the heat that sets this one apart. Higher temperatures increase evaporation from the soil and help deplete reservoirs and groundwater. The reservoirs are already almost half empty this year, and gone is the snowpack that would normally replenish lakes and farmlands well into June.

Read more …

Mar 082015
 
 March 8, 2015  Posted by at 1:21 pm Finance Tagged with: , , , , , , , , ,  1 Response »


DPC Sternwheeler Falls City, the levee, Vicksburg, Mississippi 1900

Austria Is Fast Becoming Europe’s Latest Debt Nightmare (Telegraph)
Tsipras: ‘We Don’t Want to Go on Borrowing Forever’ (Spiegel)
Eurogroup To Consider Greek Reform Proposals Amid Scramble For Funding (Kath.)
The ECB’s Lunatic Full Monty Treatment (Tenebrarum)
7 Things To Know About The ECB’s QE Game Plan (MarketWatch)
30 Years Of A Polarised Economy Have Squeezed Out The Middle Class (Observer)
Foreign Banks Tighten Lending Rules For China State-Backed Firms (Reuters)
China’s February Exports Surge 48.3% (CNBC)
Azerbaijan Should Be Very Afraid of Victoria Nuland (GR)
EU Won’t Be Pushed Into Confrontation Over Ukraine – Foreign Policy Chief (RT)
Why Do Russians Still Support Vladimir Putin? (New Statesman)
The Dark Undercurrents Of The War In The Ukraine (Saker)
‘Give Peace A Chance, Decide Sanctions Later’: EU Rethinks Russia (RT)
Layoffs And Empty Streets As Australia’s Boom Towns Go Bust (Reuters)
Venezuela To Get South American Help For Food Crisis (BBC)
Why Fresh Water Shortages Will Cause The Next Great Global Crisis (Guardian)
The Francis Miracle: Inside The Transformation Of The Pope And The Church (TIME)

The hills are alive with the sound of too little money.

Austria Is Fast Becoming Europe’s Latest Debt Nightmare (Telegraph)

Ah Austria, land of schnitzel, lederhosen, Mozart, alpine meadows and beer drinking. Less widely appreciated is its special place in the history of catastrophic banking crises. It was the failure of Creditanstalt, a Viennese bank founded in 1855 by Anselm von Rothschild, that arguably sparked the Great Depression, setting off an unstoppable chain reaction of bankruptcies throughout Europe and America. No-one would think that what happened last week at Austria’s failed Hypo Alpe-Adria Bank International falls into quite the same category; we are meant to be in the recovery phase of the latest global banking crisis, so this is more about re-setting the system than again bringing it to its knees, right? Well, make up your own mind. I suspect neither financial markets nor policymakers have yet caught onto the full significance of the latest turn of events.

In a nutshell, the Austrian government has had enough of funding the bank’s losses, and announced plans to “bail-in” external creditors to the tune of €7.6bn instead. As such, this marks a test case of new European rules to make creditors pay for failing banks. About time too, you might say. What took them so long? Only in this case, the bonds are notionally guaranteed by the Austrian state of Carinthia, which now theoretically becomes liable for the bail-in. It’s an echo of the mess Ireland got itself into at the height of the banking crisis, when it foolishly attempted to stem the panic by underwriting all Irish banking liabilities; the move very nearly ended up bankrupting the entire country. Hypo will bankrupt Carinthia. Essentially, what the Austrian government is doing is cutting loose an entire region, rather in the way the federal authorities in the US allowed Detroit to go bust a number of years ago.

It’s a mini-Greece going off in the heartlands of Europe. In Hypo’s case, the bail-in also threatens knock-on consequences for public bodies elsewhere, including Bayern Landesbank, a big holder of Hypo bonds which is owned by the German state of Bavaria, and the Munich based FMSW, which is again publicly underwritten. All this is just the tip of the iceberg; Europe is awash with interlinked banking and public liabilities, many of which will never be repaid and basically need to be written off. Massive creditor losses are in prospect. The European authorities had us all half convinced that Europe’s debt crisis was over. In truth, it may have barely begun.

Read more …

Good interview. Read.

Tsipras: ‘We Don’t Want to Go on Borrowing Forever’ (Spiegel)

SPIEGEL: Mr. Prime Minister, most of your European partners are indignant. They accuse you of saying one thing in Brussels and then saying something completely different back home in Athens. Do you understand where such accusations come from?
Tsipras: We say the same things in Germany as we do in Greece. But sometimes, problems can be viewed differently, depending on the perspective. (He points to his water glass.) This glass here can be described as being half full or half empty. The reality is that it is a glass filled half-way with water.

SPIEGEL: In Brussels, you have given up your demands for a debt haircut. But back home in Athens, you continue talking about a haircut. What does that have to do with perspective?
Tsipras: At the summit meeting, I used the language of reality. I said: Prior to the bailout program, Greece had a sovereign debt that was 129% of its economic output. Now, it is 176%. No matter how you look at that, it’s not possible to service that debt. But there are different ways to solve this problem: via a debt cut, debt restructuring or bonds whose payback is tied to growth. The most important thing, though, is solving the true problem: the austerity which has driven debt way up.

SPIEGEL: Are you a linguist or a politician? You told the Greeks that you got rid of the troika and sold it as a victory. But the European Commission, the International Monetary Fund (IMF) and the European Central Bank (ECB) are still monitoring your reforms. Now, they are simply called “the institutions.”
Tsipras: No, it isn’t a question of terminology. It has to do with the core of the issue. Every country in Europe has to work together with these institutions. But that is something very different than a troika that is beholden to nobody. Its officials came to Greece to strictly monitor us. Now, we are again speaking directly with the institutions. Europe has become more democratic because of this change.

SPIEGEL: What change? You still have to submit your reform plans to three “institutions” for approval.
Tsipras: The reforms won’t be approved by the institutions. They have a say in the process and establish a framework that applies to all in Europe. Previously, the situation was such that the troika would send an email telling the Greek government what it had to do. Our planned reforms are necessary, but we are deciding on them ourselves. They aren’t being forced onto us by anyone. We want to stop large-scale tax evasion and tax fraud more than anybody. Thus far, it has only been the low earners and not the wealthy that paid. We also want to make the state more efficient.

Read more …

Lots of emptiness.

Eurogroup To Consider Greek Reform Proposals Amid Scramble For Funding (Kath.)

Greece faces another tough Eurogroup summit Monday when a slew of reform proposals from Athens are to come under the microscope in Brussels, with the two sides apparently far from a compromise even as state coffers in Athens are close to emptying. Finance Minister Yanis Varoufakis is expected to face a barrage of questions from his eurozone counterparts on a series of proposals set out in an 11-page letter he sent to Eurogroup President Jeroen Dijsselbloem, which include the creation of a so-called fiscal council to generate budget savings, the revision of licensing for gaming and lotteries and the hiring of non-professionals, including students and tourists, as tax agents to help a foundering crackdown on tax evasion.

Sources suggested over the weekend that the proposals had met with skepticism from eurozone officials. In comments on Saturday on the sidelines of a conference in Venice, Varoufakis said he had received a response from Dijsselbloem. He added that Greece was keen to move forward with reforms but that the two sides must agree on “the process by which the reforms will be made more specific, implemented and evaluated so that they can be reviewed by the Eurogroup.” Varoufakis added that Greece’s reform program would be “discussed by technical teams that will convene shortly in Brussels.” Some eurozone officials appeared to be running out of patience. ECB governing council member Luc Coene said in an interview on Saturday that Greece must realize “there is no other way than to reform,” noting that Greeks had been sold “false promises.”

Read more …

“Perhaps the cupboards of the monetary bureaucrats are short a few plates and in need of a little pharmacological fine-tuning. Just saying.”

The ECB’s Lunatic Full Monty Treatment (Tenebrarum)

The belief that the market economy requires “steering” by altruistic central bankers, who make decisions influencing the entire economy based on their personal epiphanies, has rarely been more pronounced than today. Most probably it has actually never been stronger. It is both highly amusing and disconcerting that so many economists who would probably almost to a man agree that it would be a very bad idea if the government were to e.g. take over the computer industry and begin designing PCs and smart phones by committee, think that government bureaucrats should determine the height of interest rates and the size of the money supply.

We know of course that central banks are the major income source for many of today’s macro-economists, so it is in their own interest not to make any impolitic noises about these central planning institutions and their activities. Besides, most Western economists have not exactly covered themselves with glory back when the old Soviet Union still existed. Even in the late 1980s, Über-Keynesian Alan Blinder for instance still remarked that the question was not whether we should follow its example and adopt socialism, but rather how much of it we should adopt. The recent ECB announcement detailing its new “QE” program once again confirms though that there is nothing even remotely “scientific” about what these planners are doing. Common sense doesn’t seem to play any discernible role either. [..]

Leaving for the moment aside how sensible it is for the bond yields of virtually insolvent governments mired in “debt trap” dynamics to trade at less than 1.3%, one must wonder: what can possibly be gained by pushing them even lower? Does this make any sense whatsoever? Meanwhile, the ECB let it be known that it wouldn’t buy any bonds with a negative yield-to-maturity exceeding 20 basis points – the level its negative deposit rate currently inhabits as well. What a relief! What makes just as little sense is that the economic outlook presented by Mr. Draghi on occasion of his press conference was actually quite upbeat. To summarize: yields are at record lows, with about €2 trillion in European government bonds sporting negative yields to maturity. The economic outlook is said to be good.

The current slightly negative HICP rate is held to be a transitory phenomenon (it very likely will be). Needless to say, the arbitrary 2% target for “price inflation” makes absolutely no sense anyway. Not a single iota of wealth can be created by pushing prices up. Last but certainly not least, year-on-year money supply growth in the euro area has soared into double digits recently. And the conclusion from all this is that the central bank needs to boost its balance sheet by €1 trillion with a massive debt monetization program? Are these people on drugs? If not, then they should perhaps see a shrink. Perhaps the cupboards of the monetary bureaucrats are short a few plates and in need of a little pharmacological fine-tuning. Just saying.

Read more …

It’s no longer useful to view this from an investor point of view.

7 Things To Know About The ECB’s QE Game Plan (MarketWatch)

After years of discussion, months of urgent calls and weeks of preparation, the European Central Bank is about to write history—on Monday it will kick of its €1.1 trillion-euro, quantitative-easing program. Unlike its U.S., U.K. and Japanese central-bank peers, the ECB never resorted to sovereign QE at the height of the global financial crisis. Instead, it’s attempted an array of other extraordinary policy measures, including a negative deposit rate, programs to provide cheap funding to eurozone banks, and a less-powerful bond-buying program, often called “private QE,” focused on purchasing asset-backed securities and covered bonds. Now, as investors prepare for the launch of full-blown QE on March 9, here’s what we know about the program so far.

What’s the aim of the QE? Under quantitative easing, a central bank creates money electronically, which it then uses to buy securities, such as government bonds, from banks and other institutions. It’s hoped that these institutions will then use the new bank reserves to buy other assets, lowering interest rates and encouraging spending. The ECB hopes QE will revive growth and inflation in the eurozone. Despite repeated attempts to spur an economic recovery, the currency bloc is still grappling with painfully high unemployment, slow growth and negative inflation among its members.

Will the ECB buy government bonds with negative yields?Yes, but nothing that carries a yield below the ECB’s own deposit rate, which currently stands at negative 0.2%. The limit means that bonds currently yielding more than the deposit rate have room to fall further. Even before the big QE bazooka has been fired, yields for most eurozone countries have tanked. For Germany, France, Austria, Belgium, Holland and Finland borrowing costs for shorter-dated debt are now negative, meaning that bondholders essentially agree to pay issuers to hold their debt.

What will QE do to bond yields? Initially, sovereign QE and lower bond yields should march together hand in hand. As the ECB buys large quantities of government debt, bond prices should go up, which will send yields lower. On Friday, borrowing costs for Italy, Spain and Portugal dropped to record lows in anticipation of QE takeoff. However, big moves in the bond markets show much of the impact may have already been priced in. Longer-term, as the QE liquidity injection begins to work on the eurozone economy, and likely boost inflation and growth, bond yields should start to rise to reflect the stronger economy. The latest eurozone data indicate that the region may be turning a corner, leaving room for higher borrowing costs.

Read more …

London is a wasteland. It may be rich, but it’s still a wasteland. No there there.

30 Years Of A Polarised Economy Have Squeezed Out The Middle Class (Observer)

London has always been a city of extremes but the extent to which it has become polarised between rich and poor is laid bare in research that reveals a 43% decrease in middle-income households between 1980 and 2010. England is increasingly divided between the rich and the poor, with a 60% increase in poor households and a 33% increase in wealthy households. This has come at a time – 1980 to 2010 – when the number of middle-income households went down by 27%. But the trend is most marked in London, according to an analysis of census data by Benjamin Hennig and Danny Dorling of the School of Geography and the Environment at the University of Oxford.

Over the three decades, the capital has seen an 80% increase in poor households, an 80% increase in wealthy households – and a 43% decrease in middle households. Around 36% of London households are now classified as poor (up from 20% in 1980), while 37% are middle income (down from 65%). The largest%age point fall in households in the middle has been in Westminster, which saw its middle reduce from nearly three-quarters of all households to just one-third. The largest%age-point increase in wealthy households has been in Richmond-upon-Thames, where more than half of households are now wealthy, compared with a fifth in 1980. In contrast, in Newham, almost one in two households is now poor.

The researchers have drawn up maps of England according to wealth, described by Dorling as “fancy pie charts”. The polarising of wealth has been exacerbated in recent years, with economic growth having been slower than had been hoped, and wages in the middle failing to rise in parallel with the recovery. The economic divide between the beneficiaries of the property bubble and non-homeowners also continues to widen in the country as a whole, with upward pressure on land values. Dorling said: “This analysis shows that England is becoming more polarised, with an increase in households that are poor and those that are wealthy. The number of households in poverty has jumped by 60% since 1980, meaning that now almost three in 10 are poor.

Read more …

So more PBOC QE too?

Foreign Banks Tighten Lending Rules For China State-Backed Firms (Reuters)

Some banks are adopting stricter lending criteria for China’s state-owned enterprises (SOEs), demanding collateral from some companies they used to deem as safe as government debt, as Beijing tries to reform its bloated firms and the economy slows. Singapore’s DBS Group, which recently suffered a loss on a bad loan to an SOE-related firm it had assessed as risk-free, plans to launch a “decision grid” to assess the creditworthiness of SOEs, according to draft internal risk guidelines reviewed by Reuters. A banker at Taiwan’s Chang Hwa Commercial Bank said that from the beginning of this year his bank would only lend to state-owned Chinese companies that provide collateral, in recognition that SOEs were no longer risk free.

Such changes in policy suggest some foreign banks are preparing for a rise in defaults in the world’s second-largest economy, which is growing at its slowest pace in a quarter of a century and where the government is trying to make the state sector more efficient.
DBS will now lend more conservatively to SOEs seen as receiving less government support, as China plans to prioritize SOEs in strategic sectors. The January-dated DBS document said: “Not all SOEs receive the same degree of government support. It is our further belief that the differentiation of such support will widen in the future as the government continues to pursue market economy.” DBS will now divide SOEs into tiers according to their likely level of government support, with subsidiaries considered more risky than top-level holding companies.

Group companies that are not consolidated into the parent SOE’s financial statements will be evaluated as an ordinary borrower, the decision grid shows. DBS effectively acknowledges that lenders can no longer take for granted implicit support from above. “Compared to ordinary corporates, implicit support obtained from the parents of SOEs are subject to higher risks because of the risk of policy and people changes,” the document said. A DBS spokeswoman said: “It is still business as usual for us in China. With slower regional economic growth, we continue to be disciplined and watchful of risks in all the markets we operate in..”

Read more …

C’mon, admit it, you were due for a good laugh.

China’s February Exports Surge 48.3% (CNBC)

China’s exports surged 48.3% on year in February, sharply above analysts’ forecasts, potentially signaling stronger economic growth for its trade partners. Imports fell 20.5% for the period, according to data from China’s customs department. A Reuters poll had forecast exports would rise 14.2% and imports would fall 10%. For January and February combined – a common metric to help smoothe distortions from the Lunar New Year holiday period – exports rose 15% from a year earlier, while imports declined 20.2%. “The demand from the advanced economies bodes well,” ANZ said in a note Sunday, citing data showing shipments to the U.S. and European Union rose 40.3% and 36.6% on-year respectively.

But the bank noted that the jump in exports could be due to a base effect. “The February 2014 figures were extremely low as Chinese authorities cracked down the round-tripping trade flows,” it said. “We still see strong headwinds facing China’s exports this year,” ANZ said, citing weak export order PMI data. ANZ attributed the decline in imports to weak commodity demand compounded by sharp drops in commodity prices, citing as an example the 45.4% on year drop in the value of iron-ore imports, although the iron-ore import volume only fell 0.9%. As well, “Chinese commercial banks have significantly tightened the trade financing facilities for commodity traders,” ANZ said.

Read more …

“..it is not likely that she came to Baku with positive intentions, or even with a positive image of the country in her mind.”

Azerbaijan Should Be Very Afraid of Victoria Nuland (GR)

The US’ Assistant Secretary of State for European and Eurasian Affairs, Victoria Nuland, visited Baku on 16 February as part of her trip to the Caucasus, which also saw her paying stops in Georgia and Armenia. While Azerbaijan has had positive relations with the US since independence, they’ve lately been complicated by Washington’s ‘pro-democracy’ rhetoric and subversive actions in the country. Nuland’s visit, despite her warm words of friendship, must be look at with maximum suspicion, since it’s not known what larger ulterior motives she represents on behalf of the US government. [..]

Given the ideological context in which Nuland likely sees eye-to-eye on with her husband, plus her experience in instigating the Color Revolution in Ukraine, it is not likely that she came to Baku with positive intentions, or even with a positive image of the country in her mind. This is all the more so due to the recent scandal over Radio Free Europe/Radio Liberty. The US-government-sponsored information agency was closed down at the end of December under accusations that it was operating as a foreign agent. While the US has harshly chided the Azeri government for this, at the end of the day, it remains the country’s sovereign decision and right to handle suspected foreign agents as it sees fit. Azerbaijan’s law is similar to Russia’s, in that entities receiving foreign funds must register as foreign agents, and interestingly enough, both of these laws parallel the US’ own 1938 Foreign Agents Registration Act (FARA).

So why does the US feel that it reserves the sole right to register foreign agents and entities, and if need be, identify and punish those that are acting in the country illegally, but Azerbaijan is deprived of this exercise of sovereignty? The reason is rather simple, actually – it’s the US that is the most likely to use these foreign agents to destabilize and potentially overthrow governments (as in Ukraine most recently), whereas Azeri agents in America, should they even exist, are nothing more than an administrative nuisance incapable of inflicting any real harm on the authorities. This double standard is at the core of the US’ relations with all countries in the world, not just Azerbaijan, but it’s a telling example of the power and leverage Washington attempts to hold over Baku, which is seen most visibly by the blistering criticism leveled on the government after Radio Free Europe/Radio Liberty’s closing in compliance with the law.

Read more …

Too little too late. Fait accompli.

EU Won’t Be Pushed Into Confrontation Over Ukraine – Foreign Policy Chief (RT)

The EU is resisting calls from hotheads to supply arms to Ukraine, saying it won’t be pulled into a confrontation with Russia. Europeans cite the progress in implementing a ceasefire in eastern Ukraine between Kiev and local rebels. The idea of providing lethal aid to Kiev is popular among many NATO officials and American politicians. US House Speaker John Boehner and a bipartisan group of top lawmakers called on President Barack Obama to deliver the weapons. But Europeans are opposing the move, which would likely escalate tensions with Russia. “The European Union today is extremely realistic about developments in Russia. But we will never be trapped or forced or pushed or pulled into a confrontative [sic] attitude,” the EU’s Foreign Policy Chief Federica Mogherini told the media on Friday, following an informal meeting of EU foreign ministers in Riga, Latvia.

“We still believe that around our continent – not only in but around – cooperation is far better than confrontation. We still argue for that,” she added. Austrian Foreign Minister Sebastian Kurz said the EU’s goal in Ukraine is “a ceasefire, not an escalation.” Germany has been among the most vocal critics of sending arms to Ukraine and now German officials question the assessment of the situation in the country voiced by Kiev armament pundits. “The statements [on Ukraine] from our source do not fully coincide with the statements made by NATO and the US,” German FM Frank-Walter Steinmeier said after the conference. “We are interested in not allowing it to grow into a misunderstanding.” The German Spiegel magazine reported on Saturday that Chancellor Angela Merkel’s government suspects the US and NATO of trying to derail the EU’s mediation effort in Ukraine.

The Minsk ceasefire agreement between Kiev and rebels in eastern Ukraine was brokered last month by Germany, France and Russia. So far, it’s mostly holding, with both parties pulling some of their heavy weapons back from the front line, and OSCE monitors reporting a significant reduction in violence. The EU says it wants to increase the number of OSCE observers on the ground, doubling its current ceiling of 500. “The main point is obviously working to increase the number of selected and skilled people that can do the job,” Mogherini said. The more observers the tougher it would be to violate the conditions of the Minsk agreement with impunity. Kiev and its foreign backers, particularly in Washington, accuse Russia of propping up the rebel forces with weapons and troops. Moscow insists that it has no involvement in the armed conflict and has only delivered humanitarian aid to the ravaged areas.

Read more …

“86% of the respondents approve of Vladimir Putin as Russia’s president. When asked to name five or six politicians or government officials they trust, 59% responded: ”Putin”.”

Why Do Russians Still Support Vladimir Putin? (New Statesman)

The news of the assassination of Boris Nemtsov, a Russian opposition politician, dominated the news this weekend. It was possible to imagine – just for a day or two – that the charismatic Boris Nemtsov, who first entered the national political arena in Russia back in the Yeltsin days, had been a prominent figure without whom the opposition would struggle to have a say against Kremlin. Unfortunately, the truth is that Nemtsov was hardly a force to be reckoned with. However open his position on Putin was and however brave his last interview to the Moscow radio station Echo Moskvy was, just hours before his death, Boris Nemtsov was not important. Like any other opposition leader in Russia, he was a scribble on the margin of current affairs. The overwhelming majority of the Russian population supports the country’s president, Vladimir Putin.

A recent poll, conducted between 20-23 February 2015 among 1,600 Russians aged 18 or more in 46 different regions of Russia by an independent Russian not-for-profit market research agency Levada Centre for Echo Moskvy radio station, found that 54% of the population agreed that “[Russia] is moving in the right direction”. 86% of the respondents approve of Vladimir Putin as Russia’s president. When asked to name five or six politicians or government officials they trust, 59% responded: ”Putin”.

Let’s put aside the possibility of rigged polls because there is little to suggest Putin’s popularity is fake. Putin is respected, if not revered. He is referred to as batyushka, the holy father. Many Russians are particularly upset and angry about Nemtsov’s murder because western fingers are pointing at Putin. In their opinion, Nemtsov was most likely killed as a provocation to destabilise Russia and fuel hostility between Kremlin and the west. “With all due respect to the memory of Boris Nemtsov, in political terms he did not pose any threat to the current Russian leadership or Vladimir Putin, said presidential press secretary Dmitriy Peskov. “If we compare popularity levels, Putin’s and the government’s ratings and so on, in general Boris Nemtsov was just a little bit more than an average citizen.”

Read more …

Who’s “our son of a bitch“?

The Dark Undercurrents Of The War In The Ukraine (Saker)

The situation in the Ukraine is more or less calm right now, and this might be the time to step back from the flow of daily reports and look at the deeper, underlying currents. The question I want to raise today is one I will readily admit not having an answer to. What I want to ask is this: could it be that one of the key factors motivating the West’s apparently illogical and self-defeating desire to constantly confront Russia is simply revanchism for WWII? We are, of course, talking about perceptions here so it is hard to establish anything for sure, but I wonder if the Stalin’s victory against Hitler was really perceived as such by the western elites, or if it was perceived as a victory against somebody FDR could also have called “our son of a bitch“. After all, there is plenty of evidence that both the US and the UK were key backers of Hitler’s rise to power (read Starikov about that) and that most (continental) Europeans were rather sympathetic to Herr Hitler.

Then, of course and as it often happens, Hitler turned against his masters or, at least, his supporters, and they had to fight against him. But there is strictly nothing new about that. This is also what happened with Saddam, Noriega, Gaddafi, al-Qaeda and so many other “bad guy” who began their careers as the AngloZionists’ “good guys”. Is it that unreasonable to ask whether the western elites were truly happy when the USSR beat Nazi Germany, or if they were rather horrified by what Stalin had done to what was at that time the single most powerful western military – Germany’s? [..] for the western elites, [..] they must have known that their entire war effort was, at most, 20% of what it took to defeat Nazi Germany and that those who had shouldered 80%+ were of an ideology diametrically opposed to capitalism. Is there any evidence of that fear? I think there is and I already mentioned them in the past:

Plan Totality (1945): earmarked 20 Soviet cities for obliteration in a first strike: Moscow, Gorki, Kuybyshev, Sverdlovsk, Novosibirsk, Omsk, Saratov, Kazan, Leningrad, Baku, Tashkent, Chelyabinsk, Nizhny Tagil, Magnitogorsk, Molotov, Tbilisi, Stalinsk, Grozny, Irkutsk, and Yaroslavl.

Operation Unthinkable (1945) assumed a surprise attack by up to 47 British and American divisions in the area of Dresden, in the middle of Soviet lines.This represented almost a half of roughly 100 divisions (ca. 2.5 million men) available to the British, American and Canadian headquarters at that time. (…) The majority of any offensive operation would have been undertaken by American and British forces, as well as Polish forces and up to 100,000 German Wehrmacht soldiers.

Operation Dropshot (1949): included mission profiles that would have used 300 nuclear bombs and 29,000 high-explosive bombs on 200 targets in 100 cities and towns to wipe out 85% of the Soviet Union’s industrial potential at a single stroke. Between 75 and 100 of the 300 nuclear weapons were targeted to destroy Soviet combat aircraft on the ground.

But the biggest proof is, I think, the fact that none of these plans was executed, even though at the time the Anglosphere was safely hidden behind its monopoly on nuclear weapons (and have Hiroshima and Nagasaki not been destroyed in part to “scare the Russians”?). And is it not true that the Anglos did engage in secret negotiations with Hitler’s envoys on several occasions? (The notion of uniting forces against the “Soviet threat” was in fact contemplated by both Nazi and Anglo officials, but they did not find a way to make that happen.) So could it be that Hitler was, really, their “son of a bitch”?

Read more …

“We support sanctions that bring the other side to the negotiation table.. But we are against sanctions that are imposed simply because someone is angry.”

‘Give Peace A Chance, Decide Sanctions Later’: EU Rethinks Russia (RT)

The latest EU meeting has shown that many of its members are in no rush to extend the sanctions which were imposed on Russia last year following a US example, or to exert any more pressure on Moscow, as long as the Minsk ceasefire agreement is holding. Most foreign ministers at the EU two-day meeting in the Latvian capital expressed hopes that the latest Minsk agreement would be a success, and there would be no need to impose further sanctions on Russia. The meeting had a format of an informal discussion, where the ministers touched the topics of the Minsk agreements and the OSCE mission in Ukraine, as well as the possible stepping up of pressure on Russia to “promote peace.”

Scheduled ten days before an official summit in Brussels, the meeting has shown that the EU can’t yet agree even on the automatic extension of existing sanctions – a move that some of the hawkish states have been actively promoting. “In my opinion, we must not make any other steps, we have to give peace a chance. The extension could take place, but only if there is no improvement of the situation,” Spanish FM Jose Manuel Garcia-Margallo said, expressing his views after the meeting , according to Russian news agency RIA Novosti. The Spanish FM is heading to Moscow, during which he will not only discuss the Ukrainian crisis, but will also meet with the Russian Energy minister.

Meanwhile, Italian FM Paolo Gentiloni told reporters the he sees “encouraging signals” on the ground in eastern Ukraine, and so “at the moment we don’t need either new sanctions or automatic renewals.” Austrian Foreign Minister Sebastian Kurz shared the views of his Italian counterpart, saying that there is a “glimpse of hope” following the Minsk agreements: “We should do everything now to improve the situation and decide later whether that improvement really happened and we can reduce the sanctions, or, if we have to, extend them,” Kurz said. Greece has also spoke out against any new sanctions as long as Russia supports the Minsk agreements, with Greek Foreign Minister Nikos Kotzias saying the Greek experience suggests that “not every sanction is constructive” and can succeed. “We support sanctions that bring the other side to the negotiation table,” Kotzias told German ARD. “But we are against sanctions that are imposed simply because someone is angry.”

Read more …

Wait! Where have we heard this before? “Owner will throw in a brand new car..” “Just pick your favorite colour.”

Layoffs And Empty Streets As Australia’s Boom Towns Go Bust (Reuters)

When Probo Junio got a visa to work in Australia, he thought he had won a ticket to the good life. In 2013, the 45-year-old boilermaker left his hometown of Cebu in the Philippines, where he was getting paid about $10 a day, to work in Karratha in Western Australia for $30 an hour. Enough to support his relatives and build a new life Down Under. What Junio didn’t expect was that Australia’s booming resources industry would go bust less than two years later, taking his job, and leaving him just 60 days to find work or go home. “It’s very difficult because most of the companies don’t want 457 visa holders,” he said, referring to temporary permits for skilled workers.Across the country, people like Junio are falling victim to downsizing. Jobs, once plentiful and well paid, are scarce.

Real estate prices in boom towns are sinking and even the notoriously high coffee prices in mining capital Perth have levelled off at under $4. Prices of iron ore and coal, the country’s two biggest export earners, have plunged during the last two years amid falling demand from China, in the wake of its economic slowdown. Just a few years ago, foreign workers were flooding into Australia, lured by huge pay as the resources industry scrambled to fill positions. Truck driving and cooking jobs offering $100,000 a year made headlines abroad. But those workers, like Junio, are now hard-pressed to find work, especially if they are on temporary visas. Even permanent residents have to take lower pay. “There is reality coming into the marketplace about salaries,” said John Downing, who runs global resources recruiting firm Downing Teal, adding that salary expectations have fallen 10% to 25%.

“For Lease” signs are everywhere in West Perth, the headquarters of many mining, oil and gas companies. “You could shoot a cannon down those streets,” said resources analyst Peter Strachan. “There’s nobody there.”Commercial vacancy rates in the city are near a 20-year high of 15% as resources companies downsize or shut down, said Joe Lenzo, of the Property Council of Australia. The real estate market has also been hit in the coal country of Queensland, across the continent. “Owner will throw in a brand new car,” read advertisements for houses in the coal-mining town of Moranbah. “Just pick your favorite colour.”

Read more …

There’s something very positive about South America.

Venezuela To Get South American Help For Food Crisis (BBC)

Foreign ministers from 12 South American nations gathering in Caracas have promised to help Venezuela overcome an ongoing shortage of food, medicine and other products. The regional Unasur bloc agreed with President Nicolas Maduro to provide items that have gone missing from many Venezuelan supermarkets. The shortage of staples has contributed to popular discontent. Unasur highlighted the importance of safeguarding democratic stability. “The idea is to get all the countries to support the distribution of staples,” said Ernesto Samper, Secretary-General of Unasur (Union of South American Nations). “We will work together with the Venezuelan authorities to strengthen the distribution networks in our countries so they help Venezuela,” said Mr Samper.

He criticised recent anti-government protests in Venezuela that descended into violence. The opposition must “express its opinions in a democratic, peaceful and lawful manner,” said Mr Samper. The Unasur ministers will meet opposition leaders and government officials in the next few days to seek guarantees that Venezuela will be able to hold free and fair elections later this year. Opposition leader Henrique Capriles told the AFP news agency on Tuesday that Mr Maduro could cancel the vote, which is scheduled for the second half of this year. “The government had never had such a large deficit [in the polls] heading into an election. Now it does. How does it change that? It rigs the game,” said Mr Capriles. Mr Maduro said the elections would go ahead as planned.

Read more …

“For us, water is [now] more important than oil.”

Why Fresh Water Shortages Will Cause The Next Great Global Crisis (Guardian)

Water is the driving force of all nature, Leonardo da Vinci claimed. Unfortunately for our planet, supplies are now running dry – at an alarming rate. The world’s population continues to soar but that rise in numbers has not been matched by an accompanying increase in supplies of fresh water. The consequences are proving to be profound. Across the globe, reports reveal huge areas in crisis today as reservoirs and aquifers dry up. More than a billion individuals – one in seven people on the planet – now lack access to safe drinking water. Last week in the Brazilian city of São Paulo, home to 20 million people, and once known as the City of Drizzle, drought got so bad that residents began drilling through basement floors and car parks to try to reach groundwater.

City officials warned last week that rationing of supplies was likely soon. Citizens might have access to water for only two days a week, they added. In California, officials have revealed that the state has entered its fourth year of drought with January this year becoming the driest since meteorological records began. At the same time, per capita water use has continued to rise. In the Middle East, swaths of countryside have been reduced to desert because of overuse of water. Iran is one of the most severely affected. Heavy overconsumption, coupled with poor rainfall, have ravaged its water resources and devastated its agricultural output. Similarly, the United Arab Emirates is now investing in desalination plants and waste water treatment units because it lacks fresh water.

As crown prince General Sheikh Mohammed bin Zayed al-Nahyan admitted: “For us, water is [now] more important than oil.” The global nature of the crisis is underlined in similar reports from other regions. In south Asia, for example, there have been massive losses of groundwater, which has been pumped up with reckless lack of control over the past decade. About 600 million people live on the 2,000km area that extends from eastern Pakistan, across the hot dry plains of northern India and into Bangladesh, and the land is the most intensely irrigated in the world. Up to 75% of farmers rely on pumped groundwater to water their crops and water use is intensifying – at the same time that satellite images shows supplies are shrinking alarmingly.

Read more …

“I look at . . . so many forests, all cut, that have become land . . . that can [no] longer give life..”

The Francis Miracle: Inside The Transformation Of The Pope And The Church (TIME)

It was probably inevitable that the first pope named Francis—inspired by a saint who preached to birds and gave pet names to the sun and the moon—has turned out to be a strong environmentalist. In fact, Francis has said that concern for the environment is a defining Christian virtue. (The young Jorge Bergoglio trained as a chemist, so he has a foundation to appreciate the scientific issues involved.) This element of the social gospel bubbled to the surface as early as his inaugural mass, when Francis issued a plea to “let us be ‘protectors’ of creation, protectors of God’s plan inscribed in nature, protectors of one another and of the environment.” St. Francis’s imprint on this pope is clearly strong. In unscripted comments during a meeting with the president of Ecuador in April 2013, he said, “Take good care of creation. St. Francis wanted that.

People occasionally forgive, but nature never does. If we don’t take care of the environment, there’s no way of getting around it.” The two previous popes were also environmentalists. The mountain-climbing, kayaking John Paul II was a strong apostle for ecology, once issuing an almost apocalyptic warning that humans “must finally stop before the abyss” and take better care of nature. Benedict XVI’s ecological streak was so strong that he earned a reputation as “the Green Pope” because of his repeated calls for stronger environmental protection, as well as gestures such as installing solar panels atop a Vatican audience hall and signing an agreement to make the Vatican Europe’s first carbon-neutral state. Francis is carrying that tradition forward.

Among other things, he told French President François Hollande during a January 2014 meeting that he is working on an encyclical on the environment. (An encyclical is considered the most developed and authoritative form of papal teaching.) The Vatican has since confirmed that Francis indeed intends to deliver the first encyclical ever devoted entirely to environmental issues. In a July 2014 talk at the Italian university of Molise, Francis described harm to the environment as “one of the greatest challenges of our times.” It’s a challenge, he said, that’s theological as well as political in nature. “I look at . . . so many forests, all cut, that have become land . . . that can [no] longer give life,” the pope continued, citing South American woodlands in particular. “This is our sin, exploiting the Earth. . . . This is one of the greatest challenges of our time: to convert ourselves to a type of development that knows how to respect creation.”

Read more …

Feb 222015
 
 February 22, 2015  Posted by at 11:22 am Finance Tagged with: , , , , , , ,  12 Responses »


DPC “Car ferry Michigan Central turning in ice, Detroit River” 1900

Yellen Confronts Economists’ Ignorance (Bloomberg)
How The Eurozone Could Tear Apart (Telegraph)
Greece, The Euro And Solomon’s Wisdom (Kathimerini)
Greece Says Eurozone Deal Won Time As Cash Bled From Banks (Reuters)
The Real Battle Over Greece Still Lies Ahead (Bloomberg)
From Greek Warriors To Battered Soldiers – In A Week (Observer)
Germany Set To Approve Greek Deal If Promises Met: Merkel Ally (Reuters)
What Would Happen if Greece Leaves the Euro Zone? (Spiegel)
The 1 Reason Pope Francis Is The World’s Top Capitalist (Paul B. Farrell)
Russians Rally Against Kiev ‘Coup’ (BBC)
Poroshenko Bruised By Ukraine Army Retreat (BBC)
NATO Must Prepare For Russian Blitzkrieg, Warns UK General (FT)
Kerry Warns of More Russia Sanctions as Ukraine Simmers (Bloomberg)
Ousted Ukraine Leader Aims To Return As Rockets Threaten Peace Plan (Observer)
Ukraine, Rebels Swap Dozens Of Prisoners (Reuters)
Modi Bets On GMO Crops For India’s Second Green Revolution (Reuters)

What were ya thinking?

Yellen Confronts Economists’ Ignorance (Bloomberg)

Productivity is probably the most important measure of economic health that policy makers know the least about. Its pace will help determine how soon Federal Reserve Chair Janet Yellen and her colleagues increase interest rates and how far rates ultimately will rise. A quicker advance would argue for a later lift-off because the economy would have more room to run before bumping up against capacity constraints. It also eventually would require a higher ending point to prevent the more-vibrant expansion from overheating. Slower productivity would call for the opposite strategy. The trouble, according to former Fed Vice Chairman Alan Blinder, is that economists – including those at the Fed – don’t have a good idea of how fast productivity will grow in the next few years.

The long-run trend is “hugely important,” but “it can take years” to recognize any changes, he said in an interview. Yellen will lay out the central bank’s views of the economy and policy when she testifies before Congress next week. At their Jan. 27-28 meeting, officials discussed the timing and pace of potential rate increases. Many were inclined to keep the benchmark federal fund rate near zero “for a longer time,” according to minutes of the gathering released Feb. 18. John Fernald, a senior research adviser at the Federal Reserve Bank of San Francisco, pegs the trend growth rate of productivity at 1.8% a year for U.S. businesses and 2.1% for the economy as a whole.

Such projections are consistent with the Fed raising rates this year for the first time since 2006, said Dale Jorgenson, a professor at Harvard University in Cambridge, Massachusetts, and former chairman of its economics department. The margin of error around Fernald’s forecast is wide, though, as he is the first to acknowledge. “There’s basically an 80% chance over the next 10 years that productivity growth will average between 1 and 3%,” the Fed official said. Productivity measures the overall efficiency of the economy and matters beyond the central bank. It governs how fast the economy can expand, how much companies can earn and pay their workers, and how much the government can increase its budget. That is why economists put in a lot of time trying to parse it out.

Read more …

a 10000 ways.

How The Eurozone Could Tear Apart (Telegraph)

The eurozone was never designed with an exit plan in mind. The Maastricht Treaty’s 112 pages make no mention of a way for a country to pull out of the euro project. At the height of the eurozone crisis in 2011 and 2012, policymakers refused to countenance the idea of a splintered euro bloc. When pressed on the issue in late 2011, Mario Draghi, the president of the ECB, would only say the possibility “is not in the treaty”. He was discussing the chance of a Greek exit – or Grexit – from the euro, a risk that has come back to haunt the project’s architects in recent weeks. The rise of populist anti-austerity parties across the continent – including Syriza in Greece – threatens to tear apart the bloc. Last week analysts warned that the risk of a euro breakup was greater than at the height of the last crisis. The odds on a Grexit offered this Friday – before a deal between Greece and its creditors was struck – gave it a more than a one-in-three chance by the end of the year.

A breakup of a currency union such as this would have been without recent precedent. The classic example of a union breaking apart – in the absence of violent conflict – is the Austro-Hungarian empire in 1918. It provides a crucial lesson: changes in currency need surprise. Anyone with assets will attempt to move them to safe havens, wary of a sharp devaluation. To work well, as few people as possible should know about the planned switch. Michael Spencer, an economist, told NPR’s Planet Money that while in principle it can be done: “It is much more likely that people see this coming.” The most likely suspects for a euro exit all have weaker economies than the area as a whole. Wary that whatever new currency is issued is likely to suffer a sharp devaluation, anyone with assets will attempt to move them to safe havens. To work well, as few people as possible should know about the planned switch.

In 1918, it became apparent that a breakup was imminent. Mr Spencer said that people took “boxcar loads of currency” across borders to where, upon conversion, their money would have greater worth. The process of conversion then involved stamping currency with ink, as almost all money was held in a physical form. Now, most savings are held electronically, and could be converted in an instant. So as long as word doesn’t get out, most cash can be dealt with. If it does, then capital can flee even more quickly than before, as shuffling currency to a different currency no longer relies upon the maximum speed of a horse. In Greece this deposit exodus has already begun. Capital outflows have reached €1bn a day. JP Morgan warned a week ago that capital flight would leave lenders without collateral within 14 weeks. By Friday, fears that a compromise would not be found led deposits to fall by a further €1bn in just two days, Reuters said citing sources.

Read more …

“It doesn’t take the wisdom of Solomon to see that the defeat of one is the defeat of all.”

Greece, The Euro And Solomon’s Wisdom (Kathimerini)

Today we will see who cares more for the future of the Greek people and for the eurozone’s stability, and which government places its own prestige above all else. Will Athens give more ground? Will Berlin remain unyielding? The 19 finance ministers of the Eurogroup face a paradox: they know that what is good for the Greeks is good for the common currency and vice versa – but the clumsy handling of the issue by the protagonists of the drama has created division which harms both Greece and the euro. How can the rift be bridged so that Greece can return to its efforts for economic recovery and Europe can move toward greater union? The Greek government has covered a lot of ground from its initial promises to halve the public debt, reject the austerity program in whole, roll back many reforms and turn its back on the troika of creditors.

On Wednesday, Athens asked the Eurogroup for a six-month extension of the aid agreement and accepted many of its partners’ demands – to the point that this was widely seen as capitulation. Of course, the proposal was murky on several points, so that the government could save face but also implement at least parts of its policy. This was quickly noted by the German Finance Ministry, which rejected the Greek proposal. It is significant that Greece made major concessions whereas Germany remained fixed in its position. We could argue, of course, that Greece had to cover a greater distance because it had strayed so far from the bailout agreement it had reached with its partners, whereas Germany was simply insisting on the restoration of order. But it is also clear that Berlin needs to show some flexibility in order to achieve progress – given the weaknesses, mistakes and many injustices of the program implemented in Greece.

The rigid imposition of the agreements (with only some unclear promises of future flexibility in the program) mirrors the initial rigidity of the Greek government, which put its utopian promises above the need to come to an honorable compromise with its partners. Athens started off by drawing red lines across existing agreements and commitments, presenting any effort at compromise as an effort to blackmail it into surrender. Fortunately, the German “no” did not derail today’s Eurogroup meeting and there is still some hope for an agreement that will allow both sides to work toward the stability of the Greek economy and of the euro. If both sides move a little closer they may just achieve this. Then Greece will be able to turn toward problems that need urgent attention and the EU will have shown that with some flexibility – in a show of leadership and not vengeance – it can keep alive the spirit of communal progress. It doesn’t take the wisdom of Solomon to see that the defeat of one is the defeat of all.

Read more …

The Greek economy and the Greek government weren’t strangled, as was perhaps the original political plan by centers abroad and within the country..”

Greece Says Eurozone Deal Won Time As Cash Bled From Banks (Reuters)

Greece’s left-wing government insisted on Saturday it had avoided being “strangled” by the eurozone, which agreed in principle to extend a financial rescue deal as nervous savers pulled huge sums from Greek banks. Athens said the deal struck late on Friday in Brussels should calm Greeks who had feared capital controls might be imposed as a prelude to leaving the euro. But some weary voters questioned what their new leaders had achieved in weeks of testy exchanges with euro zone hardliners led by EU paymaster Germany. After often ill-tempered negotiations, Greece secured late on Friday a four-month extension to euro zone funding, which will avert bankruptcy and a euro exit, provided it comes up with promises of economic reforms by Monday.

“We won time,” said government spokesman Gabriel Sakellaridis. “The Greek economy and the Greek government weren’t strangled, as was perhaps the original political plan by centers abroad and within the country,” he told Mega TV, without naming the euro zone hawks who forced the government into a climbdown at the Brussels talks. Prime Minister Alexis Tsipras has won wide support at home for what Greeks see as their leaders finally getting tough instead of going to Brussels cap in hand and taking orders from Berlin. But it was also under intense pressure at home. About €1 billion flooded out of Greek bank accounts on Friday, due to savers’ fears that the talks would fail and Athens might have to halt such withdrawals or prepare to reintroduce a national currency.

This added to an estimated €20 billion euros that Greeks have withdrawn since December, when it became clear that the radical SYRIZA party of Tsipras was likely to win power in last month’s parliamentary elections. Faced with the risk of a chaotic bank run on Tuesday after a long holiday weekend, Finance Minister Yanis Varoufakis stressed that the deal should calm savers. “It is quite clear that the reason why we had a deposit flight was because every day, even before we were elected, Greeks were being told that if we were elected and we stayed in power for more than just a few days the ATMs will cease functioning,” he told reporters in Brussels on Friday. “Today’s decision puts an end to this fear, to the scaremongering.”

Read more …

“Syriza’s “red lines won’t be violated, that’s why they’re called red.”

The Real Battle Over Greece Still Lies Ahead (Bloomberg)

Greek Prime Minister Alexis Tsipras claimed an initial victory after emergency talks with creditors gave the country a reprieve from the prospect of insolvency, as he began the task to sell the deal domestically. “Yesterday we won a battle, but not the war as the difficulties, the real difficulties, not only those related to the discussions and the relationship with our partners, are ahead of us,” Tsipras said in a televised speech on Saturday. Talks in Brussels between officials from the 19 euro-area countries concluded late Friday with an agreement to extend bailout funds to Greece for four months. Tsipras’s government must submit a list of economic measures it will undertake on Monday. Finance chiefs will then decide whether his proposals go far enough.

While the agreement potentially frees up some money to meet at least some of the pledges made by Tsipras before last month’s election, the outcome may still prove politically bruising for him. Even after last night’s agreement, his policies are subject to validation by the International Monetary Fund, the European Central Bank and the European Commission, the institutions collectively known as the troika from which Tsipras vowed to break free. “While Greece secured some ability to rewrite the terms of its current program, the sense is that the combination of pressure on its banking sector and on state cash flows has forced the bulk of concessions to come from their side,” Malcolm Barr, economist at JPMorgan Chase & Co., said in a client note. “This may place some degree of strain within Syriza itself.”

Tsipras said the deal “cancels austerity” and pledges by the previous government to cut wages, pensions and public sector employees and increase sales taxes. The list of reforms will be “based on the current arrangement,” the Eurogroup meeting of finance ministers said in a statement. That will include corruption fight, public administration and tax system changes, government spokesman Gabriel Sakellaridis said on Mega TV on Saturday. Syriza lawmakers would approve the list of measures even if they didn’t fully meet pre-election promises, George Stathakis, Greek minister for economy, shipping, tourism and infrastructure, said in an interview in Kathimerini. Still, Environment and Energy Minister Panagiotis Lafazanis said in an interview with Real News that Syriza’s “red lines won’t be violated, that’s why they’re called red.”

Read more …

Not getting the idea.

From Greek Warriors To Battered Soldiers – In A Week (Observer)

Greece’s people have undergone hardship on a scale not seen in a developed country since the 1930s. At the same time, Athens was effectively forced to subcontract economic policymaking to the troika, with its budgets pored over line by line by unelected foreign officials. And as the Jubilee Debt Campaign recently pointed out, more than half of the bailout funds went not to keep schools and hospitals open, but to repay the private sector speculators, in many cases German and French banks, that lent recklessly to Greece in the runup to the crisis, charging the government in Athens little more to borrow at the time than they asked of the parsimonious Germans. Tsipras and Varoufakis were right to question the virtue of austerity as a catalyst for economic recovery, too. The ECB’s recent decision to unleash a €60bn-a-month quantitative easing programme underlines the fact that demand in the eurozone economies remains weak and the recovery fragile.

Yet once Varoufakis and his colleagues were in the harsh spotlight of the world’s media in Brussels, they appeared ill-equipped for the brutal battle. For one thing, they appeared to give away many of their strongest cards almost as a starting point. Debt forgiveness, much talked about during the campaign, seemed to be off the agenda; “Grexit”, which should have been Varoufakis’s nuclear option, seemed ruled out from the start. While extremely risky, default and devaluation could have offered the Greek economy a re-set; and the market chaos that would inevitably follow would exact a high price for other eurozone members. Varoufakis should surely have left that possibility hanging like a sword over last week’s talks, instead of insisting in his long-winded introductory remarks – later leaked to the press – that “Greece is a permanent and inseparable member of the European Union and our monetary union”.

Perhaps it was a tactic, but there was a lot of bluster and very few numbers in Greece’s initial proposals. Wolfgang Schäuble also has a democratic mandate and he was always going to want to see how Athens would make the sums add up. In the end, when Friday night’s deal was announced, it was hard to see what Varoufakis had salvaged. Admittedly no one used the word “bailout”, instead referring to “the Master Facility Agreement”. But Greece will accept the supervision of the troika (without calling it such), submitting detailed reform proposals for review by the end of Monday; it will refrain from “rowing back” on reforms where they might endanger “fiscal sustainability”; and it will seek an extension of financial support, “on the basis of the conditions of the current arrangement”. What’s more, instead of the six-month bridging loan it had asked for, it will get just four months’ grace.

Read more …

Merkle will prove to be useless in peacetime.

Germany Set To Approve Greek Deal If Promises Met: Merkel Ally (Reuters)

The German parliament is likely to approve a four-month extension to euro zone funding for Greece, on condition Athens presents a list of reforms as promised, a senior ally of German Chancellor Angela Merkel was quoted as saying. “The Greeks have to do their homework now,” Volker Kauder, leader of Merkel’s conservatives in parliament, told Welt am Sonntag newspaper, according to excerpts of an interview published on Saturday. “Then, an extension of the aid program can be approved by the German Bundestag.” Kauder added: “Greece has finally realized that it cannot turn a blind eye to reality.”

Greece late on Friday secured its four-month funding extension, averting bankruptcy and a euro exit, provided it comes up with promises of economic reforms by Monday. However, Greek Prime Minister Alexis Tsipras said on Saturday the agreement struck with euro zone ministers cancelled austerity commitments made to international creditors by a previous conservative-led government. Other German conservative lawmakers welcomed the agreement cautiously, but also stressed there was still work to do. “We’ve taken an important step forward, but we’ve not reached the finishing line yet,” said Ralph Brinkhaus, deputy parliamentary floor leader for Merkel’s conservatives.

Read more …

“..companies, banks and governments all prepare for the kind of worst case scenario that isn’t even addressed in euro-zone statutes..”

What Would Happen if Greece Leaves the Euro Zone? (Spiegel)

On Wednesday of this week, 30 top managers at a large German bank all received a text message and an email at the exact same time. A short time later, their mobile phones rang with an automated voice giving them all passwords and a number to call at exactly 8:30 a.m. to join a teleconference with the board of directors. The communication blast was the initial step of the bank’s emergency “Grexit” plan, a strategy laid out in a document dozens of pages long detailing exactly how managers should react in the event that Greece leaves the euro zone. Each of the 30 bank managers were required to work through the emergency measures pertaining to his or her division. Information was to be transferred to the supervisory board and public officials were likewise to be kept informed as was the German Finance Ministry.

The plan also called for large investors to be put at ease. Questions pertaining to potential bank losses from Greek bond holdings were to be addressed as were changes in monetary transactions with Greece once it was no longer part of the common currency zone. The response also extended to internal bank communication, with instructions to employees for dealing with the new situation posted in the financial institution’s intranet. Customers and stake holders were also to be kept informed. At exactly 6 p.m., the crisis came to an end, as did the work day. Plan “Grexit” was just a dry run, nothing more. At least not yet. Such scenarios are being acted out across Europe these days as companies, banks and governments all prepare for the kind of worst case scenario that isn’t even addressed in euro-zone statutes: the exit of one of the common currency area’s member states.

On Thursday, Greece’s new government under Prime Minister Alexis Tsipras finally applied for an extension to its bailout program. But, from the perspective of German Finance Minister Wolfgang Schäuble, he failed to fulfill the conditions laid down by the Euro Group. Chancellor Angela Merkel spoke on the phone with Tsipras and negotiations have continued, with the next major round scheduled for Friday night. But even if a compromise is found in the end, the game of high-stakes poker will not be over. Both sides would have to agree to a new plan for nursing the country back to financial health.

Read more …

Farrell going astray…

The 1 Reason Pope Francis Is The World’s Top Capitalist (Paul B. Farrell)

Yes, Pope Francis really is a capitalist. Forget his anticapitalist, anticonsumerism rhetoric. Unless he reverses Catholicism’s outdated and destructive dogma on population control, Francis is destined to help capitalists take absolute control of the global economy …. and do more damage to Planet Earth’s climate than the “poison of consumerism.” Yes, thanks to Pope Francis and his dogma on population control, marriage and contraception, capitalists have a steady supply of new consumers fueling their growth. And they’ll get far richer as this supply of new consumers grows to 10 billion by 2050. Why is this so crucial? Because the pope’s failure to reverse the Catholic Church’s historic religious policies on birth control is fueling population growth … guaranteeing explosive consumer growth for capitalists … strengthening capitalism.

Will Pope Francis ever change? Unlikely, certainly not in time to save the world from capitalism’s guaranteed self-destructive trajectory. Why? Because Francis is handicapped by his all-male army of more than 200 cardinals, 5,000 bishops and 450,000 priests all committed to celibacy, against artificial birth control, all driven by perpetual population growth policies also essential to economic growth in today’s capitalist economy, while also accelerating climate change disasters that will eventually decimate human civilization, self-destruct the planet, and even destroy their precious capitalism! Can’t save the world? Well actually there is one way Francis could save the world, if he chose to. He could reverse the Catholic dogma fueling out-of-control global population growth.

Yes, that’d ne a start, but not enough. The pope would then have to convince more than his 1.2 million Catholic faithful. He’d also have to nudge all heads of state, and the world’s seven billion humans, especially young parents making babies, that they’d have cut back their family expectations. But that isn’t going to happen, in time. Climate disasters? You bet, demographic experts like The Earth Institute’s Jeff Sachs, who warns that by the end of this century the planet not only can’t feed 10 billion, we cannot even feed five billion. What a dilemma: Parents love babies. Families thrive on children. Capitalists also love babies, but for a different reason. Babies are consumers, fuel businesses, increase revenues, profits, wealth. It’s a simple economic equation, capitalists just see babies as new consumers. It’s all about money, period. Later, those babies grow up. The cycle continues.

Read more …

Wow, BBC even!

Russians Rally Against Kiev ‘Coup’ (BBC)

A rally has taken place in Moscow to condemn the “coup” in neighbouring Ukraine, a year after the downfall of its pro-Russian president. Russian state media heavily promoted the rally and march with the slogan “We won’t forget! We won’t forgive!”. Ukraine’s protests ousted pro-Russian President Viktor Yanukovych in 2014. Speaking on Russian TV, the ex-leader condemned “lawlessness” in Ukraine, saying the situation there had caused him “very many sleepless nights”. Since Mr Yanukovych’s departure, Russia has annexed Ukraine’s Crimea peninsula and is accused of backing rebels in eastern Ukraine. A ceasefire plan agreed this month in Minsk has appeared close to collapse since taking effect just over a week ago. The Ukrainian government, Western leaders and Nato say there is clear evidence that Russia is helping the rebels in eastern Ukraine with heavy weapons and soldiers. Independent experts echo that accusation. Moscow denies it, insisting that any Russians serving with the rebels are “volunteers”.

Nearly 5,700 people have died since the fighting erupted last April and some 1.5 million people have fled their homes, according to the UN. Groups of demonstrators gathered in central Moscow on Saturday under patriotic Russian banners. Police estimated that about 35,000 people in total took part. The Moscow event was styled as an “anti-Maidan” march – a reference to Ukraine’s pro-EU protests that started on Kiev’s central Independence Square, widely known as the Maidan. The BBC’s Sarah Rainsford, at the scene, says the event was highly organised, with flags and banners distributed and buses laid on from some provinces. The marchers included Cossacks in full uniform and young women in anoraks emblazoned with pictures of Russian President Vladimir Putin, she says.

Read more …

Legal status please?

Poroshenko Bruised By Ukraine Army Retreat (BBC)

The question is not whether the fall of the strategically important road and rail hub of Debaltseve was a blow to Ukraine’s political and military leaders. It was. The question is how big the impact will be. President Petro Poroshenko is portraying the retreat of thousands of Ukrainian government forces as an “orderly” tactical withdrawal. However, initial reports indicate it may have been just the opposite. It is still possible that the retreat avoided a larger, more catastrophic defeat – something along the lines of the Ilovaysk debacle last summer, when Ukrainian forces were encircled by insurgents and possibly regular Russian forces, and were ambushed as they attempted to escape, with untold numbers killed. Much of the political fallout will depend on how big the Debaltseve losses were. So far, the government is saying at least 13 soldiers were killed, 157 wounded, 90 captured and 82 missing.

But the actual figures might be much higher. Also potentially damaging could be the reportedly slapdash, chaotic manner in which the evacuation was carried out, with soldiers escaping on foot after their vehicles were destroyed, and large amounts of armour and ammunition left behind. Already there are rumblings of public discontent. “I have seen this with my own eyes, on the battlefield and in the army headquarters, how military action is planned and executed,” Semyon Semenchenko, commander of the volunteer Donbass battalion, told the BBC. “I can assure you that we lost Debaltseve not because of the Russian military advantage, but because our generals refuse to take responsibility,” he said. Mr Semenchenko has proposed a “parallel” co-ordinating structure for the volunteer battalions fighting in the east. So far 13 battalion leaders have signed up, including Dmytro Yarosh of the nationalist Right Sector.

Mr Semenchenko insists this is not to replace, but to help, the army’s general command in “information exchange, planning, logistical assistance and facilitating mobilisation.” Still, his announcement raised concerns. Eight battalion commanders have refused to join the body, calling on Mr Semenchenko to “end his daily populist and PR statements”. President Poroshenko seems to have a firm grip on power, and many Ukrainians believe he is doing his best in a horrible political and economic situation. Nonetheless, his popularity is slipping. A recent poll showed his approval rating had decreased from 57% to 45%, with 46% saying he was doing a bad job. The “don’t knows” were 9%. Debaltseve has not helped matters at all. And it is possible that the defeat – should the truth be worse than what is being presented at the moment – could significantly damage the Ukrainian president..

Read more …

Stupid is as stupid does.

NATO Must Prepare For Russian Blitzkrieg, Warns UK General (FT)

Nato forces must prepare for an overwhelming Blitzkrieg-style assault by Russia on an eastern European member state designed to catch the alliance off guard and snatch territory, the deputy supreme commander of the military alliance has warned. Openly raising the prospect of a conventional armed conflict with Russia on European soil, the remarks by Sir Adrian Bradshaw, second-in-command of Nato’s military forces in Europe, are some of the most strident to date from Nato. They come amid a worsening in relations with the Kremlin just days into a second fragile ceasefire aimed at curbing continued bloodshed in Ukraine’s restive east between Kiev’s forces and Russian-backed separatists.

Speaking at the Royal United Services Institute think-tank in London on Friday, Sir Adrian warned that as well as adapting to deal with subversion and other “hybrid” military tactics being used by Russia in Ukraine, allied forces needed to be prepared for the prospect of an overt invasion. “Russia might believe the large-scale conventional forces she has shown she can generate at very short notice — as we saw in the snap exercises that preceded the takeover of Crimea — could in future not only be used for intimidation and coercion, but could be used to seize Nato territory,” he said.

Sir Adrian is a former commander of British land forces and the most senior UK officer in the alliance. He added: “After which the threat of escalation might be used to prevent re-establishment of territorial integrity — this use of so-called escalation dominance was, of course, a classic Soviet technique.” Deploying overwhelming force at short notice has become a hallmark of recent Russian military exercises. Russia’s 2013 “Zapad” (“West”) war game involved the rapid mobilisation of 25,000 troops in Belarus and the enclave of Kaliningrad for a conflict with a Nato state.

Read more …

The Heinz tool box.

Kerry Warns of More Russia Sanctions as Ukraine Simmers (Bloomberg)

U.S. Secretary of State John Kerry warned that further sanctions may be imposed against Russia over the next few days if further breaches of a truce in Ukraine continue. “Some additional steps will be taken in response to the breaches of this cease-fire,” Kerry told reporters at the U.S. Embassy in London after talks Saturday with U.K. Foreign Secretary Philip Hammond. “There are some yet very serious sanctions that can be taken which have a profound, increased negative impact on the Russian economy.” Ukraine accused Moscow of sending more troops into eastern Ukraine, contravening a European-brokered truce that was reached in Minsk and took effect Feb. 15. U.S. officials said at the time they wouldn’t rule out imposing tougher sanctions on Russia or giving more security assistance to Ukraine if the Minsk deal isn’t fully implemented.

“We know to a certainty what Russia has been providing and no amount of propaganda is capable of hiding these actions,” Kerry said. Moscow has denied accusations that its forces are fighting in Ukraine. The Russian economy is already swaying as households are hit by a 44% slump in the ruble in the past year and prices soar. “We are not seeking to hurt the people of Russia who regrettably pay a collateral price as a result of these sanctions,” Kerry said, but “increasingly there will be an inevitable, broader impact as the sanctions ratchet up.” Kerry travels to Geneva Sunday for two days of talks with senior Iranian officials on Tehran’s disputed nuclear program before a March 24 deadline for a framework agreement.

The Ukrainian cease-fire agreement brokered last week has been tested by persistent clashes near the cities of Donetsk and Mariupol. Ukraine’s pro-Russian rebels and the government prepared to exchange prisoners in a move toward meeting the terms of the agreement.
Ukraine, the U.S., the European Union and the North Atlantic Treaty Organization say Russia is backing the separatists with hardware, cash and troops – accusations leaders in the Kremlin deny. Russia says Ukraine is waging war on its own citizens and discriminates against Russian speakers, a majority in the Donetsk and Luhansk regions. EU President Donald Tusk said Friday he’d start consultations on new steps “to increase further the costs of aggression on eastern Ukraine” in response to continued “ruthless attacks” by the rebels.

Read more …

Ok, well, that’s a bit much maybe.

Ousted Ukraine Leader Aims To Return As Rockets Threaten Peace Plan (Observer)

Ousted Ukrainian president Viktor Yanukovych has controversially spoken out from self-imposed exile in Russia, promising, exactly a year after he fled Kiev, to return to Ukraine to ease people s lives and help stop the war. Yanukovych’s interview with Russia’s state-owned Channel One was his first public appearance since he gave two bizarre press conferences in Rostov-on-Don in February and March 2014, claiming he remained Ukraine’s president. I regret that I was unable to do anything, Yanukovych said. As soon as it s possible, I will come back and do everything in my power to ease people’s lives. The main task now is to stop the war. In the year since he fled, Russian president Vladimir Putin has annexed Crimea, Russia-backed rebels have established breakaway republics in eastern Ukraine, and at least 5,600 people have died in the conflict.

Yanukovych is despised across much of Ukraine, viewed as a corrupt Russian puppet by the pro-western protesters that forced him from office, and as a coward in the pro-Russia east. As he spoke, a fragile peace plan remained in the balance, with a prisoner exchange proceeding on Saturday amid continued shelling. Meanwhile thousands assembled in Moscow for an anti-Maidan rally . Veterans, Cossacks, prominent pro-Putin bikers and others waved signs denouncing Kiev, and banners reading, We don t need western ideology and gay parades, and Putin is our president.

Rows of buses parked nearby and the rapid departure of attenders after the rally raised suspicions that hired protesters had been brought in from other regions, a common tactic at pro-Kremlin rallies. In Kiev, Petro Poroshenko, the oligarch who publicly backed the EuroMaidan protests last winter and was elected president in May, blamed Russia for inciting conflict at an anniversary vigil in memory of more than 100 demonstrators killed at the height of the unrest. Commemorations continued on Saturday with a display by the defence ministry of grenade-launchers, drones and other weaponry seized in eastern Ukraine, which it claimed was from Russia.

Read more …

Without the CIA f%#ing things up..

Ukraine, Rebels Swap Dozens Of Prisoners (Reuters)

Ukrainian government forces and pro-Russian separatists have exchanged dozens of prisoners in east Ukraine, a Ukrainian Security Council aide confirmed on Sunday, a step toward implementing an internationally brokered peace deal. Reuters reporters in the village of Zholobok, 20 km (12 miles) west of the rebel stronghold of Luhansk, saw more than 130 Ukrainian servicemen being released late on Saturday evening in exchange for 52 rebel fighters. The exchange is one of the first moves to implement the peace deal reached on Feb. 12 in the Belarussian capital Minsk after the French, German, Russian and Ukrainian leaders met. The Security Council’s Markian Lubkivskyi, in a post on his Facebook page early on Sunday, published a list of the 139 released Ukrainian servicemen and said the government would do its utmost to free those remaining in rebel captivity.

Fighting has eased in many areas since a ceasefire came into effect a week ago, but the truce was badly shaken by the rebel capture on Wednesday of the strategic town of Debaltseve, forcing a retreat by thousands of Ukrainian troops. The Ukrainian military said rebels had launched 12 separate attacks on government troop positions overnight, using artillery and mortar fire. The town of Pesky near Donetsk had seen the most intense fighting, while separatist groups had attempted to “storm” Ukrainian positions in Shyrokyne, east of the strategic port city of Mariupol on the Sea of Azov, it said on Facebook.

Kiev accuses separatists of building up forces and weapons in Ukraine’s southeast and has said it is braced for the possibility of a rebel attack on Mariupol. Nevertheless, rebel leaders said on Saturday they had signed a document detailing a plan for the withdrawal of heavy weapons, as required by the Minsk agreement, a sign they may be prepared to halt their advance, having achieved their main military objective by seizing Debaltseve. The rebel press service DAN said Ukrainian troops had been shelling parts of Donetsk, reporting that artillery fire could be heard in the city at around 0730 GMT.

Read more …

That’s all Monsanto needs: an idiot in charge of 20%+s of the world population, and who can be bought.

Modi Bets On GMO Crops For India’s Second Green Revolution (Reuters)

On a fenced plot not far from Indian Prime Minister Narendra Modi’s home, a field of mustard is in full yellow bloom, representing his government’s reversal of an effective ban on field trials of genetically modified (GM) food crops. The GM mustard planted in the half-acre field in the grounds of the Indian Agricultural Research Institute in New Delhi is in the final stage of trials before the variety is allowed to be sold commercially, and that could come within two years, scientists associated with the project say. India placed a moratorium on GM aubergine in 2010 fearing the effect on food safety and biodiversity. Field trials of other GM crops were not formally halted, but the regulatory system was brought to a deadlock. But allowing GM crops is critical to Modi’s goal of boosting dismal farm productivity in India, where urbanization is devouring arable land and population growth will mean there are 1.5 billion mouths to feed by 2030 – more even than China.

Starting in August last year, his government resumed the field trials for selected crops with little publicity. “Field trials are already on because our mandate is to find out a scientific review, a scientific evaluation,” Environment Minister Prakash Javadekar told Reuters last week. “Confined, safe field trials are on. It’s a long process to find out whether it is fully safe or not.” Modi was a supporter of GM crops when he was chief minister of Gujarat state over a decade ago, the time when GM cotton was introduced in the country and became a huge success. Launched in 2002, Bt cotton, which produces its own pesticide, is the country’s only GM crop and covers 95% of India’s cotton cultivation of 11.6 million hectares (28.7 million acres). From being a net importer, India has become the world’s second-largest producer and exporter of the fiber.

However, grassroots groups associated with Modi’s Hindu nationalist Bharatiya Janata Party (BJP) have opposed GM crops because of the reliance on seeds patented by multinationals. The Swadeshi Jagran Manch, a nationalist group which promotes self-reliance, has vowed to hold protests if GM food crops are made commercially available. “There is no scientific evidence that GM enhances productivity,” said Pradeep, a spokesman for the group. “And in any case, why should we hand over our agriculture to some foreign companies? A handful of agrichemical and seeds companies dominate the global market for GM crops, including Monsanto, DuPont, Dow and Syngenta. Largely agricultural India became self-sufficient in foodgrains after the launch of the Green Revolution in the 1960s, when it introduced high-yielding seed varieties and the use of fertilizer and irrigation. The challenge now is to replicate that success in edible oils and vegetables, which are increasingly in demand.

Read more …

Jan 242015
 
 January 24, 2015  Posted by at 12:24 pm Finance Tagged with: , , , , , , ,  6 Responses »


Unknown Goodyear service station, San Francisco Sep 14 1932

Ripped Off, Poor, Suicidal: The Greek Farmers Turning To Syriza (Channel4)
Syriza’s Rise Fueled by Professors-Turned-Politicians (WSJ)
Economist Vatikiotis: Syriza Proposals Don’t Go Far Enough for Greece (Truthout)
Tsipras Aims For Deal With Lenders By This Summer (Kathimerini)
German Finance Minister To Greece: We Support You (CNBC)
Nothing Is Going to Save the US Housing Market (A. Gary Shilling)
Central Banks Powerless To Prevent Steep Rise In Real Rates (Russell Napier)
Will ECB’s Bazooka Be A Game Changer For Emerging Markets? (CNBC)
Head West for Best Look at US Oil Drillers’ Pain (Bloomberg)
Ruble Colluding With Oil Brews Russian Toxic Loan Morass (Bloomberg)
Spain Finance Minister: We Have The ‘Good Kind’ Of Deflation (CNBC)
Italy Central Bank: We Are Lagging Behind The World (CNBC)
States Where the Middle Class Is Dying (24/7 Wall St)
Labor-Force Participation May Hold Key To Fed Moves (MarketWatch)
Billions in Lost 401(k) Savings, Abusive Brokers Under Scrutiny (Bloomberg)
RT Equated To ISIS For ‘Daring To Advocate A Point Of View’ (RT)
Brazil’s Most Populous Region Faces Worst Drought In 80 Years (BBC)
Pope Francis’s US Tour Will Set Off Economic Fireworks (Paul B. Farrell)

“They keep saying if Syriza wins we’ll be like North Korea or Venezuela. The politicians who tried that line are making a laughing stock of themselves.”

Ripped Off, Poor, Suicidal: The Greek Farmers Turning To Syriza (Channel4)

There’s pizzazz tonight at the election rally of the Greek conservatives. There is a lot of money riding on their victory. But right now it looks like the election is slipping away from Prime Minister Antonis Samaras. Two polls last night put Syriza ahead – one, by the usually authoritative Mega channel, has the far left on 32.5% against New Democracy’s 26.5%. More polls today tell the same story: a widening Syriza lead. If Greece does elect Alexis Tsipras as the first far-left prime minister in Europe since the 1930s, then the place where it’s lost and won will not be Athens. Syriza is making inroads into towns and provinces that have traditionally voted right. In the gulf of Corinth there are a whole string of mountain villages that have traditionally been known as “castles” for the two main parties – ND and the centre-left Pasok. But Pasok has collapsed, and even some conservative voters are swinging over to support the left.

In Assos, a sleepy farming village Giannis Tsogkas, a grape farmer aged 56, explains why the place has swung towards the left. “Two-thirds of the land here has been mortgaged to the banks. Now we can’t pay our debts and we’re in constant fear of repossession. These are the worst times we’ve ever seen. We’re at a point where we can’t afford anything. “We used to go to the supermarket three times a week, now we only go once every two weeks – and we count every single cent we spend. It never used be like this: we had money, we were.. We produced, we sold, we had an income.” There’ve been a string of suicides, he tells me. And not just because of austerity. Every year, he alleges, the merchants who buy their grapes refuse to pay, or go bust. The legal system is so decrepit that it cannot help them. For the farmers in Assos the problems of falling incomes and a political system they see as corrupt merge into one.

“They shoved us into austerity with the IMF. The small farmer will die, that’s it. People here keep committing suicide. So we looked for someone to protect us, and we found it in Syriza.” Ten years ago Syriza got a grand total of 121 votes in the village – just over 2%. In the June 2012 general election it came second, with 22%. Last year, in the Euro elections it topped the polls with 27% – and Mr Tsogkas believes it will win easily on Sunday. It’s anger like this that has seen poll swings to Syriza in rural areas, suburban communities, and even regions like Thessaly that were once strongly right-wing. The government, which had relied on a fear strategy to stop Syriza, seems bereft of strategy. In the local coffee shop in Assos we meet other farmers, once staunch supporters of the centrist Pasok party. “They keep saying if Syriza wins we’ll be like North Korea or Venezuela. The politicians who tried that line are making a laughing stock of themselves. I don’t care who governs us, I care about Greece,” one man says angrily.

Read more …

Greece’s best and brightest come home to save the nation.

Syriza’s Rise Fueled by Professors-Turned-Politicians (WSJ)

Wearing suit pants and a jacket, Costas Lapavitsas stood Wednesday afternoon on the floor of a steel-fabricating shop here and addressed a few dozen workers and small-business owners who smoked while sitting in plastic chairs. “I am not a career politician,” he began. Indeed. Mr. Lapavitsas’s political career is only a few weeks old. In Greece’s elections Sunday, he is a parliamentary candidate for the leftist opposition party Syriza, which leads Prime Minister Antonis Samaras ’s conservative party in the polls and could roil politics throughout Europe if it wins. For more than 20 years, the 54-year-old Mr. Lapavitsas has taught economics at the University of London’s School of Oriental and African Studies. Now, he is part of the cadre of academics-turned-politicians forging Syriza’s economic thinking. European economic orthodoxy, led by Germany, has fought Greece’s debt crisis with painful austerity—public-spending cuts and tax hikes—and other strict reforms.

Syriza’s rise is the most potent challenge yet to that orthodoxy. If Syriza wins, it could embolden left-wing parties in other countries, especially Spain, where political tensions also are boiling. It could even result in a rift with Germany that ruptures the euro. The economic plan advanced by Mr. Lapavitsas and other professors aligned with Syriza is rooted in the core principles of debt forgiveness and higher government spending, which Germany has rejected. “We need to renegotiate the logic,” says Yanis Varoufakis, a visiting professor at the University of Texas at Austin until a few days ago. He describes himself as a “libertarian Marxist” and has been recruited by Syriza to run for a seat in Greece’s parliament. A few years ago, Syriza was a fringe coalition of leftists. It jumped into the political mainstream in 2012 because of populist fervor and the party’s charismatic young leader, Alexis Tsipras. But a muddy economic message left Syriza in second place—and out of power.

It has honed its focus since then, and Mr. Lapavitsas describes the party’s platform as “a Keynesian program with redistribution attached, with some Marxist view of the world.” He adds: “We are not ashamed of that.” In the tradition of John Maynard Keynes, Syriza advocates public spending to reignite economic growth. Greece can afford to spend more if some of its debt is forgiven by other countries. Nikolaos Chountis, a Syriza candidate in Athens, ticks off the party’s spending priorities: food and electricity subsidies for impoverished households, a pension boost for the poorest retirees, a hike in the minimum wage and tax cuts for low earners. “The legislation is ready..” Since 2010, Greece’s economic policy has largely been dictated by the “troika” of technocrats appointed by Europe and the International Monetary Fund to supervise Greece’s €240 billion ($280 billion) bailout. The troika wields a memorandum that minutely details what Greece must do in return for the rescue. Section 5.1.2.6.ii. commits Greece to reviewing customs procedures for canned peaches and four other products.

Read more …

Worth perusing.

Economist Vatikiotis: Syriza Proposals Don’t Go Far Enough for Greece (Truthout)

Economist Leonidas Vatikiotis, previously a European Parliament candidate with Greece’s Antarsya political party, shares his take on the upcoming elections in Greece, the economic proposals put forth by main opposition party Syriza, and the need, in his view, for Greece to depart from the eurozone. Michael Nevradakis: We left off before the holidays in the midst of the election for a new president of the Hellenic Republic, and we are now in the new year and in the midst of a snap parliamentary election in Greece. There are many government politicians, pro-government analysts and Greek and international media outlets who keep talking about the irresponsible, as they characterize it, stance of the opposition in not voting in favor of the government’s candidate for the presidency of the republic and for not averting these snap elections. How do you view this issue?

Leonidas Vatikiotis: To characterize as irresponsible a position adopted by several political parties that are represented in parliament, simply because they exercised their constitutional right not to vote for the government’s candidate for the presidency, is an insult to even the most basic democratic ideals. Syriza, the Communist Party of Greece, and the Independent Greeks exercised their constitutional right, and if we want to get to the heart of the matter, what Greek society as well as the political parties in parliament learned from this is that the government did not wish to simply extend its term in office. We were told that the government wished, through the election of its candidate for the presidency of the republic, Stavros Dimas, to extend its hold on power and complete its full four-year term. However, what the government of Antonis Samaras and Evangelos Venizelos also wanted was, essentially, the acceptance by Greek society of a new, and more severe, memorandum agreement.

“The troika leaked to the press that Greece still needed to ratify over 1,000 measures which it had agreed to with the troika but which had not yet been passed legislatively through the Greek parliament.” We should note where the negotiations between the Greek government and its lenders left off, at the Eurogroup meeting on December 8. At that time, the eurozone refused to continue negotiations to complete its review of the Greek economy, pending the election of a new government in Greece. On December 8, the negotiation cycle, which began during the summer of 2014, came to a close, and this was a period during which the government and the prime minister himself, Antonis Samaras, proclaimed that Greece had emerged from the crisis, that the memorandum agreements were a thing of the past, and that better days were ahead, that troika oversight of the Greek economy, which had been in place since May of 2010, would cease.

The intentions of Greece’s lenders, however, were quite different: The troika leaked to the press that Greece still needed to ratify over 1,000 measures which it had agreed to with the troika but which had not yet been passed legislatively through the Greek parliament. This was the point where the Samaras-Venizelos government did not continue its negotiations, knowing that there was no way that it could fulfill the demands of the troika and pass these measures through parliament.

Read more …

Nice detail: “..he suggested that he would negotiate with representatives of European Union institutions, rather than troika officials.”

Tsipras Aims For Deal With Lenders By This Summer (Kathimerini)

SYRIZA leader Alexis Tsipras will aim to conclude an agreement with Greece’s international lenders by the summer if his party is able to form a government after Sunday’s elections. In a televised news conference Friday, Tsipras sketched out his plans for government and revealed that he had no specific plans for meeting German Chancellor Angela Merkel if he becomes prime minister. The SYRIZA chief suggested that his government would enter negotiations with Greece’s eurozone partners after being elected and would aim to wrap up talks on the way forward in the relationship between the two sides by July or August, when Greece has a series of debt obligations to meet.

Tsipras said that he is aiming to achieve a “sustainable, mutually acceptable solution for Greece and for Europe.” However, he suggested that he would negotiate with representatives of European Union institutions, rather than troika officials. “Austerity is not enshrined in European treaties,” said Tsipras, adding that his government would recognize Greece’s “institutional obligations” toward the EU but not the “political commitments”» made by the outgoing government. When asked where he would make his first official trip to if elected prime minister, Tsipras said it would be Cyprus. He added that he would not seek direct talks with Merkel. “I do not recognize Mrs Merkel as being any different from the other leaders,” he said. “She is one of 28 so I will not rush to meet her.”

Read more …

The Greeks know what that is worth. Germany keeps saying: ‘Better do what we tell you to do’.

German Finance Minister To Greece: We Support You (CNBC)

Germany’s finance minister Wolfgang Schaueble denied that the country has started preparations for a Greece exit from the euro zone, ahead of a key election in the turbulent Mediterranean country on Sunday. “We did whatever could be done to support Greece in difficult times, again and again,” Schaueble told a CNBC panel at the World Economic Forum in Davos, Switzerland. “We had to convince the IMF to make very extraordinary conditions so that we could support this,” he said of the frantic discussions between International Monetary fund and European Union authorities around the $147 billion bailout of Greece in 2010. “There were endless discussions.”

Now, talk among commentators and politicians in Germany suggests the government is more open to the idea of a Greek exit from the single currency region – even though Chancellor Angela Merkel and other senior politicians still want it to stay. “We don’t need any problems,” Schaueble said. “We will wait on the elections in Greece.” The possibility of a Greek exit from the euro zone, if left-wing Syriza, which campaigns on an anti-austerity platform, gains power next week, is only one of many potential political events which could cause turmoil in markets this year. “Most of the disturbing things today that can go wrong are political,” legendary investor George Soros warned in Davos.

Read more …

How many Americans do you think see this Shilling’s way?

Nothing Is Going to Save the US Housing Market (A. Gary Shilling)

U.S. housing activity remains weak despite six years of federal government aid, strong interest from overseas buyers, rock-bottom interest rates and massive purchases of mortgage bonds by the Federal Reserve. Does this mean housing may never spring back to its pre-recession levels? Many signs point to yes. Don’t blame the Chinese, who are showing an abundance of interest. Their share of foreign purchases leaped to 16% in the year ending March 2014, from 5% in 2007. They paid a median price of $523,148, higher than any other nationality and more than double the $199,575 median price of all houses sold. The value of home sales to all foreigners rose 35% last year to $92 billion, up more than 50% since 2007 and accounting for 7% of all existing home sales. Foreigners view U.S. homes as safe investments and U.S. schools as good places to teach their children English.

But such robust foreign purchases can’t overcome what ails the U.S. housing market. Activity is weak even now that banks are no longer tightening mortgage-lending standards, according to a Fed survey. Banks are searching for new lines of business since the Dodd-Frank reform law and regulations are depriving them of revenue from proprietary trading, derivative origination and investing and off-balance sheet activities. The end of the mortgage refinancing surge has added to the pressure on banks. By necessity, banks remain selective about the mortgages they’ll underwrite, having paid huge penalties for originating and selling bad mortgages pre-crisis. Banks are also being careful to avoid the high cost of mortgage defaults now that they must repurchase loans with underwriting defects. The result can be seen in foreclosure data: In the third quarter, banks began foreclosure proceedings on only 0.4% of mortgages, far below the 1.4% level in the peak of the financial crisis.

Fed Chair Janet Yellen worries about the negative effects of tight credit standards on housing. While she admits that lenders should have raised their standards earlier, “any borrower without a pretty positive credit rating finds it awfully hard to get a mortgage,” she said in July. Even Ben Bernanke, her predecessor, was turned down when he tried to refinance his mortgage. With the federal funds rate at essentially zero and the Fed having ended its purchases of mortgage securities, the central bank can’t do much to help housing now. The Barack Obama Administration, however, is reversing some of the government post-crisis tightening of lending standards. Fannie Mae and Freddie Mac, which remain under government control and now guarantee about 90% of all new mortgages, have reduced the underwriting standards on packages of mortgages they guarantee, including allowing loans with as little as 3% down payments.

Read more …

“..central bankers cannot fix very much..”

Central Banks Powerless To Prevent Steep Rise In Real Rates (Russell Napier)

The Swiss National Bank (SNB) failed to ‘fix’ the exchange rate between the Swiss Franc and the Euro. The simple lesson which investors must learn from this is – central bankers cannot fix very much. The inability of the Swiss National Bank to ‘fix’ the exchange rate will come to be seen as the end of the bull market in the omnipotence of central bankers. Think for just a moment of all the key variables which you believe are ‘fixed’ (made firm), fixed (repaired) , fixed (circumvention of the laws of supply and demand) or fixed (dosed with monetary narcotics) by central bankers. These various fixes by central bankers across the world can also fail. That process of failure began in Bern and Zurich early one morning on January 15th 2015.

As the OED entries for the word ‘fix’ make clear, the failure of the SNB to fix the exchange rate was on many levels. It failed to ‘ fix’ the exchange rate in terms of making the Swiss Franc ‘firm’ to the Euro and hence ‘deprive it of volatility or fluidity’. It failed to ‘fix’ the exchange rate as the ‘laws‘ of supply and demand were ultimately not circumvented. For many, particularly Swiss exporters, the material appreciation of the Swiss Franc on the international exchanges will not ‘fix’ the currency in terms of making it ‘ready for use’. Finally, the adjustment in the exchange rate removes, rather than administers, the dose of monetary ‘narcotic’ in the form of excess growth in Swiss Franc liquidity and cheap funding for speculators in Euro. The monetary ‘fix’, which was the by-product of fixing the exchange rate, has ceased to be and the price of equities has collapsed.

Read more …

“..the weaker euro reduces the purchasing power of the Europeans and therefore their ability to import from Asia..”

Will ECB’s Bazooka Be A Game Changer For Emerging Markets? (CNBC)

The ECB bold bond-buying scheme is set to provide a temporary boost to Asian equities but is no game changer for the region’s markets, say analysts. After months of speculation, the ECB on Thursday pledged to buy €60 billion ($70 billion) worth of private and public bonds each month until September 2016 in a program that could amount to €1.1 trillion. This was more aggressive than the €50 billion in monthly asset purchases analysts expected. Investors applauded the move, sending European and U.S. equities higher overnight.The positive sentiment carried over into the Asian trading session on Wednesday, with South Korea’s KOSPI rising 0.8% and Indonesia’s Jakarta Composite up 1%. But, analysts expect the lift will be short-lived.”I doubt the increased liquidity will be driving a lot of fund inflows into Asia [over the medium-term],” Stephen Sheung at SHK Private told CNBC.

“A lot of that amount of money will likely be stuck in European banking system rather than flowing out,” he said.Funds that do flow out are likely to go into the U.S. or U.S. dollar assets instead of Asian stocks, Sheung said, citing deteriorating growth in the region.”We have growth problems here in Asia, U.S. economic conditions are on a much more stable footing, and there are prospects for further U.S. dollar appreciation,” he said. Nicholas Ferres, investment director at Eastspring Investments points out that the ECB’s action may have negative implications for European demand for Asian goods, due to the weakening euro. This does not bode well for Asian exporters. “[On the negative side], the weaker euro reduces the purchasing power of the Europeans and therefore their ability to import from Asia,” Ferres said.

The euro sank to a more than 11-year low against the dollar and a three-month low against the yen on Thursday following the ECB’s announcement.”On the positive side, it will likely improve risk perceptions and risk appetite and that might help cheap cyclical stocks rally,” he said.More than liquidity finding its way into Asia markets, Sheung says the ECB action is likely to drive Asian intuitional investors and large corporations to make investments in Europe.”With liquidly abundant and the euro cheaper, it makes investments more attractive,” he said.”Asian investors won’t necessarily look at equities or debt but more at direct investments in projects or infrastructure. This has been a hot topic for the past two to three quarters.”

Read more …

“Within the past four weeks, drillers idled half of their rigs in the state..”

Head West for Best Look at U.S. Oil Drillers’ Pain (Bloomberg)

Little is going right for California’s oil industry. Turns out the state’s shale formation holds less promise than producers expected. Aging conventional wells are drying up. And a rebound in output that cost drillers as much as $3 billion annually to create has been overshadowed by shale oil gushing from wells in North Dakota and Texas. Then, of course, came the collapse in oil prices – a seven-month, 57% drop that was exacerbated by OPEC’s refusal to cut output in order to squeeze the U.S. shale drillers. No state is feeling that pressure more than California. Drillers there have idled more rigs – on a proportional basis – than those in any other part of the country.

“We spent a lot of money to go out and drill and use new technologies just to stop production from depleting in our mature fields,” Rock Zierman, chief executive officer of trade group California Independent Petroleum Association, said by phone. “It took us a lot of capital to basically run in place and now we’re looking at crude prices under $40 a barrel.” While U.S. benchmark West Texas Intermediate oil has fallen by more than half since June, California’s heavy Kern River crude has lost 65% of its value. The spot price of that oil slid to $34.87 a barrel on Jan. 22, below Gulf Coast crudes, below Bakken in North Dakota and under Alaska North Slope oil.

Falling prices haven’t been all bad for California. Governor Jerry Brown said in an interview with Bloomberg News Jan. 15 that while the decline in California’s oil drilling is “of concern,” drivers are benefiting. Gasoline is under $2.50 a gallon for the first time since 2009 in a state that’s usually home to some of the most expensive fuel in the country. Relief at the pump will save the average California household $675 this year, said Patrick DeHaan, a Chicago-based senior petroleum analyst at GasBuddy Organization Inc. “The oil price decline goes right into consumer spending,” Brown said at his Oakland office. “So there will be trade-offs.” Within the past four weeks, drillers idled half of their rigs in the state, dragging the total down to the lowest since 2009. Oil output, which had been creeping up since 2011, is now little changed and a slide will probably follow.

Read more …

Messy.

Ruble Colluding With Oil Brews Russian Toxic Loan Morass (Bloomberg)

An increasingly toxic mixture of high interest rates, spiraling inflation and plunging oil means Russian banks will probably need a lot more than the $18 billion set aside last year to protect against bad loans. Russia is facing an “extremely widespread” banking crisis in 2015, and lenders may need to boost provisions for souring debts to $50 billion should oil stay in the mid-$40s, according to Herman Gref, the head of the nation’s biggest lender, Sberbank. That’s after banks increased reserves by 42% last year, compared with 27% in Turkey and 7.5% in Poland in the first 11 months, official figures show. Seven of Russia’s 10 worst-performing bonds this year are from banks as policy makers raised rates by the most since 1998 to shore up the ruble, whose 47% slide over the past 12 months deepened the burden of loan payments for consumers and businesses.

With the economy foundering after crude’s decline and sanctions over Ukraine, the ratio of bad debt will double from the third quarter of 2014 to as much as 13% by year-end, according to Liza Ermolenko at Capital Economics in London. “Bad loans will continue to pile up,” Yulia Safarbakova, an analyst at BCS Financial Group, said by phone. “Companies can’t refinance because of the rate increase and the ruble devaluation has hit them hard.” Lenders are on the front line of Russia’s economic crisis, bearing the brunt of oil’s slump and sanctions over President Vladimir Putin’s annexation of Crimea from Ukraine in March. The turmoil that followed forced the central bank to raise interest rates six times to shore up the ruble, choking loan growth to an almost four-year low, while retail deposits declined and bank profits tumbled 41%. The currency’s slide helped drive inflation to a five-year high of 11.4% in December, curtailing the central bank’s ability to reduce borrowing costs even as executives of the biggest Russian banks warn of the strain they are under.

Read more …

Certified idiot.

Spain Finance Minister: We Have The ‘Good Kind’ Of Deflation (CNBC)

The specter of growth-sapping deflation may have finally arrived in the euro zone but you won’t find policymakers in Spain panicking anytime soon. The country has made some “bold reforms” in the last three years, Luis de Guindos, the country’s finance minister told CNBC on Friday, shrugging off the weak consumer price data and blaming it on the dramatic fall in the price of oil. “This is positive, this is a positive sign. In Spain, oil prices are reducing the inflation rate. And it’s not because we have deflation. It’s totally different, inflation is like cholesterol. There are two kinds of deflation. The bad one and the good one. In Spain, you know, we have the good kind,” Luis de Guindos, told CNBC at the World Economic Forum in Davos.

This is the deflation that is filling the pockets of the households, he added, and has been fueled by the reforms Spain has taken in the energy markets and the cheaper price of oil at the pump, he said. Prices in the euro zone fell 0.2% year-on-year in December, marking the first time since 2009 that prices have dipped into negative territory. But the statistics for Europe showed that energy was indeed weighing massively on prices with an annual fall of 6.3%. In Spain, annual consumer prices fell around 1% in December. As well as energy reforms, de Guindos boasted that Spain’s new policies were the perfect example of the reforms that the euro zone is looking for.. “We were on the brink three years ago…we have started to reap the rewards of those policies,” he said.

Read more …

Couldn’t possibly be even partly his fault, could it?

Italy Central Bank: We Are Lagging Behind The World (CNBC)

The governor of the central bank of Italy has said slowness to reform and political uncertainty in Italy has left it “lagging behind” other nations, partly due to the political instability the country has faced in recent years. Speaking from the World Economic Forum in Davos, Switzerland, Bank of Italy Governor Ignazio Visco said during his time in office at the central bank, he has seen five separate finance ministers come and go, which has dented foreign investment in the country. “While (German finance minister) Mr. Schauble has been in office (in Germany) for the three years I have been governor of the Bank of Italy, I have had 5 finance ministers. This is a major problem – we need certainty for investment,” he told CNBC. “We are lagging behind a number of sectors, areas in innovation and technological change. We have had enormous change at the global levels in the last 20 years and we should really cut the distance.

This is why you need stability in a number of areas, among them price stability and this is what we are trying to deliver,” he said. Visco also dismissed concerns that the euro could slide below the U.S. dollar, adding that euro dollar exchange rate, which has seen the euro fall to 11-year lows against the greenback after European Central Bank President Mario Draghi unveiled a new stimulus package on Thursday, was not a level central bankers monitored.. “Parity is a figure of imagination really. I have been the chief economist at the OECD when the euro was introduced, we were foreseeing that from $1.19 it should go to £1.30, it went to $0.80, so it’s better not to talk about what is the target,” he said. “We do not target the euro, there is no question. This is a channel of transmission of monetary policy, we are doing monetary policy the old fashioned way, we are simply supplying money to the economy,” Visco added.

Read more …

“..a decoupling of productivity and wages..”

States Where the Middle Class Is Dying (24/7 Wall St)

The American economy is by many measures well on the road to full recovery. The national unemployment rate was 6.2% in 2013, down from 9.3% in 2009; U.S. gross domestic product grew 5% in the third quarter of 2014; and the S&P 500 recently reached its all time high. And yet the middle class, which historically was the driver of economic growth, is falling behind. The average income among middle class families shrank by 4.3% between 2009 and 2013, while incomes among the wealthiest 20% of American households grew by 0.4%. Based on average pre-tax income earned by the third quintile, or the middle 20% of earners in each state, middle class incomes in California declined the most in the country. Incomes among middle class Californian households fell by nearly 7% between 2009 and 2013, while income among the state’s fifth quintile, or the top 20% of state earners, grew by 1.3%. [..]

According to Joe Valenti, director of asset building at the Center for American Progress, the American middle class is essential for economic growth because middle income families are spending relatively large shares of their incomes on goods and services. “An additional dollar in the hands of a middle income earner is going to drive a lot more spending than an additional dollar in the hands of someone in that top quintile,” Valenti said. While households in the top quintile are able to spend enormous sums of money, “at some point there’s only so much that an individual can spend, even on all different kinds of luxury goods.” While the middle class is the most important cohort in terms of spending and has in the past been essential for economic growth, middle income families have been the victims of wage stagnation. Valenti argued that as early as the 1970s, American companies started becoming much more productive.

However, because of “a decoupling of productivity and wages,” wages among many workers have remained stagnant, and many in the middle class “have not been able to reap the benefits of higher productivity,” Valenti explained. Instead, returns from higher productivity have gone to owners and investors and not to the workers, he said. Many of the beneficiaries of these returns are likely part of the wealthiest 20% of households, whose incomes have grown in recent years. Much of the income growth among the highest earning households is likely due to stock market gains. As Thomas Piketty argues in “Capital in the 21st Century,” income inequality results from a higher return on capital — money used to make more money in the stock market or other revenue-generating assets — than wage and GDP growth. With the rich holding a disproportionate share of money in the stock market, their incomes have recovered much faster than those of middle class workers.

Read more …

Not very strong, Barry.

Labor-Force Participation May Hold Key To Fed Moves (MarketWatch)

Economic historian Barry Eichengreen has spent a lifetime looking at mistakes that economic policymakers have made, especially in his best known work about the Great Depression. In an interview with MarketWatch, Eichengreen, an economics professor at the University of California, Berkeley, discussed some of the challenges facing the Fed, and a recent example of a policy mistake by the Swiss National Bank. He also warns that Washington’s tepid response to the financial crisis makes another, even bigger crisis, a possibility.

MarketWatch: Do you think the Fed will be able to lift interest rates this year?

Eichengreen: I have been skeptical for a while about the market consensus that the Fed is likely to move in June. I’ve been wondering whether the labor force participation rate may begin to rise again, in which case inflationary pressures will remain subdued and the unemployment rate will not continue to fall. And that rise in the labor force participation rate could indeed happen, we simply don’t know. I think the Fed will wait and see before it moves. Now we have in addition a strong dollar that may grow even stronger. That’s going to create headwinds for economic growth in the U.S. and I think it is quite conceivable that it could lead the Fed to wait longer. Finally there is volatility. There is the Swiss National Bank, kind of reminding us that volatility happens. It’s important to recall that the SNB is a small central bank of a small country in the grand scheme of things. If [the SNB] making a surprise move can wrong foot the market so dramatically, imagine what could happen if a big central bank pulled a surprise. So it’s quite possible, in my view, there is more volatility coming, and the Fed will have to deal with that too.

MarketWatch: What are the lessons for the Fed from the Swiss National Bank decision? The Fed has to be cautious and certain before it moves?

Eichengreen: I think the silver lining here is that at the cost of a recession in Switzerland and deflation in Switzerland, the SNB having made a serious mistake, it has reminded us that financial markets are not as liquid as they have been in the past, and there can be very big market moves as a result of a central bank surprise. So people will be looking more closely at the shadow banking system then they have been in the last relatively complacent year. We can thank the SNB for that if nothing else. And secondly, I think central banks have had a reminder about the importance of good communications policy, which we did not have coming out of Switzerland last week. The Yellen Fed has been very focused on the importance of communications and they will be even more focused as a result of last week, which can only be a good thing.

Read more …

“The current regulatory environment creates perverse incentives that ultimately cost savers billions of dollars a year.”

Billions in Lost 401(k) Savings, Abusive Brokers Under Scrutiny (Bloomberg)

One of President Barack Obama’s top economic advisers said abusive trading practices are costing workers billions of dollars in retirement savings each year and called for stricter rules on Wall Street brokers. Jason Furman, chairman of Obama’s Council of Economic Advisers, drafted a Jan. 13 memo citing research that says some broker practices, such as boosting commissions with excessive trading, cost investors $8 billion to $17 billion a year. The document was circulated to senior aides and indicates the White House may support tighter oversight of brokers who handle retirement accounts. The memo, obtained by Bloomberg News, makes the case for a Labor Department regulation that would impose a fiduciary duty on brokers handling retirement accounts, requiring them to act in their clients’ best interest.

Under current rules, brokers are held to a ‘suitability’ standard, meaning they must reasonably believe their recommendation is right for a customer. “Consumer protections for investment advice in the retail and small-plan markets are inadequate,” Furman wrote in the memo, also signed by Betsey Stevenson, another member of the economic council. “The current regulatory environment creates perverse incentives that ultimately cost savers billions of dollars a year.” Wall Street has spent more than four years lobbying against the Labor rule. Led by firms like Morgan Stanley and Bank of America, the industry has argued that costlier regulations would take away options for smaller investors, who would lose access to advice as well as investment choices.

A White House official said the document, titled “Draft Conflict of Interest Rule For Retirement Savings,” shouldn’t be seen as a new turn in the Labor Department’s rulemaking. That process, the official said, would include a comment period if the administration moves forward. The Labor Department last year indicated that its proposal could come as soon as this month. A fiduciary duty on brokers would provide “meaningful protections” to investors, according to the memo.

Read more …

Anything goes in America these days.

RT Equated To ISIS For ‘Daring To Advocate A Point Of View’ (RT)

Following comments from the US overseas broadcasting chief listing RT as a challenge alongside the Islamic State and Boko Haram, critics said the outlet was singled out for “daring to advocate a point of view,” as well as for “competing for viewership.” On Wednesday, the new chief of the US Broadcasting Board of Governors (BBG), Andrew Lack, told the New York Times that RT posed a significant challenge – putting the broadcaster in a list alongside the Islamic State and Boko Haram terror groups. The comments have since been denounced on social networks and across the media spectrum. Speaking to RT, legal analyst and media commentator Lionel said the channel was being outrageously singled out and equated to the Islamic State for “daring to advocate a point of view.” “In the history of incoherent statements, this might be the granddaddy of them all.

In reading this, he alleges that Russia Today pushes… ‘a point of view,’” he told RT’s Ameera David. Georgetown University journalism professor Chris Chambers added that Lack’s words were “supremely silly and careless,” especially considering his media background. Lack previously worked for NBC, Bloomberg, and Sony Music. “This is a guy who has some media savvy, supposedly, even though he’s moved around a lot – maybe this is one reason he’s moved around,” Chambers told RT. “But this was a very careless and silly thing to say considering the prevalence of corporate media here in the United States, and the purpose of BBG’s constitutes like Voice of America, who are supposed to put out all kinds of views.” While Lack’s comments were roundly criticized, Steven Ellis of the International Press Institute said he was right in one way. “Mr. Lack could have phrased his comments more carefully: RT does indeed pose a challenge to US international broadcasting in terms of competing for viewership,” he said.

Read more …

“Brazil is supposed to be in the middle of its rainy season but there has been scant rainfall in the south-east and the drought shows no sign of abating.”

Brazil’s Most Populous Region Faces Worst Drought In 80 Years (BBC)

Brazil’s Environment Minister Izabella Teixeira has said the country’s three most populous states are experiencing their worst drought since 1930. The states of Sao Paulo, Rio de Janeiro and Minas Gerais must save water, she said after an emergency meeting in the capital, Brasilia. Ms Teixeira described the water crisis as “delicate” and “worrying”. Industry and agriculture are expected to be affected, further damaging Brazil’s troubled economy. The drought is also having an impact on energy supplies, with reduced generation from hydroelectric dams. The BBC’s Julia Carneiro in Rio de Janeiro says Brazil is supposed to be in the middle of its rainy season but there has been scant rainfall in the south-east and the drought shows no sign of abating. The crisis comes at a time of high demand for energy, with soaring temperatures in the summer months.

“Since records for Brazil’s south-eastern region began 84 years ago we have never seen such a delicate and worrying situation,” said Ms Teixeira. Her comments came at the end of a meeting with five other ministers at the presidential palace in Brasilia to discuss the drought. The crisis began in Sao Paulo, where hundreds of thousands of residents have been affected by frequent cuts in water supplies, our correspondent says. Sao Paulo state suffered similar serious drought problems last year. Governor Geraldo Alckmin has taken several measures, such as raising charges for high consumption levels, offering discounts to those who reduce use, and limiting the amounts captured by industries and agriculture from rivers. But critics blame poor planning and politics for the worsening situation. The opposition says the state authorities failed to respond quickly enough to the crisis because Mr Alckmin did not want to alarm people as he was seeking re-election in October 2014, allegations he disputes.

Read more …

Should be fun.

Pope Francis’s US Tour Will Set Off Economic Fireworks (Paul B. Farrell)

Pope Francis headlines are hard-hitting, targeted, staccato twitters, you get the whole truth in a series of blastings. First, starting with: “Pope Francis Has Declared War on Climate Deniers,” New Republic. Then, at the Week we read: “Republican Party’s war with Pope Francis has finally started,” Yes, 2015 is now a war zone: GOP conservatives at war with the Vatican. Then the Federalist, a conservative website, waves a red flag warning: “Don’t Pick Political Fights With Pope Francis.” Why? “Conservatives have everything to lose and nothing to gain from getting mad at Pope Francis for his public comments on homosexuality, global warming, free speech, and more.” Yes, conservatives warning Republicans: Don’t go to war with Pope Francis, you will lose.

He’s got an army of 1.2 billion faithful worldwide including 78 million American Catholics. Francis will win. A huge army. More important, Francis has a direct link to a heavenly power source. As the 266th descendent of the first leader of Christians, St. Peter, the pontiff will be touring America this fall. First stop, Philadelphia. Ring the Liberty Bell. Yes, Francis is actually on a campaign tour, selling his new economic mandate. And watch out. Behind that sweet smile and happy demeanor, this former boxer is attacking everything conservatives, capitalists, Big Oil, energy billionaires and Republicans love, cherish and believe as gospel. And they can’t defend their agenda nor counterpunch him directly.

From Philly, the pontiff’s campaign march heads for New York City where he’ll address the United Nations General Assembly, pushing his anticapitalist, anti-inequality, anti-the-superrich, anti-global warming, pro-climate-change, pro-the poor, pro-do-the-right-thing moral agenda. Then Francis will jet to Washington and our nation’s capitol, where a grumbling John Boehner and stoic Mitch McConnell have no choice but to invite Pope Francis to address a joint session of Congress. They may wish Pope Francis would quietly disappear. But that just isn’t going to happen, not after six million just attended his mass in the Philippines. He’s a seasoned campaigner, selling a powerful new economic agenda.

Read more …

Jan 212015
 
 January 21, 2015  Posted by at 11:28 am Finance Tagged with: , , , , , , , , ,  3 Responses »


DPC Cab stand at Madison Square, NY 1900

All Empires Die By Deflation – Not Inflation (Martin Armstrong)
Global Dollar Economy Hits ‘Deflationary Vortex’ (Zero Hedge)
Albert Edwards: ‘Markets Will Riot’ On Deflation (Huebscher)
QE Warfare Pushing World Financial System Out Of Control (AEP)
Fed Officials on Track to Raise Short-Term Rates Later in the Year (WSJ)
Central Bankers Lurch From ‘Whatever It Takes’ To ‘Whatever Next’ (Reuters)
Storm Clouds Gather Over US Economy: Can The Miracle Last? (CNBC)
Davos Is About More Control And Banksterism, Not Solutions: Lew Rockwell (RT)
Brokers Reveal Details Of Damage From Swiss Chaos (Independent)
Iran Oil Minister Sees ‘No Threat’ From $25 Oil (MarketWatch)
BHP Billiton Cuts US Shale Oil Rigs By 40% Amid Sliding Price (AFP)
Chinese Stocks’ Booms and Busts Getting Bigger on Margin Debt (Bloomberg)
The Era Of 7% Growth Is Over For China (CNBC)
Defiant Obama Pushes ‘Middle-Class Economics’ (Reuters)
Credit Rater S&P to Be Banned for Year From Commercial-Bond Market (Bloomberg)
If Money Speaks Louder Than Words, Is It Speech? (Reuters)
No Clear Majority Yet In EU For TTIP Trade Deal (Reuters)
Ukraine Crisis ‘Turning Point’ Close: Russian Deputy PM (CNBC)
If Christine Lagarde And Her EU Pals Are Our Friends, Who Needs Enemies? (IM)
Pope Francis: Failing to Care for Environment Is a Betrayal of God (Slate)

“This is the death-spiral of empires. They consume all wealth until none is left.”

All Empires Die By Deflation – Not Inflation (Martin Armstrong)

A lot of people have asked what to do because property taxes keep rising and they can see they are unable to retire under such circumstances. The politicians are wiping out the elderly diminishing their savings and exploiting them in every way. There are no exceptions for taxation when you sell your home as there are in Britain. You pay no tax on the profits from a primary residence there. In the USA, you are taxed until you die. and then they want what is left. Property taxes are the worst of all taxes for they prevent you from really owning your home. Can’t pay the tax – they take it and sell it for pennies on the dollar. You have to pay taxes as if you were still working so all you can do is sell and move south and then pay taxes on your gains. New Jersey even put in an exit tax on the people it has been forcing to leave.

California has been hunting former residents who moved demanding taxes on pensions claiming they earned it when living in that state. It is a wonder why we do not yet have a sea of grey hair people with guns and pitchforks storming Washington yet. This is how empires die. Taxes in Rome kept rising. Its population peaked about 180AD and as corruption began to rise, people began to leave. The higher the taxes, the more people left town. Eventually, people could not afford the taxes and were forced to just abandon their homes. This is the death-spiral of empires. They consume all wealth until none is left. Indeed, Ben Franklin got it right – our fate is always doomed by death and taxes. By the Middle Ages, the Roman Forum, was the grazing grounds for animals. Edward Gibbon wrote the best epitaph:

“Her primeval state, such as she -might–appear in a remote age, when Evander entertained the stranger of Troy, has been delineated by the fancy of Virgil. This Tarpeian rock was then a savage and solitary thicket; in the time of the poet, it was crowned with the golden roofs of a temple, the temple is overthrown, the gold has been pillaged, the wheel of Fortune has accomplished her revolution, and the sacred ground is again disfigured with thorns and brambles. The hill of the Capitol, on which we sit, was formerly the head of the Roman Empire, the citadel of the earth, the terror of kings; illustrated by the footsteps of so many triumphs, enriched with the spoils and tributes of so many nations. This spectacle of the world, how is it fallen! how changed! how defaced!

The path of victory is obliterated by vines, and the benches of the senators are concealed by a dunghill. Cast your eyes on the Palatine hill, and seek among the shapeless and enormous fragments the marble theatre, the obelisks, the colossal statues, the porticos of Nero’s palace: survey the other hills of the city, the vacant space is interrupted only by ruins and gardens. The forum of the Roman people where they assembled to enact their laws and elect their magistrates, is now enclosed for the cultivation of pot-herbs, or thrown open for the reception of swine and buffaloes. The public and private edifices that were founded for eternity lie prostrate, naked, and broken, like the limbs of a mighty giant, and the ruin is the more visible from the stupendous relics that have survived the injuries of time and fortune.”

Read more …

“..if the trade weighted dollar is appreciating, then this exerts downward pressure on the dollar economy on a near one-to-one basis.”

Global Dollar Economy Hits ‘Deflationary Vortex’ (Zero Hedge)

One of the macroeconomic observations that has gotten absolutely no mention in recent months is the curious fact that while global economic growth has not imploded in recent quarters, it is because GDP has been represented, as is customary, in local currency terms. Of course, this comes as a time when local currencies (at least those which are not the USD) have been plunging against the greenback on the back of the expectations that the Fed will hike rates some time in the summer or later in 2015. Which also means that in “dollar economy” terms, i.e., converted in USD, things are not nearly as good.

In fact, as the chart below shows, the global dollar economy is not only shrinking fast, but it is doing so at the fastest pace since the Lehman collapse, having shrunk by $4 trillion, or a whopping 5%, in just the last 6 months! By way of comparison the dollar economy lost $7 trillion, or a 10% contraction, during the Lehman crisis. Should the USD continue to appreciate, the global dollar economy collapse may surpass the plunge observed just as the great financial crisis struck. SocGen calls it “a deflationary vortex”; CNBC would call it a “global recovery.” Here is SocGen on this largely undiscussed topic with “The deflationary vortex of a shrinking dollar economy”:

As the ECB prepares to race faster in a bid to export deflation, the risk is that the dollar economy (world GDP measured in US dollars) will shrink further. The dollar economy is down by just over 5% since July, marking a loss of just over $4tn in nominal terms. The last sharp contraction of the dollar economy took place in 2008. Back then the economy shrank by just over $7tn, marking a loss in excess of 10%. The foreign trade mix of the US fairly closely mirrors the composition of world GDP. As such, if the trade weighted dollar is appreciating, then this exerts downward pressure on the dollar economy on a near one-to-one basis.

Any offset then comes from nominal GDP growth in local currency terms. Since July, the trade weighted dollar has gained just over 10%. Viewing the global economy from the vantage point of the dollar economy, it is hardly surprising that when the trade weighted dollar appreciates, commodity demand is eroded as economies with depreciating currencies lose purchasing power. To the extent that central banks actively seek currency depreciation, this could see further shrinkage of the dollar economy and add further downward pressure to commodity prices.

Read more …

“This is the year the markets really panic about deflation. You haven’t had that panic yet.”

Albert Edwards: ‘Markets Will Riot’ On Deflation (Huebscher)

Albert Edwards admits that his “uber bear” reputation is well deserved, at least with respect to equities, an asset class he has dismissed for the last 10 years. His bearishness has not abated, and for the coming year, he fears that “deflation will overwhelm the west.” Markets, he said, will riot. Edwards is the chief global strategist for Societe Generale and he spoke at that firm’s annual global strategy conference in London on January 13. Global markets face three risks, according to Edwards: bearishness in the U.S. government bond market, a flawed confidence that the U.S. is in a self-sustaining recovery and undue faith in the relationship between quantitative easing (QE) and the equity markets. Deflation is the main threat, though, according to Edwards. “This is the year the markets really panic about deflation. You haven’t had that panic yet.”

Edwards said that U.S. equities are “stuck in a secular-valuation bear market” and have been inflated by QE. Though he did not predict a recession, he said stocks would react very negatively if one were to happen. “The market embraces a recession by going to a new lower low on valuations,” he said. He offset that pessimism with a bullish view on the U.S. bond market. He said the 10-year yield could go below 1% and “converge on what is happening in Japan.” “Markets move on extreme surprises,” Edwards said, “and when expectations are so firmly held and they are shown not to be the case, you get these extreme moves.”

Read more …

“QE is not going to help at all. Europe has far greater reliance than the US on small and medium-sized companies and they get their money from banks, not from the bond market..”

QE Warfare Pushing World Financial System Out Of Control (AEP)

The economic prophet who foresaw the Lehman crisis with uncanny accuracy is even more worried about the world’s financial system going into 2015. Beggar-thy-neighbour devaluations are spreading to every region. All the major central banks are stoking asset bubbles deliberately to put off the day of reckoning. This time emerging markets have been drawn into the quagmire as well, corrupted by the leakage from quantitative easing (QE) in the West. “We are in a world that is dangerously unanchored,” said William White, the Swiss-based chairman of the OECD’s Review Committee. “We’re seeing true currency wars and everybody is doing it, and I have no idea where this is going to end.” Mr White is a former chief economist to the Bank for International Settlements – the bank of central banks – and currently an advisor to German Chancellor Angela Merkel. He said the global elastic has been stretched even further than it was in 2008 on the eve of the Great Recession.

The excesses have reached almost every corner of the globe, and combined public/private debt is 20% of GDP higher today. “We are holding a tiger by the tail,” he said. He warned that QE in Europe is doomed to failure at this late stage and may instead draw the region into deeper difficulties. “Sovereign bond yields haven’t been so low since the ‘Black Plague’: how much more bang can you get for your buck?” he told The Telegraph before the World Economic Forum in Davos. “QE is not going to help at all. Europe has far greater reliance than the US on small and medium-sized companies (SMEs) and they get their money from banks, not from the bond market,” he said. “Even after the stress tests the banks are still in ‘hunkering down mode’. They are not lending to small firms for a variety of reasons. The interest rate differential is still going up,” he said.

The warnings come just as the ECBprepares a blitz of bond purchases at a crucial meeting on Thursday. Most ECB-watchers expect QE of around €500bn now that the eurozone is already in deflation. Even the Bundesbank is struggling to come with fresh reasons to oppose it. The psychological potency of this largesse will depend on whether the ECB opts for shock-and-awe concentration or trickles out the stimulus slowly. It also depends on the exact mechanism used to conduct QE, a loose term at best. ECB president Mario Draghi hopes that bond purchases will push money out into the broader economy through a “wealth effect”, but critics fear this will be worse than useless if it leads to an asset bubble without gaining traction on the real economy. Classic moneratists say the ECB may end up spinning its wheels should it merely try to expand the money base. Mr White said QE is a disguised form of competitive devaluation. “The Japanese are now doing it as well but nobody can complain because the US started it,” he said.

Read more …

Jon Hilsenrath is the unofficial Fed bullhorn. So pay attention.

Fed Officials on Track to Raise Short-Term Rates Later in the Year (WSJ)

Federal Reserve officials are staying on track to start raising short-term interest rates later this year, even though long-term rates are going in the other direction amid new investor worries about weak global growth, falling oil prices and slowing consumer price inflation. The Fed’s stance, as it prepares for a policy meeting later this month, is striking because European Central Bank officials are poised to take the opposite approach later this week. The ECB is nearing a decision on whether to launch a controversial stimulus program known as quantitative easing on Thursday. It is widely expected to announce it will buy hundreds of billions or more of euro-denominated government bonds in an effort to beat back Japan-style deflation.

The world hasn’t seen an economic divergence like this since the mid-1990s, when growth in the U.S., Japan and Europe went in different directions. Back then, Japan was mired in a post-real-estate bubble downturn, Europe was grappling with the consequences of the collapse of the Soviet Union and the U.S. was enjoying a burgeoning technology boom. The looming moves have important implications for markets and growth. Investors have already been driving up the value of the U.S. dollar in anticipation of the moves and driving down long-term interest rates across the globe. “I think it is important to get started and to start normalizing policy,” St. Louis Fed President James Bullard said in an interview with The Wall Street Journal on Monday. “Even once we start to normalize, interest rates would be extraordinarily low.” [..]

“The level of inflation is not so low that it can alone justify a policy rate of zero,” Mr. Bullard said in a speech Friday. He wants the Fed to start raising rates by March, earlier than most other officials. San Francisco Fed President John Williams said in a speech Friday the middle of the year may still be the best time for the U.S. central bank to increase rates. Given the health of the broader economy, “what I’m really watching for is underlying inflation—wage growth, prices [..] My forecast is once we get through this slow path in inflation it will start moving back,” he said, adding, “I’m not expecting inflation to be 2% when we raise interest rates.I don’t need to be at the goal when we raise the rates.”

Read more …

“Monetary methadone..”

Central Bankers Lurch From ‘Whatever It Takes’ To ‘Whatever Next’ (Reuters)

The Swiss currency shock has raised an awkward question many investors have been fearful of asking – what if central banks become as unpredictable and fallible as they are powerful? The Swiss National Bank’s sudden decision to abandon its three-year-old cap on the franc – the “cornerstone” of its monetary policy just three days before – led to the biggest one-day move in major exchange rates in the post-1973 floating rates era. To some it was a warning sign of other U-turns, mishaps and possible failures by central banks still ahead, outcomes not fully appreciated by long-becalmed markets. For decades the power of currency printing presses has held markets in thrall. “Don’t fight the Fed” and all its international variations has been a devout belief among financial traders.

Even after the failure of Alan Greenspan’s Federal Reserve to spot and headoff one of the biggest credit booms and busts in history, the ability of the Fed, Bank of England, Bank of Japan, European Central Bank and others to flood their money supply to ease the fallout helped anaesthetise fractious markets. The subsequent waves of cheap credit, currency fixes and “quantitative easing” drove down borrowing rates and erased volatility. The demonstrations of central bank might culminated in ECB chief Mario Draghi’s declaration in 2012 that he would do “whatever it takes” to save the euro. In the face of the power of the money printing press, speculation became pointless. So much so that one of the biggest conundrums of recent years became the persistently low implied volatility in markets even in the face of outsized economic, political and policy risks.

Not everyone was pleased by the complacency. “Monetary methadone was the best of no choice but we have become addicted to cheap money everywhere and, somehow, that central bankers are prophetic,” Nigel Wilson, chief executive of UK insurer Legal & General told Reuters. The first cracks appeared last summer, when it became clear the Fed was turning off the printing presses even as counterparts in Europe and Japan were still cranking up theirs. The idea the world’s largest economy was about to suck dollars back out of the world just as others were pumping in euros and yen sent once-steady exchange rates lurching. The power of the central banks was as daunting as ever, but no longer such a reassuring and calming influence.

Read more …

No.

Storm Clouds Gather Over US Economy: Can The Miracle Last? (CNBC)

The world just got a bit scarier for risk assets. On Thursday morning, the Swiss National Bank shocked the world by removing its cap on the Swiss franc against the euro, causing its currency to soar and the euro to plunge—and creating fears about more sudden central bank moves. Meanwhile, global growth concerns continue to drive industrial commodities like copper and crude oil to multi-year lows. With the U.S. serving as one of the world’s few bastions of security and growth, the dollar continues to soar and Treasury yields are plummeting in a bid for safe havens. The question now: How long can America continue to shine in an increasingly uncertain and slow-growing world? A key clue could come in the week ahead, as a slate of major companies report their fourth-quarter results and release forward guidance.

Most closely watched will be energy companies like Halliburton and Baker Hughes, consumer discretionary names like Starbucks and McDonald’s, and industrial giants like GE. The overarching questions will be whether the soaring dollar and plunging energy prices are helping or hurting—and just how much the weakening global environment is a concern for corporate managers. “What I’m going to be watching for is some clarity from the companies in terms of the decline in the price of oil, and the decline of interest rates and the rise of the dollar,” said John Conlon, chief investment officer at People’s United Bank. “I’m going to see if there’s some consensus developing in terms of the price of oil and interest rates.”

Thus far, the “blended” estimate for fourth quarter earnings growth (which combines reported earnings with analyst estimates for yet-to-be-reported earnings) stands at a meager 0.6%, according to FactSet. That’s down from 1.7% on December 31st, mostly due to misses from Citigroup, Bank of America and JPMorgan. It’s worth noting that since more companies beat than miss, actual earnings growth tends to be prettier than the estimates. But if the growth rate does stand at 0.6% after the dust has settled, that would mark the slowest earnings growth since the third quarter of 2012, when S&P 500 companies reported an earnings decline of 1%.

Read more …

“..what they actually are doing is plotting even more wars, interventions, more economic controls, more ‘banksterism’, more benefits to the power elite versus the people”

Davos Is About More Control And Banksterism, Not Solutions: Lew Rockwell (RT)

The Davos meeting is not looking for world crisis solutions but plotting more controls, ‘banksterism’ and power elite benefits, says economic journalist Lew Rockwell. They are going to tax and rip off their own people to even greater extent, he added.

RT: The main theme of the Davos forum in the past has largely been finding solutions for world economic problems. How about today? Is it still about that?

Lew Rockwell: No, it is actually about control. I think it has always been about control for the US Empire, for the oligarchs associated with it. They may talk about wanting to solve problems, or make people’s lives better, [but] what they actually are doing is plotting even more wars, interventions, more economic controls, more ‘banksterism’, more benefits to the power elite versus the people. We don’t know what is going on there. I’d like to put chest cams on all of them so we can see what they are doing, what they are talking about. It is not good for the cause of freedom, for the cause of prosperity, not good for the cause of human rights what goes on in Davos.

RT: Let’s talk about numbers. For example, this year companies have to pay $20,000 per executive for a ticket. A simple dinner in an average restaurant was $40 last year. A night in a mid-range hotel has gone from roughly $600 to $700. Do the Forum’s participants need all these special arrangements to make an effective decision?

LR: It is a meeting of the very rich and it’s a meeting of the politicians that they own. They all live very well; they are not staying in the middle range hotels and are not eating at the regular restaurants. They are having the times of their lives; they lived the life of riley at the expense of everybody else. I don’t think we need to worry about cost to them. They are happy to spend the money. It is not theirs after all; they are taking it from the rest of us.

Read more …

“The aftermath is like a black hole that can suck massive amounts of credit from currency trading as we have known it.”

Brokers Reveal Details Of Damage From Swiss Chaos (Independent)

The UK’s biggest spread-betting firm, IG Group, said yesterday that it would “learn lessons” from last week’s stunning reversal by the Swiss National Bank (SNB), which cost it £30m. IG is nursing £18m in client losses from the SNB’s shock scrapping of the franc’s cap against the euro, as well as £12m in market exposure. IG honoured the loss limits of clients but was unable to close its hedging positions on bets because of the extreme volatility, which saw the euro tumble 30% against the “Swissie” at one stage. The company intends to maintain the dividend at last year’s level. “Although this was because of an unprecedented and unforeseeable degree of movement in a major global currency, and only a few hundred clients were affected, we will seek to learn lessons from this incident which we can incorporate into our risk-management approach,” the company said.

The Swiss blow took the gloss off strong results from the company, which has seen 1,700 clients sign up to a new stockbroking account. IG generated its highest monthly revenue in October, when global markets sank on growth fears, helping half-year profits up 2.8% to £101.4m. Another victim of the SNB’s currency earthquake, the US broker FXCM, also revealed the punishing terms of a $300m (£198m) rescue loan from investment firm Leucadia National, owner of a wide range of companies that includes broker Jefferies. FXCM will pay an eye-watering 10% annual interest on the loan, with the rate increasing by 1.5% a quarter up to a maximum of 17%, to encourage a sale of the business within three years. Leucadia will get half the proceeds on a sale of FXCM after the loan is repaid, although it will claim an even bigger share on a sale above $500m.

Danish investment bank and broker Saxo said it would incur losses from the SNB move but that its capital position was not in peril. The firm gave its clients less leverage to bet on the currency last year, reducing its exposure. Analysts said that the full impact of the scrapping of the Swiss franc-euro ceiling by the Swiss central bank won’t be known for months. “[It is] closer to a nuclear explosion than a 1,000-kilogram conventional bomb” said Javier Paz, senior analyst in wealth management at Aite Group. “The aftermath is like a black hole that can suck massive amounts of credit from currency trading as we have known it.”

Read more …

“If the oil prices drop to $25 a barrel, there will yet again be no threat posed to Iran’s oil industry..”

Iran Oil Minister Sees ‘No Threat’ From $25 Oil (MarketWatch)

Do I hear $25-a-barrel oil? Iran’s oil Minister Bijan Namdar Zanganeh hinted at even lower prices for crude as he declared his well positioned for plunging crude oil prices. “If the oil prices drop to $25 a barrel, there will yet again be no threat posed to Iran’s oil industry,” said Zanganeh at a conference in Tehran on Monday. That means the country should be sitting pretty as the OPEC sticks to its guns on production cuts. But Zanganeh also predicted that OPEC and non-OPEC countries will eventually “cooperate to restore balance to the oil market.” Wishful thinking perhaps in a situation where the market only reads: too much supply, not enough demand. On Sunday, his Iraq counterpart, Adel Abdul-Mehdi, said his country pumped out a record four million barrels per day of oil in December

Recently, billionaire Saudi businessman Prince Alwaleed bin Talal, said the market can kiss $100-a-barrel oil goodbye forever. “I said a year ago [that] the price of oil above $100 is artificial,” Alwaleed said. “It’s not correct.” Over at Project Syndicate last week, Anatole Kaletsky, a former Times of London columnist said $50 oil should really be the ceiling for a much lower price range, which could drop all the way down to $20 a barrel. “As it happens, estimates of shale-oil production costs are mostly around $50, while marginal conventional oilfields generally break even at around $20. Thus, the trading range in the brave new world of competitive oil should be roughly $20 to $50,” said Kaletsky, chief economist and co-chairman of Gavekal Dragonomics.

Read more …

“The announcement that BHP will reduce the number of US onshore oil rigs it operates by the end of this financial year is a pointer to the industry-wide supply response yet to come..”

BHP Billiton Cuts US Shale Oil Rigs By 40% Amid Sliding Price (AFP)

The world’s biggest miner BHP Billiton is cutting back its operating US shale oil rigs by 40% amid slumping prices. BHP said on Wednesday it would reduce the number of rigs from 26 to 16 by the end of the June in response to weaker oil prices. However, shale volumes were still forecast to grow by approximately 50% during the period. “In petroleum, we have moved quickly in response to lower prices and will reduce the number of rigs we operate in our onshore US business by approximately 40% by the end of this financial year,” chief executive Andrew Mackenzie said. “The revised drilling programme will benefit from significant improvements in drilling and completions efficiency.” Mackenzie said while the firm’s drilling operations would focus on its Black Hawk field in Texas, “we will keep this activity under review and make further changes if we believe deferring development will create more value than near-term production”.

Oil prices slid again Tuesday after the International Monetary Fund slashed its forecast for world economic growth and revived concerns about the strength of crude demand. US benchmark West Texas Intermediate for February sank US$2.30, or 4.7%, to US$46.39 a barrel, not far from its lowest level since March 2009. “The announcement that BHP will reduce the number of US onshore oil rigs it operates by the end of this financial year is a pointer to the industry-wide supply response on lower oil prices that is yet to come,” CMC Markets’ chief market analyst Ric Spooner said in a note. BHP added that its iron ore output had risen by 16% for the three months to December compared to a year earlier, hitting 56.4m tonnes. Prices in iron ore, one of BHP’s core commodities, slumped 47% in 2014 amid a global supply glut and softening demand from China.

Read more …

“When the tide turns, it’s going to be very ugly, because you will have a forced exit from the market.”

Chinese Stocks’ Booms and Busts Getting Bigger on Margin Debt (Bloomberg)

The one thing China’s bulls and bears can agree on is that swings in the world’s most-volatile major stock market are only going to get bigger after equity traders took on record amounts of debt. Both Bank of America strategist David Cui, who predicts Chinese shares will fall, and JPMorgans Adrian Mowat, who has an overweight rating, say the surge in margin lending to all-time highs is amplifying price fluctuations in the $4.9 trillion market. Volatility in the benchmark Shanghai Composite Index reached the highest level since 2009 this week after rising more than fourfold since July. While the flood of borrowed money into Chinese stocks added fuel to a 59% rally in the Shanghai Composite during the past 12 months through yesterday, the gauge’s 7.7% tumble on Monday illustrates how leverage can also accelerate declines.

Margin traders unloaded shares at the fastest pace in 19 months during the rout, which was sparked by regulatory efforts to cool the growth of margin debt in a market where individuals drive 80% of equity volumes. “Margin trading will add more up-and-down to the market and increase volatility,” Xie Weiyu at Shenyin & Wanguo in Shanghai, said. “If a correction starts, the magnitude will be bigger than the past few years.” In a margin trade, investors use their own money for just a portion of their stock purchase, borrowing the rest from a brokerage. The loans are backed by the investors’ equity holdings, meaning they may be forced to sell when prices fall to repay their debt.

The Shanghai Composite sank the most in six years on Monday after the China Securities Regulatory Commission suspended the nation’s two biggest brokerages from lending money to new equity-trading clients and said securities firms shouldn’t lend to investors with assets below 500,000 yuan ($80,467). Outstanding margin loans on both the Shanghai and Shenzhen exchanges surged more than tenfold in the past two years to a record 1.1 trillion yuan as of Jan. 16, or about 3.5% of the nation’s market value. On the New York Stock Exchange, margin debt amounts to about 2.1% of market cap on the NYSE Composite Index. Margin lending is a “new phenomenon in China,” said Cui, who anticipates the Shanghai Composite will fall about 5% by year-end. “When the tide turns, it’s going to be very ugly, because you will have a forced exit from the market.”

Read more …

Again: China is doing far worse than it pretends.

The Era Of 7% Growth Is Over For China (CNBC)

Brace for growth numbers starting with “6” from China this year, economists say, after data showed the world’s second largest economy expanded at its slowest pace in over two decades in 2014. China’s GDP release on Tuesday showed the economy grew 7.3% in the fourth quarter from the year-ago period, bringing growth in the full year to 7.4% – the weakest performance since 1990. “The challenges facing China’s economy remain as large or even larger compared to a year prior,” Brian Jackson, chief economist at IHS Global Insight wrote in a note, citing the cooling property sector, industrial overcapacity and high debt levels as persistent headwinds for the economy.

IHS predicts growth will moderate to 6.5% in 2015, far short of a 7% official target the government is expected to announce in March, as the government prioritizes economic reform over stimulus While December monthly indicators, including industrial production and retail sales also released Tuesday, pointed to some upward momentum in the economy, economists say this will proved short-lived. “Brief spells of accelerating Chinese growth are taking place within a larger narrative of China’s secular slowdown, a trend which bouts of mini-stimulus and lower commodity prices cannot fully reverse,” Jackson said.

For example, the pickup in industrial output growth to 7.9% on year in December, from 7.2% in November, is a result of the re-opening of factories following a temporary shutdown during the time of the Asia-Pacific Economic Cooperation (APEC) conference, according to Nomura. Of all the headwinds facing the economy, analysts expect the property sector will be the top drag for the economy in the first half of 2015. Real estate is an important pillar of the economy, accounting for approximately 15% of GDP and directly affecting dozens of other sectors from steel to construction. “Chinese growth will continue to face downward pressure because of the slowdown in property investment,” said Tommy Xie, economist at OCBC Bank, who sees growth dipping below 7% in the first-half.

Read more …

Empty.

Defiant Obama Pushes ‘Middle-Class Economics’ (Reuters)

President Barack Obama struck a defiant tone for his dealings with the new Republican-led Congress on Tuesday, calling on his opponents to raise taxes on the rich and threatening to veto legislation that would challenge his key decisions. Dogged by an ailing economy since the start of his presidency six years ago, Obama appeared before a joint session of Congress for his State of the Union speech in a confident mood, buoyed by an economic revival that has trimmed the jobless rate to 5.6% and eager to use this as a mandate. It is now time, he told lawmakers and millions watching on television, to “turn the page” from recession and war and work together to boost those middle-class Americans who have been left behind.

But by calling for higher taxes that Republicans are unlikely to approve and chiding those who suggest climate change is not real, Obama set a confrontational tone for his final two years in office. He vowed to veto any Republican effort to roll back his signature healthcare law and his unilateral loosening of immigration policy. Any attempt to increase sanctions on Iran while negotiations with Tehran over its nuclear program are still under way would also be rejected, he said. In sum, Obama appeared liberated: no longer having to face American voters again after his election victories in 2008 and 2012, a point that he reminded Republicans about. “I have no more campaigns to run,” Obama said. When a smattering of applause rose from Republicans at that prospect, he added with a tight smile: “I know because I won both of them.”

Read more …

Costly.

Credit Rater S&P to Be Banned for Year From Commercial-Bond Market (Bloomberg)

Standard & Poor’s will be suspended for a year from rating bonds in one of its most lucrative businesses in a $60 million settlement with the U.S. Securities and Exchange Commission, according to a person with knowledge of the matter. The deal, which the person said may be announced as soon as tomorrow, is the agency’s toughest action yet in an industry blamed for fueling the 2008 financial crisis by assigning inflated grades to risky mortgage debt. Instead of securities created during that period, though, the SEC’s investigation has looked at whether S&P bent its criteria to win business on commercial-mortgage bonds issued in 2011.

The suspension will ban S&P from rating debt in the biggest portion of that market, those that bundle multiple loans tied to anything from shopping malls to skyscrapers, into securities that are sold to bond investors, according to the person, who asked not to be identified because the discussions are private. In addition to the SEC fine, the unit of McGraw Hill is also facing a penalty to settle probes of the same ratings by Attorneys General in New York and Massachusetts, said the person and a second with knowledge of the talks. The CMBS probe is separate from a lawsuit by the Justice Department tied to subprime home loans that S&P rated before the credit crisis. S&P is expected to settle that matter as soon as this quarter for about $1 billion in penalties, people familiar with the matter said this month.

Read more …

” One has a right, for example, to procreative liberty — yet no right to buy a baby. Money would help some people exercise these rights, too. But we don’t treat laws restricting baby selling as if they were restricting procreative liberty.”

If Money Speaks Louder Than Words, Is It Speech? (Reuters)

Citizens United may have been just what the United States needed — a decision by the U.S. Supreme Court so dramatically wrongheaded that people across the country paid attention to it and said, “Hold on, something is wrong here.” Though the actual ruling simply extended the flawed approach to campaign-finance laws that the court had been following for decades, Citizens United shined a light on the justices’ reasoning and demonstrated its shortcomings by taking that rationale to its logical — if absurd — conclusion. The Supreme Court treats restrictions on both giving and spending money on elections as restrictions on “speech” under the First Amendment. While the case law has been dotted with victories for both advocates and opponents of campaign-finance restrictions over the past 40 years, it is vital to step back and look at the bigger picture.

In the seminal 1976 campaign-finance case, Buckley v. Valeo, the court laid out the line of reasoning relied on ever since. Buckley said that restrictions on giving and spending money in politics should be treated as if they are restrictions on speech. This approach was not obvious or uncontroversial. Campaign-finance laws do not “prohibit” speech — using the word in its ordinary way. Rather, they restrict giving and spending money used on political speech. The decision to treat campaign-finance laws as restrictions on speech was based on the argument that money facilitates speech. “[V]irtually every means of communicating ideas in today’s society requires the expenditure of money,” the court argued. Though that may be somewhat less true today — given the Internet — it is still largely correct.

What this rationale misses is that money facilitates speech not because there is any special connection between the two, but because money is useful stuff. It facilitates the exercise of many other constitutionally protected rights, as well as the fulfillment of many goals and interests. Yet, and here’s the important part, no one — and especially not this Supreme Court — is likely to conclude that restrictions on spending money in connection with the exercise of all other rights would violate these rights. One has a right, for example, to procreative liberty — yet no right to buy a baby. Money would help some people exercise these rights, too. But we don’t treat laws restricting baby selling as if they were restricting procreative liberty.

Read more …

Here’s how you spell democracy in Europe today: “The EU has said the final wording would, however, remain confidential until an agreement was reached..”

No Clear Majority Yet In EU For TTIP Trade Deal (Reuters)

No clear majority has so far emerged among EU states for a free-trade agreement between the European Union and the United States and both sides need to explain the benefits of such a deal, the EU’s health chief said. Chancellor Angela Merkel has urged the 28-nation EU to speed up negotiations with the United States on what would be the world’s biggest trade deal. But there is public opposition in Europe based on fears of weaker food and environmental standards. “We have to take people’s concerns seriously,” Vytenis Andriukaitis, European commissioner for health and food safety, told German daily Tagesspiegel, adding that the trade agreement ultimately needed to be ratified by all national parliaments.

“At the moment, I don’t see a safe majority for this yet,” he said in an interview published on Monday, adding the EU Commission had published some negotiating papers to improve transparency. The EU has said the final wording would, however, remain confidential until an agreement was reached on the Transatlantic Trade and Investment Partnership (TTIP). Negotiations for the TTIP were launched in July 2013 and officials are seeking a deal that goes well beyond trade to remove barriers to businesses. There is concern in Europe that U.S. multinationals would use a proposed investment protection clause to bypass national laws in EU countries. In Berlin, more than 25,000 people joined a rally against the TTIP and genetically modified food over the weekend.

Read more …

Went to Diplomat School: “Russia is interested in stabilizing the situation globally and in Ukraine in particular..”

Ukraine Crisis ‘Turning Point’ Close: Russian Deputy PM (CNBC)

The conflict over Ukraine’s borders with Russia, which has soured Moscow’s relationship with the West and stirred up new concerns about global unrest, may be close to a “turning point”, according to Arkady Dvorkovich, Russia’s deputy Prime Minister. “Russia is interested in stabilizing the situation globally and in Ukraine in particular,” Dvorkovich told CNBC at the World Economic Forum in Davos, where he is one of Russia’s most senior representatives after both President Vladimir Putin and Prime Minister Dmitry Medvedev declined to make the trip. He extended the possibility of reducing the price of gas to Ukraine, after Russia hiked it earlier in the conflict. This week, military activity in Donetsk and Luhansk, the disputed parts of eastern Ukraine where Russian-backed militants are battling the Ukrainian army, had escalated after falling back over Christmas and New Year.

Petro Poroshenko, the Ukrainian President, who came to power last year, has acknowledged this week that a military solution to the fighting, which has claimed nearly 5,000 lives so far, does not exist. Economic sanctions enacted by Western countries against Russia, following the outbreak of conflict, combined with the falling price of oil and gas, its biggest export, and a tumbling ruble, have helped send the country into economic turmoil. Nonetheless, Dvorkovich argued that thanks to the country’s currency reserves “we have the resources to keep the economy in a relatively normal stance.” “We have resources, we have an anti-crisis plan.” There has also been a lack of external investment in Russia, as Western companies are concerned that they may fall foul of current or future sanctions. But Dvorkovich dismissed this, arguing “CEOs of foreign companies are all saying that they will continue investments in Russia, with the ruble at this low level.”

Read more …

“Christine Lagarde must be smiling to herself and thinking we are thick Paddies alright.”

If Christine Lagarde And Her EU Pals Are Our Friends, Who Needs Enemies? (IM)

There is nothing worse than a posh bird arriving into town and insulting the intelligence of the natives. That’s exactly what IMF chief Christine Lagarde did yesterday. She and her friends in Europe robbed around €10,000 a year out of the pocket of every Irish citizen to save the rich on the continent and to ensure no French or German bank would collapse for lending to the bankrupt Irish banks. And then she has the cheek to tell us we are the real heroes of the recovery. What’s even worse, our Taoiseach Enda Kenny stood there applauding her as she praised the victims of brutal austerity. If Lagarde and her cohorts from Europe can be classed as friends, who needs enemies? This country is sick to death of being the best boys and girls in the class in the EU. Let’s tell the truth Brussels couldn’t give a damn about us and never will. They will protect the euro at any cost and we as a nation paid a horrendous price. We have been landed with debt that will take generations to clear, if ever.

The whole crisis set this country back 20 years. Not one treacherous banker has gone to jail. Not one politician or civil servant has been held to account for horrendous decisions taken on the night of the bank guarantee. Europe has been a failure for the Republic of Ireland, they hung this country out to dry. So lets start having the debate about it. There is also no recovery here yet – very few people have any spare cash. The country is taxed to the hilt and the working man and woman is surviving by the skin of the teeth. That’s why the water charge was a tax too far and the people took to the streets. Our politicians are still living in a Leinster House bubble. They may mean well but the majority of them haven’t a clue what’s going on in the real world. They have no vision where Ireland is going it is all a game of retaining power. Christine Lagarde must be smiling to herself and thinking we are thick Paddies alright.

Read more …

“Respect for the environment means more than simply using cleaner products or recycling what we use.”

Pope Francis: Failing to Care for Environment Is a Betrayal of God (Slate)

Pope Francis has been wading into environmental issues during his week-long Asian tour, but he issued the strongest words on Sunday, when he said that man was betraying God’s calling by destroying nature. Or at least that’s what he was supposed to say at a rally with young people at a university in Manila. But the pope ended up being moved by the story of an abandoned girl so he improvised a speech. Still, the Vatican has said that when the pope decides to improvise, the prepared text is official, notes Reuters. “As stewards of God’s creation, we are called to make the earth a beautiful garden for the human family,” the pope said in the prepared text. “When we destroy our forests, ravage our soil and pollute our seas, we betray that noble calling.” The pope also pointed out that youth in the Philippines should feel a special obligation to care for the environment.

“This is not only because this country, more than many others, is likely to be seriously affected by climate change,” he said in the prepared text. “You are called to care for creation not only as responsible citizens, but also as followers of Christ!” He also appeared to chastise those who think that simply by buying environmentally friendly products and recycling they are doing enough for the cause. “Respect for the environment means more than simply using cleaner products or recycling what we use. These are important aspects, but not enough,” he said. God “created the world as a beautiful garden and asked us to care for it,” Francis said. “Through sin, man has disfigured that natural beauty. Through sin, man has also destroyed the unity and beauty of our human family, creating social structures that perpetuate poverty, ignorance and corruption.”

Read more …

Jan 162015
 
 January 16, 2015  Posted by at 11:36 am Finance Tagged with: , , , , , , , , ,  6 Responses »


Earl Theisen Walt Disney oiling scale model locomotive at home in LA Sep 1951

Swiss Mess Could Make Oil Plunge Seem Like Minor Hiccup (MarketWatch)
World Deflationary Forces Have Swept Away Switzerland’s Defences (AEP)
Switzerland Shows The Era Of Central Bank Omnipotence Is Over (Krasting)
Swiss Franc Move Cripples, Wipes Out Currency Brokers (WSJ)
Wall Street Is Bracing For Shock Waves From Swiss Franc Move (MarketWatch)
Franc’s Surge Ranks Among Largest Ever in Foreign Exchange (Bloomberg)
Swiss Bankers Are Accelerating the Euro’s Slide (Bloomberg)
In Praise Of Price Discovery – The Market Is Off Its Lithium (David Stockman)
Iran Lowers Oil Price for Budget to $40 After Collapse (Bloomberg)
BP Sees $50 Oil For Three Years (BBC)
$50 Oil Is The Ceiling For A Much Lower Trading Range (Anatole Kaletsky)
Big Oil Gets Serious With Cost Cuts on Worst Slump Since 1986 (Bloomberg)
Schlumberger Cuts 9,000 Jobs as Oil Slump Portends Uncertainty (Bloomberg)
Aberdeen, The Energy-Rich Town Counting The Cost Of The New Oil Shock (Guardian)
Greek Systemic Banks Request Emergency Liquidity Assistance (Kathimerini)
No Risk Of ‘Deflation Spiral’ In Europe: German Minister (CNBC)
UK Retailers ‘Throttled’ By Black Friday (Daily Mail)
Warning: China May Trigger Fresh Rout In Commodities (CNBC)
China Shadow Banking Surge Chills Stimulus Hopes (CNBC)
New Russian/Chinese Credit Rating Agencies To ‘Balance Big Three’ (RT)
Ukraine President Poroshenko Signs Decree To Mobilize Up To 100,000 (TASS)
‘Corporate Wolves’ Will Exploit TTIP Trade Deal, MPs Warned (Guardian)
Pope Francis Says Freedom Of Speech Has Limits (BBC)

Anything could blow now.

Swiss Mess Could Make Oil Plunge Seem Like Minor Hiccup (MarketWatch)

One day, it’s gold. The next, it’s equities. Most days, it’s crude. On Wednesday, it was copper. On Thursday it was the Swiss franc and Swiss stocks. And the move in those two makes those others look like minor-league hiccups. While you were sleeping, all hell broke loose in Switzerland, as the central bank ditched its currency cap against the euro after four years and slashed interest rates to negative 0.75%. The Swiss franc is rallying wildly, while the Swiss stock market is cratering and U.S. stock futures are mostly on the losing side as investors figure out this latest shock to the markets Meanwhile, collapsing oil is claiming its next batch of victims. Apache just became the first, and certainly not the last, big-name oil producer to cut a notable number of jobs. And Calgary is suffering through it’s worst decline in home prices in almost two years. Airlines stocks aren’t even benefiting anymore.

So where’s that cheap oil upside? Perhaps, it’s in the opportunity created in solar stocks. The best thing that can be said about oil at this point is that, hey, at least it’s not bitcoin. Or the ruble. More fallout to come if $50 does, indeed, turn out to be a ceiling and if, as Goldman Sachs says, prices fall below the bank’s $39 target.

Read more …

Ambrose gets it right: deflation.

World Deflationary Forces Have Swept Away Switzerland’s Defences (AEP)

The Swiss National Bank has lost control. It is the latest in a list of venerable central banks to be overwhelmed by deflationary forces and global economic disorder. The country is already in deflation. The Swiss franc ended Thursday 13% higher after the SNB abandoned its three-year efforts to defend a currency floor of 1.20 to the euro. “We have a free exchange rate once again,” said the SNB’s president, Thomas Jordan. Indeed, but nobody is fooled by the SNB’s attempt to spin this as benign. “This is a huge hit to their credibility,” said Deutsche Bank. The official statement claimed that the exchange floor is no longer needed and that “overvaluation has decreased as a whole since the introduction of the minimum exchange rate”. This is eyewash. “They have had to throw in the towel. They couldn’t hold the line anymore,” said David Owen, from Jefferies Fixed Income.

“This is going to cause extreme pain for parts of the Swiss economy but SNB are trapped.” The franc has been level over the past year on a trade-weighted basis. Even before Thursday morning’s events, the exchange rate was 25% above its decade-long average. It is now 40% higher. Just one month ago the SNB argued in its quarterly report that currency floor was imperative to stop Switzerland relapsing back into deflation. “In view of heightened deflation risks, the minimum exchange rate remains the key instrument for ensuring appropriate monetary conditions. A further appreciation of the Swiss franc would have a major impact on salary and price structures. Companies in Switzerland would be forced to cut costs drastically again to remain competitive.” The statement was true then. The threat is much greater now, made all too clear by the howls of protest this morning from the Swiss export sector.

Nick Hayek, head of Swatch Group, said the collapse of the floor would cause havoc. “Words fail me. Today’s SNB action is a tsunami; for the export industry and for tourism, and for the entire country,” he said. The Swiss economy has been muddling through over the past year but the output gap is still -1% of GDP, inflation is negative and the KOF index of business sentiment has been slipping lower for two years. On top of this, the country now has to grapple with the likely hangover from its own domestic credit bubble. The SNB’s Mr Jordan said the end of an exchange floor inevitably requires subterfuge. “You can only end a policy like this by surprise. It is not something you can debate for weeks,” he said. That may be true. Less justifiable is the failure to come clean after the event and explain exactly why the SNB now judges the damage of eternal currency intervention to be even more dangerous than the threat of a systemic deflationary shock. We are left guessing.

Read more …

It was always but an illusion, though.

Switzerland Shows The Era Of Central Bank Omnipotence Is Over (Krasting)

I wrote about the Swiss National Bank being forced to abandon its currency peg to the Euro on 12/3/14, 12/8/14 and 1/11/15. That said, I’m blown away that this has happened today. Thomas Jordan, the head of the SNB has repeatedly said that the Franc peg would last forever, and that he would be willing to intervene in “Unlimited Amounts” in support of the peg. Jordan has folded on his promise like a cheap suit in the rain. When push came to shove, Jordan failed to deliver. The Swiss economy will rapidly fall into recession as a result of the SNB move. The Swiss stock market has been blasted, the currency is now nearly 20% higher than it was a day before. Someone will have to fall on the sword, the arrows are pointing at Jordan.

The dust has not settled on this development as of this morning. I will stick my neck out and say that the failure to hold the minimum rate will result in a one time loss for the SNB of close to $100B. That’s a huge amount of money. It comes to 20% of the Swiss GDP! If this type of loss were incurred by the US Fed it would result in a loss in excess of $2 Trillion! In the coming days and weeks there will be more fallout from the SNB disaster. There will be reports of big losses and gains from today’s events. But that is a side show to the real story. We have just witnesses the collapse of a promise by a major central bank. The Fed, Bank of Japan, ECB, SNB and other Central Banks have repeatedly made the same promises over the past half decade:

Don’t worry! We are here. We will do anything it takes to achieve the stability we desire. We are stronger than the markets. We can overwhelm all forces. We will never let go – just trust us!

I never believed in these promises, but the vast majority of those who are active in financial markets did. The entire world has signed onto the notion that Central Banks are all powerful. We now have evidence that they are not. Anyone who continues to believes in the All Powerful CB after today is a fool. Those who believed in Jordan’s promises now have red ink on their hands – lots of it! The next central bank that will come into the market’s cross hairs is the ECB. Mario Draghi has made promises that he would “Do anything – in any amount”. Like I said, you would be a fool to continue to believe in that promise as of this morning. We’ve just taken a huge leap into chaos. The linchpin of the capital markets has been the trust in the CBs. The market’s anchors have now been tossed overboard.

Read more …

“Where a client cannot cover this loss, it is passed on to us. This has forced Alpari (UK) Limited to confirm…that it has entered into insolvency ..”

Swiss Franc Move Cripples, Wipes Out Currency Brokers (WSJ)

A major U.S. currency broker warned its equity was wiped out, a U.K. retail broker entered insolvency and a global foreign-exchange trading house failed after suffering big losses sparked by the Swiss central bank’s move to free up its currency. On Friday, regulators in Japan, Hong Kong, Singapore and New Zealand sought information from brokers about what happened. In Japan, the Finance Ministry was checking on trading firms after industry sources said the country’s army of mom-and-pop foreign exchange traders suffered big losses. The losses were caused when liquidity dried up and volatility spiked in the debt-driven foreign exchange market, making it impossible for brokers to execute trades as losses spiraled. Many of these brokers offer 100-to-1 leverage, meaning a 1% loss can wipe a client out.

The Swiss franc jumped 30% against the euro in minutes on Thursday, after the Swiss National Bank stopped capping the rise their nation’s currency against the euro. The surprise move sent the Swiss franc soaring and caused big losses for traders who had bet against the currency. FXCM, the biggest retail foreign-exchange broker in the U.S. and Asia, said in a statement that because of unprecedented volatility in the euro against the Swiss franc, its losses left it with a negative equity balance of about $225 million and that it was trying to shore up its capital. FXCM was operating normally in Hong Kong on Friday with employees trying to sort out trading positions and answer questions from clients about their trading losses. “As a result of these debit balances, the company may be in breach of some regulatory capital requirements.

We are actively discussing alternatives to return our capital to levels prior to today’s events and discussing the matter with our regulators,” the company, which has a market capitalization of about $701.3 million, said in a statement. Shares of the company fell 15% in U.S. trading and tumbled another 12% after hours. In the U.K., retail broker Alpari entered insolvency after racking up losses amid the currency turmoil following the SNB’s decision. Alpari said in a statement on its website that a majority of its clients sustained losses exceeding the equity in their accounts. “Where a client cannot cover this loss, it is passed on to us. This has forced Alpari (UK) Limited to confirm…that it has entered into insolvency,” the firm said.

Read more …

““We expect that few risk-management algorithms in G-20 currencies were prepared for greater than 20% moves in a currency pair ..”

Wall Street Is Bracing For Shock Waves From Swiss Franc Move (MarketWatch)

Don’t be too quick to look past the turmoil that swept global financial markets after Switzerland’s central bank unexpectedly scrapped a cap on the value of its currency versus the euro. While European and U.S. equities largely regained their footing after a panicky round of selling in the wake of the decision, dangers may still lurk in some corners of the market. Here are the potential shock waves to look out for:

Needless to say, the Swiss franc, which had long been held down by the Swiss National Bank’s controversial cap, exploded to the upside. The euro is down 15% and the U.S. dollar remains down nearly 14% versus the so-called Swissie after having plunged even further in the immediate aftermath of the move. See: Swiss stunner sends euro to 11-year low against buck. Since the Swiss National Bank had given no indication it was set to move — indeed, it had previously said it would defend the euro/Swiss franc currency floor with the “utmost determination” — investors were holding large dollar/Swiss franc and euro/Swiss franc long positions, noted George Saravelos, currency strategist at Deutsche Bank, in a note. As a result, the moves Thursday likely resulted in some big losses on investor portfolios holding those positions, he said.

“This effectively serves as a large VaR [value-at-risk] shock to the market, at a time when investors were already sensitive to poor [profit-and-loss] performance for the year,” Saravelos wrote. The Wall Street Journal reported that Goldman Sachs on Thursday closed what had previously been one of its top trade recommendations for 2015: shorting the Swiss franc versus the Swedish krona after the franc jumped as much as 14% on the day versus its Swedish counterpart. Douglas Borthwick, managing director at Chapdelaine Foreign Exchange, said forex participants are bracing for aftershocks. “We expect that few risk-management algorithms in G-20 currencies were prepared for greater than 20% moves in a currency pair, for this reason the chance of a binary outcome is significant,” he said, in a note. “Either participants gained or lost considerable amounts.”

Read more …

“It’s normal for ruble to do this kind of thing, but we’re talking about Swiss franc ..”

Franc’s Surge Ranks Among Largest Ever in Foreign Exchange (Bloomberg)

The Swiss franc’s 41% surge after the central bank unexpectedly lifted its cap against the euro is one of the biggest moves among major currencies since the collapse of the Bretton Woods system in 1971. Unlike previous foreign-exchange upheavals, today’s action occurred to one of the most-traded currencies that is considered a haven in tumultuous times, and few saw the move coming. “It’s normal for ruble to do this kind of thing, but we’re talking about Swiss franc,” Axel Merk, president and founder of Merk Investments, who has 20 years of experience in the currency market. “That’s quite extraordinary and unheard of.” A history of some of the biggest moves in the now $5.3 trillion a day market:

• Mexico Tequila Crisis, December 1994: U.S. interest-rate increases helped spark a peso devaluation and fueled capital flight across Latin America. The peso lost 53% in three months. The recession the following year, when the economy contracted 6.2%, was among the worst since the 1930s.

• Thai baht, July 1997: The currency fell 48% over the second half of the year after the central bank devalued its the baht in an attempt to revive its slumping economy, marking one of the biggest shifts in Asian currency policy since the country last devalued its currency in 1984.

• Japanese yen, October 1998: During the Asian Financial Crisis, the Japanese currency rallied as much as 7.2% in a day as hedge funds rushed to unwind carry trades by repaying the yen that they borrowed to invest in higher-yielding currencies such as the Thai baht and Russia’s ruble. The yen surged 16% that week.

• Turkish lira, 2001: A spat between then-President Ahmet Necdet Sezer and Prime Minister Bulent Ecevit led to an exodus of foreign capital, pushed up government debt and throwing more than 20 banks into bankruptcy. The currency lost 54% in value that year and inflation jumped to 69% by December.

• Argentine peso, June 2002: Argentina started struggling to finance its debt in 1999 as the one-to-one peg to a rising dollar squeezed exporters and Brazil, the country’s largest trading partner, devalued the real. Interim President Adolfo Rodriguez Saa announced to default on $95 billion debts in December 2001. Within weeks, the central bank abandoned the peg, allowing the peso to fall 74% by June 2002.

• Russian Ruble, December 2014: The currency plummeted 34% in three weeks through mid-December as plunging oil prices and international sanctions pushed Russia toward a recession. The central bank has spent $95 billion of foreign reserves over the past year to shore up the ruble and boosted interest rate five times. While the efforts helped quell volatility, the ruble remains within 5% of the record low set on Dec. 16.

Read more …

Not too crazy so far.

Swiss Bankers Are Accelerating the Euro’s Slide (Bloomberg)

The euro is shaping up as the biggest casualty of Switzerland’s decision to scrap its currency cap. Soon after the Swiss National Bank unexpectedly decided yesterday to end its three-year policy of keeping the franc from appreciating beyond 1.20 per euro, bearish bets on Europe’s common currency soared. While setting a record low versus the franc, the euro also plunged 3.5% against a basket of 10 developed-nation peers, the most since its 1999 debut. The SNB’s decision removes a key pillar of support for the euro, boosting the odds that its recent slide will accelerate. Companies from Goldman Sachs to Pimco have in recent days talked about the increasing chance the euro falls to parity with the dollar, which would represent a 14% decline from its current level.

“It adds fuel to the fire,” Atul Lele, the chief investment officer of Deltec International Group, who manages $1.9 billion, said by phone from Nassau, Bahamas. “This move out of Switzerland certainly exacerbates the trade-weighted euro weakness that we expect to see.” The difference in the cost of options to sell Europe’s common currency against the dollar, over those allowing for purchases, jumped by the most in almost two years yesterday. The euro dropped 1.3% to $1.1633 yesterday. In defending its cap on the franc, the SNB almost doubled its holdings of the 19-nation currency to 174.3 billion euros ($203 billion) since September 2011.

Speculation the European Central Bank is only days away from announcing a government-bond purchase program, or quantitative easing, at its Jan. 22 meeting had already weakened the euro against its major peers. The euro also sank below parity with the franc yesterday to an all-time low of 85.17 centimes, before recovering to 1.0096 per euro today. Deltec’s Lele said he sees it falling an additional 5% to 10%. “The euro can’t find a friend for love nor money,” said London-based Kit Juckes, a strategist at Societe Generale SA, which predicts a decline to $1.14 by year-end. When one of the biggest buyers of euros “leaves the building,” losses are inevitable, he said.

Read more …

Stockman addresses the same issue, the return of price discovery, that I did yesterday in The End Of Fed QE Didn’t Start Market Madness, It Ended It.

In Praise Of Price Discovery – The Market Is Off Its Lithium (David Stockman)

This morning’s market is more erratic than Claire Danes off her lithium. Gold is soaring, the euro’s plunging, US treasury yields are in free fall, junk bonds are faltering, copper is bouncing, oil has rolled over, the Russell 2000 momos are getting mauled, the swissie has shot the moon, the Dow is knee-jerking down, correlations are failing……and the robo traders are flat-out lost. All praise the god of price discovery! For six years financial markets have been drugged into zombiedom by maniacal central bankers who have violated every known rule of sound money and financial market honesty. In expanding their collective balance sheets from $5 trillion to $16 trillion over the past decade, for instance, they have midwifed a planet-wide fiscal fraud.

Politicians have been enabled to spend and borrow like never before because central banks have swapped trillions of public debt for electronic cash confected from nothing. Likewise, never have carry traders and gamblers been so egregiously pleasured by the state. After 73 straight months of ZIRP they are still pinching themselves, wondering if such stupendous largesse is real. They have bought anything with a yield and everything with prospect of gain, financed it for nothing and collected the arb – while being swaddled in the Fed’s guarantee that it would never surprise them or perturb their trades with unannounced money market rate changes. And so they wallowed in their windfalls, proclaiming their own genius.

Does a pompous dandy like Bill Ackman end up purchasing an absurdly priced $90 million Manhattan condo just “for fun” because markets operate on the level? Do his petulant brawls with other grand “activist” speculators like Carl Icahn mark investment genius or the machinery of honest capitalism at work? No they don’t. There is absolutely nothing honest, productive or fair about the central bank dominated casinos which have morphed out of what used to be legitimate money and capital markets. Indeed, all the requisites of stability, efficiency and honest price discovery have been destroyed by the monetary central planners. The short sellers have been eradicated. Downside insurance against a broad market swoon has become dirt cheap. Momo traders have thereby been enabled to earn unconscionable returns because their carry costs have been negligible and their hedging expenses nearly nothing.

Read more …

“Saudi Arabia, the biggest producer, is probably assuming $80 ..”

Iran Lowers Oil Price for Budget to $40 After Collapse (Bloomberg)

Iran, its oil exports curbed by sanctions, is lowering the crude price for this year’s budget to $40 a barrel as the energy slump affects governments and industry. The government is revising its draft budget to assume a base price of $40, from $72, the state-run Fars News Agency reported Finance and Economy Minister Ali Tayebnia as saying Jan. 15. The minister said some projects will have to be halted, according to Fars. Iran’s calendar year begins March 21. Prices of Brent, a benchmark for more than half the world’s oil, have dropped about 50% in the past year, forcing governments to reduce subsidies on diesel, natural gas and utilities and companies to cut billions from capital budgets. Qatar Petroleum and Shell called off plans to build a $6.5 billion petrochemical plant.

“Most Gulf countries are pricing $50 oil for 2015,” said Naeem Aslam, chief market analyst at Dublin-based Avatrade Ltd. in a phone interview from Dubai. “Creditors want to be sure they recoup their money so there could be hesitation to starting up new projects.” Iran President Hassan Rouhani presented a budget to lawmakers on Dec. 7 based on $72 oil. Since then, Brent crude has dropped about 30%. It budgeted $100 oil last year. [..] Iraq, the second-biggest member of OPEC, is using $60 in its budget. Saudi Arabia, the biggest producer, is probably assuming $80, according to John Sfakianakis, a former Saudi government economic adviser. Kuwait has propsed basing its 2015-16 budget on oil at $45.

Read more …

Makes you wonder how BP itself will survive.

BP Sees $50 Oil For Three Years (BBC)

BP’s job announcement later today, including a few hundred job losses in Aberdeen, is being made because it does not expect the oil price to bounce any time soon. The oil price has dropped around 60% since June, to $48 a barrel, and I understand that BP expects that it will stay in the range of $50 to $60 for two to three years. Although no oil company has a crystal ball, this matters – especially since it has a big impact on its investment and staffing ambitions. So plans that it had already initiated to reduce costs have taken on a new element, namely postponement of investments in new capacity that have not been started, and shelving of plans to extend the life of older fields where residual oil is more expensive to extract.

Aberdeen is an important centre for BP, and it employs around 4000 there. And it is in no sense withdrawing – it is continuing to invest in the Greater Clair and Quad 204 offshore properties. But the reduction of several hundred in the numbers it will henceforth employ in the Aberdeen area is symbolic of a city and industry that faces a severe recession. Hardest hit will be North Sea companies with stakes in older fields, where production costs are on a rising trend – and whose profitable life will be significantly shortened if the oil price does not recover soon. The reason BP expects the oil price to stay in the range of $50 to $60 for some years is for reasons you have read about here – it is persuaded that the Saudis, Emiratis and Kuwaitis are determined to recapture market share from US shale gas.

This means keeping the volume of oil production high enough such that the oil price remains low enough to wipe out the so-called froth from the shale industry – to bankrupt those high-cost frackers who have borrowed colossal sums to finance their investment. This does not simply require some US frackers to be bankrupted and put out of business, but also that enough banks and creditors are burned such that the supply of finance to the shale industry dries up. Only in that way could Saudi could be confident of reinvigorating its market power.

Read more …

The end of major parts of the industry.

$50 Oil Is The Ceiling For A Much Lower Trading Range (Anatole Kaletsky)

If one number determines the fate of the world economy, it is the price of a barrel of oil. Every global recession since 1970 has been preceded by at least a doubling of the oil price, and every time the oil price has fallen by half and stayed down for six months or so, a major acceleration of global growth has followed. Having fallen from $100 to $50, the oil price is now hovering at exactly this critical level. So should we expect $50 to be the floor or the ceiling of the new trading range for oil? Most analysts still see $50 as a floor – or even a springboard, because positioning in the futures market suggests expectations of a fairly quick rebound to $70 or $80. But economics and history suggest that today’s price should be viewed as a probable ceiling for a much lower trading range, which may stretch all the way down toward $20.

To see why, first consider the ideological irony at the heart of today’s energy economics. The oil market has always been marked by a struggle between monopoly and competition. But what most western commentators refuse to acknowledge is that the champion of competition nowadays is Saudi Arabia, while the freedom-loving oilmen of Texas are praying for OPEC to reassert its monopoly power. Now let’s turn to history – specifically, the history of inflation-adjusted oil prices since 1974, when OPEC first emerged. That history reveals two distinct pricing regimes. From 1974 to 1985, the US benchmark oil price fluctuated between $50 and $120 in today’s money. From 1986 to 2004, it ranged from $20 to $50 (apart from two brief aberrations after the 1990 invasion of Kuwait and the 1998 Russian devaluation).

Finally, from 2005 until 2014, oil again traded in the 1974-1985 range of roughly $50 to $120, apart from two very brief spikes during the 2008-09 financial crisis. In other words, the trading range of the past 10 years was similar to that of OPEC’s first decade, whereas the 19 years from 1986 to 2004 represented a totally different regime. It seems plausible that the difference between these two regimes can be explained by the breakdown of OPEC power in 1985, owing to North Sea and Alaskan oil development, causing a shift from monopolistic to competitive pricing. This period ended in 2005, when surging Chinese demand temporarily created a global oil shortage, allowing OPEC’s price “discipline” to be restored.

Read more …

Just the start.

Big Oil Gets Serious With Cost Cuts on Worst Slump Since 1986 (Bloomberg)

Major oil companies are awaking from their slumber and facing up to the magnitude of the crash in crude prices. From Shell canceling a $6.5 billion project in Qatar to Schlumberger firing about 9,000 people and Statoil giving up exploration in Greenland, the oil industry this week concluded that the slump is no blip. Top producers follow U.S. shale developers such as Continental in unraveling a boom that produced more oil and natural gas than the world is ready to buy. And there’s certainly more unwinding to come. For most of this month, crude oil has traded below $50 a barrel, a level few predicted even two months ago when OPEC signaled it wouldn’t cut production to defend prices.

If the market stays this depressed, global spending on exploration and production could fall more than 30%, the biggest drop since 1986, according to forecasts from Cowen. “Not too many people expected these levels of oil prices, not even the companies themselves,” said Dragan Trajkov, an analyst at Oriel in London. “Now they have to deal with this new situation and the first impact will be on new investments.” Shell, BP, Chevron and other top producers are preparing to present 2014 earnings to investors at the end of this month or early February and will signal plans for this year. Their chief executive officers are faced with the challenge of assuring shareholders they can see through the depression without cutting dividend payments. The direction of the oil market shows companies probably need to prepare for the worst.

Bank of America, noting the speed global oil inventories are building, forecast Thursday that Brent futures are set to fall to as low as $31 a barrel by the end of the first quarter from about $48 now. That’s even lower than the $36.30 seen during the depths of 2008’s financial crisis. Oil traded above $100 a barrel in July and analysts forecast prices would stay there for years to come. The scale and speed of the price drop has forced companies to start making significant decisions. Shell, Europe’s largest oil company, took the axe this week to a $6.5 billion petrochemicals plant it planned to build in Qatar in partnership with the state oil producer. The company, based in The Hague, said the project wasn’t economically feasible in the current price environment.

Read more …

“Energy companies are expected to cut spending in the U.S. by as much as 35% this year ..”

Schlumberger Cuts 9,000 Jobs as Oil Slump Portends Uncertainty (Bloomberg)

Schlumberger, the world’s biggest oilfield-services company, tackled the “uncertain environment” of plummeting crude prices head-on by cutting 9,000 jobs and lowering costs at a vessels unit. The 7.1% workforce cutback, along with the reduction and reassessment of its WesternGeco fleet, were among steps leading to a $1.77 billion fourth-quarter charge in anticipation of lower spending by customers in 2015, the Houston- and Paris-based company said in an earnings report Thursday. Energy companies, coping with oil worth less than half its price six months ago, are expected to cut spending in the U.S. by as much as 35% this year, according to Cowen. The number of onshore U.S. rigs could fall by as much as 750 this year, Wells Fargo said. That would be a 43% decline from the 1,744 in operation at the start of the year, according to Baker Hughes. The coming year “is looking like it’s gonna be pretty rough,” Rob Desai, an analyst at Edward Jones in St. Louis, said.

“With the potential for this to last some time, it’s in the best interest of the company to attack it aggressively.” Schlumberger, which had doubled its workforce in the past 10 years, said the one-time charges for the quarter also resulted from the devaluation of Venezuela’s currency and a lower value for production assets it owns in Texas. Net income dropped to $302 million, from $1.66 billion a year earlier. “In this uncertain environment, we continue to focus on what we can control,” Schlumberger Chief Executive Officer Paal Kibsgaard said in the earnings report. “We have already taken a number of actions to restructure and resize our organization.” Shares in oilfield-services companies, which help customers find and produce oil and natural gas, were the first to fall as crude prices declined. Service companies in the Standard & Poor’s Index dropped 20% in the quarter, more than the 18% decline for producers.

Read more …

Hit hard.

Aberdeen, The Energy-Rich Town Counting The Cost Of The New Oil Shock (Guardian)

Billy Campbell’s three-year-old is spinning around in a Peppa Pig plastic rocket in the middle of Aberdeen’s Union Square shopping mall. It is not hard to believe that the wider Aberdonian population is in a similar spin given the crisis that has struck the Granite City’s key industry: oil and gas. Ed Davey, the energy secretary, and Nicola Sturgeon, Scotland’s first minister, have both rushed to Britain’s oil capital in the last 48 hours to reassure the city that they are aware of looming problems – problems that, the Bank of England governor warned on Wednesday, will deliver a “negative shock” to Scotland’s economy. Some experts think the oil price fall will wipe £6bn off the country’s GDP and Sturgeon is setting up a task force to try to preserve energy jobs.

[..] This is a very affluent city where unemployment is only a little over 2% and incomes are well above the Scottish average. In Aberdeenshire some 38% of households have an income of more than £30,000, compared to 28% across Scotland and just 19% in Glasgow. The Union Square car park is crammed with upmarket models and four-wheel drives – a survey last year by accountants UHY Hacker Young showed that Aberdeenshire has the highest sales of 4x4s in the UK. The car park is just yards away from the massive offshore support vessels that are waiting to load in the harbour beyond. But, away from the downtown bustle of the city centre, not everyone is quite so laid back.

Certainly not those at the sprawling business park at Dyce, close to the airport, where oil firms and the industry’s service companies are congregated. It was here that BP staff were just told that 300 jobs are to be lost from the North Sea business. These are just the latest staff cuts at major oil employers in the region. Shell has taken similar steps, as has Chevron. Companies such as the Wood Group and Petrofac that provide drilling and other support services to the big oil companies have also been cutting costs. Last year Wood slashed 10% off the rates it pays to its contractors, saying operating costs in the North Sea were unsustainable. And that was before the price of oil crashed over the last six months by 60% to its lowest level in six years.

Read more …

Preparing for a bank run.

Greek Systemic Banks Request Emergency Liquidity Assistance (Kathimerini)

Two Greek systemic banks submitted the first requests to the Bank of Greece for cash via the emergency liquidity assistance (ELA) system on Thursday, sources told Kathimerini. It is thought that requests from the remaining Greek banks will follow in the next few days. The move came in response to the pressing liquidity conditions resulting from the growing outflow of deposits as well as the acquisition of treasury bills forced onto them by the state. Banks usually resort to ELA when they face a cash crunch and do not have adequate collateral to draw liquidity from the European Central Bank, their main funding tool. ELA is particularly costly as it carries an interest rate of 1.55%, against just 0.05% for ECB funding.

The requests by the two lenders will be discussed by the ECB next Wednesday. Bank officials commented that lenders are resorting to ELA earlier than expected, which reflects the deteriorating liquidity conditions in the credit sector. Besides the decline in deposits, banks were dealt another blow on Thursday with the scrapping of the euro cap on the Swiss franc. Bank estimates put the impact of the euro’s drop on the local system’s cash flow at between €1.5 and €2 billion. Deposits recorded a decline of €3 billion in December – a month when they traditionally expand – while in the first couple of weeks of January the outflow continued, although banks say it is under control.

A major blow to the system’s liquidity has come from the repeated issue of T-bills: In November the state drew €2.75 billion in this way, in December it secured €3.25 billion, and it has already tapped another €2.7 billion in January. Of the above amounts, a significant share – amounting to €3 billion according to bank estimates – was in the hands of foreign investors who are not renewing their stakes, so Greek banks have to step in to buy them. Local lenders had also resorted to ELA in 2011 to cope with the outflow of deposits and consecutive credit rating downgrades of the state (and the banks) that made Greek paper insufficient for the supply of liquidity by the Eurosystem. In June 2012, due to the uncertainty of the twin elections at the time, the ELA being drawn by local banks to handle the unprecedented outflow of deposits reached a high of €135 billion. By May 2014, Greek banks had reduced their ELA financing to zero.

Read more …

If politicians – like this guy – don’t understand what deflation is, and most have no clue, that can obviously cause trouble.

No Risk Of ‘Deflation Spiral’ In Europe: German Minister (CNBC)

Despite data showing that the euro zone has slid into deflation, Germany’s deputy finance minister brushed off concerns that the region could enter a downward spiral of falling prices and lack of demand. “This is not what economists and textbooks describe as a deflation spiral, this is a modest price development,” Steffen Kampeter told CNBC Thursday. Data released last week showed that the 19-country single currency region had entered deflation territory in December. Prices in the euro zone fell 0.2% year-on-year in December, marking the first time since 2009 that prices have dipped into negative territory. The decline in prices has been largely attributed in the cost of oil, which has slipped over 60% since June 2014. However, core inflation, which strips out volatile factors like fuel and unprocessed food prices, was stable at 0.7% in December.

“I see the facts,” Kampeter said. “And the fact is that the core inflation is rising and we have a very moderate and negative price development, especially in energy and raw material.” Deflation concerns analysts because a decline in the price of goods can cause consumers to delay purchases in the hope of further price falls, putting pressure on the broader economy. The figures prompted widespread market speculation that the European Central Bank (ECB) could announce a full-scale quantitative easing program when it meets on January 22. The deputy finance minister wouldn’t comment on any forthcoming ECB action, however. As a German policymaker, Kampeter said he was tasked with looking at structural reforms in Germany and Europe as a whole, and was aiming to ensure that investment in Europe continued in order to keep the region competitive. The Germany economy – which is the largest in the euro zone – has staged something of a turnaround of late, after veering dangerously close to recession in 2014.

Read more …

Today’s episode of The Dog Ate My Homework.

UK Retailers ‘Throttled’ By Black Friday (Daily Mail)

It’s the American import that has played havoc with Christmas retail sales. Black Friday, where US shops slash their prices on the day after Thanksgiving, has joined the school prom as a stars-and-stripes tradition that has invaded our islands. For UK retailers, it has proved an unwelcome arrival. Far from boosting net sales it has proved a festive nightmare, denting Christmas trading, causing websites to crash, and sparking delivery chaos. Shoppers spent an estimated £810m on Black Friday on November 28 – making it the biggest ever day for UK online sales. But consumers more than made up for their spree by tightening their belts later on, in the run-up to Christmas.

Retailers suffered their slowest December growth in six years as Black Friday disrupted the timing and rhythm of festive sales. Several chains have lined up to blame the event for their lacklustre performance, with Argos owner Home Retail Group claiming to be the latest victim. The company, which fell short of City forecasts, accused Black Friday of fostering ‘a discount mentality’ in the run-up to Christmas, a time of year when shoppers are usually prepared to pay full price for gifts. Marks & Spencer said that it had caused systems at its Castle Donington warehouse to collapse, and Game Digital blamed it for Monday’s profit warning. Home Retail Group’s new chief executive John Walden said: ‘This year’s adoption of ‘Black Friday’ promotional events generally by the UK market significantly impacted the shape of Argos sales over its peak trading period.’

Read more …

But China can make the numbers up as it goes along.

Warning: China May Trigger Fresh Rout In Commodities (CNBC)

Commodities just can’t catch a break – and China’s GDP release on January 20 could throw another punch at the beleaguered asset class should it underperform expectations, warn analysts. “We are days from the release of China’s Q4 GDP and copper is the best barometer of growth. The rout gives me reason to believe China’s growth is not only moderating but is slowing faster than estimated,” Evan Lucas, market strategist at IG wrote in a note. “If China disappoints next Tuesday, brace for a real rout in commodities,” he said. Copper, regarded as an important indicator of economic health, joined the selloff in commodities Wednesday after the World Bank downgraded its growth outlook for the global economy. The global economy is forecast to expand by 3% this year,the Washington-based lender said in its Global Economic Prospects report released on Tuesday, a notch lower than its previous forecast of 3.4% made in June, but up from an estimated 2.6% in 2014.

The red metal suffered its biggest one-day slide in more than three years on Wednesday, with three-month copper on the London Metal Exchange falling more than 8% at one point to $5,353 a tonne before settling around $5,655 on Thursday. The World Bank expects China’s gradual pace of deceleration to continue,forecasting growth in the world’s second largest economy to slow to 7.1% this year from an estimated 7.4% last year. China plays a dominant role in the commodities market because it’s the world’s largest consumer of energy and metals, including copper. “In our view, the significant pressure on copper price lately indicates either a noticeable slow-down in demand [out of China] or troubles in the shadow banking sector, or both,” said David Cui, strategist at Bank of America Merrill Lynch.

Read more …

“.. shadow bank credit exceeded new yuan-denominated loans for the first time in 2014.”

China Shadow Banking Surge Chills Stimulus Hopes (CNBC)

Two months ago calls for broad-based stimulus in China were all the rage, but a sudden spike in shadow banking has led analysts to revise their expectations for looser monetary policy. Aggregate social financing, a measure of credit that covers bank lending and shadow banking activity, hit one-year high of 1.69 trillion yuan ($273 billion) in December, up from 1.15 trillion yuan the previous month, official data showed on Thursday. “A surge in shadow bank credit – entrusted loans, trust loans, banker’s acceptances, corporate bonds and non-financial enterprises’ domestic equity – was responsible for December’s considerably larger than expected increase in aggregate financing,” said Tim Condon, head of Asia research at ING in a note on Friday, noting that shadow bank credit exceeded new yuan-denominated loans for the first time in 2014.

China’s central bank surprised markets by cutting interest rates for the first time in two years in November, sparking expectations for further policy easing via interest rate or reserve ratio requirements (RRR) cuts. Tight funding conditions also fuelled hopes for RRR cuts late last year. The seven-day repo rate, a closely-watched measure of interbank lending costs, spiked suddenly to an over one-year high in mid-December, prompting speculation for central bank action to boost liquidity. But Thursday’s data reduce the likelihood that the People’s Bank of China will cut the RRR for lenders, Condon said: “We are reviewing our forecast of 100 basis-points of RRR cuts in the first half of the year for downward revision.” Shadow banking was fairly stable last year after Beijing introduced regulatory measures to clampdown on the sector, such as stricter financing rules for trust companies.

During the July-September period, the shadow banking sector of China’s total social financing contracted for the first time on quarter since the global financial crisis. However, those tightening measures may be the very reason for December’s surge, according to Barclays. “We suspect that borrowers including local government financing vehicles (LGFVs) could have accelerated their financing activities through shadow banking channels, since they might experience difficulties in accessing bond market for new issuance as a result of tightening regulations/declining support from provincial government on new debt,” analysts said in a note on Friday. The sudden spike in shadow banking credit leaves the central bank in a catch-22 situation, Gavin Parry at Parry International Trading said. “Here is the issue for the PBoC; it is facing rampant speculation bubbling in the economy like the stock market, while also facing weaker loan demand, local government funding needs and deflationary forces,” he said.

Read more …

Logical step.

New Russian/Chinese Credit Rating Agencies To ‘Balance Big Three’ (RT)

The creation of a joint Russian-Chinese credit rating agency will balance the global outlook and give the world an alternative view on how credit ratings should be done, Chinese international relations expert Victor Gao told RT. “Traditionally credit rating is mostly done by Western credit rating agencies. They sometimes may not fully understand the dynamics of the economics of any particular company or the sovereign borrower,” he said, adding that the agency won’t pursue a goal of replacing traditional Western credit rating agencies like S&P and Moody’s. “It will give the whole world another perspective of how risks are analyzed and how credit rating should be done,” he said. Gao believes Western rating agencies claim to be independent and professional, but in fact they turn out to be biased when it comes to issues of geopolitical importance.

“During the global financial crisis the Western rating agencies did not react as quickly as possible,” he said. “In terms of the rating of the sovereign debt of the US for example, or even for Japan, they’ve actually displayed much more flexibility in rating these countries compared with many other countries.” The announcement of a rating could actually make a situation even worse rather than help stabilize it, he added. Credit rating agencies are very much at the top of the international financial system and they’re not only active domestically in one particular country but in many cases they are active across national boundaries.

Gao said that China has its own credit rating agency Dagong which is actively operating in the country and abroad, increasingly estimating other countries’ and companies’ credit rating. The analyst believes the global economy is changing and going through an important transformation as the emerging markets are growing and their portion in the global economy is increasing despite a significant turmoil in the international financial, economic and energy sectors. Creating a joint credit rating agency of Russia and China is significant but it’s high time the world’s most important developing economies united and came up with their own credit rating agency, as in case of establishing the BRICS Development Bank, he said.

Read more …

Up to 60 years old, women up to 50.

Ukraine President Poroshenko Signs Decree To Mobilize Up To 100,000 (TASS)

Ukrainian President Petro Poroshenko has signed a decree on another mobilization. He put his signature to the document at a meeting with the heads of regional authorities. “I have handed it over to parliament, because it requires approval by the national legislature,” Poroshenko said. Under a decision by the National Security and Defense Council of December 20, 2014, a fourth mobilization wave is beginning on January 20, and two more will be held in April and June.

Some categories of reservists will be exempt from mobilization: men with poor health, university and post-graduate students, clerics, parents having three or more children, and those resident in the territories uncontrolled by the Ukrainian authorities. On January 8, Defense Minister Stepan Poltorak said that in 2015 about 104,000 men may be mobilized, if need be. Ukrainian General Staff spokesman Volodymyr Talalai said that women aged 25 through 50 might be drafted into the army, if necessary.

Read more …

There needs to be far more protest against TTIP, or it’ll be pushed through.

‘Corporate Wolves’ Will Exploit TTIP Trade Deal, MPs Warned (Guardian)

The controversial TTIP trade deal between Europe and the US could depress workers’ wages by £3,000 a year and allow “corporate wolves” to sue the government for loss of profit, MPs have heard. The claims were made in a highly-charged House of Commons debate, with many Conservative MPs defending the proposed Transatlantic Trade and Investment Partnership free trade deal and opposition MPs warning that it risks giving too much power to big US corporations. Anti-TTIP campaigners claim one million people have signed a petition against the deal, mainly because of worries that it could open the door to US health companies running parts of the NHS. This has been firmly denied by the UK government and the European commission, who have said public services are explicitly excluded. However, Labour is still worried that the proposals not do enough to protect the public interest.

Many MPs have particular concerns about the investor-state dispute settlement clauses, which would give private companies the right to sue the government in international tribunals for loss of profit arising from policy decisions. Labour MP Geraint Davies, who called the debate, urged negotiators to drop controversial clauses, insisting the judicial system in each country was sufficient protection in mature democracies. His motion called for the UK parliament to play a role in scrutinising any eventual deal, instead of it being passed exclusively by Brussels. “The harsh reality is this deal is being stitched up behind closed doors by negotiators with the influence of big corporations and the dark arts of corporate lawyers – stitching up laws that will be quite outside contract law and common law, outside the shining light of democracy, to in fact give powers to multinationals to sue governments over laws designed to protect their citizens.”

“My view is we should pull the teeth of the corporate wolves scratching at the door of TTIP by scrapping the investor-state dispute settlement rules altogether and so we can get on with the trade agreement without this threat over our shoulder.” Caroline Lucas, the former Green party leader and MP for Brighton Pavilion, said she believed TTIP amounted to a corporate takeover and cited independent research from Tuft University suggesting workers’ wages could suffer by £3,000 a year. “Countries like the Czech Republic, Slovakia and Poland who are in trade agreements which include this kind of investor-state relationship have been sued 127 times and lost the equivalent money that could have employed 300,000 nurses for a year,” she said. “The idea this isn’t a problem is patently wrong; this is about a corporate takeover and that is why it is right to oppose this particular mechanism.”

Read more …

Good man.

Pope Francis Says Freedom Of Speech Has Limits (BBC)

Pope Francis has defended freedom of expression following last week’s attack on French satirical magazine Charlie Hebdo – but also stressed its limits. The pontiff said religions had to be treated with respect, so that people’s faiths were not insulted or ridiculed. To illustrate his point, he told journalists that his assistant could expect a punch if he cursed his mother. [..] Speaking to journalists flying with him to the Philippines, Pope Francis said last week’s attacks were an “aberration”, and such horrific violence in God’s name could not be justified. He staunchly defended freedom of expression, but then he said there were limits, especially when people mocked religion. “If my good friend Doctor Gasparri [who organises the Pope’s trips] speaks badly of my mother, he can expect to get punched,” he said, throwing a pretend punch at the doctor, who was standing beside him. “You cannot provoke. You cannot insult the faith of others. You cannot make fun of the faith of others. There is a limit.”

Read more …

Jan 022015
 
 January 2, 2015  Posted by at 12:16 pm Finance Tagged with: , , , , , , ,  2 Responses »


G.G. Bain St. Paul’s Church and St. Paul Building from Woolworth Building, NYC Apr 1919

The Year Of Dollar Danger For The World (AEP)
Iran Says Saudi Arabia Should Move To Curb Oil Price Fall (Reuters)
Could 2015 Herald A ‘New Oil Order’? (CNBC)
Falling Oil Raises Headache For Developing Nations (MarketWatch)
Russia Oil Output Hits Post-Soviet High (Reuters)
Oil At $14 A Barrel? Here’s How It Could Happen (CNBC)
Draghi Says ECB Prepares Action as Deflation Risk Non-Negligible (Bloomberg)
Draghi: Risk of ECB Failing Its Mandate Higher Than 6 Months Ago (Reuters)
Euro Forecasters See Pain After Worst Year Since 2005 (Bloomberg)
Merkel Ally Urges ECB Not To Buy Struggling States’ Bonds (Reuters)
New Year Brings Eurozone Closer To A Lost Decade (MarketWatch)
2014 “End Of Year” Report And A Look Into What 2015 Might Bring (Saker)
Commodity Prices Are Cliff-Diving: The Case Of Iron Ore (David Stockman)
China Property Developer Fails To Repay $51 Million Loan (Reuters)
China Goes Organic Amid Food Scandals (CNBC)
Thomas Piketty Rejects Légion d’Honneur Award (FT)
The 10 Most Generous Nations (MarketWatch)
The Pope Blesses the Climate Treaty (Bloomberg)
The Secret To A Happy Life – Courtesy Of Tolstoy (BBC)

Ambrose is all over the place here. But the core is dead on: the dollar will decide a lot in 2015, it’ll be a global wrecking ball.

The Year Of Dollar Danger For The World (AEP)

America’s closed economy can handle a surging dollar and a fresh cycle of rising interest rates. Large parts of the world cannot. That in a nutshell is the story of 2015. Tightening by the US Federal Reserve will have turbo-charged effects on a global financial system addicted to zero rates and dollar liquidity. Yields on 2-year US Treasuries have surged from 0.31% to 0.74% since October, and this is the driver of currency markets. Since the New Year ritual of predictions is a time to throw darts, here we go: the dollar will hit $1.08 against the euro before 2015 is out, and 100 on the dollar index. Sterling will buckle to $1.30 as a hung Parliament prompts global funds to ask why they are lending so freely to a country with a current account deficit reaching 6% of GDP.

There will be a mouth-watering chance to invest in the assets of the BRICS and mini-BRICS at bargain prices, but first they must do penance for $5.7 trillion in dollar debt, and then do surgery on obsolete growth models. The MSCI index of emerging market stocks will slide another third to 28 before touching bottom. The Yellen Fed will be forced to back down in the end, just as the Bernanke Fed had to retreat after planning a return to normal policy at the end of QE1 and QE2. For now the Fed is on the warpath, digesting figures showing US capacity use soaring to 80.1%, and growth running at an 11-year high of 5% in the third quarter. The Fed pivot comes as China’s Xi Jinping is trying to deflate his own country’s $25 trillion credit boom, early in his 10-year term and before it is too late. He does not need or want uber-growth.

The Politburo will more or less keep its nerve as long as China continues to meet its target of 10m new jobs a year – easily achieved in 2014 – and job vacancies outstrip applicants. Uncle Xi will ultimately blink, but traders betting on a quick return to credit stimulus may lose their shirts first. Worse yet, when he blinks, a tool of choice may be to drive down the yuan to fight Japan’s devaluation, and to counter beggar-thy-neighbour dynamics across East Asia. This would export yet more Chinese deflation to the rest of the world. At best we are entering a new financial order where there is no longer an automatic “Fed Put” or a “Politburo Put” to act as a safety net for asset markets.

That may be healthy in many ways, but it may also be a painful discovery for some. A sated China is as much to “blame” for the crash in oil prices as America’s shale industry. Together they have knouted Russia’s Vladimir Putin. The bear market will short-circuit at Brent prices of $40, but not just because shale capitulates. Marginal producers in Canada, the North Sea, West Africa and the Arctic will share the punishment. The biggest loser will be Saudi Arabia, reaping the geostrategic whirlwind of its high stakes game, facing Iranian retaliation through the Shia of the Eastern Province where the oil lies, and Russian retaliation through the Houthis in Yemen.

Read more …

This is about much more than oil: “The Iranian deputy minister also criticised Saudi military involvement in Bahrain, which has been gripped by tension since 2011 protests led by majority Shi’ite Muslims demanding reforms and a bigger role in running the Sunni-ruled country.”

Iran Says Saudi Arabia Should Move To Curb Oil Price Fall (Reuters)

Falling world oil prices will hurt countries across the Middle East unless Saudi Arabia, the world’s biggest crude exporter, takes action to reverse the slump, Iran’s deputy foreign minister told Reuters. Hossein Amir Abdollahian described Saudi Arabia’s inaction in the face of a six-month slide in oil prices as a strategic mistake and said he still hoped the kingdom, Tehran’s main rival in the Gulf, would respond. Oil prices closed on Wednesday at a 5-1/2 year low, registering their second-biggest ever annual decline after OPEC oil exporters, led by Saudi Arabia, chose to maintain oil output despite a global glut and calls from some of the cartel’s members – including Iran and Venezuela – to cut production.

“There are several reasons for the drop of the price of oil but Saudi Arabia can take a step to have a productive role in this situation,” Abdollahian said. “If Saudi does not help prevent the decrease in oil price … this is a serious mistake that will have a negative result on all countries in the region,” Abdollahian said in an exclusive interview on Wednesday evening. His comments highlight continued tensions between the Shi’ite Muslim republic and Sunni Muslim kingdom, locked in a battle for regional power and influence despite hopes of rapprochement since the inauguration of Iran’s President Hassan Rouhani in August 2013.

Abdollahian said Iran would have more discussions with Saudi Arabia about the oil price, both through oil officials at OPEC and through the foreign ministry. He did not give specific details on when any meeting might take place. Saudi Arabia said last month that it would not cut output to prop up oil markets even if non-OPEC nations did so. The Iranian deputy minister also criticised Saudi military involvement in Bahrain, which has been gripped by tension since 2011 protests led by majority Shi’ite Muslims demanding reforms and a bigger role in running the Sunni-ruled country. Abdollahian said Bahraini authorities’ continued detention of Shi’ite opposition leader Sheikh Ali Salman would have “serious consequences” for the government there.

Tehran and Riyadh accuse each other of interfering in the pro-Western Gulf island kingdom, one of several countries where their power struggle has played out. They also support opposing sides in wars and disputes in Iraq, Syria, Lebanon and Yemen. Abdollahian dismissed United States efforts to fight Islamic State, also known by its Arabic acronym Daesh, as a ploy to advance U.S. policies in the region. “The reality is that the United States is not acting to eliminate Daesh. They are not even interested in weakening Daesh, they are only interested in managing it,” he said.

Read more …

“.. the impact on that on production would only be start to felt in 2016 onwards and not as much as we would like to see in 2015.”

Could 2015 Herald A ‘New Oil Order’? (CNBC)

Last year was a tumultuous year for oil, with Brent crude prices declining around 50% since June on the back of an over-supplied market and lack of global demand. From “old school” oil producers Russia and Saudi Arabia in the east to shale oil in California and oil sands in Alberta in the west, the glut of oil and its impact on currencies and economies has been felt across the world. When OPEC decided not to cut production when it met in November, the 12 major oil producers effectively threw down the gauntlet to the young guns of U.S. oil to see who could withstand the fall in prices and who would blink first and trim production. As of January 2, benchmark Brent crude was trading at $57.58, having fallen from a high of around $115 a barrel hit in mid-June.

With prices falling fast and hitting five-year lows in mid-December, commodities research teams at the world’s investment houses and banks scrambled to revise their 2015 predictions for oil and the potential impact on global economies. And as wildly fluctuating as the price of oil has been, so have the predictions. While HSBC told investors to prepare for $95 a barrel by the end of 2015, other analysts were far more bearish. Morgan Stanley cut its 2015 forecast for Brent saying that in a worst case scenario crude prices could fall to $43 per barrel in 2015, although its base case scenario was for $70. The U.S. shale revolution and its accompanying rise in oil production has been a decisive factor in the fall in the price this year. The newcomer has affronted the old guard of producers like Saudi Arabia, the biggest oil exporter in the OPEC group and analysts believed its decision not to cut production was a move to put price pressure on U.S. producers.

The U.S. might not give up so easily though, according to Citi’s commodities research team who said in their 2015 outlook for the commodities markets that there is a “distinctive underlying ‘Made in America’ quality that looks likely to dominate the commodity complex through 2015.” Whether U.S. shale oil producers can withstand the fall in prices into 2015 and dent OPEC’s market share is a key matter for debate, however. “Prices are already approaching the danger point for the bulk of U.S. shale output, so industry costs would have to fall for prices to be sustainable at these lower levels,” Melanie Debono, economist at Capital Economics, said in the consultancy’s accompanying note.

There was a risk, Debono added, that an extended period of lower oil prices would lead to large cuts in output in both the U.S. and Canada. Companies like ConocoPhillips who are active in the U.S. shale industry have already announced that it would “defer significant investment” in Canada and the U.S. as returns looked far less attractive. “It’s very clear if oil prices remain below in the region of $64 per barrel for a sustained period of time – that’s about a three to six month period at least – we would start seeing increased scale backs in the U.S.,” Abhishek Deshpande, oil and gas analyst at Natixis. “But the impact on that on production would only be start to felt in 2016 onwards and not as much as we would like to see in 2015.”

Read more …

Oil and the dollar.

Falling Oil Raises Headache For Developing Nations (MarketWatch)

The drops last year in the prices of oil and other commodities are threatening to stunt growth in poor African and Latin American nations that sought to use vast natural-resource wealth to climb the development ladder. During a decadelong boom, governments on those continents vowed to use a windfall from surging raw-material prices to lift the vast underclass. Governments that sought big development leaps by funding social-welfare programs and ambitious infrastructure initiatives, such as building roads, ports and power plants, may now have less money to do so. “The good-governance records in many [Latin American] countries were linked to commodity prices, and this will be tested by the end of the commodity boom,” said Jorge Castaneda, Mexico’s former foreign minister.

The commodity-rich nations of Africa and Latin America are also facing a slowdown in China, a key buyer of exports from South Africa, Nigeria, Brazil, Chile and others. The two regions have been hit by a global selloff of emerging-market stocks, bonds and currencies. The stakes are high for these often-volatile economies, which have some of the world’s widest rich-poor gaps. Economic slowdowns and declining investment flows threaten to stretch budgets. In Latin America, credit-ratings firm Fitch expects to downgrade more countries than it upgrades in 2015. In some cases, the declines could expose levels of corruption and mismanagement that weren’t detected during the good times. In resource-rich Brazil, millions of families escaped extreme poverty and joined a growing working class.

Now, the country’s growth has stagnated, investment is declining and currency declines are raising inflation fears. Allegations of widespread corruption at the state oil firm Petroleo Brasileiro SA are adding to the pain. Brazilian officials had placed the oil firm at the center of a far-reaching plan to overhaul the economy and lift millions of poor into better paying jobs. Shares of Petrobras have fallen to multiyear lows. The situation is worse in Venezuela, where President Nicolás Maduro is seeking to use oil wealth to fuel a Socialist revolution. With oil prices plunging, investors are gauging the risk that Venezuela may fail to pay its debt. Default would add to the woes of an economy saddled with double-digit inflation and shortages of basic items.

Even countries with more moderate policy mixes, such as Chile, among the biggest copper exporters, are getting hit. Chile cut its 2015 growth outlook by half a percentage point to 2.5% in December. In Africa, the impact is magnified by the dependence of some fast-growing economies, such as Zambia, on the export of a single commodity. If the price of that commodity falls–in Zambia’s case, copper–the fallout can be far-reaching. Countries that didn’t balance budgets or curtail corruption while times were good will face painful choices, said Jack Allen of Capital Economics in London. Capital Economics forecasts average growth in sub-Saharan Africa to fall by one percentage point in 2015, to 4%, the slowest pace in more than a decade.

Read more …

Race to the bottom.

Russia Oil Output Hits Post-Soviet High (Reuters)

Russia’s 2014 oil output hit a post-Soviet record high average of 10.58 million barrels per day (bpd), rising by 0.7% helped by small non-state producers, Energy Ministry data showed on Friday. Oil and gas condensate production in December hit 10.67 million bpd, also a record high since the collapse of the Soviet Union. The data showed Russia’s so-called small producers, mostly privately held, increased their output by 11% to just over 1 million barrels per day. Crude oil exports via state monopoly Transneft fell 5% to 195.5 million tonnes due to rising domestic demand and refinery runs.

Exports to China reached a new high of 22.6 million tonnes (452,000 bpd), up 43% on the year as Russia seeks to diversify its energy customers. Russian producers capitalized on rising oil prices in the first half of 2014, when they reached over $113 per barrel. However, they have halved since then. Hurt by falling oil prices and Western sanctions prompted by Moscow’s role in Ukraine, growth in oil output in 2014 slowed from a gain of 1.4% in 2013. Top listed oil company Rosneft, which produces more oil than OPEC members Iraq or Iran, saw its output slip 0.7% as it struggled to arrest declining production at its West Siberian fields. Oil and gas fund about half of Russia’s budget.

The country’s economy is slipping into recession following a fall in oil prices and could see oil output decline to 525 million tonnes in 2015, according to an Energy Ministry forecast. The International Energy Agency (IEA) expects Russian oil output to fall by 1%. The country’s natural gas production in 2014 fell by 4% to 640.237 billion cubic meters (bcm). Top producer Gazprom posted an output fall of 9% to an all-time low of 432 bcm due to its pricing dispute with Ukraine, once its second-largest customer after Germany.

Read more …

Sounds crazy?

Oil At $14 A Barrel? Here’s How It Could Happen (CNBC)

No one really saw 2014’s dramatic plunge in oil price coming, so it’s probably fair to say that any predictions about where it’s going from here fall somewhere between educated guesses and picking a number out of a hat. In that light, it’s less than shocking to see one analyst making a case—albeit in a pure outlier sense—for a drop all the way below $14 a barrel. Abigail Doolittle, who does business under the name Peak Theories Research, posits that current chart trends point to the possibility that crude has three downside target areas where it could find support—$44, $35 and the nightmare scenario of, yes, $13.65. Make no mistake, she thinks that’s an extreme case.

Her target for the more likely move is the $35 range, which in itself is quite a call considering light crude had been just above $100 a barrel this summer and the move would represent a 33% or so plunge just from current levels. But Doolittle makes room for an even more extreme scenario, in which technical support gives way as part of what she describes as a triangular pattern forming in an “ascending trend channel” that brings about the extreme case. “There is a wild case scenario for a massive fall in oil and it is made by both the triangle and the possibility that oil’s true trading path will turn out to be sideways on a potential false initial reaction of epic proportions,” Doolittle explained in a report she distributed Wednesday morning.

“This possibility cannot be ignored or discounted because it is simply too strong from a technical standpoint.” She acknowledges that the scenario “may sound outrageous” but cautions “odds appear fairly strongly” that the move could be triggered by “a false initial reaction or basically a massive head fake caused by a variety of factors.” Before consumers get too giddy about the cost of even lower fuel prices at the pump, Doolittle offers a word of caution. “Clearly this would seem to be a tail wind for consumers, but the various shocks and possible financial market crashes that could be triggered by such a collapse in oil would not be, and thus this seems a very dangerous scenario indeed,” she said.

Read more …

“Italian and Spanish bond yields dropped to record lows after the interview was published and the euro fell to the weakest since June 2010.”

Draghi Says ECB Prepares Action as Deflation Risk Non-Negligible (Bloomberg)

European Central Bank President Mario Draghi said he can’t exclude the risk of deflation in the euro area, hinting that the likelihood of large-scale quantitative easing is increasing. “The risk that we don’t fulfill our mandate of price stability is higher than it was six months ago,” Draghi said in an interview with German newspaper Handelsblatt. “We are in technical preparations to alter the size, speed and composition of our measures at the beginning of 2015, should this become necessary, to react to a too-long period of low inflation. There’s unanimity in the ECB council on that.”

While policy makers agree in principle, the debate over whether fresh stimulus is needed at this point has reopened a rift on the ECB’s Governing Council that now comprises 25 officials after Lithuania joined the currency region on Jan. 1. With inflation seen turning negative this year, some have warned of a deflationary spiral, as others have urged waiting to allow previously agreed measures to show their effect. Draghi said on deflation that “the risk cannot be entirely excluded, but it is limited” and “we have to act against such risk.” Asked how much the ECB will have to spend on government bonds, he said “it’s difficult to say.” Italian and Spanish bond yields dropped to record lows after the interview was published and the euro fell to the weakest since June 2010.

Read more …

“A break-up of the euro zone? That will not happen. That’s why there is no plan B ..,”

Draghi: Risk of ECB Failing Its Mandate Higher Than 6 Months Ago (Reuters)

European Central Bank President Mario Draghi said the risk of the central bank not fulfilling its mandate of preserving price stability was higher now than half a year ago, and reiterated its readiness to act early this year should it become necessary. In an interview with German financial daily Handelsblatt, Draghi urged politicians to implement necessary reforms, reduce tax burdens and cut red tape to support the euro zone recovery, which Draghi said was “fragile and uneven”. There was a limited risk of deflation in the euro zone, Draghi said, but if inflation remained too low for too long and led to receding inflation expectations and a delay in spending, the ECB would need to act to fulfill its mandate.

“The risk that we do not fulfill our mandate of price stability is higher than six months ago,” Draghi was quoted as saying in an interview that will be published on Friday. “We are in technical preparations to adjust the size, speed and compositions of our measures early 2015, should it become necessary to react to a too long period of low inflation. There is unanimity within the Governing Council on this.” He added that government bond purchases were among the tools the ECB could use to fulfill its mandate, but that state financing – which is prohibited by the EU treaty — had to be avoided.

Printing money to buy government bonds, a step known as quantitative easing (QE), is seen as one of the last tools the ECB has to revive inflation, with the key interest rate at 0.05% and growing doubts about the impact of earlier measures. Euro zone inflation stands at 0.3%, far below the ECB’s target of just under 2%, and calls for more ECB action have grown louder as policymakers warn that plunging oil prices could push inflation below zero in coming months. Concerns are that weaker price expectations could affect wages and investments and dampen growth prospects. Regardless, Draghi ruled out a break-up of the euro zone. “A break-up of the euro zone? That will not happen. That’s why there is no plan B,” he said.

Read more …

Beggar thy world.

Euro Forecasters See Pain After Worst Year Since 2005 (Bloomberg)

Midway through European Central Bank President Mario Draghi’s May press conference in Brussels, the euro rose to its strongest level during his tenure. Then he said the ECB was ready to introduce more stimulus measures, sending it into a slide that strategists say will extend into 2015. Europe’s common currency, which appreciated to $1.3993 that May day, ended last year down 12% against the dollar at $1.2098, its biggest loss since 2005. Strategists, who were too timid with their call for a decline in 2014 to $1.28, now see a slump to $1.18 by the end of this year. A weaker euro is key for Draghi as he tries to spur the region’s struggling economy and ward off deflation. This week, ECB Chief Economist Peter Praet told German newspaper Boersen-Zeitung the threat of a drop in consumer prices is increasing, bolstering speculation policy makers will soon start actions such as buying bonds that tend to weigh on a currency.

“The euro-bearish consensus was struggling hard for the first half of the year, but it has come good as the ECB has driven rates down,” Kit Juckes, a global strategist at SocGen in London, said in a Dec. 30 phone interview. “The best thing the ECB can try to engineer is still a weaker euro.” Juckes forecasts the euro will weaken to $1.14 by year-end, a level last seen in 2003. With inflation languishing below the ECB’s goal of just under 2% and the market’s outlook for consumer prices crumbling as crude oil declines, more than 90% of respondents in a monthly Bloomberg survey in December predicted that the ECB would expand the supply of euros by beginning to purchase sovereign bonds in 2015. That’s up from 57% the previous month.

The euro-area may see “negative inflation during a substantial part of 2015” amid a slide in crude, and the Governing Council “cannot simply look through” that, Praet said in comments published Dec. 31 on the ECB’s website. “Inflation expectations are extremely fragile” and “the risk of second-round effects seems to be greater today than it was in the past,” he said. Since the May meeting, the ECB cut its deposit rate below zero for the first time on record, began a program of targeted loans, and started purchasing asset-backed securities and covered bonds. At the same time, the dollar is strengthening as the Federal Reserve moves closer to raising interest rates.

Read more …

The Germans are not about to give in.

Merkel Ally Urges ECB Not To Buy Struggling States’ Bonds (Reuters)

A senior member of Angela Merkel’s party warned the European Central Bank not to pour money into Greece and other struggling euro zone states through bond purchases, saying this would reduce pressure on them to enact much-needed reforms. Michael Fuchs, deputy parliamentary floor leader of the German chancellor’s Christian Democrats (CDU), told Deutschlandfunk radio on Friday: “We shouldn’t pump extra money into these states, but rather make sure they continue along the reform path. “I’d be grateful if (ECB President Mario) Mr Draghi would make statements along these lines.” In an interview with German financial daily Handelsblatt published on Friday, Draghi urged politicians to implement necessary reforms, reduce tax burdens and cut red tape to support a fragile euro zone recovery.

He also said the risk of the central bank not fulfilling its price stability mandate was higher now than half a year ago, and reiterated its readiness to act soon if needed, with government bond purchases among the tools it could use. With the euro zone flirting with deflation, financial markets interpreted Draghi’s comments on Friday as strongly suggesting the ECB would soon embark on outright money-printing, and the euro sank to a 4-1/2 year low against the dollar. Printing money to buy government bonds, a measure known as quantitative easing (QE), is seen as one of the last tools the ECB has to revive inflation. The bank has already pushed its key interest rate down to a record low of 0.05% and doubts are growing about the impact of earlier measures.

“I expect there to be fierce discussion over this at the next ECB meeting,” said Fuchs, referring to opposition to the bond-buying plan by the head of the Bundesbank Jens Weidmann. The ECB’s next policy meeting is on Jan. 22. Fuchs has frequently expressed frustration felt by many German politicians and the public about the pace of reform in twice-bailed-out Greece. He was quoted as saying in a newspaper interview published on Wednesday that euro zone politicians were not obliged to rescue Greece as the country was no longer of systemic importance to the single currency bloc. Greece holds a general election just three days after the ECB meeting and polls suggest the left-wing Syriza party, which rejects the terms of Greece’s euro zone bailouts, will emerge as the strongest party.

Read more …

A decade filled with wrong decisions and futile policies.

New Year Brings Eurozone Closer To A Lost Decade (MarketWatch)

It looks like it will be a “lost decade” after all. As the eurozone enters the eighth year of a slump that began with the 2008 financial crisis, only true optimists believe that the bloc will find a path to faster growth over the next couple of years. Slow growth and rock-bottom inflation have set in. This combination inevitably delays a reduction of the bloc’s heavy private- and public-sector debt burdens. While their debt loads remain high and their incomes in nominal terms are stagnant, people perpetuate slow growth by saving rather than spending. As 2015 begins, economic activity in the eurozone is below the level it was at the start of 2008. The hardest-hit economies are a long way below. With growth so anemic, it doesn’t take much of a shock to turn it negative. Last year, the imposition of European Union sanctions on Russia and its modest retaliation were almost enough to tip the bloc into recession.

This year starts once again with political uncertainties in Greece–and a Jan. 25 general election–that may further set back faltering confidence. And as long as the bloc’s economic prospects remain sickly, the more likely become political crises among members of the currency union. In Greece and in other debt-burdened countries such as Italy and Spain, antiausterity, antiestablishment parties of the left are gaining ground. In Europe’s core, including France, anti-EU, anti-immigration parties of the right are finding traction. At the least, these political shifts are likely to weaken appetite for more supply-side reforms to improve the functioning of labor and goods markets. They may also further fan an incipient backlash against U.S. companies in the vanguard of technological change that would be a motor for long-term growth.

But it could be worse. History offers a cautionary tale about what happens when societies struggle to pay back debt burdens, argues Moritz Kraemer, an analyst with Standard & Poor’s in Frankfurt, in Germany’s struggles after World War I to repay its heavy debts. “While the political and economic environment is hardly comparable one hundred years on and the stakes are not likely to be nearly as high, elevated and sustained debt burdens could still pose risks to social cohesion and political stability,” he wrote in a report last month. To be sure, thanks in part to their expectation that the European Central Bank would step in to save the currency, investors rate the risk of a euro breakup far lower than they did a few years ago. “The existential question for the euro is nowhere near as potent as it was back in 2010 and 2011,” said Peter Goves, a bond strategist at Citi Research in London.

Read more …

Good read. The Vineyard Saker also has Russian versions of Automatic Earth articles .

2014 “End Of Year” Report And A Look Into What 2015 Might Bring (Saker)

Introduction: By any measure 2014 has been a truly historic year which saw huge, I would say, even tectonic developments. This year ends in very high instability, and the future looks hard to guess. I don’t think that anybody can confidently predict what might happen next year. So what I propose to do today is something far more modest. I want to look into some of the key events of 2014 and think of them as vectors with a specific direction and magnitude. I want to look in which direction a number of key actors (countries) “moved” this year and with what degree of intensity. Then I want to see whether it is likely that they will change course or determination. Then adding up all the “vectors” of these key actors (countries) I want to make a calculation and see what resulting vector we will obtain for the next year. Considering the large number of “unknown unknowns” (to quote Rumsfeld) this exercise will not result in any kind of real prediction, but my hope is that it will prove a useful analytical reference.

The main event and the main actors A comprehensive analysis of 2014 should include most major countries on the planet, but this would be too complicated and, ultimately, useless. I think that it is indisputable that the main event of 2014 has been the war in the Ukraine. This crisis not only overshadowed the still ongoing Anglo-Zionist attack on Syria, but it pitted the world’s only two nuclear superpowers (Russia and the USA) directly against each other. And while some faraway countries did have a minor impact on the Ukrainian crisis, especially the BRICS, I don’t think that a detailed discussion of South African or Brazilian politics would contribute much. There is a short list of key actors whose role warrants a full analysis. They are: The USA, The Ukrainian Junta, The Novorussians (DNR+LNR), Russia, The EU. NATO. China. I submit that these seven actors account for 99.99% of the events in the Ukraine and that an analysis of the stance of each one of them is crucial. So let’s take them one by one:

1 – The USA Of all the actors in this crisis, the USA is by far the most consistent and coherent one. Zbigniew Brzezinski, Hillary Clinton and Victoria Nuland were very clear about US objectives in the Ukraine:

Zbigniew Brzezinski: Without Ukraine Russia ceases to be empire, while with Ukraine – bought off first and subdued afterwards, it automatically turns into empire…(…) the new world order under the hegemony of the United States is created against Russia and on the fragments of Russia. Ukraine is the Western outpost to prevent the recreation of the Soviet Union.

Hillary Clinton: There is a move to re-Sovietise the region (…) It’s not going to be called that. It’s going to be called a customs union, it will be called Eurasian Union and all of that, (…) But let’s make no mistake about it. We know what the goal is and we are trying to figure out effective ways to slow down or prevent it.

Victoria Nuland: F**k the EU!

Read more …

Much of it coming from emerging nations. That’s a triple hit: oil, dollar and other commodities.

Commodity Prices Are Cliff-Diving: The Case Of Iron Ore (David Stockman)

Crude oil is not the only commodity that is crashing. Iron ore is on a similar trajectory and for a common reason. Namely, the two-decade-long economic boom fueled by the money printing rampage of the world’s central banks is beginning to cool rapidly. What the old-time Austrians called “malinvestment” and what Warren Buffet once referred to as the “naked swimmers” exposed by a receding tide is now becoming all too apparent. This cooling phase is graphically evident in the cliff-diving movement of most industrial commodities. But it is important to recognize that these are not indicative of some timeless and repetitive cycle – or an example merely of the old adage that high prices are their own best cure.

Instead, today’s plunging commodity prices represent something new under the sun. That is, they are the product of a fracturing monetary supernova that was a unique and never before experienced aberration caused by the 1990s rise, and then the subsequent lunatic expansion after the 2008 crisis, of a cancerous regime of Keynesian central banking. Stated differently, the worldwide economic and industrial boom since the early 1990s was not indicative of sublime human progress or the break-out of a newly energetic market capitalism on a global basis. Instead, the approximate $50 trillion gain in the reported global GDP over the past two decades was an unhealthy and unsustainable economic deformation financed by a vast outpouring of fiat credit and false prices in the capital markets.

For that reason, the radical swings in commodity prices during the last two decades mark the path of a central bank generated macro-economic bubble, not merely the unique local supply and demand factors which pertain to crude oil, copper, iron ore, or the rest. [..] What really happened is that the central bank instigated global macro-economic bubble ripped commodity pricing cycles out of their historical moorings, resulting in a one time eruption of price levels that had no relationship to sustainable supply and demand factors in the mines and petroleum patch. What materialized, instead, was an unprecedented one-time mismatch of commodity production and use that caused pricing abnormalities of gargantuan proportions.

Read more …

Let’s see how many will be allowed to fail.

China Property Developer Fails To Repay $51 Million Loan (Reuters)

Chinese property developer Kaisa Group Holdings said it had failed to repay a HK$400 million ($51.3 million) loan and warned it may default on more debt, the latest problem to hit the firm amid a downturn in the real estate sector. In a stock market filing late on Thursday, the company said the payment of the loan and its interest became compulsory on Dec. 31, following the resignation of its chairman Kwok Ying Shing. The failure to repay the HSBC term loan may trigger default on other loan facilities, debt and equity securities, co-chairman Sun Yuenan said in the filing to the Hong Kong exchange. Last month, Kaisa said the Chinese authorities had imposed a sales blockage on some its projects in the southern city of Shenzhen. Independent research firm CreditSights said the Shenzhen projects were expected to account for around a fifth of Kaisa’s saleable resources by book value.

It also said two other senior executives – Vice Chairman Tam Lai Ling and Chief Financial Officer Cheung Hung Kwong – had left in December. Analysts have questioned the company’s fund raising ability since these two executives left, as they were instrumental in arranging Kaisa’s offshore debt issues. Trading in Kaisa’s shares, which has a market capitalisation of HK$8.2 billion, was halted on Monday. Its bond yields have also more than trebled, with the yield on its bonds due 2018 rising to more than 29% from around 9% at the start of the month. On Friday, its bonds due 2019 and 2020 were both indicated at 40-50 cents on the dollar, after trading as high as 101 and 104 cents on the dollar in December. Moody’s downgraded its credit rating to B3 from B1, warning of further cuts, and Standard & Poor’s said its sales and operations could be “significantly affected” over the next year.

Read more …

“In 2013, 3,000 pig carcasses were seen floating in Shanghai’s Huangpu river, one of the city’s key sources of drinking water.”

China Goes Organic Amid Food Scandals (CNBC)

An organic food craze is emerging among China’s urbanites as food safety scandals spur the younger generation toward alternative ways to buy fresh produce and meat. So far, organic foods’ penetration into China appears small, accounting for 1.01% of total food consumption, but that’s nearly triple 2007’s 0.36%, according to data from organic trade fair Biofach. A series of high-profile food scandals over the past seven years has been a primary catalyst for growth in the organic food market. Biofach expects the segment’s share of China’s overall food market to hit 2% this year. China was ranked as one of the world’s worst safety-violation offenders by American food consulting firm Food Sentry this year. In 2013, 3,000 pig carcasses were seen floating in Shanghai’s Huangpu river, one of the city’s key sources of drinking water.

A few months later, reports that a Beijing crime ring was selling rat and fox meat as lamb sparked international outrage, resulting in the arrest of more than 900 people. The trouble continued in 2014, with the Chinese affiliate of U.S. meat supplier OSI Group accused of using expired meat. OSI caters to major fast-food chains such as McDonald’s and Yum Group’s KFC operating on the mainland. Wal-Mart was also dragged into the limelight this year following revelations that its donkey meat product contained fox meat. Most recently, Subway also came under scrutiny after Chinese media reported in late December that workers at a Beijing franchise changed expiry dates on meat and vegetables to extend their use.

Read more …

“Mr Piketty added that the government instead “would do better to concentrate on reviving growth in France and Europe.“ Oh well, now I don’t have to read those 600 pages.

Piketty Rejects Légion d’Honneur Award (FT)

France’s sputtering economy was a source of endless frustration for President François Hollande in 2014. It found a new way to torment the French president on the first day of the new year when Thomas Piketty, one of the country’s most celebrated economists, rejected a Légion d’Honneur award, saying the government had no standing to grant such recognition. Mr Piketty, whose 2014 book Capital in the Twenty-First Century has already sold more than 1m copies, told the AFP on Thursday: “I refuse this nomination because I do not think it is the government’s role to decide who is honourable.”

In a clear indictment of Mr Hollande’s economic record, Mr Piketty added that the government instead “would do better to concentrate on reviving growth in France and Europe”. Mr Piketty’s comments come on top of a series of disappointing performances and false dawns on the economic front ever since Mr Hollande and his socialist government took office. Unemployment has remained persistently high in spite of promises to change the upward trend by the end of last year. Meanwhile, sluggish growth — the economy was stagnant for the first six months of 2014 — has helped drag down Mr Hollande’s popularity to the lowest levels of any French president in modern history.

But the rejection of the award by the French economist – who argues for the redistribution of concentrated wealth in his best-selling book, which was the Financial Times and McKinsey Business Book of the Year – is particularly galling coming on the same day that the French president dumped his supertax scheme for the rich. The measure to increase tax rates to 75% on earnings over €1m, which earned Mr Hollande support from the left when he announced the plan to great fanfare in 2012, was on Thursday abandoned after bringing in just a small portion of the expected revenue. In rejecting the Legion of Honour, Mr Piketty joins a list of personalities that includes Claude Monet, Jean-Paul Sartre, Albert Camus, Hector Berlioz and Brigitte Bardot – all of whom declined the award for varying reasons.

Read more …

Curious article.

The 10 Most Generous Nations (MarketWatch)

Have you helped a stranger in the past month? If you live in the U.S., Iraq or Trinidad and Tobago, chances are you have. Americans more likely than any other nationality to help strangers, with 79% of people doing so last year, according to an annual index of the most giving nations. The World Giving Index is based on a Gallup survey of more than 130,000 people in 2013 and evaluates charitable behavior in 135 countries around the world. It is sponsored by the Charitable Aid Foundation. The index scores countries based on an average of three measures of giving behavior — the percentage of people who in a typical month donate money to charity, volunteer their time, and help a stranger.

Giving is about more than just existing wealth, the report notes — only five of the top 20 most generous countries are members of the G-20, a group representing the largest economies in the world. Women were more likely to give money than men, but only in high income countries. The country that scored worst in the index was Yemen, where only 3% of people volunteered their time in 2013. Based on the World Giving Index, these are the 10 most generous nations:

Read more …

He should simply write his own.

The Pope Blesses the Climate Treaty (Bloomberg)

When a church that once felt threatened by heliocentrism sees hydrocarbons as a threat to God’s creation, there is reason to hope that today’s science skeptics will find religion, too. Fresh off his success in helping to end one of the last remaining battles of the Cold War, Pope Francis is turning his attention – and bringing his considerable star power – to the fight against global warming. His decision to push for an international treaty on climate change in Paris in December may alienate some conservative Catholics who are skeptical of climate science. But Francis’s leadership on the issue is a hopeful sign that 2015 could be the year that the nations of the world finally commit themselves to collective action. Francis could be forgiven for concentrating on other weighty matters: He is challenging the church’s approach to divorced couples and gays and lesbians, reforming its change-resistant curia, and cleaning up its scandal-plagued bank.

All are mammoth undertakings that will earn him enemies. But this pope has shown no interest in shying away from major controversies. His new focus on climate change is a natural outgrowth of his concern for the poor, who will suffer most if droughts and storms worsen, allowing disease and instability to spread more easily. He is not the first pope to sound the alarm on climate change: Both John Paul II and Benedict XVI did so, and in 2011 the Vatican’s Academy of Sciences issued a report that called on “all people and nations to recognize the serious and potentially irreversible impacts of global warming” caused by human activity. Francis is not changing church teaching, only seizing the moment, as a public consensus emerges around the need for coordinated action. In March, he is expected to visit Tacloban, the Philippine city hardest hit by last year’s typhoon Haiyan, which killed thousands and left millions homeless.

As the planet warms and the seas rise, severe storms are expected to become even more destructive. This trip may be followed by a papal encyclical on climate change, a letter to the bishops that will formalize the church’s position on the issue and guide its ministry at the parish level. In September, Francis will have a chance to raise the issue when he addresses the UN General Assembly. He may also convene a summit of religious leaders to focus attention on climate change, which has generated widespread ecumenical agreement. All these steps will occur in the run-up to the UN summit on climate change in Paris at the end of this year. Francis, who has no lack of ambition, is throwing the weight of the church – and his papacy – behind an international agreement.

Read more …

Well, Tolstoy was an interesting character.

The Secret To A Happy Life – Courtesy Of Tolstoy (BBC)

We can learn a lot about the art of living from Tolstoy’s War and Peace. It acutely observes vanity and folly, sexual jealousy and family relationships. But we can also learn from the life of the master novelist himself, writes Roman Krznaric. Tolstoy, who was born in 1828 and died in 1910, was a member of the Russian nobility, from a family that owned an estate and hundreds of serfs. The early life of the young count was raucous, debauched and violent. “I killed men in wars and challenged men to duels in order to kill them,” he wrote. “I lost at cards, consumed the labour of the peasants, sentenced them to punishments, lived loosely, and deceived people…so I lived for ten years.” But he gradually weaned himself off his decadent, racy lifestyle and rejected the received beliefs of his aristocratic background, adopting a radical, unconventional worldview that shocked his peers.

So how exactly might his personal journey help us rethink our own philosophies of life?
1. Keep an open mind
2. Practice empathy
3. Make a difference
4. Master the art of simple living
5. Beware your contradictions
6. Become a craftsman
7. Expand your social circle

Read more …

Dec 282014
 
 December 28, 2014  Posted by at 12:28 pm Finance Tagged with: , , , , , , , ,  4 Responses »


DPC Cuyahoga River, Lift Bridge and Superior Avenue viaduct, Cleveland, Ohio 1912

Pope Francis Climate Change Encyclical To Anger Deniers, US Churches (Observer)
Hungry Britain: Millions Struggle To Feed Themselves, Face Malnourishment (Ind.)
Decline in Oil Could Cost OPEC $257 Billion in 2015 (Daily Finance)
US Oil-Producing States See Budgets, Jobs at Risk as Price Falls (NY Times)
China’s 3.5% Trade Growth in 2014 Falling Far Short Of 7.5% Target (Reuters)
Japan Approves $29 Billion Stimulus Plan, Impact In Doubt (Reuters)
Japan Approves $29 Billion Spending Package to Boost Economy
The Keynesian End Game Crystalizes In Japan’s Monetary Madness (Stockman)
How Central Banks Saved The World (Stocks) In 2014 (Zero Hedge)
Now Whitehall’s Crazy Eco Zealots Want To Ban Your Gas Cooker (Daily Mail)
Mexico Withdraws $3.4 Billion From Pemex as Oil Revenue Shrinks (Bloomberg)
Greece Faces New ‘Catastrophe’ As PM Battles To Avert Snap Elections (Observer)
Challenging UK Party Games Ahead As Greece Threatens 2nd Debt Crisis (Observer)
You Can Put The Next Crash On Your 2016 Calendar Now (Paul B. Farrell)
2014: The Year The Internet Came Of Age (Guardian)
China Needs Millions of Brides ASAP (Bloomberg)
Rising Oceans Force Bangladeshi Farmers Inland for New Jobs (Bloomberg)
Siberian Dog Allowed To Stay In Hospital Where Owner Died 1 Year Ago (RT)

A Papal Encyclical is a big deal.

Pope Francis Climate Change Encyclical To Anger Deniers, US Churches (Observer)

He has been called the “superman pope”, and it would be hard to deny that Pope Francis has had a good December. Cited by President Barack Obama as a key player in the thawing relations between the US and Cuba, the Argentinian pontiff followed that by lecturing his cardinals on the need to clean up Vatican politics. But can Francis achieve a feat that has so far eluded secular powers and inspire decisive action on climate change? It looks as if he will give it a go. In 2015, the pope will issue a lengthy message on the subject to the world’s 1.2 billion Catholics, give an address to the UN general assembly and call a summit of the world’s main religions. The reason for such frenetic activity, says Bishop Marcelo Sorondo, chancellor of the Vatican’s Pontifical Academy of Sciences, is the pope’s wish to directly influence next year’s crucial UN climate meeting in Paris, when countries will try to conclude 20 years of fraught negotiations with a universal commitment to reduce emissions.

“Our academics supported the pope’s initiative to influence next year’s crucial decisions,” Sorondo told Cafod, the Catholic development agency, at a meeting in London. “The idea is to convene a meeting with leaders of the main religions to make all people aware of the state of our climate and the tragedy of social exclusion.” Following a visit in March to Tacloban, the Philippine city devastated in 2012 by typhoon Haiyan, the pope will publish a rare encyclical on climate change and human ecology. Urging all Catholics to take action on moral and scientific grounds, the document will be sent to the world’s 5,000 Catholic bishops and 400,000 priests, who will distribute it to parishioners. According to Vatican insiders, Francis will meet other faith leaders and lobby politicians at the general assembly in New York in September, when countries will sign up to new anti-poverty and environmental goals.

In recent months, the pope has argued for a radical new financial and economic system to avoid human inequality and ecological devastation. In October he told a meeting of Latin American and Asian landless peasants and other social movements: “An economic system centred on the god of money needs to plunder nature to sustain the frenetic rhythm of consumption that is inherent to it. “The system continues unchanged, since what dominates are the dynamics of an economy and a finance that are lacking in ethics. It is no longer man who commands, but money. Cash commands. “The monopolising of lands, deforestation, the appropriation of water, inadequate agro-toxics are some of the evils that tear man from the land of his birth. Climate change, the loss of biodiversity and deforestation are already showing their devastating effects in the great cataclysms we witness,” he said.

Read more …

Dickens never died.

Hungry Britain: Millions Struggle To Feed Themselves, Face Malnourishment (Ind.)

Millions of the poorest people in Britain are struggling to get enough food to maintain their body weight, according to official figures published this month. The Government’s Family Food report reveals that the poorest 10% of the population – some 6.4 million people – ate an average of 1,997 calories a day last year, compared with the average guideline figure of about 2,080 calories. This data covers all age groups. One expert said the figures were a “powerful marker” that there is a problem with food poverty in Britain and it was clear there were “substantial numbers of people who are going hungry and eating a pretty miserable diet”. The use of food banks in the UK has surged in recent years. The Trussell Trust, a charity which runs more than 400 food banks, said it had given three days worth of food, and support, to more than 492,600 people between April and September this year, up 38% on the same period in 2013.

Based on an annual survey of 6,000 UK households, the Family Food report said the population as a whole was consuming 5% more calories than required. Tables of figures attached to the report reveal the average calorie consumption for the poorest 10%, but the report itself did not highlight this. Chris Goodall, an award-winning author who writes about energy, discovered the figures while investigating human use of food resources. “The data absolutely shocked me. What it shows is for the first time since the Second World War, if you are poor you cannot afford to eat sufficient calories,” he said. He also highlights a widening consumption gap between rich and poor. In 2001/2, there was little difference, with the richest 10th consuming a total of 2,420 calories daily, about 4% more than the poorest. But in 2013, the richest group consumed 2,294 calories, about 15% more than the poorest. The report, published by the Department for Environment, Food & Rural Affairs, also found that the poorest people spent 22% more on food in 2013 than in 2007 but received 6.7% less.

Read more …

2012 revenues: $900 billion. 2015: $446 billion.

Decline in Oil Could Cost OPEC $257 Billion in 2015 (Daily Finance)

Falling oil prices are giving a huge boost to the U.S. economy just in time for the holidays, and the reprieve from high gas prices doesn’t look like it will stop anytime soon. But elsewhere around the world, the drop in oil might not be looked upon so kindly. Most of OPEC’s 12 member countries rely on oil as a major source of revenue, not only supporting their domestic economies but also balancing national budgets. The amount of potential revenue they’ve lost as crude oil prices have fallen is staggering. If you’re a country like Saudi Arabia, Kuwait or Iraq, which rely on oil as a major revenue source, the drop in oil prices can impact your country dramatically. The U.S. Energy Information Administration just estimated that next year’s OPEC oil export revenue (excluding Iran) will drop an incredible $257 billion to $446 billion. That’s off its peak of nearly $900 billion in 2012.

The chart above shows the scale of OPEC’s potential revenue drop and the chart below shows who has the most at stake. Interestingly, Saudi Arabia is leading the charge against cutting OPEC’s production, which is keeping oil prices low, despite having the most money at stake. The reason may be a long-term need for greater market share in the oil market.

Read more …

“Nothing is off the table at this point.”

US Oil-Producing States See Budgets, Jobs at Risk as Price Falls (NY Times)

States dependent on oil and gas revenue are bracing for layoffs, slashing agency budgets and growing increasingly anxious about the ripple effect that falling oil prices may have on their local economies. The concerns are cutting across traditional oil states like Texas, Louisiana, Oklahoma and Alaska as well as those like North Dakota that are benefiting from the nation’s latest energy boom. “The crunch is coming,” said Gunnar Knapp, a professor of economics and the director of the Institute of Social and Economic Research at the University of Alaska Anchorage. Experts and elected officials say an extended downturn in oil prices seems unlikely to create the economic disasters that accompanied the 1980s oil bust, because energy-producing states that were left reeling for years have diversified their economies. The effects on the states are nothing like the crises facing big oil-exporting nations like Russia, Iran and Venezuela.

But here in Houston, which proudly bills itself as the energy capital of the world, Hercules Offshore announced it would lay off about 300 employees who work on the company’s rigs in the Gulf of Mexico at the end of the month. Texas already lost 2,300 oil and gas jobs in October and November, according to preliminary data released last week by the federal Bureau of Labor Statistics. On the same day, Fitch Ratings warned that home prices in Texas “may be unsustainable” as the price of oil continues to plummet. The American benchmark for crude oil, known as West Texas Intermediate, was $54.73 per barrel on Friday, having fallen from more than $100 a barrel in June. In Louisiana, the drop in oil prices had a hand in increasing the state’s projected 2015-16 budget shortfall to $1.4 billion and prompting cuts that eliminated 162 vacant positions in state government, reduced contracts across the state and froze expenses for items like travel and supplies at all state agencies. Another round of reductions is expected as soon as January.

And in Alaska – where about 90% of state government is funded by oil, allowing residents to pay no state sales or income taxes – the drop in oil prices has worsened the budget deficit and could force a 50% cut in capital spending for bridges and roads. Moody’s, the credit rating service, recently lowered Alaska’s credit outlook from stable to negative. States that have become accustomed to the benefits of energy production — budgets fattened by oil and gas taxes, ample jobs and healthy rainy-day funds — are now nervously eyeing the changed landscape and wondering how much they will lose from falling prices that have been an unexpected present to drivers across the country this holiday season. The price of natural gas is falling, too. “Our approach to the 2016 budget includes a full review of every activity in every agency’s budget and the cost associated with them,” said Kristy Nichols, the chief budget adviser to Gov. Bobby Jindal of Louisiana. “Nothing is off the table at this point.”

Read more …

“.. according to a report on the Ministry of Commerce’s website that was subsequently revised to remove the numbers.”

China’s 3.5% Trade Growth in 2014 Falling Far Short Of 7.5% Target (Reuters)

China’s trade will grow 3.5% in 2014, implying the country will fall short of a current 7.5% official growth target, according to a report on the Ministry of Commerce’s website that was subsequently revised to remove the numbers. The initial version of the report published on the website on Saturday, which quoted Minister of Commerce Gao Hucheng, was replaced with a new version that had identical wording but with all the numbers and percentages removed. The Commerce Ministry did not answer calls requesting comment on the reason for the change. China’s trade figures have repeatedly fallen short of expectations in the second half of this year, providing more evidence that China’s economy may be facing a sharper slowdown. Foreign direct investment will amount to $120 billion for the year, the earlier version of Ministry of Commerce report said, in line with official forecasts.

The earlier version of the report also said outward non-financial investment from China could also come in around the same level. That would mark the first time outward flows have pulled even with inward investment flows in China, and would imply a major surge in outward investment in December given that the current accumulated level stands slightly below $90 billion. The earlier version of the report also predicted that retail sales growth would come in at 12% for 2014, in line with the current average growth rate. In a separate report, the Chinese Academy of Social Sciences predicted that real estate prices in Chinese cities would continue to slide in 2015, with third- and fourth-tier cities hit hardest. But it said the market would have a soft landing as local governments take action to provide further policy support to the market.

Read more …

“.. the government will avoid fresh debt issuance and fund the package with unspent money from previous budgets and tax revenues that have exceeded budget forecasts due to economic recovery ..”

Japan Approves $29 Billion Stimulus Plan, Impact In Doubt (Reuters)

Japan’s government approved on Saturday stimulus spending worth $29 billion aimed at helping the country’s lagging regions and households with subsidies, merchandise vouchers and other steps, but analysts are skeptical about how much it can spur growth. The package, worth 3.5 trillion yen ($29.12 billion) was unveiled two weeks after a massive election victory by Prime Minister Shinzo Abe’s ruling coalition gave him a fresh mandate to push through his “Abenomics” stimulus policies. The government said it expects the stimulus plan to boost Japan’s GDP by 0.7%. Given Japan’s dire public finances, the government will avoid fresh debt issuance and fund the package with unspent money from previous budgets and tax revenues that have exceeded budget forecasts due to economic recovery.

With nationwide local elections planned in April which Abe’s ruling bloc must win to cement his grip on power, the package centers on subsidies to regional governments to carry out steps to stimulate private consumption and support small firms. Of the total, 1.8 trillion yen will be spent on measures such as distributing coupons to buy merchandise, providing low-income households with subsidies for fuel purchases, supporting funding at small firms and reviving regional economies. The remaining 1.7 trillion yen will be used for disaster-prevention and rebuilding disaster-hit areas including those affected by the March 2011 tsunami. Tokyo will also seek to bolster the housing market by lowering the mortgage rates offered by a governmental home-loan agency. “It’s better than doing nothing, but I don’t think this stimulus will have a big impact on boosting the economy,” said Masaki Kuwahara, a senior economist at Nomura Securities.

Read more …

Shopping vouchers?

Japan Approves $29 Billion Spending Package to Boost Economy

Japan’s government approved a 3.5 trillion yen ($29 billion) fiscal stimulus package to boost the economy after April’s sales tax hike caused consumption to slump. The measures include shopping vouchers, subsidized heating fuel for the poor and low interest loans for small businesses hurt by rising input costs, and will boost gross domestic product by 0.7%, the government estimates. The spending will be paid for with tax revenue and unspent funds and won’t need new bond issuance, Economy Minister Akira Amari said today in Tokyo. Unexpected falls in output and retail sales in November underscore the continued weakness in the economy. With little sign of a rebound in domestic demand, getting growth back on a recovery track is a priority for Prime Minister Shinzo Abe.

“This will support private consumption and boost regional economies, so that the virtuous economic cycle spreads to all corners of the nation,” Abe said in Tokyo after the decision. About 1.7 trillion yen will be spent on public works in areas damaged by natural disasters and to improve disaster preparedness, with 600 billion yen for revitalizing regional economies and 1.2 trillion yen to support people and small businesses hurt by the current economic situation, according to documents released by the Cabinet Office. The package is part of an extra budget for the fiscal year through March which will be adopted by the cabinet on Jan. 9, Finance Minister Taro Aso said in Tokyo today. The budget then needs to be approved by parliament, which is controlled by the ruling coalition.

Abe last month delayed the planned further hike in the sales tax by 18 months after data showed the economy fell into recession. GDP shrank an annualized 1.9% last quarter, more than initially estimated, after a 6.7% contraction in the three months from April, when the levy was raised for the first time since 1997. The postponement fueled concern about the government’s effort to rein in the world’s heaviest debt and prompted Moody’s Investors Service to cut its credit rating on Japan.

Read more …

“Japan’s work force of 80 million will drop to 40 million by 2060.”

The Keynesian End Game Crystalizes In Japan’s Monetary Madness (Stockman)

If the BOJ’s mad money printers were treated as monetary pariahs by the rest of the world, it would at least imply that a modicum of sanity remains on the planet. But just the opposite is the case. Establishment institutions like the IMF, the US treasury and the other major central banks urge them on, while the Keynesian arson squad led by Professor Krugman actually faults Japan for being too tepid with its “stimulus”. Now comes several new data points that absolutely confirm Japan is a financial mad house – even as its policy model is embraced by mainstream officials and analysts peering from a distance. Front and center is the newly reported fact from the Cabinet Office that Japan’s household savings rate plunged to minus 1.3% in the most recent fiscal year, thereby entering negative territory for the first time since records were started in 1955.

Indeed, Japan had been heralded as a nation of savers only a generation ago. During the era before it’s plunge into bubble finance in the late 1980s, households routinely saved 15-25% of income. But after nearly three decades of Keynesian policies, Japan has now stumbled into an insuperable demographic/financial trap; and one that is unusually transparent and rigidly delineated, to boot. Since Japan famously and doggedly refuses to accept immigrants, its long-term demographics are rigidly baked into the cake. Accordingly, anyone who will make a difference over the next several decades has already been born, counted, factored and attrited into the projections.

Japan’s work force of 80 million will thus drop to 40 million by 2060. At the same time, its current 30 million retirees will continue to rise, meaning that its retiree rolls will ultimately exceed the number of workers. Given those daunting facts, it follows that on the eve of its demographic bust Japan needs high savings and generous interest rates to augment retirement nest eggs; a strong exchange rate to attract foreign capital to help absorb its staggering $12 trillion of public debt, which already stands at a world leading 230% of GDP; and rising real incomes in order to shoulder the heavy taxation that is unavoidably necessary to close its fiscal gap and contain its mushrooming public debt.

With its debilitating Keynesian fiscal and monetary policies now re-upped on steroids under Abenomics, however, it goes without saying that nearly the opposite conditions prevail. Most notably, no household or institution anywhere in Japan can earn anything on liquid savings. The money market rate which determines deposit money yields was driven from a “high” of 100 basis points (as ridiculous as that sounds) at the time of the financial crisis to 10 basis points today, which is to say, nothing. But what is even more astounding is that the yield on the 10-year JGB dipped to an all-time low of 0.31% in recent trading. Given the militant insistence of the BOJ that it will hit its 2% inflation target come hell or high water, it is accurate to say that the official policy of Abenomics is to cause holders of the government’s long-term debt to loose their shirts.

Read more …

“Escape velocity”. Hadn’t heard that in while.

How Central Banks Saved The World (Stocks) In 2014 (Zero Hedge)

2014 was awash with potentially status quo destabilizing ‘realities’ to the “we’re back on track and world economic growth is about to reach escape velocity” meme… but time after time, the well-conditioned ‘investor’ was rescued… here’s how… Because – fun-durr-mentals.

Read more …

Love the picture.

Now Whitehall’s Crazy Eco Zealots Want To Ban Your Gas Cooker (Daily Mail)

As many as 14 million households slid their turkey into a gas oven yesterday, then waited for a succulent, browned and delicious meal to emerge. But such a familiar festive scene will be a thing of the past just a few years down the line, if the Government has its way. As for turning up the thermostat to ensure our gas boiler keeps our home snug and warm on a chilly festive morning – that simple action too, is under threat, even though some 90% of all homes in Britain are heated by gas. Householders across the country will be horrified to learn that, over the next decade or two, the Government plans to phase out all our gas-fired cookers and heating systems – forcing us to replace them at a cost of untold billions. Official documents reveal the Government is seriously contemplating that, within 25 years or so, gas will be all but banned — along with petrol and diesel.

The intention is that not only our cooking and heating but much else, including our cars and most of the vehicles on Britain’s roads, will have to be powered by electricity. The Government admits this astonishingly ambitious plan will be the most far-reaching energy revolution since electricity itself was discovered. But it is not being planned because our gas and oil supplies will have run out – or even because of any looming shortage. On the contrary, the world is now facing a glut of gas and oil, thanks in part to the ‘shale gas revolution’ led by the U.S., a country which almost overnight, has become the world’s largest natural gas producer as a result of a process called fracking – where water and sand are fired at high pressure into shale rock to release the oil and gas inside. This has led to plummeting prices, and prompted many industries to switch to gas.

Yet our own rulers want to abandon it. Astonishingly, the plan to change the way we cook our food and heat our homes is being instigated by the Government as the only way by which we can meet a statutory requirement under the Climate Change Act. This particular piece of legislative folly was pushed through Parliament six years ago by Ed Miliband, as our first ever Secretary of State for Energy and Climate Change, and decreed that Britain must cut its emissions of carbon dioxide from fossil fuels by a staggering 80% within 35 years. When this Act passed almost unanimously through Parliament in 2008, not a single MP, let alone Mr Miliband, had the faintest idea how we could actually meet such an improbable target.

Read more …

Got to admire the spin: “.. to “make management of public-sector finances more efficient ..”

Mexico Withdraws $3.4 Billion From Pemex as Oil Revenue Shrinks (Bloomberg)

Mexico’s Finance Ministry took out 50 billion pesos ($3.4 billion) from the state oil company Petroleos Mexicanos, according to a statement sent to the Mexican Stock Exchange. The payment this month was meant to “make management of public-sector finances more efficient,” according to the filing from the oil company, known as Pemex. The withdrawal marks a departure from the government’s usual methods of obtaining revenue from Pemex, which include taxes and royalties.

Pemex typically provides about a third of the federal budget, and its contributions dropped this year as the oil company faced production declines and falling crude prices. During the first 11 months of 2014, taxes paid by Mexico City-based Pemex declined by about 260 billion pesos, or 22%, from the same period of 2013, according to records. The withdrawal shows “a near addiction to Pemex’s revenue by the ministry,” Fluvio Ruiz, a board member of the oil company’s petrochemical unit, said in a phone interview. He said he had no prior knowledge of the disclosure through his role at the company.

Read more …

I don’t think he still believes in it.

Greece Faces New ‘Catastrophe’ As PM Battles To Avert Snap Elections (Observer)

Greece’s embattled prime minister, Antonis Samaras, issued an eleventh-hour appeal to parliamentarians on Saturday in an attempt to avert snap elections that would almost certainly plunge the eurozone into renewed crisis. In an impassioned plea, he urged MPs to rid the country of “menacing clouds” gathering over it by supporting the government’s presidential candidate when they gather for the final round of a three-stage vote on Monday. Failure would automatically trigger elections that radical leftists would be likely to win. The ballot has therefore electrified Greece, rattled markets and unnerved Europe. “I am once again appealing to all MPs, of all parties, to vote for the president of the republic,” Samaras told state television. “If we don’t elect a president the responsibility will hang heavily over those who don’t vote for [him]. They will be remembered by everyone, especially history.”

Samaras’s high-stakes gamble of calling the poll two months early has brought him face-to-face with the spectre of losing power if he fails to convince 12 MPs to back Stavros Dimas, his choice for the presidential post. A former European commissioner, Dimas received 168 ballots in a second round of voting last week – well short of the 200 required. On Monday he must amass 180 to be elected. Following a Christmas of frantic behind-the-scenes politicking, the prime minister warned of the perils of taking the debt-stricken country down the road of “absurd adventure” if deputies failed to endorse Dimas. “People do not want early elections… We gave sweat and blood in recent years to keep Greece standing upright.”

Read more …

Understatement of the day/week/month/year: “With so much cheap money sloshing around the global markets, a second financial crisis cannot be ruled out.”

Challenging UK Party Games Ahead As Greece Threatens 2nd Debt Crisis (Observer)

Europe. Emerging markets. Earnings. Equality. And the election. Look out, because 2015 is going to be the year of the five Es. In the UK, it will be the election that dominates the economic and business scene, particularly in the first half of the year and for much longer if the result is inconclusive. The prospect of a minority government living from hand to mouth would certainly unsettle the markets. But the election result will be influenced by the four other Es, starting with Europe, where the first crunch moment comes tomorrow in Greece with the third and final chance for the government of Antonis Samaras to get its choice of a new president through parliament. If he fails to secure 180 votes, there will be a snap election that the anti-austerity Syriza party is currently favourite to win. That would prompt fears of a fresh leg to Europe’s debt crisis, which began in Greece more than six years ago. This is something Europe can ill afford. The eurozone economy is barely growing; the German locomotive is slowing; and falling oil prices bring with them the threat of deflation.

The issue for the European Central Bank in 2015 is whether to take the plunge with a quantitative easing programme, something the Germans have resisted up until now. Berlin’s hardline stance has, however, softened in recent months as the situation in Russia – the key emerging market to watch – has deteriorated. Europe’s trade links with Russia are not all that important, but there are two big concerns. The first is of heightened geopolitical risk. Russia is being squeezed by western sanctions and now faces the inevitability of a deep recession in 2015. This might make Vladimir Putin more willing to come to terms over Ukraine, but it might not. The second risk is that the collapse of the rouble puts intolerable strain on Russian companies and Russian banks, with corporate losses ricocheting through the entire global financial system through the sort of highly leveraged derivatives trades that caused the 2007 meltdown. With so much cheap money sloshing around the global markets, a second financial crisis cannot be ruled out.

The third E is equality, brought to prominence in the past year not just by the bestselling book Capital by the French economist Thomas Piketty, but by evidence from the IMF and the Organisation for Economic Co-operation and Development that inequality is bad for growth. Standing trickle-down economics on its head, the OECD said recently that UK growth in the two decades from 1990 to 2010 would have been nine percentage points higher had it not been for widening inequality. Given that the trend towards greater inequality has been evident for the past three decades, it is worth asking why it has become a political issue now. The answer is simple. In the years leading up to the financial crisis, incomes were rising across the board. People on low and middle incomes didn’t mind all that much that the bankers and hedge fund owners were earning stratospheric sums when their own pay packets were going up.

Read more …

Think it’ll take that long?

You Can Put The Next Crash On Your 2016 Calendar Now (Paul B. Farrell)

With the recent budget bill, the too-big-to-fail banks were handed even more of what they’ve wanted: a further delay of the Volcker Rule, which could effectively kill it, and, worse, a rollback of Dodd-Frank provisions that protected taxpayers against abusive gambling in the shadowy global derivatives casino using Main Street depositors’ money. It’s as if we’re back to 1999, when the banks got Congress to erase the Glass-Steagall Act, which for 80 years protected Main Street by separating retail banks and investment banking. Now the banks are back to their speculation and gambling, exposing the economy to great risk, just as they were before the 1929 crash. As MarketWatch’s David Weidner put it, Yellen’s Fed looks to have forgotten that banks caused the Great Recession: that hellish era that was set off by the Bear Stearns, Lehman, Countrywide, AIG, Merrill, Freddie, Sallie and the other disasters.

Now Yellen’s Fed and our too-big-to-fail banks and their mainly Republican co-conspirators have set another big trap. A huge trap. As Stephen Roach, former chairman of Morgan Stanley Asia, wrote for Project Syndicate, Yellen’s Federal Reserve “is headed down a familiar — and highly dangerous — path.” “Steeped in denial of its past mistakes, the Fed is pursuing the same incremental approach that helped set the stage for the financial crisis of 2008-2009. The consequences,” writes Roach, “could be similarly catastrophic.” The next crash is due in 2016, around the presidential election. Why? Yellen’s brain is trapped in the same myopic capitalist dogma that blinded Greenspan for 18 years, forcing him to confess he “really didn’t get it till very late,” long after the $10 trillion market loss was a reality.

Same with Yellen. It will happen again. Losses bigger than 2000 and 2008 combined. Think I’m kidding? Bet against this at your peril. Jeremy Grantham’s already on record predicting that “around the presidential election or soon after, the market bubble will burst, as bubbles always do, and will revert to its trend value, around half of its peak or worse.” That could translate to the DJIA crashing – which on Friday posted the week’s (and history’s) second close above the 18,000 level – to around 10,000. The Dow crashing all the way back down to 10,000? Wow. Unimaginable. No wonder our brains tune out. Instead, we prefer the happy talk that will just keep coming out of Wall Street and Washington till 2016. We’ll keep denying reality … till it’s too late, and another $10 trillion loss is in the books.

Read more …

So the question is: did the internet facilitate the rise in propaganda?

2014: The Year The Internet Came Of Age (Guardian)

The best we can say about 2014 is that it was the year when we finally began to have a glimmer of what the internet might mean for society. Not the internet that we fantasised about in the early years, but the network as it has evolved from an exotic curiosity into the mundane underpinning of our lives – a general-purpose technology or GPT. And, in a way, the timescale is about right. The internet that we use today was switched on in January 1983, but it didn’t really become a mainstream medium until the web began to explode in 1993. So we’re about 21 years into the revolution. And what we know from the history of other GPTs is that it generally takes at least two decades before they form the unremarked-upon backdrops to everyday life.

In 1999, Andy Grove, then the CEO of Intel, the dominant chip-maker of the time, made a famous prediction. In five years’ time, he said, “companies that aren’t internet companies won’t be companies at all”. He was widely ridiculed for this pronouncement at the time. But in fact he was just being prescient. What he was trying to communicate was that the internet would one day become like the telephone or mains electricity – something that we take for granted. Grove’s point was that companies that boasted that they “were now on the internet” in 2004 would already be regarded as ridiculous. And so indeed they were.

Could we live without the net? Answer: on an individual level possibly, but on a societal level no – simply because so many of the services on which industrialised societies depend now rely on internet connectivity. In that sense, the network has become the nervous system of the planet. This is why it now makes no more sense to argue about whether the internet is good or bad than to debate whether oxygen or water are desirable. We’ve got it and we’re stuck with it. Which means that we’re also stuck with its downsides. While offline crime has decreased dramatically – car-related theft has reduced by 79% since 1995 and burglary by 67%, for example, what’s happened is that much serious crime has now moved online, where its scale is staggering, even if the official statistics do not count it.

The same goes for industrial espionage (at which the Chinese are currently the world champions) and counter-espionage and counter-terrorism (at which the NSA and GCHQ currently top the international league tables). And we’re just getting started on cyberwarfare. So here we are at the end of 2014, finally wising up to what we’ve got ourselves into: an internet that provides us with much that we love and value and would be hard put to do without. But an internet that is also dangerous, untrustworthy and comprehensively monitored. The question for 2015 and beyond is whether we can have more of the former and less of the latter. Happy New Year!

Read more …

A problem still in its infancy.

China Needs Millions of Brides ASAP (Bloomberg)

In the villages outside of Handan, China, a bachelor looking to marry a local girl needs to have as much as $64,000 – the price tag for a suitable home and obligatory gifts. That’s a bit out of the price range of many of the farmers who live in the area. So in recent years, according to the Beijing News, local men have been turning to a Vietnamese marriage broker, paying as much as $18,500 for an imported wife, complete with a money-back guarantee in case the bride fled. But that fairy tale soon fell apart. On the morning of November 21, sometime after breakfast, as many as 100 of Handan’s imported Vietnamese wives – together with the broker – disappeared without a trace. It was a peculiarly Chinese instance of fraud. The victims are a local subset of a fast-growing underclass: millions of poor, mostly rural men, who can’t meet familial and social expectations that a man marry and start a family because of the country’s skewed demographics.

In January, the director of China’s National Bureau of Statistics announced that China is home to 33.8 million more men than women out of a population exceeding 1.3 billion. China’s vast population of unmarried men is sure to pose an array of challenges for China, and perhaps its neighbors, for decades to come. What’s already clear is that fraudulent mail-order wives are only the start of a much larger problem. The immediate cause of China’s gender imbalance is a long-standing cultural preference for boys. In China’s patrilineal culture, they’re expected to carry on the family name, as well as serve as a social security policy for aging parents. In the 1970s, China’s so-called One Child policy transformed this preference into an imperative that parents fulfilled via sex selective abortions (made possible by the widespread availability of ultrasounds). As a result, millions of girls never made it onto China’s population rolls.

In 2013, for example, the government reported 117.6 boys were born for every 100 girls. (The natural rate is 103 to 106 boys to every 100 girls.) In the countryside, the ratio can run much higher — Mara Hvistendahl, in her 2011 book, Unnatural Selection, reports on a town where ratios run as high as 150 to 100. Long-term, such imbalances can create an excess of males that might reach 20% of the overall male population by 2020, according to one estimate. Of course, social expectations aren’t just confined to boys. In China, daughters are expected to marry up – and in a country where men far outnumber women, the opportunities to do so are excellent, especially in the cities to which so many of China’s rural women move. The result is that bride prices – essentially dowries paid to the families of daughters – are rising, especially in the countryside. One 2011 study on bride prices found that they’d increased seventy-fold between the 1960s and 1990s in just one representative, rural hamlet.

Read more …

Very real. Not some theory.

Rising Oceans Force Bangladeshi Farmers Inland for New Jobs (Bloomberg)

About seven years ago, Gaur Mondol noticed he couldn’t grow as much rice on his land as salty water seeped in from the Passur River, which stretches from his home in Bangladesh’s interior all the way to the Indian Ocean. Now the rice paddies are completely inundated, leaving the land barren. To find work, he must walk for miles each day to other villages. His annual income has fallen by half to 36,000 taka ($460). He makes about $4 a day if he’s lucky, and most of that goes to buy food for his family of four. “I’m always worried that my house will be washed away someday,” Mondol said from his home in Mongla sub-district, pointing to a river-side tamarind tree with water swirling around its exposed roots. “My family is constantly under threat as the river creeps in.” Rising sea levels are one of the biggest threats to the $150-billion economy over the next half a century, with farmers like Mondol already facing the consequences.

Bangladesh, which needs to grow at 8% pace to pull people out of poverty, stands to lose about 2% of gross domestic product each year by 2050, according to the Asian Development Bank. “The sea-level rise and extreme climate events are the two ways that salinity intrudes into the freshwater system,” Mahfuzuddin Ahmed, an adviser in the ADB’s regional and sustainable development department, said by phone from Manila. “The implication for food security is quite big.” Bangladesh is one of the world’s most densely populated countries, with half the U.S. population crammed into an area the size of New York state. About 50% of its citizens are directly dependent on agriculture for their livelihoods, a quarter live in the coastal zone, and 21% of these lands are affected by an excess of salinity.

The proportion of arable land has fallen 7.3% between 2000-2010, faster than South Asia’s 2% decline, with geography playing a large role. Bangladesh is nestled at a point where tidal waves from the Indian Ocean flow into the Bay of Bengal. While these create the Sundarbans mangroves, home to the endangered Bengal tiger, winds and currents cause saline water to mix with upstream rivers. Global weather changes worsen this. Bangladesh’s average peak-summer temperature in May has climbed to 28.1 degrees Celsius (83 Fahrenheit) in 1990-2009 from 26.9 in 1900-1930, and could rise to 31.5 degrees in 2080-2099, World Bank data show. Average June rainfall has dropped to 467.1 millimeter from 517.5 in that time.

Read more …

Wonderful.

Siberian Dog Allowed To Stay In Hospital Where Owner Died 1 Year Ago (RT)

The holiday spirit is alive and well in a hospital in Siberia, where Masha, Russia’s own ‘Hachiko’ dog was given permanent residence status. For a whole year the loyal pet kept ‘dogging’ the hospital, waiting for her owner who had passed away. Despite a number of attempts to have Masha adopted, the heartbroken pooch kept running away and coming back to the Novosibirsk District Hospital Number One, where she last saw her owner in December, 2013. “Masha will always stay here, because she is waiting for her owner. I think that even if we took her to his grave, she wouldn’t believe it. She’s waiting for him alive, not dead,” nurse Alla Vorontsova told the Siberian Times.

The dog’s heartbreaking story has gathered quite a bit of attention in Russia and even abroad, after it went viral in the media. The sad dachshund was adopted a number of times, but all unsuccessfully. “People in Russia tried to adopt her three times, but she always came back. I also heard that a number of foreigners wanted to adopt her too, but it is impossible – she doesn’t want to leave the hospital. And besides, we love her and she loves us. How could she live somewhere far away? She would just pine away,” Vorontsova said. For a year, hospital workers fed and walked Masha, and now they have finally managed to make it official; Masha has her own cozy spot inside the building.

“Here all the patients come to her, stroke her and give something tasty, especially the older people. She warms their hearts,” the nurse added. Masha’s elderly owner was admitted to the hospital and his dog was his sole visitor there. Masha’s loyalty earned her the media nickname Hachiko – in reference to the famous story of a Japanese Akita dog. Agricultural science professor Hidesaburo Ueno got Hachiko in 1924. The dog would greet the owner at the station every day. After Ueno passed away, Hachiko kept returning to the train station for 10 years, waiting for him to come back. The amazing story turned the pet into a national hero and later inspired a Hollywood movie, ‘Hachiko: A Dog’s Tale,’ starring Richard Gere.

Read more …