Mar 262016
 
 March 26, 2016  Posted by at 9:29 am Finance Tagged with: , , , , , , , , ,  1 Response »


Jack Delano Freight operations on the Indiana Harbor Belt railroad 1943


• US Q4 GDP Rose 1.4% As Corporate Profits Plunged (ZH)
• World Trade Collapses in Dollars, Languishes in Volume (WS)
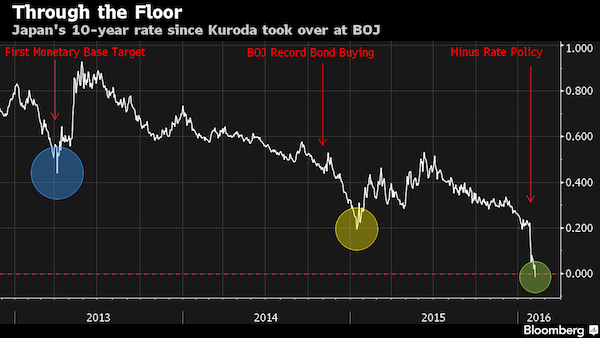
• Bank of Japan’s Latest PR Move: ‘Negative Rates in Five Minutes’ (WSJ)
• Foreigners Dumped More Japanese Stocks This Week Than Ever Before (ZH)
• Yuan’s Fall Drags Down Chinese Companies (WSJ)
• Shanghai Rolls Out Tightening Measures To Cool Home Market (Reuters)
• Affordable Housing Crisis Has Engulfed All Cities In Southern England (G.)
• Radical Economic Ideas Grab Attention Amid Low-inflation Torpor (SMH)
• Modern Monetary Theory Has Ardent Proponents (SMH)
• Brazil Economic Woes Deepen Amid Political Crisis (WSJ)
• The River: America’s 40-Year Hurt (BBC)
• Hope Turns To Despair As Lesbos Camp Becomes Open-Air Prison (Ind.)

“The resilient consumer”. Sure.

• US Q4 GDP Rose 1.4% As Corporate Profits Plunged (ZH)

While the final revision to Q4 2015 GDP was so irrelevant it was released on a holiday when every US-based market is closed, even the futures, it is nonetheless notable that according to the BEA in the final quarter of 2015 US GDP grew 1.4%, up from the 1.0% previously reported, and higher than the 1.0% consensus estimate matching the highest Q4 GDP forecast. The final Q4 GDP print was still well below the 2.0% annualized GDP growth reported in Q3.


The figure marks a slowdown from the 2.2% average pace in the first three quarters of 2015. For all of last year, the U.S. economy grew 2.4% matching the advance in 2014. The reason for the change was largely due to upwardly Personal Consumer Spending, which rose from a contribution of 1.38% to the annualized bottom line to 1.66%. In CAGR terms, personal consumption rose 2.4%, following the 3.0% increase in Q3, higher than the 2.0% previously estimated.

Stripping out inventories and trade, the two most volatile components of GDP, so-called final sales to domestic purchasers increased at a 1.7% rate, compared with a previously estimated 1.4% pace.  The rest of the GDP components were largely unchanged, with Fixed Investment adding 0.06% to the bottom line, up from 0.02% in the previous estimate, Private Inventories contracting fractionally more than previously estimated (-0.22% vs -0.14%), net trade subtracting 0.1% less from growth (-0.14% vs -0.25%), and finally government spending largely unchanged and hugging the unchanged line at 0.02%.


But while the “resilient consumer” once again carried the US economy in the fourth quarter, largely due to an estimated jump in spending on Transportation and Recreational services, which added an annualized $13 billion to the US economy vs the prior estimate, more disturbing was the drop in profits which we already knew courtesy of company reports and is known confirmed by the BEA whose GDP report also showed that corporate profits dropped in 2015 by the most in seven years. As Bloomberg writes, the earnings slump illustrates the limits of an economy struggling to gather steam at the start of this year. Some companies, encumbered by low commodities prices and sluggish foreign markets, are cutting back on investment while a firm labor market and low inflation encourage households to keep shopping.

Pre-tax earnings declined 7.8%, the most since the first quarter of 2011, after a 1.6% decrease in the previous three months. The estimate of nonfinancial corporate profits was reduced by a $20.8 billion settlement, considered a transfer to the government, between BP and the U.S. after the 2010 oil spill in the Gulf of Mexico. Profits in the U.S. dropped 3.1% in 2015, the most since 2008. Corporate earnings are being weighed down by weak productivity, rising labor costs and the plunge in energy prices. Economists at JPMorgan had expected a 9.5% drop in pre-tax earnings in the fourth quarter. “The pace of growth slowed as we ended 2015, though consumer spending is still the primary underpinning of this economic expansion,” Sam Bullard at Wells Fargo in Charlotte, North Carolina, said before the report. “Any pickup we might see is still likely going to be capped given the overall global picture.”

Read more …

Globalization is ending.

• World Trade Collapses in Dollars, Languishes in Volume (WS)

The Merchandise World Trade Monitor by the CPB Netherlands Bureau for Economic Policy Analysis, a division of the Ministry of Economic Affairs, tracks global imports and exports in two measures: by volume and by unit price in US dollars. And the just released data for January was a doozie beneath the lackluster surface. The World Trade Monitor for January, as measured in seasonally adjusted volume, declined 0.4% from December and was up a measly 1.1% from January a year ago. While the sub-index for import volumes rose 3% from a year ago, export volumes fell 0.7%. This sort of “growth,” languishing between slightly negative and slightly positive has been the rule last year. The report added this about trade momentum:

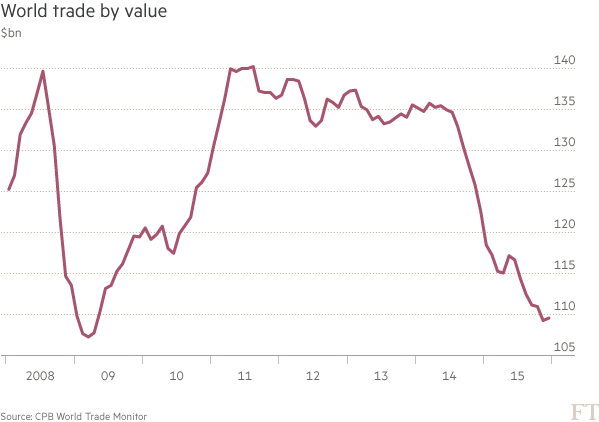
“Regional outcomes were mixed. Both import and export momentum became more negative in the United States. Both became more positive in the Euro Area. Import momentum in emerging Asia rose further, whereas export momentum in emerging Asia has been negative for four consecutive months.” This is also what the world’s largest container carrier, Maersk Lines, and others forecast for 2016: a growth rate of about zero to 1% in terms of volume. So not exactly an endorsement of a booming global economy. But here’s the doozie: In terms of prices per unit expressed in US dollars, world trade dropped 3.8% in January from December and is down 12.1% from January a year ago, continuing a rout that started in June 2014. Not that the index was all that strong at the time, after having cascaded lower from its peak in May 2011.

If June 2014 sounds familiar as a recent high point, it’s because a lot of indices started heading south after that, including the price of oil, revenues of S&P 500 companies, total business revenues in the US…. That’s when the Fed was in the middle of tapering QE out of existence and folks realized that it would be gone soon. That’s when the dollar began to strengthen against other key currencies. Shortly after that, inventories of all kinds in the US began to bloat. Starting from that propitious month, the unit price index of world trade has plunged 23%. It’s now lower than it had been at the trough of the Financial Crisis. It hit the lowest level since March 2006:
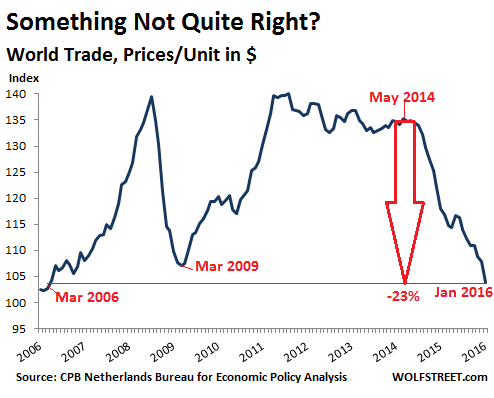
This chart puts in perspective what Nils Andersen, the CEO of Danish conglomerate AP Møller-Maersk, which owns Maersk Lines, had said last month in an interview following the company’s dreary earnings report and guidance: “It is worse than in 2008.” But why the difference between the stagnation scenario in world trade in terms of volume and the total collapse of the index that measures world trade in unit prices in US dollars? The volume measure is a reflection of a languishing global economy. It says that global trade may be sick, but it’s not collapsing. It’s worse than it was in 2011. This sort of thing was never part of the rosy scenario. But now it’s here.

Read more …

‘Explaining’ what they don’t understand themselves.

• Bank of Japan’s Latest PR Move: ‘Negative Rates in Five Minutes’ (WSJ)

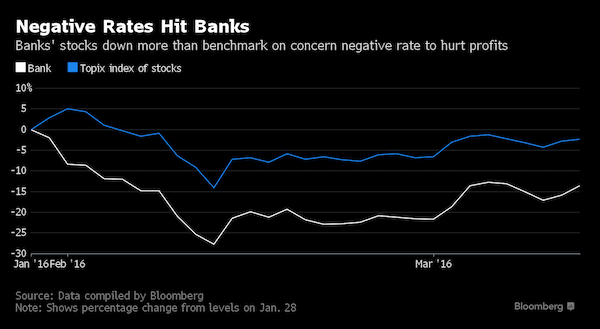
The Bank of Japan launched a charm offensive Friday to win over spooked members of the public who have reacted negatively to negative interest rates. The central bank issued a booklet offering a crash course in the basic implications of negative rates, a move that demonstrates the strength of unease created by the introduction of a policy in a nation largely unfamiliar with the concept behind it. Written in a question-and-answer format and in a somewhat casual Japanese, the three-page booklet aims to explain negative rates “in five minutes” by covering 18 issues that have grabbed public attention. Negative rates have become a political hot potato ahead of July’s national elections, with opposition lawmakers accusing the central bank of creating anxiety among consumers. Some ruling party politicians, perhaps feeling uncomfortable about the prospect of explaining the policy to their constituents, are also feeling the jitters.

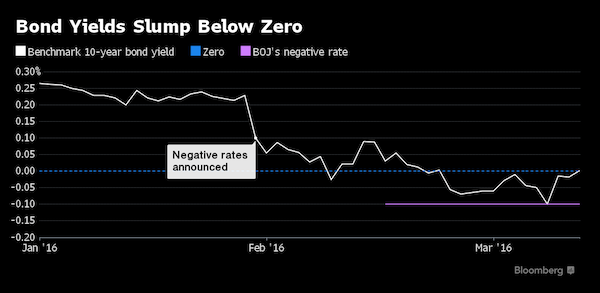
Prime Minister Shinzo Abe acknowledged Thursday that negative rates have made households nervous and it will likely take some time before people understand them. The Bank of Japan decided to start charging interest on some deposits held by commercial banks at the central bank in January. The policy is part of broader efforts to defeat deflation and create a stronger economy, but the central bank was ill-prepared for the public backlash the policy generated. One of the most common concerns over the policy is whether individuals with regular bank accounts will be charged interest on their deposits at the commercial banks. Opposition lawmakers have frequently quizzed BOJ Gov. Haruhiko Kuroda on this issue in parliament.

“Although the measure is called negative rates, it only involves imposing negative rates on a part of the money deposited at the BOJ by banks,” the booklet says. “Individuals’ deposits are different.” While addressing concerns over the new policy, the central bank also tries to convey the message that Japan must get rid of deflation, a negative cycle of price falls, adding that it has taken the right steps to do just that. “If prices don’t rise because of deflation, this means companies’ revenues don’t increase, and that’s why salaries don’t rise,” the booklet says. Since company earnings have improved a lot during the past three years of monetary easing, firms have started increasing basic pay, it says, adding that salaries will keep rising each year if deflation is overcome.

Read more …

“..weakness means weak Japanese economy means sell Japanese assets.. and we will soon see capital controls in the world’s largest debtor nation…”

• Foreigners Dumped More Japanese Stocks This Week Than Ever Before (ZH)

USDJPY just had its best week in 2 months, funding bullish momentum and carry trades around the world in the midst of dismal economic data everywhere and tumbling earnings expectations. This "bullish" Yen strength, however, amid China's biggest weekly devaluation in almost 3 months, was ironically driven by drastic investment outflows – record sales of Japanese stocks by foreigners (sell JPY), and record purchases of foreign bonds by Japanese investors (sell JPY). Sooner, rather than later, it is obvious that the investment outflows will dominate the carry trades (see Thursday and Friday) and Kuroda and Abe will have a major problem.

Yen was dumped all week…


Which provided just enough juice for carry trades to lift Japanese stocks (despite the weakness in data and China's biggest weekly Yuan devaluation in almost 3 months)


But notice that the last two days have seen Japanese stocks decouple from USDJPY, perhaps the first glimpse of the investment outflows overwhelming any casino-based carry trades flows.

And this is why… Foreigners sold a record amount of Japanese stocks last week… (implicitly meansing Yen was sold)


And Japanese investors fled the insanity of record low yields in JGBs, buying a record amount of foreign bonds last week (implicitly selling Yen again)…


So the Yen weakness – which was so bullishly supportive of global equity markets via carry – was in fact a signal of massive investor anxiety fleeing the sinking ship. Peter Pan-ic indeed.

Abe and Kuroda will soon face a major problem as a weaker Yen will signal the exact opposite trade that has been so active since 2012 – weakness means weak Japanese economy means sell Japanese assets.. and we will soon see capital controls in the world's largest debtor nation.

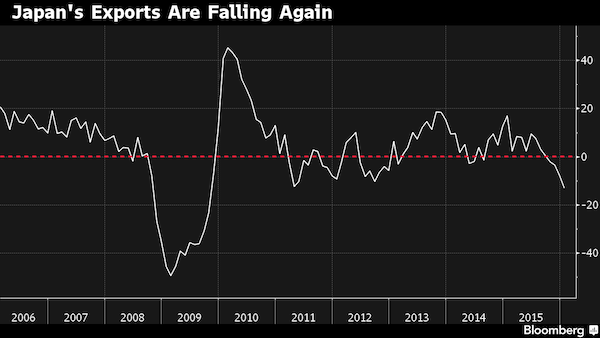
And remember – the devaluation of The Yen has done nothing – NOTHING – to improve exports for Japan…

Read more …

It’s all about the dollar.

• Yuan’s Fall Drags Down Chinese Companies (WSJ)

A weaker Chinese currency has roiled global markets and heightened worries about the state of the world’s second-largest economy. Now, some Chinese companies are reporting they’ve taken a hit from a depreciating yuan. The yuan fell 5% against the U.S. dollar in 2015, plunging after China’s central bank surprisingly devalued the currency in mid-August. A weaker currency helps the country’s exporters but hurts Chinese companies that pay for raw material in U.S. dollars or need to pay off loans in U.S. dollars. Among those negatively affected are firms that source from outside China, such as milk or food companies, as well as real estate companies that hold a lot of dollar-denominated debt, says Herald van der Linde at HSBC.

This was the case with Hengan International, one of the leading makers of tissue paper in China. The company said in a statement it saw $55.3 million in foreign-exchange losses in 2015 because it pays for raw material in U.S. dollars, holds U.S.-denominated debt and has Hong Kong-based yuan-denominated assets, which dropped in value. This contributed to a decline in tissue sales, it said. Weaker currencies also hurt China’s heavily-indebted real-estate developers. Shanghai-based property developer Shui On Land reported its 2015 profit dropped to 1.77 billion yuan ($272 million) from 2.49 billion yuan ($382 million) a year earlier in large part due to the depreciation of the company’s USD- and HKD-denominated debt. Then there are companies that suffer losses from selling to countries whose currencies have weakened.

Sourcing and logistics giant Li&Fung said 2015 revenue dropped 2.4% on year. The main reason? Foreign-exchange losses from weak European and Asian currencies, it said, since 38% of the company’s business is in non-U.S. markets but it accounts in U.S. dollars. In order to tackle the problem, some companies are looking to shed yuan — or at least get it out of the country. Hengan, the tissue company, has remitted the equivalent of several billion Hong Kong dollars from mainland China to Hong Kong in 2015, and another HK$2 billion in the first quarter of this year, said CFO Vincent Loo in Hong Kong. It is also negotiating with sources to pay them in less time — from 30 to 60 days rather than 90 — just in case the yuan continues to fall.

Read more …

Beijing’s ‘vision’ is now limited to short term only.

• Shanghai Rolls Out Tightening Measures To Cool Home Market (Reuters)

Municipal authorities in Shanghai tightened mortgage down payment requirements for second home purchases on Friday, in a move to cool an overheating property market and reduce fears of a bubble. Senior Chinese leaders raised concerns about the country’s overheated housing market during an annual parliament meeting this month, and Shanghai is the biggest city to take action in the wake of the National People’s Congress, which ended a week ago. Under the new rules, home buyers will need to put down 50-70% of the price of a second home, compared to 40% previously, to qualify for a mortgage. “The new measure will have a big impact on market sentiment on both the primary and secondary market; new launches being sold out within one, two hours will not happen again,” said Joe Zhou, head of East China research at real estate services firm Jones Lang LaSalle.

With the new rules, Shanghai also made it harder for non-residents to buy homes in the city, according to a statement issued by the local government. Potential buyers who do not hold local residence permits, or hukou, must have paid social insurance or taxes in Shanghai for at least five years before they can purchase property. Previously the requirement was two years. Shanghai will also increase the supply of small- and medium-sized homes and crack down on property financing by informal financial institutions. Shanghai home prices gained 20.6% in February from a year ago, posting the second biggest gain in the country after the southern city of Shenzhen, where prices soared 56.9%, despite slowing economic growth.

Read more …

A world full of housing bubbles. Haven’t we understood how dangerous that is?

• Affordable Housing Crisis Has Engulfed All Cities In Southern England (G.)

There is no longer a city in the south of England where house prices are less than seven and a half times average local incomes, according to analysis by Lloyds Bank that reveals how the home affordability crisis now stretches far beyond London. “The housing affordability gap has widened to its worst level in eight years,” said the Lloyds analysis, noting that the last time prices were so high was at the very top of the boom in 2008, just before the financial crisis struck. The Lloyds analysis is unique in that it compares local house prices with local earnings rather than national averages. On this measure, the worst house prices are not in London but in other parts of the south-east. Oxford is again identified as the least affordable city in the UK, with average prices at 10.68 times local earnings.

Winchester is a close second at 10.54, with London third at 10.06. Cambridge, Brighton and Bath all have prices that are now nearly 10 times local earnings, while cities such as Bristol and Southampton have prices close to eight times earnings. Wage growth has fallen far behind the rise in house prices, said Lloyds, with affordability worsening for the third successive year. The average home in a city in the UK now costs 6.6 times average local earnings, up from 6.2 last year. In the 1950s and 1960s, buyers could typically find homes with mortgages of three to four times their income. But the Lloyds figures show that there is now just one city in the UK that fits that profile: Derry in Northern Ireland. House prices in the city currently fetch 3.81 times local incomes.

While most of the “most affordable” cities in the Lloyds rankings are in the north, Scotland and Northern Ireland, buyers will still be stretched to afford a home from the local salaries on offer. Hull is widely regarded as a low house price area, yet local residents face having to pay 5.11 times average local incomes to buy a home. Meanwhile, York has joined the ranks of cities in the south in the unaffordability tables, with prices at 7.5 times incomes.

Read more …

When crazy ‘conventional’ ideas fail…

• Radical Economic Ideas Grab Attention Amid Low-inflation Torpor (SMH)

Our economic guardians at Federal Treasury and the Reserve Bank sound increasingly uneasy about some policy choices being made offshore. Since the global financial crisis, quantitative easing has pumped trillions of dollars into major economies with limited success. More recently central banks in Europe and Japan have opted for negative interest rates in a bid to kick-start growth. On Tuesday the Treasury Secretary, John Fraser, pointed out that we’ve now been in an “experimental stage” with monetary policy for more than seven years. “A range of different interventions have been tried with, at least to date, mixed results,” he said. “Sadly, we will have to await the passage of years before we can pass final judgment.” What is clear, warned Fraser, is that these unusual policies “have had a pervasive and frankly quite worrying impact on the pricing of financial risk.”

Earlier this month the Reserve’s deputy governor, Philip Lowe, said it was “very rare” for central banks to worry that inflation is too low. “Yet today, we hear this concern quite often, and the ‘unconventional’ has almost become conventional,” he said. Lowe warned the abnormal monetary policies being adopted in some countries were “a complication for us” because they put upward pressure on exchange rate. But in a world where traditional economic remedies are proving ineffective a swag of other unorthodox policy suggestions are getting a hearing. One controversial option being canvassed by experts is for central banks to deliver “helicopter drops” of cash directly to citizens’ bank accounts in the hope they will spend it and revive growth. Even more radical is a proposal for governments to mandate an across-the-board pay rise for workers.

Olivier Blanchard, a former chief economist at the IMF, and Adam Posen, president of the Peterson Institute for International Economics, recently recommended the Japanese government try this approach to boost growth. The Bank of England’s chief economist, Andy Haldane, raised eyebrows last September when he argued abandoning cash altogether would make it easier for central banks to manage downturns. He warned that in future it might be necessary for central banks to opt for negative interest rates when depositors are charged for putting their money in the bank in a bid to encourage spending. One problem with that strategy, however, is that people are likely to convert deposits into cash. Eliminating cash and replacing it with a government-backed digital currency would remove that option. “This would preserve the social convention of a state-issued unit of account and medium of exchange… But it would allow negative interest rates to be levied on currency easily and speedily,” Haldane said.

Read more …

A second part from the article above.

• Modern Monetary Theory Has Ardent Proponents (SMH)

As central banks struggle to revive growth, attention has shifted to fiscal policy the way governments use taxation and spending to influence the economy. Even the hard-heads at the IM have advised governments, including Australia’s, to spend more especially on infrastructure. The fund’s most recent assessment of our economy said “raising public investment (financed by borrowing, thus reducing the pace of deficit reduction) would support aggregate demand, take pressure off monetary policy, and insure against downside growth risks.” Amid these debates about fiscal policy, a radical school of thought called Modern Monetary Theory, or MMT, has gained more prominence. Proponents of this theory have been on the periphery of mainstream economics for more than two decades but their profile has been raised by this year’s US presidential race.

Academic economist Stephanie Kelton , a leading advocate of MMT, is an adviser to presidential hopeful, Senator Bernie Sanders. Kelton calls herself a deficit “owl” rather than a deficit hawk or dove. The hawks, of course, have a straightforward view of government finances: deficits are bad. The doves say deficits are necessary when economic times are tough but they should be balanced by surpluses over time. But deficit owls like Kelton have a far more radical take: deficits don’t matter. The starting point for Modern Monetary Theory is that a currency issuing government can keep printing and spending money but never go broke, so long as it doesn’t borrow in a foreign currency. The Australian Commonwealth, for example, will never run out of Australian dollars because it is a monopoly issuer of that currency.

It can always create the money it needs and, therefore, will always be able to service debts. The MMTers claim that in the modern era of floating exchange rates and deregulated financial markets, governments can, and should, run deficits whenever they are needed. There is a strong moral case for this: in a modern economy, there’s no good reason to have unemployed labour or capital. For the MMTers mass unemployment is a great evil and its daily, human cost dwarfs other economic challenges. They acknowledge there are limits to government spending. Resources in the real economy can be constrained and taxes are an essential tool to ensure demand for the currency and to cool the economy if it overheats. But there’s plenty of scope for governments to print and spend money without causing inflation or triggering a financial crisis. MMTers say sophisticated modern economies like the US and Australia are in no danger of the hyper-inflation which plagued Zimbabwe last decade or Germany’s Weimar Republic in the 1930s.

Read more …

Barely functioning, politically nor economically.

• Brazil Economic Woes Deepen Amid Political Crisis (WSJ)

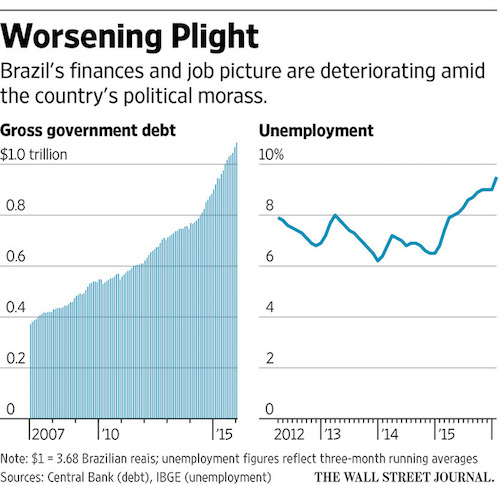
Brazil’s economic crisis is as bad as its political one. Latin America’s biggest economy appears headed for one of its worst recessions ever. It stalled in 2014, shrank 3.8% last year and now faces a similar contraction this year. Unemployment rose to 9.5% on Thursday as wages fell 2.4%, both trends forecast to worsen. One in five young Brazilians is out of work, and Goldman Sachs says Brazil may be facing a depression. The deteriorating outlook forms a dire backdrop for Brazil’s political straits. President Dilma Rousseff, deeply unpopular, faces impeachment proceedings in Congress amid a widening corruption scandal surrounding the state oil company, Petróbras. That situation is consuming so much energy from policy makers and Congress that the economic downturn isn’t getting the attention it needs, observers say.

“The gravity of the situation is this: We have the kind of problems where if nothing is done, things will definitely get worse,” said Marcos Lisboa, a former finance ministry official who is now president of the Insper business school in São Paulo. “Pretty soon we could be talking about the solvency of the federal government.” Brazil fended off the results of the 2008 global downturn with stimulus spending, and is trying to again inject money into the economy to spur demand. In January, the Rousseff administration unveiled some $20 billion of subsidized loans from state-owned banks such as the BNDES to boost agriculture and builders of big infrastructure projects.

But this time, the country has less leeway to fund stimulus measures. Brazil’s tax take is diminishing, and the Planning Ministry said Tuesday the government needs to cut around $5.9 billion of spending to meet its budget target. On Thursday, Finance Minister Nelson Barbosa asked Congress to loosen the target to allow a bigger deficit in 2016. Some investors say stimulus policies such as cheap credits from state banks haven’t done much long-term good, because they produced big deficits and the money was often poorly invested in money-losing dams and refineries.
Read more …

“..very few people understood that an epochal change had taken place in the American economy. GDP would grow. Income wouldn’t.”

• The River: America’s 40-Year Hurt (BBC)

Bruce Springsteen is coming to London with the River tour. At £170 for the cheapest pair, I can’t afford to see the Boss any more, even if my body could handle standing on Wembley Stadium’s pitch for three-and-a-half-hours in an early June drizzle. It’s interesting that Springsteen is re-exploring The River album again. Whenever the anger that simmers in America erupts and reminds the rest of the world that the country is troubled, he seems to be the cultural figure whose work offers an explanation. In late 1986, midway through Ronald Reagan’s second term of office, with the twin scourges of Aids and crack racing through American cities and New Deal ideas of economic and social fairness consumed by the Bonfire of the Vanities taking place on Wall Street, Britain’s Guardian newspaper ran an editorial that said, “for good or ill, [America] is becoming a much more foreign land”.

I had just celebrated my first anniversary as an ex-pat in London and wrote an essay trying to explain what America was like away from the places Guardian readers knew. I described the massive population dislocations that followed the long recession that had begun in the mid-70s. I referenced Springsteen. The piece ran under the headline “Torn in the USA”. Now America is going through even worse ructions. But there is nothing fundamentally new. What we are seeing is the continuation of a disintegration that began forty years ago around the time Springsteen was writing the title song of the album. The River, which came out in 1980, was very much about guys trying to kick back at father time and stave off the inevitable arrival of life’s responsibilities – wife, kids, job, mortgage – and the equally probable onset of life’s disappointments in wife, kids, job, mortgage, and in oneself.

The title track is a long, mournful story about that process and the narrator’s desire to reconnect to the person he was when younger and full of hope. “I come from down in the valley / Where mister, when you’re young / They bring you up to do/like your daddy done…” The key point is being brought up to be like your father. Work the same job, carry yourself in the same way, do the right thing. In the song this tie that binds is seen as restricting the choices you can make in life. Your daddy worked in a steel mill, you will work in a steel mill, or on the line at River Rouge, or down a mine. Today, what wouldn’t many of us give for the economic and social stability that gave resonance to Springsteen’s lyrics? A union job, 30 years of work, a pension. Sounds sweet. The narrator of the song goes on to tell us, “I got a job working construction at the Johnstown company / but lately there ain’t been much work on account of the economy.”

Springsteen based the song on the struggle of his brother-in-law to stay employed during the bleak days after the Oil Shock of 1973: a half-decade of inflation and economic stagnation. At the time this stagflation was seen as a cyclical event, the economy would rebound soon. It would be boom time for all. The economy did rebound, but then went into recession in 1982, and rebounded and went into recession at regular intervals, until the near-death experience of 2007/2008. But very few people understood that an epochal change had taken place in the American economy. GDP would grow. Income wouldn’t. Median salaried workers’ wages stagnated. Those working low-wage jobs saw their incomes decline. As for job security, a perfect storm of automation, declining union power, and free-trade agreements put an end to that.

Read more …

All the time I’m thinking someone must stand up and say ‘till here and no further’. But instead, Europe tumbles to new lows on a daily basis.

• Hope Turns To Despair As Lesbos Camp Becomes Open-Air Prison (Ind.)

Even before it became a holding pen, Moria was a pretty poor registration centre, unable to provide basic facilities and painfully slow to process the thousands of refugees and migrants who arrive on the shores of Lesbos every week. But since midnight on Sunday, when the new EU-Turkey migrant deal came into force, refugees have been picked up by the coastguard and transported directly to Moria by the Greek authorities. The camp has become an open-air prison, a compound of temporary buildings on a hill overlooking the coast of this island, not far from Turkey’s Mediterranean coast. It is to here that all arrivals must wait for the news their long struggle to reach Europe will almost certainly get them no further than the Greek islands.

They will be returned to Turkey, which the EU has now declared a safe country, in its bid to stem the biggest refugee crisis since the Second World War. The lightning fast implementation of the deal, signed last Friday, has stretched to the limit the capacity of the Greek government, which has no means to process the asylum claims that everyone who arrives has the right to make. Those who came looking for peace and a better life have instead found themselves locked up, and handed detention papers. In response, aid agencies have dropped out of their involvement at the centre one by one, refusing to be associated with the detention of migrants – among whom are more than 100 unaccompanied children. Oxfam this week said the development was “an offence” to Europe’s values.

“They have told us nothing,” says Naima Abdullah, 28, speaking through the chain link fence, her four-year-old daughter Mirna by her side. She paid $2,000 for herself, Mirna, and her one-month-old baby to cross the sea from Turkey after fleeing air strikes in rural Damascus three months ago. She arrived on Sunday, in the first boats after the deal came into force. But four days later, she still hadn’t been given an opportunity to register a claim for asylum. And as the numbers grow, observers worry the only possible outcome will be the mass expulsions Europe has promised to avoid. Nadine Abuasil, 25, said she came to Lesbos because life in Turkey since she fled Deraa in Syria a month ago was not worth living. Her family were blackmailed for money by local gangs, and there was no work in a country that is expensive to live in. “We cannot go back to Turkey,” she says simply.

She and her 23-year-old brother arrived on Sunday after a five hour boat journey during which two men died. They had apparently suffocated. She points to the ground of the detention centre. “We would rather die here than in Turkey.” Her brother, Mohammed, was no less emphatic when asked what he’d do if he was forced to return. “I don’t speak English,” he says. “But: kill myself, kill myself.” The deal has been decried by human rights groups and legal experts who question if Turkey can be considered a safe third country for the forcible return of migrants, and if Greece, which has floundered under the pressure of more than one million refugees arrivals in the past year, is capable of processing asylum claims – even with promised outside help.

“Greece has effectively been asked to build an asylum system in two weeks,” says Camino Mortera, a research fellow for the Centre for European Reform and a specialist in EU law. “The EU claims there won’t be returns en masse but if you are not able to process people in a regulated fashion, how else are they going to deal with this?”
Read more …

Mar 242016
 
 March 24, 2016  Posted by at 9:28 am Finance Tagged with: , , , , , , , , , , ,  2 Responses »


John M. Fox National Peanut Corp. store on Broadway, NY 1947

• Goldman to Fed: Stop Worrying So Much About the Stronger Dollar (BBG)
• China Sends Fed A Warning: Devalues Yuan By Most In 2 Months (ZH)
• Pimco Sees 7% Drop For Yuan, ‘No. 1 Risk For Global Economy This Year’ (BBG)
• Kyle Bass Is Wrong On China: Policy Adviser Li (CNBC)
• China’s Debt Bubble Threatens Global Economy (Nikkei)
• China Online P2P Financing Firms Face More Regulation (WSJ)
• There’s No Sign of a China Rebound (BBG)
• China Exports Its Environmental Problems (BBG)
• Liquidity Death Spiral Traps Credit Suisse (BBG)
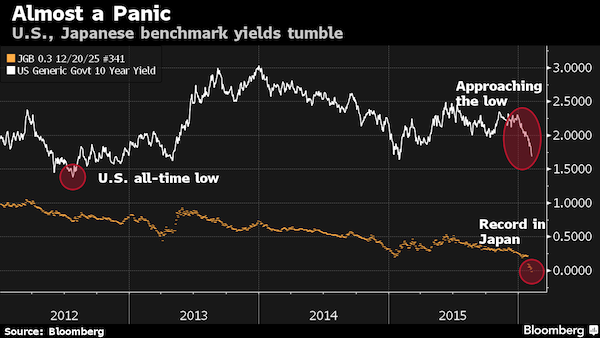
• Japan’s Bond Market Is Close to Breaking Point (BBG)
• US Oil Falls After Big Jump In Stockpiles (Reuters)
• Osborne’s Disability Cuts Are Devastating Families (G.)
• Trump Is Right – Dump NATO Now (David Stockman)
• Methane and Warming’s Terrifying New Chemistry (McKibben)
• EU Border Agency Has Less Than A Third Of Requested Police (AFP)
• Key Aid Agencies Refuse Any Role In ‘Mass Expulsion’ Of Refugees (G.)

Everybody knows a stronger dollar is inevitable. Priced in.

• Goldman to Fed: Stop Worrying So Much About the Stronger Dollar (BBG)

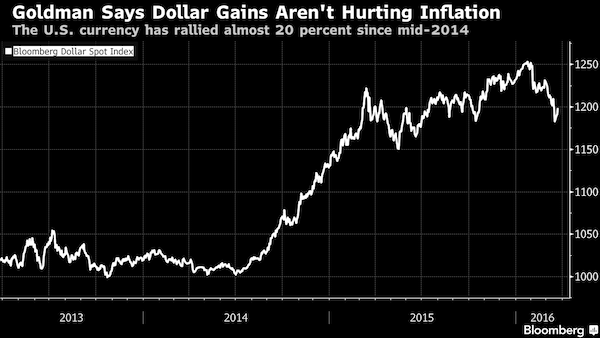
It’s time for the Federal Reserve to end its dollar fixation. That’s the takeaway from a Goldman Sachs report Wednesday that suggests the U.S. currency poses little threat to the Fed’s inflation goals, challenging policy makers’ comments to the contrary. That’s good news for dollar bulls who are betting on expanded monetary-policy divergence between the U.S., Europe and Japan. Inflation is at the heart of the Fed’s debate about the timing of interest-rate increases as officials look to normalize monetary policy after seven years of near-zero interest rates. With a stronger dollar not translating into significantly cheaper import prices, Goldman Sachs suggests the central bank faces fewer headwinds to hiking rates than markets are currently pricing in.

“The majority of the effects of a stronger dollar on import prices have already been realized,” analysts Zach Pandl and Elad Pashtan wrote in the note. “Inflation data to date appears to be more closely tracking a path with less dollar pass-through to core inflation” than implied by the Fed’s projections for consumer prices. Investors agree. The gap between yields on Treasury Inflation-Protected Securities and nominal 10-year notes, known as the break-even rate, climbed to the highest since August earlier this week. The measure indicates inflation will average about 1.59% over the next decade, compared with 1.2% last month. The Bloomberg Dollar Spot Index, which tracks the currency versus 10 peers, advanced 0.7% on Wednesday, extending its longest streak of gains since the period ending Feb. 16.

Read more …

Fed must hike?!

• China Sends Fed A Warning: Devalues Yuan By Most In 2 Months (ZH)

With the USD Index stretching to its longest winning streak of the year, jawboned by numerous Fed speakers explaining how April is ‘live’ (and everyone misunderstood the dovishness of Yellen), it appears that The PBOC wanted to send a message to The Fed – Raise rates and we will unleash turmoil on your ‘wealth creation’ plan. Large unexpected Yuan drops have rippled through markets in recent months spoiling the party for many and tonight, by devaluing the Yuan fix by the most since January 7th, China made it clear that it really does not want The Fed to hike rates and cause a liquidity suck-out again. The last 4 days have seen nearly a 1% devaluation in the Yuan fix with today’s drop the biggest in over 2 months…


And while everyone is quietly commenting on how “stable” the Yuan has been this year, the truth is that is only the case against the USD, the Yuan basket has been consistently devaluing since PBOC admitted it was more focused on that than the USD only…

The last time they sent a message, The Fed rapidly acquiesced and decided a rate hike was inadvisable due to global market turmoil… we wonder what happens this time.

Read more …

Only question is will it be voluntary.

• Pimco Sees 7% Drop For Yuan, ‘No. 1 Risk For Global Economy This Year’ (BBG)

The offshore yuan dropped to a one-week low after China’s central bank weakened its daily fixing and Pimco. said it sees further depreciation for the currency. The People’s Bank of China lowered its reference rate by 0.33%, the most since Jan. 7, following an overnight advance in the dollar on comments from Federal Reserve officials on the possibility of an interest-rate increase as soon as April. The yuan, “by far the single biggest risk for the global economy and markets this year,” is expected to depreciate 7% against the dollar over the next year, according to a Pimco report issued Wednesday. “If the Fed raises interest rates in April, the dollar will rebound sharply and pressure the yuan weaker,” said Gao Qi at Scotiabank, who sees a June move as more likely. “We expect the yuan to depreciate modestly to 6.7 against the greenback by the end of this year” as capital leaves, the economy slows and the dollar advances.

The yuan’s share of global payments dropped to the lowest since October 2014, according to the Society for Worldwide Interbank Financial Telecommunications, with data affected by the one-week Lunar New Year holiday. China’s growth will likely decelerate as a trend, with mini-cycles of weak recovery and slowdown led by policy swings, Morgan Stanley economists Chetan Ahya and Elga Bartsch wrote in a note. China won’t devalue the yuan to boost exports, and is confident that the nation’s economy will expand by more than 6.5% annually in the next five years, Premier Li Keqiang said in a speech in Boao, Hainan province, on Thursday. Although pressures for the yuan to depreciate do exist, the nation will be able to keep the exchange rate basically stable as long as the economy stays sound, PBOC adviser Huang Yiping said on Wednesday.

Read more …

Saying it does not inspire confidence.

• Kyle Bass Is Wrong On China: Policy Adviser Li (CNBC)

Many assumptions about China held by global market players, such as thinking Beijing wants a weaker yuan or that low oil prices are caused by the mainland’s slowing growth, are simply wrong, according to a leading Chinese policy adviser. Li Daokui, director of the Center for China at Tsinghua University and former member of the People’s Bank of China (PBOC) monetary policy committee, said prominent hedge fund managers, including the likes of Kyle Bass, have misunderstood the world’s second-largest economy. For one, focusing on the currency is “the biggest mistake in reading the Chinese economy,” said Li on the sidelines of Thursday’s Boao Forum for Asia conference. “There is no need for the Chinese economy to rely on a big boost of exports….the economy is still facing a big trade surplus.”

Ever since Beijing surprised the world by unexpectedly depreciating the renminbi in August, money managers such as Kyle Bass, David Tepper and Bill Ackman have ramped up bearish bets against the yuan. Goldman Sachs predicts the dollar will be fetching 7 yuan by the end of the year, from 6.5 currently, amid expectations for looser monetary policy and the government’s desire to boost sagging exports. But exports are no longer as important as before the global financial crisis, Li explained, adding that the sector now makes up 20% of GDP, compared with 35% previously. “The renminbi is already an international currency in the region, so when it devalues, everybody devalues. The net impact is almost zero,” he added.

Indeed, fears for an Asian currency war hit fever-pitch after August’s historic devaluation. Export-oriented economies, such as neighboring South Korea, are typically flagged as the most vulnerable to a weaker renminbi as their goods appear more expensive overseas, sparking worries that other central banks would weaken their own currencies to maintain trade competitiveness. “When the Chinese economy does devaluation, the momentum of financial markets will kick in to expect more devaluation. The game has no good ending for anyone,” Li said. Li’s views echo those of Premier Li Keqiang, who said on Thursday that depreciation would not help companies be more competitive, repeating that the government would not devalue the yuan to lift exports.

Read more …

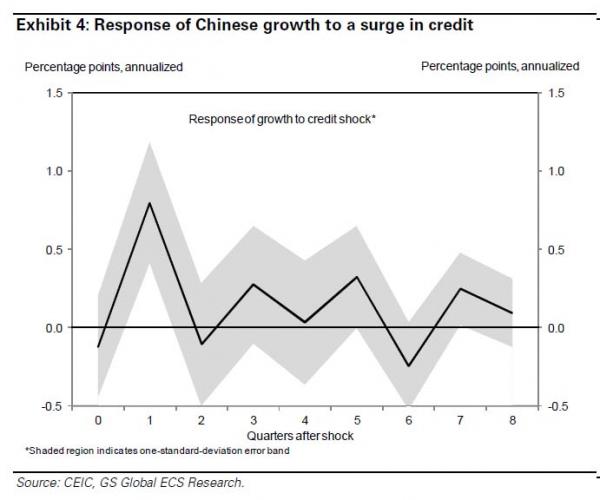
Non-financial private debt is over 200% of GDP and counting. $21.5 trillion.

• China’s Debt Bubble Threatens Global Economy (Nikkei)

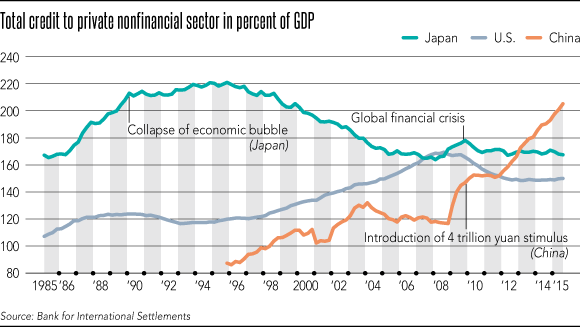
Excessive debt held by Chinese companies and households is highlighting a grave reality behind the country’s economy. In a sign that this debt is being regarded as a risk to the global economy, it became a topic of discussion at a meeting of G-20 finance ministers and central bank governors held in February. China even appears to be taking steps similar to Japan’s moves in its own post-bubble era. Total credit to the Chinese private non-financial sector stood at $21.5 trillion at the end of September 2015, accounting for 205% of the country’s GDP, according to the Bank for International Settlements. In Japan, the figure accounted for more than 200% of the nation’s GDP at the end of September 1989, when the country was in the late stage of its economic bubble.

After that bubble burst, the number shot up to 221% by the end of December 1995. Japan had fallen victim to its own excessive debt, and banks wrestled with bad loans for the next 10 years. In the U.S., the boom in subprime housing loans for low-income borrowers evolved into a global financial crisis in 2008. At the end of September that year, total credit to the U.S. private sector reached its peak, accounting for 169% of the country’s GDP. It took U.S. banks about four years to overcome their bad loan problems. And now in China, the outstanding amount of total credit to the private sector has surged 300% from the end of December 2008. After the crisis triggered by the Lehman bankruptcy in 2008, Chinese companies began borrowing money and increasing investment, thanks to the Chinese government’s introduction of economic measures worth 4 trillion yuan (around $586 billion at the time).

That stimulus has helped the country to account for half of the world’s crude steel production. Now, however, China is facing the difficult task of making production adjustments, which is putting deflationary pressure on overseas economies. At the opening session of the 12th National People’s Congress, which ended on March 16, Chinese Premier Li Keqiang announced that the country will accelerate the development of a new economy. He also stated that China will address overcapacity in steel, coal and other industries. Despite the positive stance, though, total credit to Chinese non-financial companies stood at $17.4 trillion at the end of September 2015, accounting for 80% of the total.

Read more …

Beijing has let shadow banking grow so big that regulating it is a risk to the economy.

• China Online P2P Financing Firms Face More Regulation (WSJ)

China’s online lending companies are bracing for an industry shake-up this year as competition heats up, the economy slows further and regulatory scrutiny tightens following a bevy of scandals. Operators of online lenders, a hot sector in Chinese finance just two years ago, bemoaned the tougher operating environment and the industry’s battered reputation. Speaking at a forum on Wednesday, executives cited rising credit risks and potential new government restrictions on their ability to accept public deposits. They said those firms that aren’t adaptable and lack proper risk controls will likely fail. “When these guys can’t get access to capital, what will they do?” Simon Loong of online financing platform WeLab said at the Boao Forum for Asia, a gathering of business and government leaders.

“They’ll slowly go bust,” and that in turn could rattle the financial system, Mr. Loong said without elaborating. Having made investing easy, major Chinese Internet companies are now competing to sell financial products. Here’s an introduction to some of the popular online investment platforms. Online lending boomed over the past half-decade. Peer-to-peer, or P2P, financing soared, raising capital from wealthier investors and routing it to smaller businesses and consumers often overlooked by commercial banks. P2P platforms numbered 2,595 at the end of last year, up from 880 at the start of 2014, while outstanding loans rose 14-fold to 440 billion yuan ($66.8 billion), according to data provider Wind Information. After the fast rise, however, business conditions deteriorated and some P2P platforms imploded.

Most spectacular was Ezubo Ltd., which collapsed last year, leaving investors short of $7.6 billion and causing regulators to vow to tighten supervision of the sector. While saying greater oversight is welcome, the online lenders at Wednesday’s panel said defended their business models. “The P2P word now seems to have a negative connotation now,” said Yang Fan, CEO of Iqianjin (Beijing) Information. “But P2P financing supplements the existing financial system. It can more effectively direct resources.” The executives said regulators should distinguish between shady operators and credible firms that are trying to manage the risks of loan default. “Those who were accused of illegal fundraising had just put on the hat of P2P” and weren’t genuine operators, said Zhang Shishi, co-founder of online platform Renrendai.

Read more …

But they’ll paint the rosy picture anyway.

• There’s No Sign of a China Rebound (BBG)

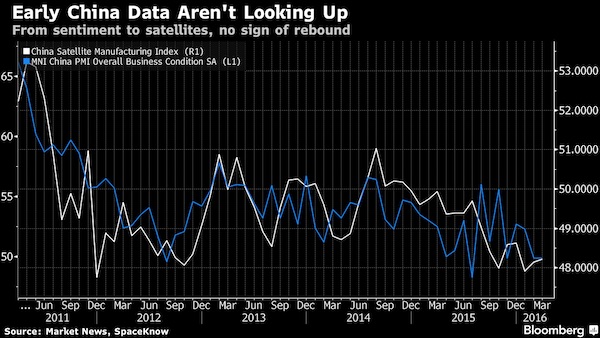
China’s monetary and fiscal stimulus have yet to spur a rebound in the world’s second-largest economy, according to the earliest private economic indicators for March. A purchasing manager’s index focused on small businesses, a gauge of corporate confidence and a new reading of the economy derived from satellite imagery all remained at levels signaling deterioration, though the pace of declines moderated. Sales manager sentiment was unchanged. The reports follow mixed official data showing investment and property sales recovered in the first two months of the year as trade plummeted and manufacturing remained weak. Meanwhile, the newest data show government reforms to slash industrial capacity and shift to a greater reliance on consumption and services haven’t been able to offset the slump.

“Confidence of companies is still slowly bottoming,” Jia Kang, director of the China Academy of New Supply-side Economics, said in a statement. “As long as the supply-side reforms can push forward, the effects will gradually show up.” That’s more unwelcome news for top officials who are gathered this week at the Boao Forum for Asia on the southern island of Hainan to discuss the challenges facing the economy and goals of the reform. Premier Li Keqiang will deliver a keynote speech Thursday and People’s Bank of China Governor Zhou Xiaochuan is scheduled to participate in a panel discussion with Commerce Minister Gao Hucheng and Foreign Minister Wang Yi.

Read more …

Obviously.

• China Exports Its Environmental Problems (BBG)

One of the best pieces of news in years is that China’s finally getting serious about cleaning up its environment. Renewable energy use is growing rapidly while coal use is declining. Air pollution targets are being tightened. Contaminated farmland is finally getting high-level attention. Yet all that good could be undermined if China simply exports its environmental problems elsewhere. A case in point is China’s campaign to protect its forests. For years, logging ran rampant as the country transformed itself into the world’s biggest buyer of timber and wood products, including everything from furniture to paper. Denuded hillsides contributed to massive floods in 1998 that forced millions to evacuate their homes. Fortunately, according to a study published last week in Science, stricter enforcement of localized logging bans has reversed the trend: Between 2000 and 2010, tree cover increased over 1.6% of Chinese territory (and declined over .38%).

This year, China plans to cut its commercial logging quota another 6.8% and will expand a ban on logging natural forests nationwide. Here’s the problem, though: As China has quieted its chainsaws, the country has become the world’s largest importer of timber; the government predicts that by 2020 it will rely on imports for 40% of its needs. And as buyers, Chinese companies aren’t terribly discerning. According to the London-based think tank Chatham House, China’s purchases of illegally harvested timber nearly doubled between 2000 and 2013, growing to more than 1.1 billion cubic feet. The damage extends across the developing world. China buys up 90% of Mozambique’s timber exports, around half of which were harvested at rates too fast to sustain the forest over the long-term.

In 2013, the World Wildlife Fund declared that illegal logging in the Russian Far East had reached “crisis proportions” after finding that oak was being logged for export to China at more than twice the authorized volumes. That same year, Myanmar tripled the volume of endangered rosewood exported to China (where it’s particularly valued for its use in furniture). At those rates, some of Myanmar’s rosewood species could be extinct by 2017. Despite a total ban enacted in 2014, rosewood exports to China surged last year to levels reportedly not seen in a decade.

Read more …

This does not bode well for TBTF banks.

• Liquidity Death Spiral Traps Credit Suisse (BBG)

Credit Suisse just got caught up in the same liquidity death spiral that has claimed a growing number of debt funds.Some of the bank’s traders increased holdings of distressed and other infrequently traded assets in recent months without telling some senior leaders, Credit Suisse CEO Tidjane Thiam said on Wednesday. This is bad on several levels. For one, it highlights some pretty poor risk management on the part of senior officers at the Swiss bank.But perhaps more important from a market standpoint, it exposes a trap in the current credit market: Traders are getting increasingly punished for trying to sell unpopular debt at the wrong time. The result has been a growing number of hedge-fund failures, increasing risk aversion by Wall Street traders and further cutbacks at big banks.

This all simply reinforces the lack of trading in less-common bonds and loans. At best, this spiral is inconvenient, especially for mutual funds and exchange-traded funds that rely on being able to sell assets to meet daily redemptions. At worst, it could set the stage for another credit seizure given the right catalyst – perhaps a sudden, unexpected corporate default or two, or the implosion of a relatively big mutual fund. To give a feeling for just how inactive parts of the market have become, consider this: About 40% of the bonds in the $1.4 trillion U.S. junk-debt market didn’t trade at all in the first two months of this year, according to data compiled from Finra’s Trace and Bloomberg. While corporate-debt trading has generally increased by volume this year, more of the activity is concentrated in a fewer number of bonds.

This has made it even harder for big banks to justify buying riskier bonds to make markets for their clients, the way they used to, because they could get stuck holding the bag. That’s what happened with Credit Suisse, apparently. The bank suffered $258 million of writedowns this year through March 11, and $495 million of losses in the fourth quarter, because of its holdings of distressed debt, leveraged loans and securitized products, including collateralized loan obligations [..] Credit Suisse is in a tough spot because it is trying to get out of its hard-to-trade assets at a bad time. It’s re-evaluating its business model under new leadership, higher capital requirements and the shadow of poor earnings. But it’s certainly not alone in feeling the pain from a brutal and unforgiving period in debt markets. JPMorgan Chase, Bank of America and Goldman Sachs are expected to report disappointing trading revenues in the first three months of the year, and Jefferies already reported its train wreck of a quarter.

Read more …

Abe’s run out of wiggle room. He can’t even turn around on a dime anymore.

• Japan’s Bond Market Is Close to Breaking Point (BBG)

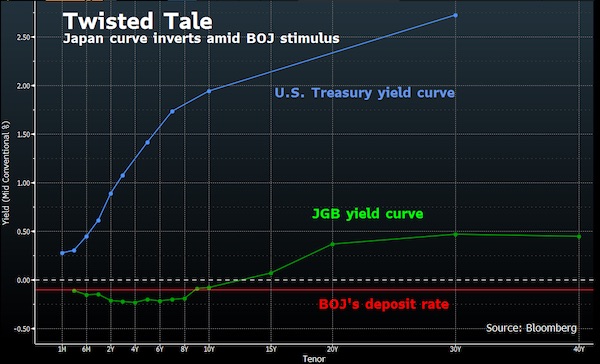
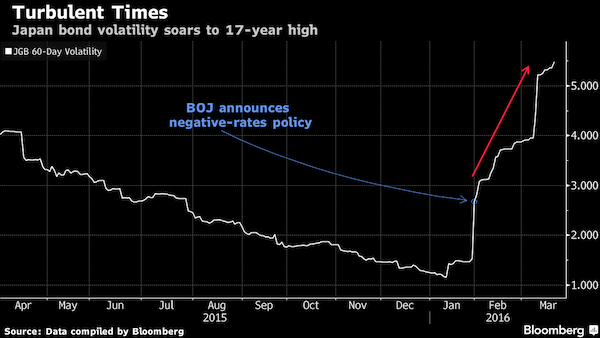
Signs of stress are multiplying in Japan’s government bond market, which is crumbling under pressure from the central bank’s unprecedented asset-purchase program and negative interest rates. BOJ Governor Haruhiko Kuroda has repeatedly said his policies are having the desired effect on markets, including suppressing JGB yields. His success is driving frenzied demand for longer-dated notes as investors avoid the negative yields offered on maturities up to 10 years. And as buyers hang on to debt offering interest returns, the BOJ is finding it harder to press on with bond purchases of as much as 12 trillion yen ($107 billion) a month, sparking sudden price swings leading to yield curve inversions that have nothing to do with economic fundamentals. “We hold a lot, and we’re not selling,” said Yoshiyuki Suzuki, the head of fixed income at Fukoku Mutual Life Insurance, which has $59 billion in assets. “We can get interest income. If we sell, there are no good alternatives.”

Yields on 40-year JGBs dipped below those on 30-year securities Tuesday, and a BOJ operation to buy long-term notes last week met the lowest investor participation on record. Bond market functionality has deteriorated, with 41% of respondents last month rating it as “low,” the highest proportion since the BOJ began the quarterly survey more than a year ago. “It wouldn’t be surprising to see some BOJ operations fail,” said Yusuke Ikawa at UBS in Tokyo. “The biggest risk of that is in superlong bonds.” A dearth of liquidity has driven a measure of bond-market fluctuations to levels unseen since 1999.

Read more …

Back on the way to $30 and beyond.

• US Oil Falls After Big Jump In Stockpiles (Reuters)

U.S. oil prices fell in Asian trading on Thursday, adding to a slump in the previous session, after stockpiles rose for the sixth week to another record, sapping the strength of a two-month rally in prices. U.S. crude futures were down 10 cents at $39.69 a barrel at 0302 GMT, trading further below the important $40 level. It closed down $1.66, or 4%, at $39.79 a barrel on Wednesday. That marked the sharpest one-day drop for the front-month contract in U.S. crude since Feb. 11. Brent crude futures were up 7 cents at $40.54 a barrel, after trading lower earlier in the session. They finished the last session down $1.32, or 3.2%, at $40.47 a barrel. Earlier this week, both benchmarks had risen by more than 50% from multi-year lows that hit in January.

The U.S. government’s Energy Information Administration (EIA) said crude stockpiles climbed by 9.4 million barrels last week – three times the 3.1 million barrels build forecast by analysts in a Reuters poll. The continued rise in stockpiles is grinding away at the gains in prices that were largely driven by plans of major producers, including Saudi Arabia and Russia, to freeze production. “OPEC production is still high and Iran is expected to continue to ramp up,” said Tony Nunan at Mitsubishi in Tokyo. “I expect crude to come back down again and test the $35 level again if we continue to get builds,” he said. The market was also supported by a release showing crude stockpiles at the Cushing, Oklahoma, delivery hub – an important data point – fell for the first time in seven weeks.

Read more …

People die from austerity.

• Osborne’s Disability Cuts Are Devastating Families (G.)

A few stabbings in SW1, a couple of careers seriously injured. Politicians and pundits are frantically trying to shrink the implications of Iain Duncan Smith’s resignation down to Westminster size. So it’s about cabinet feuds and leadership hopes, George Osborne’s snottiness and David Cameron’s way with a swearword. What the welfare secretary’s exit is not about, you understand, is a busted austerity programme that has missed nearly every goal and deadline set forward by its creators. It’s not about a benefits system in chaos – economic chaos being so much uglier a prospect than a flat-pack “Tory civil war”. And it’s certainly not about the people who actually have to use that benefits system.

People like Paul and Lisa Chapman. They won’t pop up in the coverage of the “great social reformer” – yet their story takes you to the heart of what’s wrong with our welfare system. It starts a decade ago when Paul, at only 39, started getting a tremor in his right hand. “Just a small one”, but then his eyes would swell up and his sense of smell disappeared. The doctors guessed what was wrong well before the scans picked it up, but a couple of years ago the diagnosis was confirmed: Parkinson’s disease. Incurable. Evil. Now Paul’s body won’t do what his brain tells it to. Miss any tablets and he shakes “really bad”. Even having taken them cramps still seize his neck, legs and arms. “My speech is going,” Paul begins. “I know what I want to say, but … ” Lisa picks up: “The words come out back to front.”

We were in the Chapmans’ small front room, gazing out on the same Northamptonshire town where Paul had worked for years. “I used to be the quickest postman in Irthlingborough!” He could knock off a round in two hours that would take his colleagues four. Even before taking medical retirement, he was slowing down, sometimes forgetting where he was. Now the same route would take “seven or eight hours”. Anyway, Lisa points out, he no longer has the strength to lift a letterbox. We met two days after Osborne’s announcement of the cuts to the personal independence payment (PIP). Disabilities such as Paul’s cost a lot, – in extra kit, travel and care – and PIP is meant to help. The Chapmans were worried that they’d lose out.

This, famously, was the cut too far for IDS. But the Chapmans told me another story, which underlined how this government’s welfare mess is so much bigger than just one line in a red book. Last summer they were summoned for a medical assessment, to be conducted by Capita for the Department for Work and Pensions. Capita employees apologised for not making a home visit, but said the £4.4bn multinational didn’t have sufficient staff to do one soon (Capita says it initially offered a home visit, which was rescheduled). Lisa asked the assessor if he was a GP. Yes, he said – but on the report he is described as a nurse. [..] The assessor found that Paul wasn’t as disabled as previously thought. He immediately lost £49 a week -a huge blow for the Chapmans.

In front of me, Paul remembered what he told Lisa: “The best thing we can do now is you go round your mum’s. I’ll clear off and I won’t take my tablets or my insulin. And it ll be over then. I won t be here. You go back to work and live your life as normal.” Paul: “I couldn’t face this much aggravation. I felt that bad. I’ve got something which anybody could get and I’m so used to doing 70-80 hours at work.” And now he was reduced to this. [..] A government assessment is made, a brown envelope of bad news is put in the post, and in a terraced house in a small town a sick man is driven to consider suicide.

Read more …

NATO does a lot of harm. Which makes a lot of sense given that it’s now 25 years over it’s best-by date.

• Trump Is Right – Dump NATO Now (David Stockman)

If you want to know why we have a $19 trillion national debt and a fiscal structure that will take that already staggering figure to $35 trillion and 140% of GDP within a decade, just consider the latest campaign fracas. That is, the shrieks of disbelief in response to Donald Trump’s sensible suggestion that the Europeans pay for their own defense. The fact is, NATO has been an obsolete waste for 25 years. Yet the denizens of the Imperial City cannot even seem to grasp that the 4 million Red Army is no more; and that the Soviet Empire, which enslaved 410 million souls to its economic and military service, vanished from the pages of history in December 1991. What is left is a pitiful remnant -145 million aging, Vodka-besotted Russians who subsist in what is essentially a failing third world economy.

Its larcenous oligarchy of Putin and friends appeared to live high on the hog and to spread a veneer of glitz around Moscow and St. Petersburg. But that was all based on the world’s one-time boom in oil, gas, nickel, aluminum, fertilizer, steel and other commodities and processed industrial materials. Stated differently, the Russian economy is a glorified oil patch and mining town with a GDP the equivalent of the NYC metropolitan area. And that’s its devastating Achilles Heel. The central bank driven global commodity and industrial boom is over and done. As a new cycle of epic deflation engulfs the world and further compresses commodity prices and profits, the Russian economy is going down for the count; it’s already been shrunk by nearly 10% in real terms, and the bottom is a long way down from there.

The plain fact is Russia is an economic and military weakling and is not the slightest threat to the security of the United States. None. Nichts. Nada. Nope. Its entire expenditure for national defense amounts to just $50 billion, but during the current year only $35 billion of that will actually go to the Russian Armed Forces. On an apples-to-apples basis, that’s about 3 weeks of Pentagon spending! Even given its non-existent capacity, however, there remains the matter of purported hostile intention and aggressive action. But as amplified below, there has been none. The whole demonization of Putin is based on a false narrative arising from one single event. To wit, the February 2014 coup in Kiev against Ukraine’s constitutionally elected government was organized, funded and catalyzed by the Washington/NATO apparatus. Putin took defensive action in response because this supremely stupid and illegal provocation threatened vital interests in his own backyard.

Read more …

CH4 is some 22 times as powerful as CO2.

• Methane and Warming’s Terrifying New Chemistry (McKibben)

Global warming is, in the end, not about the noisy political battles here on the planet’s surface. It actually happens in constant, silent interactions in the atmosphere, where the molecular structure of certain gases traps heat that would otherwise radiate back out to space. If you get the chemistry wrong, it doesn’t matter how many landmark climate agreements you sign or how many speeches you give. And it appears the United States may have gotten the chemistry wrong. Really wrong. There’s one greenhouse gas everyone knows about: carbon dioxide, which is what you get when you burn fossil fuels. We talk about a “price on carbon” or argue about a carbon tax; our leaders boast about modest “carbon reductions.” But in the last few weeks, CO2’s nasty little brother has gotten some serious press. Meet methane, otherwise known as CH4.

In February, Harvard researchers published an explosive paper in Geophysical Research Letters. Using satellite data and ground observations, they concluded that the nation as a whole is leaking methane in massive quantities. Between 2002 and 2014, the data showed that US methane emissions increased by more than 30%, accounting for 30 to 60% of an enormous spike in methane in the entire planet’s atmosphere. To the extent our leaders have cared about climate change, they’ve fixed on CO2. Partly as a result, coal-fired power plants have begun to close across the country. They’ve been replaced mostly with ones that burn natural gas, which is primarily composed of methane. Because burning natural gas releases significantly less carbon dioxide than burning coal, CO2 emissions have begun to trend slowly downward, allowing politicians to take a bow.

But this new Harvard data, which comes on the heels of other aerial surveys showing big methane leakage, suggests that our new natural-gas infrastructure has been bleeding methane into the atmosphere in record quantities. And molecule for molecule, this unburned methane is much, much more efficient at trapping heat than carbon dioxide. The EPA insisted this wasn’t happening, that methane was on the decline just like CO2. But it turns out, as some scientists have been insisting for years, the EPA was wrong. Really wrong. This error is the rough equivalent of the New York Stock Exchange announcing tomorrow that the Dow Jones isn’t really at 17,000: Its computer program has been making a mistake, and your index fund actually stands at 11,000.

These leaks are big enough to wipe out a large share of the gains from the Obama administration’s work on climate change—all those closed coal mines and fuel-efficient cars. In fact, it’s even possible that America’s contribution to global warming increased during the Obama years. The methane story is utterly at odds with what we’ve been telling ourselves, not to mention what we’ve been telling the rest of the planet. It undercuts the promises we made at the climate talks in Paris. It’s a disaster—and one that seems set to spread.

Read more …

This is an established pattern.

• EU Border Agency Has Less Than A Third Of Requested Police (AFP)

EU border agency Frontex on Wednesday said member states have provided less than a third of the personnel it requested to deal with the record influx of migrants. Frontex, which coordinates border patrols and collects intelligence about the bloc’s frontiers, had called on European countries Friday to provide 1,500 police and 50 readmission experts “to support Greece in returning migrants to Turkey.” Only 396 police officers and 47 re-admission experts have been offered, according to a statement released Wednesday by the Warsaw-based agency. “I am grateful to the countries who have offered (personnel)… but I urge other member states to pledge many more police officers if we want to be ready to support readmission to Turkey as agreed by the EU Council,” Frontex head Fabrice Leggeri said.

Leggeri had earlier said: “It is important to stress that Frontex can only return people once the Greek authorities have thoroughly analyzed each individual case and issued a final return decision.” The European Union struck a landmark deal with Turkey last week to stem the massive influx of migrants. The European Commission has said the implementation of the deal will require the mobilization of some 4,000 personnel, including a thousand security staff and military officers, and some 1,500 Greek and European police. Frontex spokeswoman Ewa Moncure told AFP the officers requested by the agency were part of this figure.

Read more …

“Nobody knows. Every five minutes, the orders change. So who knows. Maybe God knows. If you have any communication with God, you can ask him.”

• Key Aid Agencies Refuse Any Role In ‘Mass Expulsion’ Of Refugees (G.)

A triple blow has been dealt to the EU-Turkey migration deal after five leading aid groups refused to work with Brussels on its implementation, a Turkish diplomat ruled out changing Turkish legislation to make the deal more palatable to rights campaigners, and a senior Greek official said nobody knew how the agreement was supposed to work. The UN refugee agency said it was suspending most of its activities in refugee centres on the Greek islands because they were now being used as detention facilities for people due to be sent back to Turkey. UNHCR was later joined by Médecins Sans Frontières, the International Rescue Committee, the Norwegian Refugee Council and Save the Children. All five said they did not want to be involved in the blanket expulsion of refugees because it contravened international law.

The UNHCR spokeswoman, Melissa Fleming, said: “UNHCR is not a party to the EU-Turkey deal, nor will we be involved in returns or detention. We will continue to assist the Greek authorities to develop an adequate reception capacity.” In a separate and stronger statement, Marie Elisabeth Ingres, MSF’s head of mission in Greece, said: “We will not allow our assistance to be instrumentalised for a mass expulsion operation and we refuse to be part of a system that has no regard for the humanitarian or protection needs of asylum seekers and migrants.” Over the past year, around 1 million people have crossed the narrow straits between Turkey and Greece to try to claim asylum in Europe. In an attempt to stop this flow, the EU and Turkey reached a deal last week that would see almost all asylum seekers returned to Turkish soil.

To do this, the EU has deemed Turkey a safe country for refugees; a decision strongly contested by rights groups. Turkey is not a full signatory to the UN refugee convention, and while it has accepted more Syrian refugees than any other country, it has sometimes forcibly returned Syrian, Iraqi and Afghan asylum seekers to their countries of origin. Just hours after the EU deal was signed, Amnesty International reported that 30 Afghan refugees were sent back to Afghanistan – in a sign, Amnesty said, of what could be to come. “The ink wasn’t even dry on the EU-Turkey deal when several dozen Afghans were forced back to a country where their lives could be in danger,” said John Dalhuisen, Amnesty’s Europe and Central Asia director.

[..] The deputy mayor of Lesbos, the island where most migrants land, said no Greek official knew exactly how the deportation process would work, nor what to do with the refugees while they waited. When asked by the Guardian if he had received any concrete instructions about how refugees would be processed and returned to Turkey, Giorgos Kazanos said: “No, not yet.” “Nobody knows. Every five minutes, the orders change. So who knows. Maybe God knows. If you have any communication with God, you can ask him.”

Read more …

Mar 142016
 
 March 14, 2016  Posted by at 9:45 am Finance Tagged with: , , , , , , , , ,  2 Responses »


John M. Fox WCBS studios, 49 East 52nd Street, NYC 1948

• Marc Faber: Central Banks Will End Up Buying All Financial Assets (CNBC)
• There’s Only One Buyer Keeping the S&P 500’s Bull Market Alive (BBG)
• The Central Bankers Are Crazy & Public is Out Of Its Mind (Armstrong)
• The Effects of a Month of Negative Rates in Japan (BBG)
• Bank Of Japan Scrambles To Find Positives In Negative Rates (Reuters)
• There Is A Limit To Draghi’s Negative Interest Rate Madness (Mish)
• The European Central Bank Has Lost The Plot On Inflation (FT)
• A Thought Experiment On Budget Surpluses (Steve Keen)
• Central Banks Beat Bitcoin At Own Game With Rival Supercurrency (AEP)
• China Debt Swap Could Leave Banks In Capital Hole (Reuters)
• China’s Next Bubble? Iron Ore Surges As Speculators Weigh In (AFP)
• China’s Growth Target Is the Next Test for Its Central Bank (BBG)
• Goldman: 4 Reasons Why Yuan Will Weaken vs Dollar (CNBC)
• Subprime Flashback: Early Defaults Are a Warning Sign for Auto Sales (WSJ)
• Key Formula for Oil Executives’ Pay: Drill Baby Drill (WSJ)
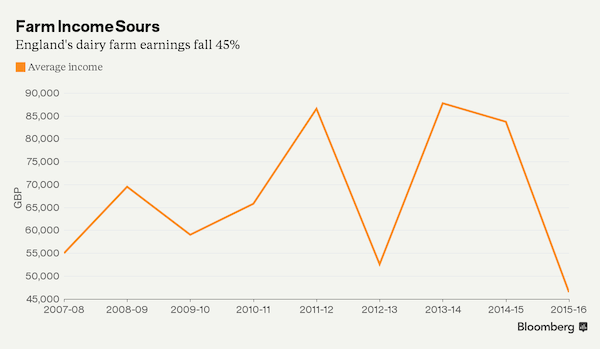
• Dairy Industry In Race To Ruin (NZH)
• Why Monsanto’s GMO Business Isn’t Growing in India (WSJ)
• February Breaks Global Temperature Records By ‘Shocking’ Amount (Guardian)
• Anti-Refugee And Pro-Refugee Parties Both Win In German Elections (Guardian)
• Bulgaria Pushes To Be Part Of EU-Turkey Refugee Deal (AFP)

Don’t know that you would call this socialism, but with the limits to negative rates, it sounds plausible.

• Marc Faber: Central Banks Will End Up Buying All Financial Assets (CNBC)

Central banks around the globe are pursuing strategies that will put all financial assets into government hands, perma-bear Marc Faber, told CNBC’s Squawk Box. He also took the opportunity to endorse Donald Trump’s bid for the U.S. presidency. Faber said central bank policies are essentially monetizing debt, particularly in Japan, where he claims the Bank of Japan is buying all the government bonds the treasury is issuing. He expects that asset buying by global central banks will only increase, even though he believes those policies aren’t working to stimulate the economy. “The central banks aren’t interested in what works, they’re interested in their own prestige. And they are so deep into it already and it didn’t work. They will increase the medicine,” said Faber, the publisher of The Gloom, Boom & Doom Report.

“Eventually, they’ll buy all the government bonds; they’ll buy all the corporate bonds, all the shares outstanding. Afterwards the housing market goes down, they’ll buy all the homes and then the government will own everything.” That’s the road to socialism, he said. “I could see a situation where at the end the government owns all the corporations and all the government bonds and then we are back into socialism, into a planning economy,” said Faber. To be sure, the Bank of Japan does not buy Japan government bonds (JGBs) directly from the treasury; it only purchases them in the open market. Since some entities, such as banks and insurers, are required to hold JGBs in their reserves, the BOJ is unlikely to acquire all of the bonds outstanding. The BOJ does, however, use its quantitative easing program to purchase select exchange traded funds (ETFs) in the open market.

The U.S. Federal Reserve began tapering its quantitative easing program in 2013 and officially ended it in late 2014. But last week, the ECB announced further easing measures, including expanding the size of its bond-buying program to 80 billion euros ($89.23 billion) worth of assets a month, to include corporate bonds. Faber expects these programs will only expand. “The governments in my view, with their agents the Federal Reserve and other central banks and with the treasury department, they will do anything not to let asset prices go down,” said Faber. “If the stock markets go down, I’m convinced all the central banks will buy stocks. All of them,” he said, noting that this is not without precedent, citing Hong Kong’s purchase of stocks during the Asian Financial Crisis in the late 1990s.

Read more …

Beware.

• There’s Only One Buyer Keeping the S&P 500’s Bull Market Alive (BBG)

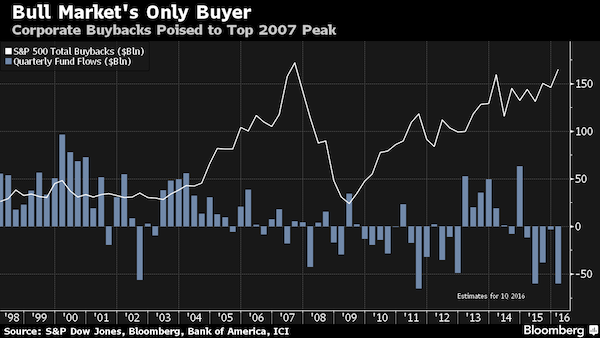
Demand for U.S. shares among companies and individuals is diverging at a rate that may be without precedent, another sign of how crucial buybacks are in propping up the bull market as it enters its eighth year. Standard & Poor’s 500 Index constituents are poised to repurchase as much as $165 billion of stock this quarter, approaching a record reached in 2007. The buying contrasts with rampant selling by clients of mutual and exchange-traded funds, who after pulling $40 billion since January are on pace for one of the biggest quarterly withdrawals ever. While past deviations haven’t spelled doom for equities, the impact has rarely been as stark as in the last two months, when American shares lurched to the worst start to a year on record as companies stepped away from the market while reporting earnings.

Those results raise another question about the sustainability of repurchases, as profits declined for a third straight quarter, the longest streak in six years. “Anytime when you’re relying solely on one thing to happen to keep the market going is a dangerous situation,” said Andrew Hopkins at Wilmington Trust.. “Over time, you come to the realization, ‘Look, these companies can’t grow. Borrowing money to buy back stocks is going to come to an end.”’

Read more …

“I asked John if he slept with Karen and got his admittal!” “I told him, Oh that’s cool, I think it’s probably about time you stopped drinking.”

• The Central Bankers Are Crazy & Public is Out Of Its Mind (Armstrong)

The central bankers are simply crazy, not evil. They are trying to steer the economy by utilizing this simpleton theory that if you make something cheaper, someone will buy it. Japanese and German cars managed to get a major foothold in the U.S. because the quality of U.S. manufacturers collapsed, thanks to unions. The socialist battle against corporations forgot something important – the ultimate decision maker is the consumer. The last American car I bought in the 1970s simply caught on fire while parked in my driveway. Another friend bought a brand-new American car and there was a terrible rattle. When they took the door panel off, there was an empty bottle of Coke inside. Cheaper does not always cut it. Gee, shall we cheer if the stock market goes down by 90%? It would be a lot cheaper. Why does the same theory not apply?

Then we have the trading public. If the central bankers have gone crazy with this whole negative interest rate theory, then the public is simply out of their minds. The euro rallied because Draghi cut rates further, extended the stimulus another year, increased the amount by another 33%, and then declared rates would stay there for years to come. And these insane traders cheer. Unbelievable! They are celebrating the public admission of Draghi that all his efforts to date have failed, so let’s do even more of the same. And they love this nonsense? Negative interest rates have become simply a tax on saving money and the stupid traders and media writers love it. The Fed tries to raise rates and they say – NO! This is a stunning combination of admission and stupidity that one would expect from a pretty but clueless girl and her drunk college boyfriend who can’t say no to any girl: “I asked John if he slept with Karen and got his admittal!” “I told him, Oh that’s cool, I think it’s probably about time you stopped drinking.”

All they see is that lower interest rates “should” stimulate but ignore the fact that they never do. They are too stupid to grasp the fact that raising taxes cannot be offset by lower interest rates. People judge everything by the bottom-line and not some crazy theory that’s just stupid. A simple correlation study by a high school student in math class would prove this theory does not correlate to the expected outcome. And we cheer this insanity confirming our own overall stupidity and one is left wondering who is crazier? I suppose it is just that central bankers are crazy and the public, as well as the media, are just out of their minds.

Read more …

Bank hits.

• The Effects of a Month of Negative Rates in Japan (BBG)

The Bank of Japan shocked markets in January with negative rates. The policy had immediate effects on financial markets, even before it actually started on February 16. Although most analysts don’t expect a change on Tuesday, they are expecting the central bank eventually to cut the rate further. Here’s a look at some effects of negative rates:

About 70% of government bonds have a yield of zero or below, meaning investors are paying to hold the debt. Pushing the yield curve down to make borrowing less costly and to encourage lending is the aim of the new policy, according to Governor Haruhiko Kuroda. However, those actions are hurting the bond market, with 69% of traders in February saying market function has declined compared with three months ago, according to a BOJ survey.

A 10-year, fixed-rate home loan carried a 0.8% rate last week, down from 1.05% before the introduction of the negative rate, according to a speech by Kuroda. Japan’s three biggest banks cut their deposit rate to a record low of 0.001%, meaning you receive 10 yen (9 cents) in income on a deposit of 1 million yen. All 11 companies running money-market funds stopped accepting new investments, citing the BOJ stimulus. They plan to return money to investors, the Nikkei newspaper reported, and money from the funds is moving to deposits, according to analysts at Deutsche Bank. Deposit returns are still positive, if negligible.

Read more …

“Bank shares fell sharply.”

• Bank Of Japan Scrambles To Find Positives In Negative Rates (Reuters)

Bank of Japan officials have been scurrying to commercial banks to explain and apologize for its surprise adoption of negative interest rates in January, while Prime Minister Shinzo Abe has distanced himself from a decision that is proving unpopular with the public. Some officials close to the premier say it could cause a rift in his once close relationship with BOJ Governor Haruhiko Kuroda, whose radical stimulus measures have so far failed to lift Japan clear of two decades of deflation and stagnation. A government press relations official said there was nothing to add beyond remarks made publicly by Chief Cabinet Secretary Yoshihide Suga that no such rift exists. With the economy shrinking again and prices flat, Abe has already announced he will set up a panel to consider fresh budget spending to provide the stimulus that monetary policy has struggled to achieve.

The controversy over the negative rates move, which unlike his previous eye-catching policy steps was not welcomed by Japan’s stock market, comes even as Kuroda is on the verge of gaining greater control of the bank’s nine-member board. Two skeptics of his stimulus program are stepping down in the coming months. The diminishing returns from his preferred modus operandi of market-shocking measures will leave him little option but to revert to the drip-feed easing he derided in his predecessor Masaaki Shirakawa if inflation fails to pick up, some analysts say. “Given the confusion caused by the January move, I don’t think the BOJ will be able to cut rates again for the time being,” said Hideo Kumano, a former BOJ official who is now chief economist at Dai-ichi Life Research Institute.

“The BOJ may instead expand asset purchases in small installments. That would be returning to the incremental approach of easing Kuroda dismissed in the past as ineffective.” Mandated by Abe to transform the risk-shy BOJ, Kuroda delighted markets and silenced skeptics within the bank by deploying a massive money-printing program, dubbed “quantitative and qualitative easing” (QQE), in April 2013. The Tokyo stock market soared and the yen tumbled, giving exporters a boost, and Japanese growth and inflation registered a pulse. He struck again in October 2014 with a big expansion of QQE, though the market boost was smaller, price rises were already moderating and the economy was taking a step back for every step forward. But the late-January rates decision failed to reverse a rise in risk-aversion that was hitting stocks and forcing up the yen, traditionally a safe haven in times of market stress. Bank shares fell sharply.

Read more …

Very clear and simple explanation of what the limits are.

• There Is A Limit To Draghi’s Negative Interest Rate Madness (Mish)

On Thursday, ECB president Mario Draghi lowered the deposit rate on money parked at the ECB to -0.4% from -0.3%. Draghi also cut the main refinancing rate by 5 basis points to 0%. How low can he go? Is there a limit? There is indeed a practical limit to negative interest rate madness, and it’s likely we have already hit that limit. Let’s investigate why. All hell would break loose if rates fell lower than -1.0%, and perhaps well before that. This has to do with Euribor. Euribor is the rate offered to prime banks on euro-denominated interbank term loans. It is based on the average interest rates of about 50 European banks that lend and borrow from each other. [..]

How does Euribor place a Limit? Millions of mortgages in Europe are based on Euribor. The vast majority of mortgage rates in Spain and Portugal are based on Euribor. A huge number in Italy are based on Euribor. The typical mortgage loan in many Eurozone countries is Euribor plus 1%age point. For those on 1-month Euribor, the interest banks collect is no longer 1%. Instead, banks collect 0.70%. Servicing fees eat into that profit. If Euribor fell below -1.0% banks would have to pay customers interest on their mortgages rather than collect interest! This has already happened in some instances, primarily related to the Swiss Franc where rates are even lower.

Low rates eat into bank profits. Such concerns place a floor on negative rates. This is why Draghi announced he is finished cutting rates. The practical limit on negative interest rates in Europe may very well be -0.4%, right where we are now. Perhaps Draghi has a buffer of another -0.20% or so, but he is reluctant to use it. If 12-month Euribor rates go any lower, it will affect bank profits on every Euribor-based mortgage loan. Loans based on 1-month and 6-month Euribor are already impacted. Draghi is unable or unwilling to go further down the interest rabbit hole, but there are still lots of rabbit hole possibilities regarding various QE measures. Corporate bonds still offer Draghi wide possibilities for more economic madness.

Read more …

“The only reason you would want to make a long-term investment at these rates is that you do not believe in the target.”

• The European Central Bank Has Lost The Plot On Inflation (FT)

Better than expected. How often have we heard these three words after a policy decision by the European Central Bank? My advice is to stop reading immediately whenever you see them. After all, what the markets expect to happen is entirely in the control of the ECB. The only thing that matters is the policy decision itself: the extent to which it can help achieve a target in this case an inflation rate of just under 2%. It may have been better than expected. But was it sufficient? The components of the decision an≠nounced on Thursday by Mario Draghi, ECB president, were: cuts in the three official interest rates; an increase in the volume of asset purchases; and more generous terms on targeted longer-term refinancing operations, a liquidity facility for banks pegged to the quantity of loans on their balance sheet.

The deposit rate, at which banks park their reserves at the central bank, is down from -0.3 to -0.4%. Mr Draghi hinted that we should not expect further cuts in that rate. And that line was the really big news of the day. He did not so much cut the rates as end the rate cuts. This is why the euro first fell then rose when investors realised this rate cut was not what it seemed. There is nothing fundamentally wrong with any of the decisions except that the ECB missed a trick. It could have widened the spread between short-term and long-term interest rates or, in financial parlance, it could have steepened the yield curve. One method would have been to make a bigger cut in the deposit rate and a smaller increase in the size of asset purchases. Since asset purchases reduce long-term rates, a small increase in purchases would have reduced them by less.

There are big problems with a flat yield curve. It is a nightmare for the banks because their business consists of turning short-term savings into long-term loans. When long rates are similar to short rates, banks find it hard to make money. They have to find other ways to generate income. Think also about the deeper meaning of a flat yield curve with all interest rates near 0%. Assume you trust Mr Draghi’s commitment to the inflation target. Would you, as a private investor, buy a 10-year corporate bond that yields 0.5%? If inflation really were to reach 2% within two or three years, you would surely make a loss. The only reason you would want to make a long-term investment at these rates is that you do not believe in the target. Long-term rates are low because people believe the ECB has lost the plot on inflation. I, too, believe this.

Read more …

Government surpluses kill economies.

• A Thought Experiment On Budget Surpluses (Steve Keen)

While conservative parties—like the USA’s Republicans, the UK’s Tories, and Australia’s Liberals,—are more emphatic on this point than their political rivals, there’s little doubt that all major political parties share the belief that the government should aim to have low government debt, to at least balance its budget, and at best to run a surplus. As the UK’s Prime Minister put it in 2013:

“Would you want a government that is not targeting a surplus in the next Parliament, that just said no, we’re going to run overdrafts all the way through the next parliament,” he told BBC political editor Nick Robinson. “I don’t think that would be responsible. So the other parties are going to have to answer this question, ‘Do you think it’s right to have a surplus?’ I do.” (David Cameron: It’s responsible to target budget surplus”, BBC October 1 2013)

So is it “right to run a surplus”? Let’s consider this via a little thought experiment. The numbers are far-fetched, but they’re chosen just to highlight the issue: Imagine an economy with an GDP of $100 per year, where the money supply is just $1—so that $100 of output each year is generated by that $1 changing hands 100 times in a year. And imagine that this country’s government has accumulated debt of $100—giving it a debt to GDP ratio of 100%—and it decides to reduce it by running a surplus that year of 1% of GDP. And imagine that it succeeds in its target. What will this country’s GDP the following year, and what will happen to the government’s debt to GDP ratio? The GDP will be zero, and the government’s debt to GDP ratio will be infinite.

Huh? The outcomes of this policy are the opposite of its intentions: a policy aimed at reducing the government’s debt to GDP ratio increased it dramatically; and what is perceived as “good economic management” actually destroys the economy. What went wrong? The target of running a surplus of 1% of GDP means that the government collects $1 more in taxes than it spends. This $1 surplus of taxation over spending takes all of the money in the economy out of circulation, leaving the population with no money at all. The physical economy is still there, but without money, no-one can buy anything, and the economy collapses. The government can pay its debt down by $1 as planned, but the GDP of the economy is now zero, so the government debt to GDP ratio has gone from $100/$100 or 100%, to $99/$0 or infinity.

As I noted, the numbers are far-fetched, but the principle is correct: a government surplus effectively destroys money. A government surplus, though it might be undertaken with the noble aim of reducing government debt, and the noble intention of helping the economy to grow, will, without countervailing forces from elsewhere in the economy, increase the government’s debt to GDP ratio, and make the economy smaller (if the rate of turnover of money—it’s so-called “velocity of circulation”—is greater than one). This little thought experiment illustrates the logical flaw in the conventional belief that running a government surplus is “good economic management”: it ignores the relationship between government spending and the money supply. Unless the public finds some other way to compensate for the effect of a government surplus on the money supply, the surplus will reduce GDP by more than it reduces government debt.

Read more …

Provocative. Let’s see how this unfolds.

• Central Banks Beat Bitcoin At Own Game With Rival Supercurrency (AEP)

Computer scientists have devised a digital crypto-currency in league with the Bank of England that could pose a devastating threat to large tranches of the financial industry, and profoundly change the management of monetary policy. The proto-currency known as RSCoin has vastly greater scope than Bitcoin, used for peer-to-peer transactions by libertarians across the world, and beyond the control of any political authority. The purpose would be turned upside down. RSCoin would be a tool of state control, allowing the central bank to keep a tight grip on the money supply and respond to crises. It would erode the exorbitant privilege of commercial banks of creating money out of thin air under a fractional reserve financial system.

“Whoever reacts too slowly to these developments is going to take it on the chin. They will lose their businesses,” said Dr George Danezis, who is working on the design at University College London. “My advice is that companies should play very close attention to what is happening, because this will not go away,” he said. Layers of middlemen in payments systems face a creeping threat across the nexus of commerce, stockbroking, currency trading or derivatives. Many risk extinction over time. “Deep in the markets there are dark pools buying and selling shares, and entities that facilitate that foreign exchange. There are Visa, Master, and PayPal. These are the sorts of guys that we are going to disrupt,” he said. University College drafted the plan after being encouraged by the Bank of England last year to come up with a radical design for a secure digital currency.

The Bank itself has an elite four-man unit grappling with the implications of crypto-currencies and blockchain technology. Central banks at first saw Bitcoin as a rogue currency and a threat to monetary order, but they are starting to glimpse ways of turning the new technology to their advantage. The findings of the University College team were delivered to the Network and Distributed System Security Symposium (NDSS) in San Diego, revealing for the first time what may be in store. Dr Danezis said a national pilot project could be up and running within eighteen months if a decision were made to launch such a scheme. The RSCoin is deemed more likely to gain to mass acceptance than Bitcoin since the ledger would remain exclusively in the hands of the central bank, with the ‘trust’ factor of state authority. It would have the incumbency benefits of an established currency behind it.

Read more …

“..any bank that swaps a corporate loan for equity of the equivalent value will need at least four times as much capital for that exposure.”

• China Debt Swap Could Leave Banks In Capital Hole (Reuters)

China’s mooted debt-for-equity swap could leave the country’s banks in a capital hole. New rules are being proposed that would allow lenders to exchange bad loans for shares. That could ease pressure on ailing companies. But it would also put pressure on bank capital ratios. In developed economies, it’s not unusual for creditors of troubled companies to accept shares in exchange for loans. In China, however, banks are restricted from investing in non-financial companies, limiting their scope for restructuring ailing borrowers. The regulations being prepared would remove that constraint, Reuters reported on March 10, potentially clearing the way for a wave of debt conversions. Some exchanges are already happening: Huarong Energy, a troubled shipbuilder, announced on March 8 it would give creditors a 60% stake in the company in return for forgiving debt worth $2.2 billion.

Yet while such swaps help overindebted Chinese companies, they are less positive for banks. True, the industry’s reported ratio of non-performing loans – which rose to 1.7% of total lending at the end of 2015 – will fall. But capital requirements will also rise as banks recognize more losses. Under China’s interpretation of international Basel rules, corporate loans typically attract a risk weighting of 100% for capital purposes. But the risk weighting for equity investments is at least 400%, and can be as high as 1250%, according to a 2013 assessment of Chinese regulations by the Bank for International Settlements. In other words, any bank that swaps a corporate loan for equity of the equivalent value will need at least four times as much capital for that exposure.

This calculation also assumes that banks have already written down troubled loans to their correct value. In reality, that’s unlikely to be the case. So-called “special mention” loans, which are wobbly but not yet officially classed as bad, accounted for a further 3.8% of overall lending at the end of last year. The true level of non-performing debt is probably much higher. The result is that any large-scale swap of debt-for-equity in the country will leave lenders short of capital. As the largest shareholder of Chinese banks, the government would have to step in. Though that might be one way to start solving China’s debt problem, other investors in the banks would feel the pain.

Read more …

Casino.

• China’s Next Bubble? Iron Ore Surges As Speculators Weigh In (AFP)

With a huge global steel glut and slowing demand in China, an enormous recent spike in the price of iron ore has left analysts scratching their heads, with some even claiming a flower show might be to blame. But observers say the extraordinary movements for one of the world’s basic bulk commodities have been fuelled by something far more prosaic than daisies and daffodils – simple speculation. The spot price for iron ore – the key material for steel – jumped 20% on the Dalian Commodity Exchange on Monday. It closed at $57.35 per tonne on Friday, up nearly 33% so far this year. But the vast majority of trades on the exchange do not reflect real-world transactions: the iron ore futures volume on Wednesday alone represented an underlying 978 million tonnes of the commodity – more than China’s entire imports last year.

“Steel prices are in a crazy phase now. Everyone’s emotions are high and pushing up prices is the norm,” Chen Bingkun at Minmetals and Jingyi Futures told AFP. “The price rise is also caused by speculation.” Only part of the real global iron ore trade passes through exchanges such as Dalian or Singapore, the other main hub for derivatives based on the commodity. Instead, the business is dominated by a small group of producers, including Anglo-Australian giants Rio Tinto and BHP Billiton, Brazil’s Vale and Fortescue Metals of Australia. They all compete to sell to steelmakers in China and elsewhere on longer-term contracts, often priced according to indices calculated by specialist trade publications, leaving limited liquidity for the spot market and heightening its volatility.

Chinese analysts and industry officials have cited a mix of factors driving the speculation that fuelled the price surge, including hopes for higher government spending on steel-hungry infrastructure after the economy grew at its slowest pace in a quarter of a century last year. The beginning of warmer weather and the end of the Lunar New Year holiday have restarted construction projects and steel production. Even an upcoming flower show in the Chinese steel hub of Tangshan has been named as a factor, with local steel companies expected to suspend output to ensure blue skies for the event – which could prompt them to step up production before the halt. China produces more steel than the rest of the world combined, and in the long term, cuts of up to 150 million tonnes in its capacity over five years could ultimately support steel prices, although their impact on iron ore costs is less clear.

Read more …

“If market participants have been worried about China since June-July 2015, they have not seen the real thing yet.”

• China’s Growth Target Is the Next Test for Its Central Bank (BBG)

China’s central bank chief oozed calm in an annual press briefing in Beijing Saturday, supported by weeks of composure in markets as investor anxiety over the nation’s currency policy eased. How long the lull lasts will depend on how policy makers manage a balancing act made tougher by a weaker-than-anticipated start to the year for the world’s No. 2 economy. After People’s Bank of China Governor Zhou Xiaochuan spoke at the country’s annual gathering of the legislature, data showed an “alarming” failure of growth to respond to recent stimulus, Bloomberg Intelligence analysts Tom Orlik and Fielding Chen concluded. The weakening momentum seen in industrial output and retail sales highlight skepticism about the Communist Party’s goal of achieving average growth of at least 6.5% in its five-year plan to 2020.

Gavekal Dragonomics calls the target “incredible.” JPMorgan says a sustainable pace is “much lower” than what officials are targeting for this year. The danger is that to meet the leadership’s objective, which for 2016 is an expansion of 6.5% to 7%, Zhou will need to loosen monetary policy faster and further. That could intensify depreciation pressures on the yuan, which has benefited in recent weeks from a drop in the dollar. Looser monetary policy, along with the expanded fiscal deficit pledged by Premier Li Keqiang’s cabinet, would quicken a buildup of debt that already amounts to almost 2.5 times GDP. “This is a risky target for the next five years as it means the continuation of super-loose monetary and fiscal policy,” said Chen Zhiwu, a finance professor at Yale University, and a former adviser to China’s State Council.

“If market participants have been worried about China since June-July 2015, they have not seen the real thing yet.” The data released Saturday showed industrial production rose 5.4% in the first two months of the year from a year before, the weakest reading since the 2009 global recession. That’s even before policy makers have much to show for a campaign to shut down excess capacity in the unproductive state-owned sector. Retail sales also slowed, while the value of homes soared versus a year ago with property sales in some mid-sized cities doubling. Fixed-asset investment exceeded economists’ estimates. Speaking hours before the data releases, Zhou, 68, warned banks about increased credit risk and rising real estate prices in the biggest cities. He sought to ease concerns over volatility in the stock and currency markets while saying meeting the five-year growth target would not require a big stretch.

Read more …

China is going to get called on its illusions.

• Goldman: 4 Reasons Why Yuan Will Weaken vs Dollar (CNBC)

The Chinese yuan, the source of much anguish in financial markets from Sao Paulo to Singapore since last summer, is enjoying some respite. The currency, also known as renminbi, is currently trading near its best levels against the dollar this year at 6.5241, having slumped to 6.5800 earlier in 2016. Efforts by Chinese policymakers to shore up confidence in the economy have helped somewhat. Capital outflows, a big factor behind the weakness in the currency and the subsequent depletion of China’s foreign exchange reserves as the People’s Bank of China intervened to prevent the yuan from falling more, also appear to have eased. But Goldman Sachs still expects the currency to weaken to 7 against the greenback by the end of the year and has listed four reasons behind its call. Here they are:

Debt overhang The sharp surge in credit in recent years has led to an accumulation of debt in the economy that will likely imply interest rates will stay lower for longer, Goldman Sachs estimates. The softer monetary policy should add to depreciation pressures on the currency.

Economic slowdown China’s once-runaway export growth has slowed (shipments fell at their fastest pace since 2009 in February) as the currency has appreciated on a trade-weighted basis over many years. Overall economic growth was 6.9% in 2015, sturdy by global standards but the slowest pace in China in 25 years. Policymakers may now have to tweak the currency to counter the slowdown in the economy, Goldman reckons.

Preference for weaker currency According to Goldman Sachs, the managed depreciation of the yuan in December and the early weeks of 2016 suggests “a degree of bias” on the part of the authorities for a weaker currency. Goldman cites a recent interview given by PBOC Governor Zhou Xiaochuan to Caixin magazine, in which Zhou suggested that the current yuan level against the dollar did not represent a “reasonable and balanced” level for the currency.

Policy divergence Goldman’s U.S. team expects the U.S. Federal Reserve to raise interest rates three times this year, while forecasting economic growth to be above the trend level. An increase in U.S. interest rates coupled with a downward trend in Chinese monetary policy will imply outflow pressures and lead to yuan weakness, Goldman says. The trend for further softness in the yuan has raised speculation on policy options for the PBOC, including a one-off devaluation in the yuan or a more steady weakness. Goldman believes the second option is more likely as a chunky one-off devaluation would raise doubts over the credibility of Chinese policymakers and draw political attention at a sensitive time.

Read more …

This is going to go so wrong.

• Subprime Flashback: Early Defaults Are a Warning Sign for Auto Sales (WSJ)

To understand how far the U.S. auto business has been reaching for new customers, consider the early performance of a bond issue called Skopos Auto Receivables Trust 2015-2. The bonds were built out of subprime auto loans and sold in November. Through February, about 12% of the underlying loans were at least 30 days past due, a third of which were more than 60 days delinquent. In another 2.6% of loans, borrowers had filed for bankruptcy or the vehicles had been repossessed. Those borrowers are at the outer fringe of the auto market. Still, the high level of missed payments for loans made so recently is a warning sign for an industry that needs every customer it can get to keep sales increasing at a record pace.

The early delinquency rates seen in the debt issue from Skopos Financial, a Dallas-based lender that specializes in loans to people with weak or no credit histories, are in line with those for several similar bond deals from other lenders around the same time. About 12% of the loans backing bonds sold in November by Exeter Finance, another Dallas-based subprime lender, were more than 30 days delinquent through February, according to the company. A spokeswoman said delinquency rates came down from the previous month. Loan payments have been slipping as well for the broader group of subprime borrowers who make up a big slice of the auto market. The 60-plus day delinquency rate among subprime car loans that have been packaged into bonds over the past five years climbed to 5.16% in February, according to Fitch Ratings, the highest level in nearly two decades.

The rate of missed payments is higher for loans made in more recent years, a reflection of more liberal credit standards and the larger number of deals from lenders serving less creditworthy customers, according to Standard & Poor’s Ratings Services. Investors are becoming concerned. Flagship Credit Acceptance, another small lender, recently had to offer higher yields than expected to sell bonds backed by subprime auto loans. Flagship declined to comment. “What’s driving record auto sales is not the economy, but record auto lending,” said Ben Weinger, who runs hedge fund 3-Sigma Value LP in New York and who has bearish bets on some auto lenders. He said demand for auto debt has led lenders to systematically loosen underwriting standards, which he predicts will result in higher loan delinquencies.

Read more …

Paid to harm your own company. Perfect.

• Key Formula for Oil Executives’ Pay: Drill Baby Drill (WSJ)

Markets have been waiting for U.S. energy producers to slash output during a period of depressed crude prices. But these companies have been paying their top executives to keep the oil flowing. Production and reserve growth are big components of the formulas that determine annual bonuses at many U.S. exploration and production companies. That meant energy executives took home tens of millions of dollars in bonuses for drilling in 2014, even though prices had begun to fall sharply in what would be the biggest oil bust in decades. The practice stems from Wall Street’s treatment of such companies’ shares as growth stocks, favoring future prospects over profitability. It has helped drive U.S. energy producers to spend more unearthing oil and gas than they make selling it, energy executives and analysts say.

It has also helped fuel the drilling boom that lifted U.S. oil and natural-gas production 76% and 31%, respectively, from 2009 through 2015, pushing down prices for both commodities. “You want to know why most of the industry outspent cash flow last year trying to grow production?” William Thomas, CEO of EOG Resources, said recently at a Houston conference. “That’s the way they’re paid.” Lately, though, some shareholders are asking companies to reduce connections between pay and production, saying such incentives don’t make sense since abundant supplies have caused commodity prices to crash. Signs that oil production may finally be easing helped push up crude prices Friday to their highest levels of the year. The International Energy Agency said in a monthly report that output in some regions was falling faster than expected and that prices may have “bottomed out.”

A separate report said the number of rigs drilling for oil and natural gas in the U.S. fell to a record low. Still, CEO pay and production are likely to remain a flash point for investors because few wells are profitable even at these higher crude prices. The persistence of U.S. production in the face of such economics has been one of the biggest puzzles in the energy market. Members of the Organization of the Petroleum Exporting Countries have increased production, betting that U.S. energy producers would curtail drilling or be forced out of business. But even as oil prices began their plunge in the second half of 2014, many companies kept drilling.

Read more …

New Zealand is so toast. Land prices are doomed, and home prices will follow a swell as corporate defaults.

• Dairy Industry In Race To Ruin (NZH)

Imagine being approached with an investment proposal that went something like this: how about you borrow almost $30 billion to invest in something that produces a commodity that swings in price by more than 50% over a two-year cycle? How about you invest in producing that commodity on the idea that demand has moved structurally higher, but pretty much ignores what other suppliers of that commodity might do? You would probably be more than a little sceptical. Yet that was the proposition New Zealand Inc essentially agreed to invest in over the past decade. This is the story of the dairy boom that has now bust, leaving dairy farmers holding debts of more than $40b and producing a commodity that is losing them $1.6b a year. Those debts are worth more than three times the income produced by that land and up from just $11.3b as recently as 2003.

The Reserve Bank has forecast that if this week’s payout cut to $3.90/kg is extended into next season, and then recovers only slowly, then 44% of those loans would be non-performing. That doesn’t necessarily mean the banks would kick 44% of farmers off their land – but it does mean the banks face profit drops. No other business leader in any other industry would borrow three times the income to build a business that produced something they couldn’t control the price of. Robert Muldoon was ridiculed and condemned for borrowing and betting big on a continued high price for oil when he invested in petro-chemical plants at Motonui, Waitara and Kapuni, and indirectly on the Clyde Dam and Tiwai Point expansion. This sort of investment decision makes no sense. Unless, of course, you weren’t actually borrowing the money purely to produce cashflow from the sale of that commodity.

It makes perfect sense if you are borrowing money to push up the value of land, the gains from which are tax-free. Most farmers would vehemently deny they are farming for tax-free capital gains, and most hold their land for multiple decades and often for multiple generations. But it is simply not credible to say that land value is irrelevant in their decision-making. It’s certainly relevant in the decision-making of the banks. Finance Minister Bill English put it best this week when he said it was time for farmers to be more like proper business investors. “This is an industry where they’ve had a focus on growing equity and growing land values for quite a long time now. It’s going to be a significant adjustment to getting back to the core business of effective farming for cash flow. “They are going to see land values drop. That is pretty much certain.”

Read more …

“Despite dozens of biotech-food-crop trials in India, the country has approved none for commercial cultivation.”

• Why Monsanto’s GMO Business Isn’t Growing in India (WSJ)

Genetically modified organisms, or GMOs, grow in an estimated 97% of India’s cotton fields and have helped India by some measures become the fiber’s top global producer. But after a decade of Monsanto’s efforts with Mahyco to win Indian-government approval for biotech food crops, seeds for plants like Mr. Char’s remain in limbo, stymied by environmentalist opposition, farmer skepticism and bureaucratic inertia. Despite dozens of biotech-food-crop trials in India, the country has approved none for commercial cultivation. “What greater case study in terms of food security than a country that will soon have more people than any other country in the world?” said Robert Fraley, Monsanto’s chief technology officer. “To see a country that has the potential and intellectual ability to be a leader in these biotech advances, to be stymied politically, I think it’s a tragedy.”

India’s Agriculture Minister, Radha Mohan Singh, said the government was waiting for India’s Supreme Court to rule in a case opposing genetically modified food crops before deciding on their commercial cultivation. Meanwhile, Monsanto’s established cotton business in India faces new threats, including new government price controls around seed genetics and an antitrust probe into pricing practices, prompting Monsanto on March 4 to warn that it could withdraw its biotech crop genes from the country. Monsanto’s experience is part of a broader backlash against genetically engineered crops from a mix of environmentalists, consumer groups and nationalism thwarting the technology’s expansion after years of growth. Biotech-crop opponents say they can damage the environment, burden poor farmers with high-price seeds and potentially harm health.

GMO proponents reject such assertions, and the U.S. Food and Drug Administration, World Health Organization and European Commission have concluded GMOs are safe to eat. Yet pushback has swept the world. More than half of European Union countries have moved to bar GMO cultivation. Russia hasn’t approved any biotech crops. China, which allows cultivation of some, isn’t expected to approve new ones soon. In the U.S., where GMO crops are widespread, some food brands are stripping GMOs from their products. The backlash has slowed global-sales growth of genetically modified seeds. Sales grew 4.7% to $21 billion in 2014, compared with 8.7% growth in 2013 and average annual growth of 21% from 2007 through 2012, according to research firm PhillipsMcDougall.

Read more …

Looks insane.

• February Breaks Global Temperature Records By ‘Shocking’ Amount (Guardian)

Global temperatures in February smashed previous monthly records by an unprecedented amount, according to Nasa data, sparking warnings of a climate emergency. The result was “a true shocker, and yet another reminder of the incessant long-term rise in global temperature resulting from human-produced greenhouse gases”, wrote Jeff Masters and Bob Henson in a blog on the Weather Underground, which analysed the data released on Saturday. It confirms preliminary analysis from earlier in March, indicating the record-breaking temperatures. The global surface temperatures across land and ocean in February were 1.35C warmer than the average temperature for the month, from the baseline period of 1951-1980.

The global record was set just one month earlier, with January already beating the average for that month by 1.15C above the average for the baseline period. Although the temperatures have been spurred on by a very large El Niño in the Pacific Ocean, the temperature smashed records set during the last large El Niño from 1998, which was at least as strong as the current one. The month did not break the record for hottest month, since that is only likely to happen during a northern hemisphere summer, when most of the world’s land mass heats up. “We are in a kind of climate emergency now,” Stefan Rahmstorf, from Germany’s Potsdam Institute of Climate Impact Research and a visiting professorial fellow at the University of New South Wales, told Fairfax Media. “This is really quite stunning … it’s completely unprecedented,” he said.

Read more …

Polarization

• Anti-Refugee And Pro-Refugee Parties Both Win In German Elections (Guardian)

The anti-refugee party, Alternative für Deutschland (AfD), has shaken up Germany’s political landscape with dramatic gains at regional elections, entering state parliament for the first time in three regions off the back of rising anger with Angela Merkel’s asylum policy. But, in a sign of the increasingly polarised nature of Germany’s political debate, pro-refugee candidates also achieved two resounding victories in the elections – the first to take place in Germany since the chancellor embarked on her flagship open-doors approach to the migration crisis. Merkel’s Christian Democrat party suffered painful defeats to more left-leaning parties in two out of three states, one of them Baden-Württemberg, a region dominated by the CDU since the end of the second world war. News weekly Der Spiegel described the result as a “black Sunday” for the conservatives.

The CDU also failed to oust the incumbent Social Democrats in Rhineland-Palatinate. But it was the breakthrough of the AfD – a party that did not exist a little more than three years ago and last year was on the verge of collapse – that was arguably most striking. In Saxony-Anhalt in the former east Germany, the party with links to the far-right Pegida movement had gained 24.4%, according to initial exit polls, thus becoming the second-biggest party behind the CDU. In both Rhineland-Palatinate and Baden-Württemberg, it appeared to have gained 12% and 15%. Germany’s rightwing upstarts appeared to have benefited from an increased voter turnout across the country. In all three states, the AfD gained most of its votes from people who had not voted before, rather than disillusioned CDU voters. In Saxony-Anhalt, as many as 40% of AfD voters were previously non-voters, while 56% of AfD voters in the state said they had opted for the party because of the refugee crisis, according to one poll.

[..]If the AfD’s strong showing reflected deep hostility to Merkel’s plan, however, other results last night told a different story. [..] The politician who won in Baden-Württemberg’s, Green state premier Winfried Kretschmann, had passionately defended the German chancellor’s open-borders stance, stating in one day that he was “praying every day” for her wellbeing. With a centrist, pro-business party programme that defied orthodox ideas of what an environmental party should stand for, the Green party in Germany’s southwest managed to come top with 30.5% in a state. Remarkably, 30% of voters who had switched from Christian Democrat to Green in the state said they had done so because of the refugee debate. “In Baden-Württemberg we have written history”, Kretschmann told reporters after the first exit polls.

Read more …

More closed borders.

• Bulgaria Pushes To Be Part Of EU-Turkey Refugee Deal (AFP)

Bulgarian Prime Minister Boyko Borisov pressed on March 12 to have his country’s borders protected as part of a proposed EU-Turkey deal aimed to stop the flow of migrants to Europe. Bulgaria has so far remained on the sidelines of the EU’s worst migration crisis since WWII after it built a 30-kilometre razor wire fence in 2014 and sent 2,000 border police to guard its 260-kilometre (160-mile) border with Turkey. But the EU member fears that it could become a major transit hub after countries along the main western Balkan migrant trail shut their borders this week. All countries on the frontline should be able to rely on support from the EU for protection of the EU’s external borders,” Borisov told visiting Austrian Interior Minister Johanna Mikl-Leitner and Austrian Defense Minister Hans Peter Doskozil in Sofia.

Borisov said he had sent a letter to that effect to EU President Donald Tusk on March 11. “Bulgaria insists that the talks between the EU and Turkey for solving the migration problem should also include Bulgaria’s land borders with Turkey and Greece as well as the Black Sea border between the EU and Turkey,” the letter read. [..] Bulgarian media reported on Saturday that Borisov was ready to block the deal if Turkey only agreed to stop the flow of migrants to the Greek islands in the Aegean Sea. Mikl-Leitner and Doskozil, who were due to visit the Bulgarian-Turkish border later on Saturday, expressed their “full support” for Borisov’s demands. “What applies to Greece also has to apply to Bulgaria,” Doskozil said. Mikl-Leitner meanwhile pledged to host a police conference on border security and human traffickers with the countries along the western Balkan migrant trail, including Germany and Greece.

Read more …

Mar 112016
 
 March 11, 2016  Posted by at 10:57 am Finance Tagged with: , , , , , , ,  Comments Off on Debt Rattle March 11 2016


Dorothea Lange American River camp, Sacramento, CA. Destitute family. 1936

• ECB’s Draghi Plays His Last Card To Stave Off Deflation (AEP)
• Draghi Can Cut Borrowing Costs, But He Can’t Make Companies Borrow (BBG)
• Japan, An Economics Lab Where Theories Go to Die (BBG)
• China May Rein in Wage Increases to Boost Economy (WSJ)
• Germany Confirmed To Be Back In Deflation (FT)
• Australians Have Amnesia On Housing And Banks (BS)
• Americans’ Home Wealth Recovers $7 Trillion as Prices Firm (BBG)
• An Economy Under Austerity Is Like A Filthy Restaurant Kitchen (Leveller)
• How a BREXIT Could Save Europe From Itself (Heath)
• Netherlands: Turkey-EU Refugee Swap Deal ‘Temporary’ (AFP)
• EU To Ease Greece Refugee Buildup Amid Doubts Over Turkey Deal (Reuters)
• 500,000 Refugees Reached Greece In Q4 2015 (Reuters)

“..“We don’t anticipate it will be necessary to reduce rates further,” he said. The throw-away comment was instantly taken to mean that -0.4pc is the absolute floor that will be permitted by Germany.”

• ECB’s Draghi Plays His Last Card To Stave Off Deflation (AEP)

The ECB has pulled out all the stops to avert a dangerous deflation-trap, launching a blast of triple stimulus despite angry criticism from Germany that it is entirely unnecessary and will do more harm than good. The markets reacted wildly to the package of measures, surging at first and then plummeting on creeping fears that the bank has exhausted its policy options and may be defenceless against a fresh shock. Mario Draghi no longer seems able to conjure confidence with his former panache. His magic has, for now, deserted him. The ECB cut the deposit rate by 10 basis points to a historic low of -0.4pc and stepped up the pace of QE from €60bn to €80bn a month. It buttressed the effect with unlimited 4-year loans to banks at near-zero cost, hoping this will limit the damaging side-effects of negative rates for banks.

“We have shown we are not short on ammunition,” insisted Mr Draghi, who was badly burned in December after seeming to over-promise and then falling short. “Mario Draghi has returned to the fray firing a blunderbuss,” said Simon Ward from Henderson Global Investors. Mr Draghi pledged to flood the financial system with fresh liquidity for as long as it takes to keep the fragile economic recovery alive and prevent a deflationary psychology taking hold, yet there was a sting in the tail. “We don’t anticipate it will be necessary to reduce rates further,” he said. The throw-away comment was instantly taken to mean that -0.4pc is the absolute floor that will be permitted by Germany. Marc Ostwald, from Monument Securities, said the ECB has bet everything on one last throw of the dice. “It’s a kitchen sink job, but at the same time Draghi is saying there is a limit to what they can do, that this is it, and there will nothing more,” he said.

The euro surged by more than two cents to $1.12 against the dollar, making it even harder for the ECB to stave off deflation. “It is not what they were hoping for,” said Simon Derrick from BNY Mellon. “What’s clear is that people are very uncomfortable with negative rates, and markets have become hypersensitive to any shift in monetary expectations,” he said. Hans Redeker, currency chief at Morgan Stanley, said foreign exchange traders had latched onto a subtle shift in ECB policy. It is moving away from efforts to force down the yield curve on sovereign debt, switching instead to a drive for lower corporate credit spreads. This is likely to draw money into eurozone assets. Negative interest rates are widely seen as a tool to force down the exchange rate, a form of “currency war” that will no longer be tolerated by the US after the G20 meeting in Shanghai. The ECB’s shift to other tools is a sign that it is backing away from this game. “We’re not in that war at all,” said Mr Draghi. [..]

Professor Richard Werner from Southampton University, the man who invented the term QE, said the ECB’s policies are likely to destroy half of Germany’s 1,500 savings and cooperative banks over the next five years. They cannot pass on the negative rates to savers so their own margins are suffering. “They are under enormous pressure from regulatory burdens already, and now they are reaching a tipping point,” he said. These banks make up 70pc of German deposits and provide 90pc of loans to small and medium firms, the Mittelstand companies that form the backbone of German industry. Prof Werner said these lenders are being punished in favour of banks that make their money from asset bubbles and speculation. “We have learned nothing from the financial crisis. The sooner there is a revolt in Germany, the better,” he said.

Read more …

How can you fight deflation when you don’t know what it is?

• Draghi Can Cut Borrowing Costs, But He Can’t Make Companies Borrow (BBG)

Mario Draghi’s plans to buy corporate bonds will cut financing costs for European companies, if history is any guide. Getting the firms to actually borrow and spend money will be harder. Corporations already have hefty incentives to sell debt, with average yields on investment-grade bonds in the region below 2 percent for a second year. But they have little appetite to raise money to invest in new factories and equipment, because the economic outlook is so weak. “If you don’t need the funds then why should you raise them?” said Ivo Kok, the treasurer of Alliander NV, an investment-grade Dutch gas and electricity distribution company. “It is more of a risk to have an awful lot of cash around that you’re not putting to work.”

The ECB said on Thursday that it will start buying investment-grade corporate bonds sometime toward the end of the second quarter, as part of a broader bond purchase program. To help stave off deflation and stimulate growth, it plans to buy €80 billion of debt a month, also including eurozone government bonds, asset-backed securities, and covered notes. The central bank is also taking steps to provide cheap funding to banks through a program known as “targeted longer-term refinancing operations.” That financing, which essentially pays banks to borrow, is meant to encourage more lending. The ECB’s efforts are already looking like they may cut companies’ borrowing costs. A measure of investment-grade corporate credit risk, the Markit iTraxx Europe Index, dropped to its lowest point in two months.

Banks are seen benefiting too – notes issued by Italian lenders Intesa Sanpaolo and UniCredit, the biggest users of the TLTRO facility, were among the gainers. But even before the ECB’s moves, companies had access to cheap credit, said Gary Herbert at Brandywine Global Investment Management. “Is there a need to lever up a balance sheet to grow a business when underlying customers aren’t demanding more of what you make?” Herbert said.

Read more …

“Japan has a number of unusual traits that make it a very good proving ground for macro models, including a shrinking population, inefficient labor markets, an economy out of sync with the rest of the world and a government willing to engage in dramatic economic experiments.”

• Japan, An Economics Lab Where Theories Go to Die (BBG)

The main thing you have to understand about macroeconomic theory – both of the type used by academics and the type employed by private-sector forecasters – is that it doesn’t really work. Events are constantly taking macro people by surprise, counterexamples to pet theories are a dime a dozen, and the rare theory that can be tested against available data is usually rejected outright. In macroeconomics, your choice of model is usually between “awful” and “very slightly less awful.”

Most macroeconomic theories can be easily tested: all we have to do is take a look at Japan. Japan has a number of unusual traits that make it a very good proving ground for macro models, including a shrinking population, inefficient labor markets, an economy out of sync with the rest of the world and a government willing to engage in dramatic economic experiments. Once we start examining theories used to explain the U.S. economy, and apply them to Japan, we find that these theories usually fail.

For example, take the theory of loanable funds, which is taught in most undergraduate introductory econ classes. According to this model, when the government borrows a lot of money, it pushes up interest rates. That makes a certain logical sense, since interest rates are the price of borrowing, and an increase in demand for credit should push up the price. But even as Japanese government deficits and borrowing have exploded since 1990, interest rates have done nothing but fall as the chart below shows:

Read more …

Doesn’t sound like a good sign.

• China May Rein in Wage Increases to Boost Economy (WSJ)

China’s Communist leaders are trying to rein in wage increases, favoring business interests at the expense of increasingly discontented workers as growth sags. China’s labor ministry recently urged “steady and cautious control” over minimum wages and proposed a formula change that would slow increases, according to people briefed on the plan. The southern province of Guangdong, a manufacturing hub, last month announced a two-year freeze on minimum wages. During annual legislative meetings in Beijing this past week, Finance Minister Lou Jiwei criticized China’s labor laws as being overly protective of workers, saying they fuel wage inflation and discourage employers from creating more jobs. Despite a rise in labor strife, Premier Li Keqiang made no direct mention of labor relations in his annual speech, a departure from previous years.

Over much of the past decade, Chinese wages grew faster than the economy, lifting workers’ living standards but also diminishing China’s competitive edge. The increases helped ensure workers shared in economic prosperity. Now, as growth slows, leaders are signaling wages and labor rights—already poorly enforced—might need to take a back seat. “China, as a developing country, has adopted labor laws of a European welfare state,” said Yang Keng, chairman of real-estate firm Sichuan BRC Group and a political adviser to the government. “The motives are good but businesses have been hurt.” China is trying to avoid painful job losses by keeping growth at a robust 6.5% over the next five years. Leaders already plan to lay off 1.8 million steel and coal workers and aren’t eager to drive up unrest with deeper cuts.

Instead, they are trying to free up funds for businesses to invest, including by tackling workers’ wages and welfare benefits. “The government is moving in a broadly pro-capital direction,” said Eli Friedman, an assistant professor at Cornell University who studies labor relations in China. “This would be a disaster for Chinese workers, and would certainly undermine efforts at economic rebalancing.”

Read more …

Schäuble rules.

• Germany Confirmed To Be Back In Deflation (FT)

Germany’s inflation rate for February came in unchanged from its preliminary reading, confirming Germany has fallen back into deflation. Consumer prices were confirmed to have fallen 0.2% year-on-year in February on an EU-harmonised basis, down from a 0.4% rise in January. Economists had forecast the figure to remain the same. On a month-on-month basis, consumer prices rose by 0.4%. The news will give a further headache to the ECB, which yesterday announced a package of additional monetary easing measures partly designed to ward off deflationary pressures from the single currency zone.

Read more …

Scary numbers.

• Australians Have Amnesia On Housing And Banks (BS)

Australian investors are far too over-exposed to housing and should not be doubling down on that risky exposure by owning shares in the banks as well, according to Lazard Asset Management. Lazard portfolio manager Philipp Hofflin says his greatest concern is the risk posed by the housing market, which he argues is fundamentally overvalued as an asset class. “We are concerned about it because we think the price is fundamentally wrong,” Hofflin told a conference of investment advisers in Melbourne. “It is the biggest issue that faces Australia and the largest asset class by far. There are clearly signs of speculative activity,” he said, citing high levels of interest-only loans and the majority of first homebuyers choosing investment properties rather than owner-occupied.

The media has been awash with reports in recent weeks about the risks of the housing bubble bursting, but Hofflin says it is impossible to predict the timing of such an event because you could only identify the catalysts in retrospect. But if capital-city housing were a fully equity-funded stock (with no debt), it would be trading at a price to earnings ratio of 65, compared with a long-term stock average of 16 to 17. Units are trading about 49 times earnings. The net yield on an Australian home of 2.2% is well below the comparable yield on a US home of 6.2%; on a unit it is 2.9% compared with 5.7% in the US. He pointed to parallels with Australia’s two previous debt-fuelled housing booms in the 1880s and 1920s, both of which were followed by extended economic depressions.

“We’ve been here before. We got here because we suffer from collective intergenerational amnesia,” Hofflin argues. Australians’ over-exposure to housing is evident in the middle 60% of income households, where housing accounts for 90% of their net worth. At the top of the US housing bubble in 2006, that figure was 36% of the household balance sheet and it fell to 28% in the recession. “Often in Australia, the only other thing they own is bank shares, who lend on that property, and hybrids, and term deposits with those same banks. It is one very large, concentrated risk,” Hofflin says. Of investors who directly own shares, over 60% are held in the banks while 80% are in financials.

Read more …

Just as scary.

• Americans’ Home Wealth Recovers $7 Trillion as Prices Firm (BBG)

In March 2014, Steven and Bernadette Doherty paid $183,000 for a two-bedroom home in Charlotte, North Carolina, $6,000 more than its appraised value. Today, similar houses in the neighborhood are being priced at $300,000 or more. “We bought at the right time,” said Bernadette, a retired Wells Fargo information technology worker. “In retrospect, we were lucky as prices have gone up so much more.” Home-price appreciation is a welcome development for households whose nest eggs were shattered by the residential real-estate bust that began a decade ago. The 2006-2009 housing slump reduced wealth by $7 trillion. Since then, the value of homeowners’ equity in real estate has more than doubled from a low in the first quarter of 2009, a Federal Reserve report today showed. What’s more, housing wealth is poised to reach a new record as early as the second quarter, say economists at the St. Louis Fed and Pantheon Macroeconomics.

Improving property values are allowing homeowners to shake off recent stock-market volatility and keep spending. From the end of 2013 through last year’s fourth quarter, home equity climbed 22% compared with a 11% gain in the Standard & Poor’s 500 Index. The stock index has declined 3% this year. “The increase in housing wealth is a kind of stealth offset to falling stock prices,” said Ian Shepherdson, chief economist at Pantheon Macroeconomics, who predicts record home equity values next quarter. “Home ownership is much wider than stock ownership. The consumption effect from a given rise in holdings has been bigger for homes.” Some cities, including Charlotte, are already seeing prices at all-time highs. Home values in Dallas, Denver, and San Francisco and Portland, Oregon, all hit records in December, while they’re down less than 1% in Boston from an August peak, according to S&P/Case-Shiller indexes. About 38% of 87 U.S. metropolitan areas were in record territory last year, data tracker RealtyTrac figures show.

Read more …

A year old, but an excellent explanation of austerity.

• An Economy Under Austerity Is Like A Filthy Restaurant Kitchen (Leveller)

The austerity fetishists trying to do to Europe and America what the IMF and World Bank did to its third world victims in the eighties, on behalf of their masters in Wall Street, often compare an economy to a household. This household, they tell us, has lived beyond its means, by maxing out its credit card and getting into debt. What do you do when you get into debt? You pay it off! Stop shopping at Whole Foods and go to Walmart instead. Take the shiny gadgets you don’t need to a pawn shop for a bit of extra cash. Work harder. Even ignoring the fact that the increased indebtedness of households these days is part of a structural problem rather than a moral one, the basis for the ‘economy is like an indebted household’ analogy has no relation whatsoever to economics. They would have you believe that austerity is a practical measure, where if you sell off your wasteful trinkets you will become solvent once again – all premised on the iron moral principle that Debts Must Be Paid.

This is a load of bollocks. We want to propose instead that austerity is like a restaurant kitchen, not because we think the analogy is perfect, but because every time a Keynesian economist tries to knock down the household analogy they drone on with “households can’t print money”. Which is hardly a catchy argument to throw at the right wing pub bore. It is possible to have a little more imagination than that. Here is the Leveller’s austerity kitchen analogy, for your pub argument utility belt. Use it carefully. The restaurant has got itself into debt. We don’t really care how, suffice to say the decisions that led to it were made by the owners and not the staff. The owners like to say “we” are in debt to include the staff, which is interesting, given that when the restaurant was making a tidy profit the previous year there was no “we” when it came to giving themselves a fat pay rise. But now, for whatever stupid structural reason you’d care to pick, they are in debt.

Even if there isn’t some troll sat there insisting that the ovens and hobs don’t create value through being there – let’s call her Libby Terrian – consider austerity as being like the restaurant saying, “well there is no immediate value being created by the dishwasher, and we already have a porter and a sink, so let’s sell the dishwasher”. As in the machine, not the porter. So they flog the dishwasher and get some liquidity, and use it to pay off some of their interest-ridden debt. Sadly the value of the dishwasher is not equal to the value of the debt, not even close, and so the debt starts to mount once more; all they’ve done is bought a little time. At the same time, the poor kitchen porter is having to work much harder to keep everything clean – naturally they can’t afford to give him a pay rise to reflect this increase in workload – but he just can’t keep up, because the value of his labour has been reduced by taking the dishwasher out of the microeconomy.

Meanwhile Libby Terrian thinks it would be way better if the chefs just cooked the food at home and brought it in because then the restaurant wouldn’t have to spend money on oven maintenance every few months, but thankfully nobody listens to Libby, because she is mental. Further problems mount from this, of course. The porter’s increased workload with less ability to do it properly leads to an unfortunate situation several nights a week whereby he can’t produce clean plates quickly enough for the chefs, who end up having to wash plates by themselves. Not only does this affect the quality of their dishes, it also affects general hygiene in the restaurant. The restaurant begins to get a reputation for being dirty.

Read more …

Mostly what I said not long ago.

• How a BREXIT Could Save Europe From Itself (Heath)

It is those who love Europe, its diversity, its history and its humanity who should be the most enthusiastic about Brexit. A paradox? Not at all. The European Union, as currently constituted, has run out of road. It is doomed to fail, sooner or later, with catastrophic consequences for our part of the world, and the only way forward is for one major country to break ranks and show that there can be a better alternative consistent with Europe’s core enlightenment values. It would be far better if we, rather than a more socialist or nationalistic country, were the first to break the mould: Britain would have the opportunity to show that free trade, an open, self-governing society and a liberal approach could ensure the peace and prosperity at the heart of the European dream. Others would soon join us. If we vote to stay, we will lose the moral authority to speak out, and other, less benign, inward-looking, illiberal approaches may triumph instead.

The eurozone is broken, and another, far greater economic crisis inevitable. The next trigger could be a fiscal meltdown in Italy, or another banking collapse, or a political implosion in Spain or France, or another global recession. Nobody can be sure what the proximate cause will be – but there will be one, and the fallout will be turmoil of a far greater magnitude than anything we saw in Greece. At the same time, the tensions fuelled by the migration crisis will grow relentlessly, especially if hundreds of thousands or even millions of people are settled across the continent over the next few years. Many in the Remain camp agree that the eurozone requires drastic surgery, but their solution is naive. They believe that even more integration – a pan-eurozone welfare state, greater transfers between countries, central powers over fiscal policy – would help cancel out the currency’s inherent defects.

I doubt that this would actually work in purely economic terms, but even if it did, it is delusional to believe that such a model can be politically sustainable. Democracy, the term, is derived from the ancient Greek: it denotes a system whereby the people (dêmos) are in power or in which they rule (krátos). One cannot, by definition, have a genuine democracy in the absence of a people; and there is no such thing as a European demos. The French are a people; the Swiss are a people, even though they speak multiple languages; the Americans are a people, even though Democrats and Republicans hate each other. But while Europeans have much in common, they are not a people. Danes don’t know or care about Portuguese politics; the Spanish have no knowledge or interest in Lithuanian issues.

One could hold pan-European elections, of course, with voters picking multi-national slates of candidates; but, then, one could also ask every person on the planet to vote for a world president. Such initiatives would ape democratic procedures, but would be a sham. They would be Orwellian takedowns of genuine democracy, not extensions of it. There would be no relationship or understanding between ruler and citizen, zero genuine popular control, nil real accountability; coalitions of big countries would impose their will on smaller nations, and elites would run riot. We would be back to imperial politics, albeit in a modernised form.

Read more …

Did they tell the Turks this?

• Netherlands: Turkey-EU Refugee Swap Deal ‘Temporary’ (AFP)

A proposed EU-Turkey deal to swap Syrian refugees one-for-one will be only “temporary” and a longer-term resettlement arrangement will be necessary, the Netherlands warned Thursday. European Union interior ministers meeting in Brussels were debating a proposal made by Ankara at a leaders’ summit on Monday for a wide-ranging deal to curb the migration crisis. Under the deal the EU would resettle one Syrian refugee directly from camps in Turkey, in exchange for every Syrian that Turkey takes from the overstretched Greek islands, a scheme both sides have hailed as “game-changing”.

But Dutch migration minister Klaas Dijkhoff, whose country holds the six-month rotating presidency of the 28-nation EU, said that it was “not a permanent mechanism.” “I think the one-on-one readmission and resettlement, it’s temporary,” Dijkhoff told reporters as he arrived for the meeting. “I think when you have the one-on-one scheme, we will see over time that it won’t pay off to cross the sea in an illegal and very dangerous fashion. So that flow will stop,” he said. “And then we will have to talk with Turkey about a more permanent resettlement scheme in a sense of burden sharing.”

Read more …

“It will be very difficult to arrive at something legally sound and implementable before the summit..”

• EU To Ease Greece Refugee Buildup Amid Doubts Over Turkey Deal (Reuters)

The European Union aims to rehouse thousands of asylum-seekers from Greece in the coming months, officials said on Thursday as EU ministers wrestled with concerns about the legality of a new plan to force migrants back to Turkey. Dimitris Avramopoulos, the member of the executive European Commission who handles migration, told reporters at a meeting of national interior ministers that at least 6,000 people a month should be relocated to other member states under a scheme which has moved only about 900 hundred people so far. Avramopoulos noted a recent acceleration in relocations under the system which has divided EU governments as some refuse to take in refugees, most of whom are from Syria and Iraq, though he acknowledged the target was ambitious.

Some 35,000 people have been stranded in Greece since Austria and states on the route to Germany began closing borders, barring access to migrants hoping to follow more than a million who reached northern Europe last year. EU officials said that blockage appeared to have made more asylum seekers ask for relocation rather than try to make their own way northward. Chancellor Angela Merkel, under electoral pressure at home after opening Germany’s doors to a million Syrians, has pressed EU partners to share the load. But few are keen and critics say many of those rehoused elsewhere will head for Germany anyway. On Monday, Merkel pushed EU leaders to pencil a surprise deal she brokered with Ankara to halt the flow to Greece by returning to Turkey anyone arriving on the Greeks islands.

But legal details are still being worked out for an EU summit next week and many governments are still sceptical of the scheme. The top United Nations human rights official said it could mean illegal “collective and arbitrary expulsions”. EU ministers also voiced unease at the price of Ankara’s cooperation, notably an accelerated process to ease visa rules for Turks by June and revive negotiations on Turkey’s distant EU membership hopes. “I ask myself if the EU is throwing its values overboard,” said Austrian Interior Minister Johanna Mikl-Leitner, whose government has led a push to seal off Greece from the north as an alternative to relying on Turkey to stop migrants leaving.

She noted the seizure of an opposition newspaper in Turkey three days before it presented EU leaders with the draft deal, under which Europeans will take one Syrian direct from Turkey for every compatriot who is detained and sent back from Greece. Human rights concerns also pose problems for EU lawyers trying to tie up the package by the March 17-18 summit, notably because to despatch people at speed back to Turkey relies on an assessment that Turkey is a “safe” country for them to be in. An EU definition of such a state includes a reference to the Geneva Convention on refugees, to which Turkey does not fully comply, leaving legal experts in Brussels hunting a solution. “It will be very difficult to arrive at something legally sound and implementable before the summit,” an EU official said.

Read more …

That EU ‘ease’ above talks about resettling 6,000 per month.

• 500,000 Refugees Reached Greece In Q4 2015 (Reuters)

Nearly half a million irregular migrants arrived in Greece in the last three months of 2015, most of whom then moved north through the Balkans, data from EU border agency Frontex showed on Thursday. Frontex, which collates data on the number of irregular border crossings, recorded 484,000 such incidents on the Eastern Mediterranean route from Turkey to Greece between October and December and 466,000 on the Western Balkan route, notably people re-entering the European Union at the Croatian border from non-EU Serbia.

That took the total number of illegal EU border crossings, not using regular crossing points, to 978,300 in the quarter, a record since Frontex began collating such data in 2007. Of those arriving in Greece, mostly on islands off the Turkish coast, 46% said they were Syrian and 28% Afghan, Frontex said. It recorded a drop in arrivals in Italy from Libya but noted a sharp increase in arrivals in Spain from Morocco, albeit at a low level. There were 2,800 illegal crossings in the fourth quarter on the Western Mediterranean route, it said, a record for that season and double that in the same period of 2014.

Read more …

Feb 272016
 
 February 27, 2016  Posted by at 1:56 pm Finance Tagged with: , , , , , , , ,  8 Responses »


Theodor Horydczak Lincoln Memorial 1925

There has been quite a bit of talk lately over the need for a new Plaza Accord, something several parties saw happening during this weekend’s G20 summit in Shanghai -hence the term ‘Shanghai Accord’-. (On September 22, 1985 at the Plaza Hotel in New York City, France, West Germany, Japan, the US, and the UK signed an accord to depreciate the US dollar vs the Japanese yen and German Deutschmark by intervening in currency markets).

Unless all the G20 finance ministers and central bankers gathered in China are in close and secretive cahoots, though, it doesn’t look like it is going to happen. And that seems to both make sense and not. What those advocating such an accord are calling for is a -large- devaluation of the Chinese yuan (RMB) vs the USD and yen -perhaps even the euro-, but the climate simply doesn’t look ripe for it.

Still, the problem is, if they don’t do it, they open the doors to a whole lot more volatility, unpredictability and losses in the markets. All things that those markets do not want. Because, like it or not, the yuan is overvalued, China’s fabricated trade numbers are increasingly under scrutiny, and a large devaluation could settle things at least for a while.

However, Beijing looks too full of hubris and pride -and inclusion in the IMF basket of currencies is an issue too- to do what seems natural. Lest we forget, no matter how much China seeks to obfuscate the numbers, everybody already knows that numbers like producer prices and exports, and most importantly imports, have seen steep falls, and for a long time too.

China’s oil tanks look as close to overflowing as the American ones, and without those oil imports, who knows who bad import numbers would have looked? So from a Chinese point of view, a cheaper yuan would mean much cheaper Chinese exports for global buyers, whereas the negative effect of more expensive imports would be relatively small.

But there’s the other side of the equation as well: other nations’ exports would see a potentially enormous effect of cheaper Chinese imports on their domestic manufacturing base. For countries like Germany, the US and Japan, any such devaluation may therefore be an absolute non-starter at this point.

That, however, leaves the fact that there is that large imbalance in currency (FX) markets, and that those markets, along with hedge funders like Kyle Bass, have already made it known that they will seek to exploit that imbalance to go after the yuan for profit. That finance ministers seem unable to ‘soften’ the imbalance will only make them more determined. It’s like the central bankers and finance ministers make their case for them.

A few news snippets from the past week. First, Tyler Durden’s take on BofA’s Michael Hartnett a week ago, who’s quite clear on why there should be a devaluation.

BofA: ‘Shanghai Accord’, Massive Central Bank Intervention Imminent

Any time the relative performance of global financials to US Treasuries has stumbled as far as it has, as shown in the chart below, it has meant one thing – a major central bank intervention was imminent. At least that’s the interpretation of BofA’s Michael Hartnett, who shows that in order to provide the kick for the bounce in this all too important “deflationary leading indicator”, central banks engaged in major unorthodox easing episodes, whether QE1-3, or the ECB’s QE.

Why intervene now? Here are the problems according to Hartnett:
• Problem 1: US economy in “bad Goldilocks”, i.e. US economy not hot/strong enough to lift global GDP & EPS; but not cold/bad enough to induce global coordinated response
• Problem 2: global policy-maker rhetoric in recent days shows “coordinated innocence” not stimulus, all blaming global economy for weak domestic economies (“Overseas factors are to blame”…Japan PM Abe; “drag on U.S. economy from greater-than-expected-slowdown in China & other EM economies“…FOMC minutes; “increasing concerns about the prospects for the global economy”…ECB Draghi; “the change in China’s growth rate can be attributed in part to weak performance of the global economy”…PBoC)

Problem 2 is static, meant for media propaganda and jawboning; it can easily be removed once the global economy takes the next leg lower. Which incidentally would also resolve the gating factor of Problem 1 – as we have said for months, the Fed and its central bank peers need the political cover to launch more stimulus.

And in a reflexive world, where the “economy is the market”, this means just one thing – a big leg lower in stocks is the necessary and sufficient condition to once again push stocks higher, as policy failure is internalized, and global risk reprises from square 1. This is Bank of America’s summary, warning that unless a major policy intervention is enacted, the market will then sell off to the next support level, below the 1,812 which has proven so stable since August. Stabilization of “4C’s” (China, Commodities, Credit, Consumer) allowed SPX 1800 to hold/bounce to 1950-2000; weak policy stimulus in coming weeks could end rally/risk fresh declines to induce growth-boosting policy accord.

Next up, Bloomberg:

Barclays Says Sharp Yuan Devaluation Needed

A sharp, one-off devaluation of the yuan is among options China’s central bank might consider to stem capital outflows and shift market psychology to appreciation from depreciation, according to Barclays. The risk of such a move, which Barclays says would need to be in the region of 25% to alter perceptions, is rising as China’s foreign-exchange reserves plunge, analysts Ajay Rajadhyaksha and Jian Chang wrote in a report. Based on the current pace of decline in those holdings, there’s a six- to 12-month window before they drop to uncomfortable levels and measures such as capital controls or monetary tightening may also have to be looked at to curb the exodus of money, they said. All those options carry elements of danger.

Another rapid yuan depreciation could spook investors just as concern about the state of the global economy is growing and other central banks would likely follow, countering the beneficial impact on Chinese exports, the analysts said. Strict capital controls won’t work in an export-driven economy, while a move to policy tightening could slow growth and cause credit defaults, they said. “A devaluation of this magnitude seems impossible to ‘sell’ to the rest of the world,” according to the analysts at Barclays, the world’s third-biggest currency trader.

And then this from the FT, which confirms the huge question mark over the option:

Scepticism Rife Over G20 Move To Calm FX

Scepticism is rife that the G20 gathering of finance ministers will agree to co-ordinate currency policy but there is some belief it could provide a short-term boost to risk appetite. Japan has led calls for the two-day meeting in Shanghai to bring calmness to an unstable market with a broad-based FX strategy, seen by some market commentators as a reprise of the 1985 Plaza Accord that succeeded in weakening a rampant dollar. But those hopes have been knocked back by China and the US, and market expectations have been subdued in the run-up to the G20 meeting that ends with a communique on Saturday. “A grand solution like the Plaza Accord feels far-fetched”, said Peter Rosenstrich at the online bank Swissquote.

Then, the South China Morning Post a few days back on how Beijing apparently seeks to hide capital outflows data.

Sensitive Financial Data ‘Missing’ From PBOC Report On Capital Outflows

Sensitive data is missing from a regular Chinese central bank report amid concerns about capital outflow as the economy slows and the yuan weakens. Financial analysts say the sudden lack of clear information makes it hard for markets to assess the scale of capital flows out of China as well as the central bank s foreign exchange operations in the banking system. Figures on the “position for forex purchase” are regularly published in the People’s Bank of China’s monthly report on the “Sources and Uses of Credit Funds of Financial Institutions”. The December reading in foreign currencies was US$250 billion. But the data was missing in the central bank’s latest report. It seemed the information had been merged into the “other items” category, whose January figure was US$243.9 billion -a surge from US$20.4 billion the previous month.

Combine that with new world trade numbers as reported by the FT, and you can’t help but wonder 1) what is going on with trade (though this is in USD, and that tweeks things somewhat), and 2) how much the yuan would have to drop to make up for the difference.

World Trade Falls 13.8% In Dollar Terms (FT)

Weaker demand from emerging markets made 2015 the worst year for world trade since the aftermath of the global financial crisis, highlighting rising fears about the health of the global economy. The value of goods that crossed international borders last year fell 13.8% in dollar terms — the first contraction since 2009 — according to the Netherlands Bureau of Economic Policy Analysis’s World Trade Monitor. Much of the slump was due to a slowdown in China and other emerging economies. The new data released on Thursday represent the first snapshot of global trade for 2015.

Next, Christopher Balding, an associate professor at Peking University HSBC Business School, who does them all one better by questioning even what may be the most widely accepted idea about the Chinese economy.

China Does Not Have a Trade Surplus

Whereas Chinese Customs reports $1.68 trillion and SAFE report $1.57 in goods imports into China, banks report paying $2.55 trillion for imports. In other words, funds paid for imported goods and services was $870-980 billion or 52-62% higher than official Customs and SAFE trade data. This level of discrepancy is extreme in both absolute and relative terms and cannot simply be called a rounding error but is nothing less than systemic fraud. If we adjust the official trade in goods and services balance to reflect cash flows rather than official headline trade data as reported by both Customs and SAFE, the differences are even worse.

According to official Customs and SAFE data, China ran a goods trade surplus of $593 or $576 billion but according to bank payment and receipt data, China ran a goods trade surplus of only $128 billion. If we include service trade, the picture worsens considerably. China via SAFE trade data reports a $207 billion trade deficit in services trade. Payment data reported via SAFE actually reports about $42 billion smaller deficit of $165 billion. In other words, the supposed trade surplus of $600 billion has become a trade in goods and services deficit of $36 billion. Expand to the current, through a significant primary income deficit, and the total current account deficit is now $124 billion.

That doesn’t leave much in one piece of what we’ve been told about the China growth miracle. No wonder the PBoC is ‘airbrushing’, as the NYT says. The problem with this is that analysts are already scrutinizing the data up -very- close, and they’re not going to be easily fooled anymore. For instance, in the case of the missing capital outflows data mentioned earlier, analysts say they can find them out through other channels anyway, and they will be that much more eager to do just that. Trying to bully them is senseless.

As China’s Economic Picture Turns Uglier, Beijing Applies Airbrush

This month, Chinese banking officials omitted currency data from closely watched economic reports. Weeks earlier, Chinese regulators fined a journalist $23,000 for reposting a message that said a big securities firm had told elite clients to sell stock. Before that, officials pressed two companies to stop releasing early results from a survey of Chinese factories that often moved markets. Chinese leaders are taking increasingly bold steps to stop rising pessimism about turbulent markets and the slowing of the country’s growth. As financial and economic troubles threaten to undermine confidence in the Communist Party, Beijing is tightening the flow of economic information and even criminalizing commentary that officials believe could hurt stocks or the currency.

The effort to control the economic narrative plays into a wide-reaching strategy by President Xi Jinping to solidify support at a time when doubts are swirling about his ability to manage the tumult. The persistence of that tumult was underscored on Thursday by a 6.4% drop in Chinese stocks, which are now down more than a fifth since the beginning of this year alone. The government moved to bolster confidence on Saturday by ousting its top securities regulator, who had been widely accused of contributing to the stock market turmoil. Mr. Xi is also putting pressure on the Chinese media to focus on positive news that reflects well on the party. But the tightly scripted story makes it ever more difficult to get information needed to gauge the extent of the country’s slowdown, analysts say. “Data disappears when it becomes negative,” said Anne Stevenson-Yang, co-founder of J Capital Research, which analyzes the Chinese economy.

A bit more of that through CNBC:

Chinese Accounting Is ‘Highly Questionable’

Financial reporting in China was back in the spotlight again Friday, with one strategist claiming Chinese businesses were using “accounting trickery” to mask underlying credit problems. China looks like it’s heading towards a credit bust, Chris Watling, CEO and chief market strategist at Longview Economics told CNBC on Friday, explaining that cash borrowed by mainland firms is primarily being used to service debts. “We’ve been looking a lot at Chinese accounting recently and it is highly questionable,” he said. The corporate sector is increasing borrowing to pay interest, while instances of fraud and default are on the rise, he added in a note published Thursday. He said there were many examples where operating profit has been high, while cash flow has been negative — a “classic sign” that firms aren’t generating a profit, he added.

Watling highlighted that the balance sheets of commercial banks were particularly worrying. “In an economy which has undergone a credit boom, all of the lending is not necessarily readily apparent from the top level data,” he said. “Accounting trickery is often at work..”

A good example of where the data fit with reality is this graph from ZH, which has a strong correlation with Balding’s claim that there is no Chinese trade surplus. What there is, is a lot of fake invoices.

And that inevitably leads to this kind of Bloomberg piece. Beijing is dying to get investments flowing in from abroad, but investors have no idea what potential profits will be worth in yuan, or, given capital controls, whether or when they can take them out of the country.

Yuan Uncertainty Scares Funds Away From China Bond Market

Yield versus yuan. That’s the crux of the investment decision now facing the global funds given more access to China’s bond market. While it offers the highest yields among the world’s major economies, PIMCO and Schroder Investment say exchange-rate risk is damping global demand for Chinese assets. Barclays said this week there’s a growing chance China will announce a sharp, one-time devaluation to change sentiment toward the currency and suggested such a move would need to be in the region of 25% to be effective. “Uncertainty around currency policy remains one of the larger hurdles for foreign investors,” said Rajeev De Mello at Schroder Investment in Singapore. “This should be resolved as the year progresses and would then be a signal to increase investments in Chinese government bonds.”

Of course the Chinese claim that this particular uncertainty is just a temporary thing, and it will all be fine soon, but that doesn’t look to be true. Or at least, it will remain an issue, and probably THE issue, as long as the yuan is seen as substantially overvalued. The PBoC and politburo thus far have apparently thought they could solve this by hiding data, uttering soothing words and/or bullying, but that’s not going to work. They need to devalue, and not by a few percent either.

Barclays says a devaluation “would need to be in the region of 25% to alter perceptions”, while Kyle Bass earlier mentioned a 30% to 50% move. Central bankers and politicians can try and stand still in the Mexican standoff until they’re blue in the face, but the markets will not stand still, and only get more nervous as time passes.

It doesn’t need to be done in Shanghai over the weekend, though one may wonder what will happen in the Chinese equity markets next week if nothing is done while there are great expectations now. From whatever angle we look at the issue, the outcome seems crystal clear: better get it done soon.

The US and Germany may not like it initially, but the uncertainty will hit them too, because the anticipation of a -strong- yuan devaluation affects their export markets, bonds, equities and currencies as well.

One problem we should not overlook may be that in the 1985 Plaza Accord, the strongest party -the US- wanted to get something done and got their devaluation wish. This time around, it’s not the strongest party that needs a devaluation, and the party that does need it doesn’t want it.

It is a very different set-up.

Feb 182016
 
 February 18, 2016  Posted by at 8:46 am Finance Tagged with: , , , , , , , , ,  2 Responses »


Russell Lee “Yreka, California, seat of a county rich in mineral deposits” 1942

• Negative Interest Rates A ‘Dangerous Experiment’, Warns Morgan Stanley (MW)
• Negative Interest Rates Are A ‘Gigantic Fiscal Failure’ (AEP)
• Japan’s Exports Drop Most Since 2009 as Sales to China Fall (BBG)
• Japan Shelves Plan to Let Pension Fund Directly Invest in Stocks (WSJ)
• China’s Banks May Be Getting Creative About Hiding Their Losses (BBG)
• China Central Bank Takes Another Step To Guide Interest Rates Lower (BBG)
• High Chance of China Hard Landing, Says Adviser to Japan’s Abe (BBG)
• Why the Chinese Yuan Will Lose 30% of its Value (CHS)
• China’s $600 Billion Subprime Crisis Is Already Here (BBG)
• Not Even a Wave of Oil Bankruptcies Will Shrink Crude Production (WSJ)
• Less Than 4% Of World Oil Supply In The Red At $35/b (Platts)
• Venezuela Lifts Gasoline Price by 6,200% and Devalues Currency by 37% (BBG)
• The Real Crisis is for Bank Bonds, Not Banks (WSJ)
• Fed’s Kashkari: 25% Capital Requirement May Be Right for Banks (WSJ)
• Banking Reform Is More Complex Than It Needs To Be (Chu)
• Italy Would Veto Any Cap On Banks’ Government Debt Holding (Reuters)
• German Central Bank Chief On Collision Course With Draghi Over QE (T.)
• Russia Sues Ukraine in London High Court Over $3 Billion Default (BBG)
• WikiLeaks Releases Classified Data On EU Military Op Against Refugee Flows (RT)
• European States Deeply Divided On Refugee Crisis Ahead Of Summit (Guardian)

“..the “ECB is ready to do its part” and would “not hesitate to act” to crisis-proof the eurozone.” You don’t crisis-proof by creating a crisis.

• Negative Interest Rates A ‘Dangerous Experiment’, Warns Morgan Stanley (MW)

After ECB chief Mario Draghi on Monday hinted more economic stimulus could be coming in March, expectations have risen that deposit rates will be pushed further into negative territory in a bid to fend off the impact from lower oil prices and world-wide economic jitters. While rate cuts usually are seen as a way to stimulate economic growth and weaken the currency, analysts at Morgan Stanley on Wednesday raised concerns that exactly the opposite would happen were the ECB to take rates even lower. Part of this is because investors already have rejigged their portfolios to account for the policy, they explained. Here’s the bank’s thinking:

“Further moves into negative rates will have much less of an impact on the euro, in our view, given that most of the portfolio adjustment is already complete. Rather, we are concerned it erodes bank profitability, creating other systemic risks,” they said in a note. “Could the most bullish ECB outcome be no rate cut?,” Morgan Stanley analysts asked. Calling negative interest rates a “dangerous experiment’, the economists argued such policy would erode bank profits 5%-10% and risk curbing lending across eurozone borders. European banks have already been off to a rough start to the year, down 21% on concerns about the fallout from negative rates, lackluster profits, tougher regulation and a slowdown in global growth. “The credit impulse has turned negative, new loan origination has slowed, and systemic stress in the financial system has risen,” the Morgan Stanley analysts said.

The comments come ahead of the ECB’s March 10 meeting, where investors increasingly are banking on some easing action. The central bank massively disappointed investors in December by introducing a smaller-than-expected rate cut and choosing not to pump more new money into the eurozone economy each month. But at the January meeting, Draghi opened the door for more easing if the economy and inflation showed no signs of improvement. Fast forward a few weeks, and markets have taken a serious beating as investors started to get really nervous about the impact of persistently low oil prices and a slowdown in the world economy.This didn’t go unnoticed by the ECB boss. At his quarterly hearing before the European Parliament on Monday he stressed the “ECB is ready to do its part” and would “not hesitate to act” to crisis-proof the eurozone.

Read more …

Negative rates and the war on cash.

• Negative Interest Rates Are A ‘Gigantic Fiscal Failure’ (AEP)

[..] negative rates are a creeping threat to civil liberties since the only way to enforce such a regime over time is to abolish cash, for otherwise people will move their savings beyond reach. Mao Zedong briefly flirted with the idea during the Cultural Revolution in his bid to destroy every vestige of China’s ancient culture, but even he recoiled. The eurozone already plans to eliminate the €500 note – allegedly to hurt organized crime – and from there it is a slide down the scales to notes in daily use and then to curbs on quasi-money. It is a step to FDR’s gold embargo and Emergency Banking Act of 1933, when Americans were ordered to hand over their bullion or face 10 years in prison. One policymaker in Davos this year let slip that drastic action to scrap cash would be needed to fight a decade-long war against “secular stagnation” once rates test the limits of -1pc or -2pc.

The Bank of England’s Andrew Haldane floated the idea in a speech last September, suggesting that central banks may have to take radical action to circumvent the constraints of the “lower zero-bound”. Mr Haldane said NIRP reinforced by electronic money is a safer course than going down the “most slippery of slopes” by printing money to cover government spending. Here he is wrong. As Lord Turner argues, there is nothing inherently more slippery about direct monetary financing of fiscal stimulus than any other crisis measure. “Everything we are doing is risky,” he says. One can hardly claim that chronic use of QE to inflate asset prices and to stoke more credit is sound practice, or socially just. A monetary policy committee can calibrate what is judged to be the proper level of debt monetisation needed to avert deflation in exactly the same way as the MPC or the FOMC calibrate interest rates.

The money creation must be permanent to avoid “Ricardian Equivalence”, where people anticipate that more spending now merely mean more debt in the future. All debt accumulated by central banks under QE should be converted to perpetual non-interest bearing debt, and preferably burned on a pyre in public squares to the sound of trumpets to drive home the message that the debt has been eliminated forever. This will pre-empt the panic that might occur among investors and politicians should public debt ever cross some arbitrary totemic level. Any New Deal should be funded in the same way – partly or in whole – with the same vow that the debt will never be repaid. The money creation should continue at the therapeutic dose until the objective is achieved.

There is no technical objection to this form of “fiscal dominance”, as monetary guru Lars Svensson told the IMF forum. All that is missing is political will. Needless to say, the eurozone cannot venture down this path. Maastricht prohibits the ECB from overt financing of deficits and any such thinking in Frankfurt would lead to a court challenge and destroy German consent for monetary union. This augurs ill, because they will need it. Thankfully, those of us with our own currencies, central banks and fully sovereign governments always have the means to prevent the collapse of nominal GDP and to avert debt-deflation. We can run out of wit: we can never run out of monetary ammunition.

Read more …

Japan exports to China down 18%. Japan imports also down 18%. World trade falls off a cliff.

More numbers:

January Exports from Asia’s Largest Economies

Singapore -9.9%
China -11.2%
Japan -12.9%
Taiwan -13%
Korea -18.5%
Indonesia -20.7%

• Japan’s Exports Drop Most Since 2009 as Sales to China Fall (BBG)

Japan’s exports fell for a fourth consecutive month and dropped the most since 2009, underscoring continued weakness in an economy that contracted in the final months of 2015. Exports to China, Japan’s largest trading partner, were down almost 18%, driving an overall decline of nearly 13% in the value of overseas shipments in January from a year earlier. Imports dropped 18%, leaving a 645.9 billion yen ($5.7 billion) trade deficit, the Ministry of Finance said on Thursday. Falling exports compound poor sentiment in Japan, where wage gains have stagnated, consumer prices are barely rising and households are reluctant to spend. This year stocks have plunged and the yen has gained more than 5% against the dollar amid concerns over China’s slowdown and U.S. growth.

This adds to worries about the seesawing nature of Japan’s economy between modest growth and contraction. “The environment for Japanese exports is looking bad as Japanese companies shift production abroad, the global economy slows and the yen strengthens,” said Yasunari Ueno at Mizuho. “It’s becoming clear that that there is no driver to support Japan’s economy.” While exports to China typically ease in the weeks before lunar new year holidays, and the break came earlier this year, shipments to Japan’s neighbor have dropped for six straight months. Part of the weakness in the export figure is also because Japanese companies received lower prices for sales of steel and chemical products amid the general downturn in commodity and energy markets, said Atsushi Takeda at Itochu in Tokyo.

By volume, exports fell 9.1% in January from a year earlier, the biggest drop since February 2013, while import volumes declined 5.1%. Earlier this week, GDP data showed the Japanese economy shrank an annualized 1.4% in the three months ended Dec. 31. After that, Nomura cut its forecast for Japan’s fiscal 2016 GDP to 1% from a previous projection of 1.4%. The firm sees a high chance that the Bank of Japan will expand monetary stimulus at its March meeting if the market turmoil continues. Itochu’s Takeda doesn’t think it is likely that Japan will fall into a recession though he said “there are growing downside risks to the economy.” “Should gains in the yen and declines in stocks continue, they may take a toll on capital spending, exports and consumption,” he said.

Read more …

A sign of Abe’s waning clout?!

• Japan Shelves Plan to Let Pension Fund Directly Invest in Stocks (WSJ)

Japan’s government has put off a plan to let its $1.1 trillion public pension fund buy and sell stocks directly, following criticism that the move could lead to excessive state influence on the market. The decision dashes the hopes of the Government Pension Investment Fund’s chief investment officer and some foreign money managers who believed that a direct role in the stock market could make the fund a more effective investor and improve corporate governance in Japan. A committee in Prime Minister Shinzo Abe’s ruling Liberal Democratic Party decided Tuesday to postpone consideration of the issue for three years, said LDP lawmaker Shigeyuki Goto, the committee’s secretary-general. “There won’t be any in-house stock investing, but it remains to be debated in the future,” Mr. Goto said. “The stock issue was the biggest sticking point for those involved in the discussions.”

The GPIF currently outsources decisions on its nearly ¥60 trillion ($520 billion) stock portfolio to more than a dozen outside asset managers. It handles domestic bonds in-house. Mr. Abe’s government has pushed to make the GPIF a more sophisticated investor in line with its overseas peers. The fund has moved more money into stocks and foreign bonds. Yet opposition from business and union leaders shows concern about allowing too much change at the GPIF, whose investment decisions ultimately affect how much Japan’s pensioners can receive. Recent market turmoil has made the fund a politically sensitive subject. The GPIF was criticized by opposition politicians after losing nearly ¥8 trillion in the third quarter of 2015 as global stock prices fell, and it is expected to post more losses in the coming months.

Mr. Abe was asked about the issue in parliament Monday and responded, “If expected returns aren’t met, that will of course impact pension payments.” Japan’s leading business group, Keidanren, as well as Rengo, an umbrella group for labor unions, both opposed letting the fund directly invest in stocks. They expressed concern about the GPIF being used to influence management at Japanese companies by using its voting rights as a shareholder. “It’s a very serious issue if the GPIF were to become a direct shareholder,” said Keidanren official Susumu Makihara at a meeting to debate the change in January. He said “a massive state organization would become a market player” under the proposal and it wasn’t clear how it would use its clout at companies.

Read more …

“We tend to think that the Chinese government is likely to provide support if there is any sign of a crisis.” Well, they would like to, but can they?

• China’s Banks May Be Getting Creative About Hiding Their Losses (BBG)

Chinese lenders are reacting to a regulatory crackdown on shadow financing by increasing activity in their more opaque receivables accounts, a practice Commerzbank estimates may result in losses of as much as 1 trillion yuan ($153 billion) over five years. Banks are increasingly using trusts or asset management plans to lend and recording them as funds to be received rather than as loans, which are subject to stricter regulatory oversight and capital limits. The German bank’s forecast is based on total outstanding receivables of around 11.5 trillion yuan. “Chinese banks haven’t provisioned for receivables and those are essentially riskier loans,” said Xuanlai He at Commerzbank. “The eventual losses will have significant impact on China’s economy because you could have contagion risk in banking sector.”

Official data show nonperforming loans at Chinese commercial banks jumped 51% last year to a decade-high of 1.27 trillion yuan amid a stock market rout and the worst economic growth in a quarter century. While Moody’s Investors Service doesn’t expect a banking crisis in China in the next 12 to 18 months, it said in a Jan. 26 note that it does see higher loan delinquencies, more defaults on corporate debt and some losses in wealth-management products. “The receivables portfolio in Chinese banks is opaque so we can’t make an assumption on the asset quality,” said Christine Kuo, analyst at Moody’s in Hong Kong. “Provisions for receivables are indeed very low compared to that for loans. We tend to think that the Chinese government is likely to provide support if there is any sign of a crisis.”

China CITIC Bank’s assets under receivables tripled to 900 billion yuan by June 30, from 300 billion yuan at the end of 2013, according to the bank’s financial statements. Concerns about Chinese banks’ creditworthiness are mounting with the cost of insuring Industrial & Commercial Bank of China’s debt against default reaching an all-time high of 199.5 basis points on Jan. 21. The bank’s 6% perpetual notes that count as Additional Tier 1 capital fell to a record low of 99.5 cents last Thursday. The securities traded at 102.5 cents on the dollar Wednesday. The yield spread on China CITIC’s $300 million 6% 2024 notes surged to a one-year high of 336 basis points over U.S. Treasuries Wednesday.

Read more …

How afraid is Beijing of deflation? Apparently enough to blow another bubble.

• China Central Bank Takes Another Step To Guide Interest Rates Lower (BBG)

China’s central bank took another step to guide interest rates lower, offering to reduce the medium-term borrowing cost it charges lenders in the second such move this year. The People’s Bank of China has told banks it can provide cash through its Medium-term Lending Facility at 2.85% for six-month loans, down from 3%, according to a person with direct knowledge of the matter. The one-year borrowing rate would be eased to 3% from 3.25%, according to the person, who asked not to be identified because the plans aren’t public. Such a reduction would amount to a kind of monetary easing outside of traditional tools such as lowering benchmark lending or deposit rates or the reserve-requirement ratio for the biggest banks.

Overuse of RRR cuts may add too much pressure on short-term interest rates and would therefore be bad for stabilizing capital flows and the exchange rate, PBOC researcher Ma Jun said in a China Business News report published last month. “The PBOC is trying to find ways for monetary easing without making a high-profile interest-rate cut,” said Louis Kuijs at Oxford Economics in Hong Kong. “There’re likely to be more following steps in a similar direction, since a single move will not be enough to turn around the momentum of the economy.” China’s consumer price index climbed 1.8% in January from a year earlier, the National Bureau of Statistics said on Thursday. That was below the medium estimate of 1.9%.

The producer-price index fell 5.3%, extending declines to a record 47 months. “The data show that the economy is pretty weak,” said Larry Hu at Macquarie Securities in Hong Kong. The central bank is attempting to square the circle of supporting growth without using up limited monetary policy space or putting more downward pressure on the yuan, said Bloomberg Intelligence economist Tom Orlik. “That means more use of low-visibility instruments like the MLF to guide rates lower, rather than cuts in benchmark rates,” he said. “The trade off for low visibility, is the confidence boosting effect on the market is reduced.”

Read more …

Very high.

• High Chance of China Hard Landing, Says Adviser to Japan’s Abe (BBG)

The chances are high China will have a hard landing, and it must undergo a severe adjustment period, an economic adviser to Japanese Prime Minister Shinzo Abe said. “There’s a high possibility of a hard landing in China” as its economy is oversupplied and adjusting demand and supply will cause a shock, Etsuro Honda said in an interview late Tuesday in Tokyo. The problem is more acute as “China can’t use monetary policy for quantitative easing as it has been used to stabilize its currency.” While officials from the IMF to the Bank of Japan have said China will avoid an economic crash, Honda’s comments echo concerns among investors about the direction of China’s economy.

A surprise currency devaluation, the slowest growth in a quarter century and perceived policy missteps are raising anxiety about the world’s second-largest economy. Unlike the idea of capital controls suggested by BOJ Governor Haruhiko Kuroda, Honda recommended China adopt a floating exchange rate system. Otherwise, China’s economy will suffer from a problem of oversupply for quite a while, he said. Honda, 61, is an academic and has been an adviser to Abe for the past three years. “I really don’t think that China’s economic fundamentals are good and it’s just real estate markets and stock markets that are panicking,” Honda said. “China has to go through massive structural reforms and its impact on other economies is quite large. That’s different from other nations.”

Read more …

The yuan has turned toxic.

• Why the Chinese Yuan Will Lose 30% of its Value (CHS)

The U.S. dollar has gained over 35% against major currencies since 2011. China’s government has pegged its currency, the yuan (renminbi) to the USD for many years. Until mid-2005, the yuan was pegged at about 8.3 to the dollar. After numerous complaints that the yuan was being kept artificially low to boost Chinese exports to the U.S., the Chinese monetary authorities let the yuan appreciate from 8.3 to about 6.8 to the dollar in 2008. This peg held steady until mid-2010, at which point the yuan slowly strengthened to 6 in early 2014. From that high point, the yuan has depreciated moderately to around 6.5 to the USD. Interestingly, this is about the same level the yuan reached in 2011, when the USD struck its multiyear low.

Since 2011, the USD has gained (depending on which index or weighting you choose) between 25% and 35%. I think the chart above (trade-weighted USD against major currencies) is more accurate than the conventional DXY index. Due to the USD peg, the yuan has appreciated in lockstep with the U.S. dollar against other currencies. On the face of it, the yuan would need to devalue by 35% just to return to its pre-USD-strength level in 2011. This would imply an eventual return to the yuan’s old peg around 8.3–or perhaps as high as 8.7.

[..] Here’s the larger context of China’s debt/currency implosion. From roughly 1989 to 2014 -25 years- the “sure bet” in the global economy was to invest in China by moving production to China. This flood of capital into China only gained momentum as the yuan appreciated in value against the USD once Chinese authorities loosened the peg from 8.3 to 6.6 and then all the way down to 6 to the dollar. Every dollar transferred to China and converted to yuan gained as much as 25% over the years of yuan appreciation. Those hefty returns on cash sitting in yuan sparked a veritable tsunami of capital into China. Now that the tide of capital has reversed, nobody wants yuan: not foreign firms, not FX punters and not the Chinese holding massive quantities of depreciating yuan.

This is why “housewives” from China are buying homes in Vancouver B.C. for $3 million. That $3 million could fall to $2 million as the yuan devalues to the old peg around 8.3 to the USD. Who’s left who believes the easy money is to be made in China? Nobody. Anyone seeking high quality overseas production is moving factories to the U.S. for its appreciating dollar and cheap energy, or to Vietnam or other locales with low labor costs and depreciated currencies. For years, China bulls insisted China could crush the U.S. simply by selling a chunk of its $4 trillion foreign exchange reserves hoard of U.S. Treasuries.

Now that China has dumped over $700 billion of its reserves in a matter of months, this assertion has been revealed as false: the demand for USD is strong enough to absorb all of China’s selling and still push the USD higher. The stark truth is nobody wants yuan any more. Why buy something that is sure to lose value? the only question is how much value? The basic facts suggest a 30% loss and a return to the old peg of 8.3 is baked in. But that doesn’t mean the devaluation of the yuan has to stop at 8.3: just as the dollar’s recent strength is simply Stage One of a multi-stage liftoff, the yuan’s devaluation to 8 to the USD is only the first stage of a multi-year devaluation.

Read more …

“China’s bad loans have grown 256% in six years even as their ratio to total lending dropped.”

• China’s $600 Billion Subprime Crisis Is Already Here (BBG)

Sorry, Kyle Bass, you’re a bit late to the game. The debt problem in China has already reached the proportions of the U.S. subprime mortgage debacle. Don’t worry, though: Chinese authorities are on the case – discussing reducing the required coverage for bad loans so that banks can keep booking profits and lending. Including “special-mention” loans, which are those showing signs of future repayment risk, the industry’s total troubled advances swelled to 4.2 trillion yuan ($645 billion) as of December, representing 5.46% of total lending. That number is already higher than the $600 billion total subprime mortgages in the U.S. as of 2006, just before that asset class toppled the world into the worst financial crisis since 1929.

The amount of loans classed as nonperforming at Chinese commercial banks jumped 51% from a year earlier to 1.27 trillion yuan by December, the highest level since June 2006, data from the China Banking Regulatory Commission showed on Monday. The ratio of soured debt climbed to 1.67% from 1.25%, while the industry’s bad-loan coverage ratio, a measure of its ability to absorb potential losses, weakened to 181% from more than 200% a year earlier. The news looks to have scared Chinese authorities into reacting. Note that they aren’t curbing the ability of Chinese banks to lend or asking them to write off bad credit. Instead they’re considering putting aside checks already in place that are aimed at ensuring the health of the financial system: by reducing the ratio of provisions that banks must set aside for bad debt, currently set at a minimum 150%.

Perhaps, they’re hoping banks will lend even more if they ease the rules. That’s one way to keep the ratio of nonperforming loans under control. As the denominator increases the ratio remains steady or even drops. The absolute number of bad loans, however, keeps swelling. Guess what? Banks are lending more. China’s new yuan loans jumped to a record 2.51 trillion yuan in January, the People’s Bank of China reported on Tuesday. Aggregate financing, the broadest measure of new credit, also rose to a record, at 3.42 trillion yuan. China’s bad loans have grown 256% in six years even as their ratio to total lending dropped. The true amount of debt that isn’t being repaid is open for debate.

One example of how the data can be distorted: Banks are making increasing use of their more opaque receivables accounts to mask loans and potential losses. Still, adding special-mention loans to those classed as nonperforming gives some measure of the size of the bad-debt problem. Unfortunately, the CBRC started to publish special-mention loan numbers only last year, so it’s hard to put them in historical context. The dynamic is clear. A splurge of new lending can help to dilute existing bad loans, but only at a cost. This is a game that can’t continue forever, particularly if credit is being foisted on to an already over-leveraged and slowing economy. At some point, the music will stop and there will have to be a reckoning. The longer China postpones that, the harder it will be.

Read more …

Selling at a loss is often preferable over not selling at all, because of sunk costs or expected restart costs.

• Not Even a Wave of Oil Bankruptcies Will Shrink Crude Production (WSJ)

More than one-third of oil and natural-gas producers around the world are at risk of declaring bankruptcy this year, according to a new report from Deloitte. Oil prices have plunged from more than $100 a barrel in mid-2014 to about $30 a barrel today. Yet just 35 so-called exploration and production companies filed for bankruptcy between July 2014 and the end of last year, Deloitte says. Most producers managed to stay afloat by raising cash through capital markets, asset sales and spending cuts. Those options are running out.

The only moves left for most producers are dividend cuts and share buybacks, Deloitte says. The firm estimates that 175 companies, or 35% of the E&Ps listed world-wide, are in danger of declaring bankruptcy this year. The conundrum for many investors is that a slew of bankruptcies won’t necessarily shrink the global glut of crude. Companies need cash to repay their debts, so their existing wells are unlikely to stop operating throughout the bankruptcy process. In fact, those wells will probably be sold to better-financed buyers, who can afford to keep production going or even increase it.

Read more …

“Given the cost of restarting production, many producers will continue to take the loss in the hope of a rebound in prices.” (h/t ZH)

• Less Than 4% Of World Oil Supply In The Red At $35/b (Platts)

Fears of a deepening non-OPEC supply crunch in response to the latest oil price slump may be overdone as many producers are absorbing short-term losses in the hope of a price rebound, according a new study by research group Wood Mackenzie. Citing up-to-date analysis of production data and cash costs from over 10,000 oil fields, Wood Mac said it believes 3.4 million b/d, or less than 4% of global oil supply, is unprofitable at oil prices below $35/b. Even the majority of US shale and tight oil, which has been under the spotlight due to higher-than-average production costs, only becomes cash negative at Brent prices “well-below” $30/b, according to the study.

For many producers, being cash negative is not enough of an incentive to shut down fields as restarting flow can be costly and some are able to store output with a view to selling it when prices recover. “Curtailed budgets have slowed investment, which will reduce future volumes, but there is little evidence of production shut-ins for economic reasons,” Wood Mac’s vice president of investment research Robert Plummer said in a note. “Given the cost of restarting production, many producers will continue to take the loss in the hope of a rebound in prices.” Even since oil prices began sliding in late 2014, there have been relatively few outright field production halts due to low prices, with only around 100,000 b/d shut in globally, according to the study.

Despite widespread fears of a major supply collapse, the US’ shale oil output since late 2014, sharp deflation in service sector costs and greater drilling efficiencies have seen shale oil output remain more resilient to lower prices than first thought. Wood Mac said falling production costs in the US over the last year have resulted in only 190,000 b/d being cash negative at a Brent price of $35/b. The latest study contrasts with a similar report from the research group a year ago when it estimated that up to 1.5 million b/d of output – focused in the US – was vulnerable to being shut in at $40/b Brent.

Read more …

Count the failed states the west has created.

• Venezuela Lifts Gasoline Price by 6,200% and Devalues Currency by 37% (BBG)

Venezuela hiked gasoline prices for the first time in almost two decades and devalued its currency as President Nicolas Maduro attempts to address triple-digit inflation and the economy’s deepest recession in over a decade. The primary exchange rate used for essential imports, such as food and medicine, will weaken to 10 bolivars per dollar from 6.3, Maduro said in a televised address to the nation. The government will also eliminate an intermediate rate that last sold dollars for about 13 bolivars and improve an alternative “free-floating, complementary” market that trades around 203 bolivars per dollar. The devaluation will ease the drain on government coffers by giving state oil company Petroleos de Venezuela more bolivars for each dollar of oil revenue, while higher gasoline prices will reduce expenditure on subsidies.

At the same time, the devaluation will probably force the government to raise the cost of staple foods such as rice and bread that most of the country now depends on to eat. “Faced with a criminal, chaotic inflation induced a long time ago, we must act with the power of the state to control and regulate markets,” Maduro said below a portrait of South American independence leader Simon Bolivar. While Maduro’s measures may fall short of fully addressing Venezuela’s ailing economy, the announcements may “bring some relief that it’s something after months (years) of nothing,” Sibohan Morden at Nomura Securities said in a note to clients published prior to Maduro’s speech. “It is also important that Chavismo shifts toward pragmatism and finally realizes that the Bolivarian revolution has failed.”

Something had to change after the bolivar lost 98% of its value on the black market since Maduro took office in 2013. The government was hemorrhaging funds as it struggled to meet international debt obligations and maintain the supply of essential items amid the collapse in oil prices. By long subsidizing the cost of fuel, the government has ensured that Venezuelans enjoy the cheapest gasoline in the world. Gasoline prices on Thursday will leap more than 60-fold to 6 bolivars a liter from 9.7 centavos. That’s equal to about 11 U.S. cents per gallon using the weakest legal exchange rate of 202.94 bolivars per dollar, up from about 0.2 U.S. cents per gallon. The price of 91-octane gasoline will increase to 1 bolivar a liter from 7 centavos. Even after these increases, Venezuela still has the lowest gasoline prices in the world.

Read more …

Then again, they’re not separate entities.

• The Real Crisis is for Bank Bonds, Not Banks (WSJ)

The fall from grace has been swift and hard. Buying high-yielding subordinated bank bonds that count toward Tier 1 capital was a hot trade in a world where investors were scrambling for yield. This is a case where markets have been their own worst enemy. European banks have been at the center of the recent market storm, with Deutsche Bank’s bonds particularly in focus. The move in prices has been big, even with a bounce in the last couple of days. Bank of America Merrill Lynch’s index of contingent capital bonds—popularly known as CoCos—has dropped 7.6% this year. Europe clearly has unresolved issues to address in its fragmented banking system. But this is hardly news. The issue lies more with the securities and the investors that hold them than the balance sheets of the banks that issued them.

The big risk that investors have woken up to isn’t that these bonds can be bailed-in if a bank hits trouble—it is that interest payments on them can be skipped under certain circumstances. In turn, falling prices have raised concerns that banks won’t exercise their option to redeem them at the first opportunity, requiring a further repricing downwards. That has upset the apple cart of what had become a so-called crowded trade—one that caught many investors’ imagination as central banks poured liquidity into markets. During the good times these instruments looked like more lucrative versions of safer, lower-yielding senior debt. But now their equity-like features have come to the fore. That is a big shift for holders to take on board and one that is unlikely to be reversed quickly.

In the meantime, it isn’t clear that there is a natural buyer for these securities. For those holders who wish to sell, that poses an immediate problem: there is no way out, and the turmoil may not be over yet. Longer term, the economics of these hybrid structures may depend on buyers seeing them as safe debt while issuers consider them as quasi-equity. If they are priced more like equity, they may not be so attractive to issuers. Regulators may have helped create an instrument that is only truly viable in fair-weather conditions.

Read more …

Kashkari seems to go mostly for the shock effect, and turns opaque as soon as he’s called on his words.

• Fed’s Kashkari: 25% Capital Requirement May Be Right for Banks (WSJ)

Q: You talk about higher capital requirements. How high should they be?

MR. KASHKARI: I don’t have a number in my head. I’ve seen some proposals for a 25% capital requirement. So leverage ratios, effectively, just to keep it simple, you know, 4:1. You know, I think that’s a place we could discuss. I don’t have that – I don’t have a magic number yet. And also, importantly, we’re not suggesting that we at the Minneapolis Fed necessarily have all the answers. What we’re trying to do is launch a process where we can bring all of these ideas out from across the country and give them the serious analysis and consideration that I feel like they deserve.

Because when I look at the Dodd-Frank Act – and I was – I had already left government by then – but from the outside, it appeared that the more transformational solutions were just taken off the table – like, OK, that’s too bold; let’s keep the financial system roughly in its current form, and let’s make it safer and stronger. And that’s not an irrational conclusion for legislators to have drawn at that time, because we were – the recovery was still so unclear. But here we are, six years later, the economy is a lot stronger than it was coming out of the crisis. In my judgment, we still have the problem of too-big-to-fail banks, and now feels like the right time to look at this again.

Read more …

That second graphic here is very scary. The UK banking sector is 480% of GDP. With a reserve requirement of 3%, tops.

• Banking Reform Is More Complex Than It Needs To Be (Chu)

“All that is necessary for the triumph of evil is that good men do nothing.” There’s some uncertainty over whether Edmund Burke actually made this observation. But, regardless of its provenance, the wisdom merits a tweak for our times. Today the necessary condition for vested interests to prevail over the public interest is that good men don’t understand what the hell is going on. Something has happened in the UK banking reform debate. Sir John Vickers, a central figure in the Government’s post-crisis financial overhaul, has questioned whether the Bank of England’s latest proposals to shore up the sector go far enough. Yet this debate is perfectly impenetrable to the non-expert. Read the exchanges between Sir John and the Bank and you will soon slip into a numbing bath of acronyms and jargon from which you will very likely not resurface any the wiser.

G-SIBs, D-SIBs, SRBs, RWAs, Tier 1, Basel III, CoCos … These names will float across your vision, like the members of the world’s most boring rap group. You will read about the appropriate threshold for the activation of “a risk-weighted SRB rate of 3%” and the relevance of “counter-cyclical buffers” and, you will, quite understandably, conclude there is something better you could be doing with your time. But ignore the detail. This complexity is the outcome of years, perhaps even decades, of horse trading between bank lobbyists, regulators and politicians from all around the world. As a non-expert you’re not supposed to be able to follow it. It hasn’t been designed to confuse ordinary people. That’s just a happy side-effect (as far as the banks are concerned).

So clear it from your mind. Focus, instead, on the essentials. Banks are not as complex as they are made out to be by bankers and regulators. A bank has a balance sheet just like any other business. On the asset side of the balance sheet are its loans to customers. On the liabilities side are the current account deposits of customers, plus borrowings from the wholesale capital markets and, most importantly of all, the equity of its investors. The liabilities of a bank fund its assets. Equity is what gets eaten into first when a bank makes losses. If the equity is all used up, the bank is bust. And as we saw in 2008, that can mean taxpayers forced to step in to stop these institutions collapsing and taking the entire economy down with them. That’s why regulators must make sure banks have a sufficiently large tranche of equity financing on their balance sheets.

In support of his case Sir John has chosen to cite the analysis of the respected independent expert in finance, Anat Admati of Stanford University. This is interesting. Ms Admati has recommended that a private bank’s equity cushion should be equivalent to between 20 to 30% of its assets. So what would you guess is the current level of equity for banks being targeted by the Bank of England? 15%? 10%? Try 3%. Or 4% at most. And even Sir John’s report, despite his complaints today, only wanted banks to hold equity worth a maximum of around 4% of assets. Consider what this means: it implies that a mere 3 or 4% fall in the value of a bank’s assets would bankrupt it – and government ministers and regulators would, once again, need to consider whether to step in. To state what should be obvious: that’s not very much. And that simple ratio – known as the “leverage ratio” – should be focus of debate.

Read more …

Bye bye banking union. Renzi’s clear: clean up Deutsche first.

• Italy Would Veto Any Cap On Banks’ Government Debt Holding (Reuters)

Italy would oppose capping banks’ holdings of domestic sovereign bonds, Prime Minister Matteo Renzi said on Wednesday, throwing down the gauntlet to European policymakers who are considering a cap to strengthen the euro zone banking system. The European Commission plans to review the current rules on banks’ exposure to their home countries’ debt as a way to reduce the risk that wobbly public finances might pose to a national financial system. “We will veto any attempt to put a ceiling on government bonds in banks’ portfolios,” Renzi told the upper house Senate. The European Central Bank’s chief supervisor has proposed a limit on national sovereign debt holdings at 25% of a bank’s equity, but the ECB vice president favours a risk-weighted approach.

Bond markets in Italy and Spain would likely see the biggest impact among major euro zone countries if a cap were imposed, as banks in both countries hold piles of state-issued bonds. Around €405 billion ($451 billion), or 21.6% of all Italian government debt, is owned by its banks. The 41-year-old prime minister said Italy would take a firm line on the issue, adding: “Rather than worrying about government bonds in the banks we should be strong enough to say that (banks elsewhere in Europe) hold too many toxic assets.” Renzi, who has recently taken several swipes at Germany’s banking sector, mentioned the case of Deutsche Bank, which said last week it would buy back more than $5 billion in senior debt.

Read more …

Plus ça change..

• German Central Bank Chief On Collision Course With Draghi Over QE (T.)

Germany’s powerful central bank chief has said quantitative easing is no longer appropriate for Europe, putting Berlin on a collision course with the ECB over expanding stimulus measures to revive the single currency area. Jens Weidmann, head of the Bundesbank and a member of the ECB’s governing council, said QE was “no longer necessary” for the eurozone, despite the widespread expectation that more stimulus will be announced as early as next month. However, Mr Weidmann defended the ECB’s bond-buying scheme – launched in March last year – at a hearing at the German Constitutional Court on Tuesday, arguing that it did not contravene the principles of the German constitution. But his resistance to expanding QE suggests the ECB’s hawkish members are hardening in their stance against expanding the stimulus programme from its current €60bn a month.

Crucially, Mr Weidmann will not be able to take part in the March vote under the ECB’s rotating voting rules. The Bundesbank chief’s position is in stark opposition to that of ECB president Mario Draghi, who has repeated the central bank’s willingness to “do its part” to revive inflation and growth in the bloc as turmoil has engulfed global markets this year. Draghi’s failure to ramp up QE in December sent markets into a tailspin and has helped European equities plunge by as much 13pc this year. Mr Weidmann was speaking as a witness in front of Germany’s powerful constitutional court in Karlsruhe on Tuesday. The court – which has the power to strike down EU laws it deems incompatible with Germany’s supreme federal constitutional law – was meeting to consider the legality of the ECB’s landmark Outright Monetary Transactions scheme (OMT), first announced in 2012.

Mr Weidmann has been a vociferous opponent of OMT, which acts as a financial backstop for the euro’s distressed debtors but has never been deployed, arguing that it represents the illegal financing of government debt. But he refrained from repeating his criticisms on Tuesday, saying only that the QE measures were less “problematic” than the more ambitious OMT. ECB board member Yves Mersch said OMT was devised to “confront an extraordinary crisis situation” when the future of the eurozone was in doubt. “This crisis situation was characterised by massive distortions of the government bond market that developed their own momentum,” said Mr Mersch. “This in turn led to a disruption of the monetary policy transmission mechanism, which posed a threat for price stability.” The German court is not expected to make a formal ruling until later in the year.

Read more …

Ukraine has been turned into a failed state. Even if Russia wins in court, what are the odds it will ever be paid?

• Russia Sues Ukraine in London High Court Over $3 Billion Default (BBG)

Russia said it filed a lawsuit against Ukraine in the High Court in London after the government in Kiev defaulted on $3 billion in bonds. Cleary Gottlieb Steen & Hamilton was hired to represent the government in Moscow in a case that will seek to recover the principal in full, $75 million of unpaid interest and legal fees, Russian Finance Minister Anton Siluanov said on Wednesday. The filing comes after Germany attempted to mediate talks between the two former-Soviet neighbors to try to reach an out-of-court settlement. “I expect that the process in the English court will be open and transparent,” Siluanov said. “This lawsuit was filed after numerous futile attempts to encourage Ukraine to enter into good faith negotiations to restructure the debt.”

The case brings to a head a standoff between the two countries after Russia declined to take part in a $15 billion restructuring that Ukraine negotiated with its other Eurobond holders last year. Siluanov reiterated that Russia was demanding better treatment than private creditors, which include Franklin Templeton, and wants to be treated as a sovereign debtor. Russia has to pursue legal action against Ukraine in the U.K. because the bond was structured under English Law. President Vladimir Putin bought the debt in December 2013 to bail out his former Ukrainian counterpart and ally, Viktor Yanukovych, just months before he was toppled and Russia annexed Crimea. The notes were priced to yield 5%, less than half the rate on Ukrainian debt at the time.

The filing poses another obstacle to Ukraine’s government as it faces political infighting that’s threatening to sink the ruling coalition and further stall a $17.5 billion IMF lifeline that the country needs to stay afloat. The IMF warned last week the aid package risked failure if the government doesn’t kick start an overhaul of its economy.

Read more …

The smugglers are by now better funded than the military.

• WikiLeaks Releases Classified Data On EU Military Op Against Refugee Flows (RT)

WikiLeaks has released a classified report detailing the EU’s military operations against refugee flows in Europe. It also outlines a plan to develop a “reliable” government in Libya which will, in turn, allow EU operations to expand in the area. The leaked report, dated January 29, 2016, is written by the operation’s commander, Rear Admiral Enrico Credendino of the Italian Navy, for the EU Military Committee and the Political and Security Committee of the EU. The document gives refugee flow statistics and details of performed and planned operation phases of the joint EU forces operating in the Mediterranean. The report also places pressure on the responsible EU bodies to help speed up the process of forming a “reliable” government in Libya, which is expected to invite EU forces to operate within its territorial waters, and later give permission to extend EU military operations onshore.

“Through the capability and capacity building of the Libyan Navy and Coastguard we will be able to give the Libyan authorities something in exchange for their cooperation in tackling the irregular migration issue. This collaboration could represent one of the elements of the EU comprehensive approach to help secure their invitation to operate inside their territory during Phase 2 activities,” the document states. Admiral Credendino writes that the task force is ready to proceed to phase 2B despite political and legal challenges: “…We are ready to move to phase 2B (Territorial Waters) where we can make a more significant impact on the smuggler and traffickers business model.” “However, in order to move into the following phases we need to have a government of national accord with which to engage.” “A suitable legal finish is absolutely fundamental to the transition to phase 2B (Territorial Waters) as without this, we cannot be effective.”

“Central to this and to the whole transition to phase 2B, is an agreement with the Libyan authorities. Ultimately they have the casting vote on the legal finish which will in turn drive the transition to phase 2B and the appetite for Member States to provide assets. As a European Union, we must therefore apply diplomatic pressure appropriately to deliver the correct outcome,” the document states. The leak comes less than five months after it was reported that Operation Sophia would consist of 22 member states and 1,300 personnel which would board and seize suspect vessels in the Mediterranean. However, the document notes that when the operation progresses into phases 2B and 3, “the smugglers will again most likely adapt quickly to the changing situation. The primary concern for smugglers will likely remain to avoid being apprehended so they can continue their illegal activities.”

The operation’s objective is primarily to disrupt smuggling routes by human traffickers, rather than to stop migration flows, according to the European Union Institute for Security Studies, which wrote in a document that the operation began on July 27, 2015. The Institute noted, however, that there is a “real uncertainty on whether the operation will ever be able – for either legal or political reasons – to get to the core of its mandate, i.e. neutralising the smuggling networks through deterrence or open coercion, both off the Libyan coast and onshore.” It went on to note that regardless of the operation’s support for EU member states, only “a very few” are likely to “have the skills and experience for such missions, let alone the will.” It also stressed that the operation cannot be a “solution” to the refugee crisis, and that “no one in Brussels is contending that it could.”

Read more …

They can talk for years and still won’t agree. Sticks and carrots galore, but those don’t keep the EU together.

• European States Deeply Divided On Refugee Crisis Ahead Of Summit (Guardian)

Europe’s deep divide over immigration is to be laid bare at an EU summit in Brussels on Thursday, with German chancellor Angela Merkel struggling to salvage her open-door policy while a growing number of countries move to seal borders to newcomers along the Balkan routes. A dinner debate on the migration crisis on Thursday evening will do little to resolve the differences, senior EU officials predict. Donald Tusk, the president of the European council, has avoided putting any new decisions on the agenda in an attempt to avoid fresh arguments. The leaders of four anti-immigration eastern European countries met in Prague on Monday and demanded alternative EU policies by next month.

Their plan amounts to exporting Hungary’s zero-immigration razor-wire model to the Balkans, sealing Macedonia’s border with northern Greece, and bottling up the vast numbers of refugees in Greece unless they are deported back to Turkey. Merkel, by contrast, is to lead a rival meeting of leaders of 10 countries on Thursday in an attempt to invigorate a pact with Turkey, which is aimed at trading money and refugee quotas for Ankara’s efforts to minimise the numbers crossing the Aegean to Greece. Merkel’s plan hinges on EU countries volunteering to take in quotas of refugees directly from Turkey. But even among her allies – a so-called coalition of the willing – support for the policy is fading. Austria, which is hosting Thursday’s meeting at its embassy in Brussels, announced much stiffer national border controls this week.

It has also told Brussels and Balkan governments that it could close its borders within weeks. France, also part of the coalition, announced that it would not participate in any new quotas system. “You can’t have 20 [EU] countries refusing to take in refugees,” said a European commissioner. But senior officials in Brussels admit that there is now a solid majority of EU states opposing Merkel. In a pre-summit statement to parliament in Berlin on Wednesday, Merkel stoutly defended the policies that are under fire at home and across Europe. Despite the problems, she said, 90% of Germans continued to support taking in people fleeing war, terror and persecution. “I think that’s wonderful,” Merkel said.

Her speech dwelt overwhelmingly on the faltering pact with Turkey, struck in November. Ahmet Davutoglu, the Turkish prime minister, is to attend the mini-summit in Brussels. The issue at the EU summit, Merkel said, will be whether to press ahead with the Turkey pact or whether to concentrate on the closed scenario of more fences and quarantining Greece.

Read more …

Feb 162016
 
 February 16, 2016  Posted by at 9:24 am Finance Tagged with: , , , , , , , ,  1 Response »


Byron On the streets after a New York blizzard 1899

• Central Bankers ‘Don’t Have A Clue’ – Jim Rogers (CNN)
• There Is Worse To Come As QE Loses Its Impact (FT)
• Markets Putting Faith in QE4? (WSJ)
• BOJ Launches Negative Rates, Already Dubbed A Failure By Markets (Reuters)
• China’s Problems ‘Just Gargantuan’ (CNBC)
• China Created A Record Half A Trillion Dollars Of Debt In January (ZH)
• China’s Bad Loans Rise to Highest in a Decade (BBG)
• Chinese Premier Faults Regulators’ Handling of Stocks, Yuan Rout (BBG)
• China Favors Flexibility in Managing Yuan (WSJ)
• Capital Flight Signals Investors Still Bracing For China To Devalue Yuan (MW)
• A Massive Banking Crisis Is Brewing In Singapore, Says Zulauf (SBR)
• Keiser: Deutsche Bank ‘Technically Insolvent’, Running A ‘Ponzi Scheme’ (RT)
• The Never-Ending Story: Europe’s Banks Face a Frightening Future (BBG)
• Low Oil Prices Claim New Victim, an Offshore Driller From Texas (NY Times)
• Sellers Of Auckland Houses Want $100,000 More Than They Did Last Year (Stuff)
• Repricing Reality (Jim Kunstler)
• German Minister Asks For Half A Billion To Create Jobs For Refugees (EA)
• Greek Minister: Hungary Has Sent Nothing, Not Even A Blanket (EA)
• Unknown Dead Fill Lesbos Cemetery For Refugees Drowned At Sea (Reuters)

Love the CNN side link: “Related: Rogers wants to buy North Korea.” Jim Rogers is so dead on.

• Central Bankers ‘Don’t Have A Clue’ – Jim Rogers (CNN)

Famed investor Jim Rogers is warning that financial Armageddon is just around the corner, and it’s being fueled by moronic central bankers. “We’re all going to pay a horrible price for the incompetence of these central bankers,” he said Monday in a TV interview with CNNMoney’s Nina dos Santos. “We got a bunch of academics and bureaucrats who don’t have a clue what they’re doing.” The Singapore-based American investor said central bankers are doing everything they can to prop up financial markets, but it’s all for naught. He predicts their unconventional monetary strategies will lead to a stock market rally in the near future, but deep trouble later this year and into 2017. “This is going to be a disaster in the end,” he said. “You should be very worried and you should be prepared.”

Central bankers around the world have been increasingly using negative interest rates to prop up inflation and support their economies, but Rogers said the moves aren’t working. He said they are simply trying to rescue stock markets and help brokers keep their Lamborghinis. “The mistake they’re making is, they’ve got to let the markets sort themselves out,” he said. “It’s been over seven years since we’ve had a decent correction in the American stock market. That’s not normal … Markets are supposed to correct. We’re supposed to have economic slowdowns. That’s the way the world has always worked. But these guys think they’re smarter than the market. They’re not.”

Rogers made his fortune several times over by investing where others feared to tread. He made a name for himself in the 1970s after co-founding a top-performing fund with George Soros. He has also penned a range of investment books and become a fixture on the international speakers’ circuit. Rogers set a Guiness world record between 1999 and 2002 by visiting more than 100 countries by car.

Read more …

“..It is an odd world where the failure of unconventional monetary policies leads to more rather than less of the same. There will be worse to come.”

• There Is Worse To Come As QE Loses Its Impact (FT)

Ahead of a recent appearance in Hong Kong, one minder for Ben Bernanke suggested the former chairman of the Federal Reserve be asked not about the cost of quantitative easing, but about the impact of the policy instead. For years, central bankers have been reluctant to suggest that unconventional monetary policies even had costs. But while developed markets plunge ever deeper into uncharted financial territory as a result of central bank actions, the drawbacks and the limitations of such policies are finally becoming apparent. The negative effects will become even more obvious over time. This will come as asset price inflation — the main consequence of central bank policies — goes into reverse, robbing financial engineering of its efficacy and flattening the yield curve.

Suddenly, the success of central bankers in lifting financial asset prices through unconventional monetary policies seems to be coming to an end. Those policies did little for the real economy on the way up, as most companies engaged more in share buybacks than in investing in capacity, and economic growth in the US never broke through a range of 2% to 2.5%, falling under 1% in the fourth quarter. The impact on the real economy on the way down will be greater. The Bank of Japan’s embrace of negative rates, dovish coos from New York Fed Chairman William Dudley, and carefully worded statements from Mr Bernanke’s successor, Janet Yellen, last week spooked markets rather than soothed them. The fallout is already being felt in stock and credit markets, and in sectors from the banks to tech companies.

The extent to which quantitative easing is losing effectiveness can be seen best in the drop in the share prices of the private equity firms. In the past few years, it is possible to argue that no single group of investors has been as big a beneficiary of QE as these large alternative investment firms. They could finance their deals with cheap debt, sell down their holdings of portfolio companies in stock markets which kept rising, and mark up the value of their privately held portfolio companies on the basis of their listed peers. Now those perfect conditions are going into reverse. That’s why last week both Apollo Global Management and Carlyle announced that they were planning on some financial engineering by buying back their own shares for the first time ever. They may be too late.

“The share buyback boom has peaked,” notes Christopher Wood, strategist for the CLSA arm of Citic Securities, citing “the dramatic underperformance of the S&P 500 Share Buyback Index relative to the S&P 500 itself. The stock market has been ignoring the clear evidence of deteriorating margins and profitability, a form of deception encouraged by the share buybacks.” Meanwhile, Blackstone’s Steve Schwarzman spent much of his recent earnings call with his investors talking up the dividend yield (11% as of January 28, the day of the call) and value of his firm’s shares. “Right now you’re getting Blackstone on sale,” said the eternal salesman. We are in a world where the yield curve is flattening and there is little demand to borrow other than to engage in financial engineering. Banks’ inability to earn money in that world dominated headlines last week. But it will leave other kinds of financial institutions in even worse shape, especially insurers that sold guaranteed investment contracts. And savers will earn even less on their savings.

In an election year in the US, it seems unlikely that the Fed will return to its previous pattern of purchasing more securities, given the fact that such policies are partly responsible for deepening income inequality. It is even more risky for the Fed to adopt negative interest rates policy (NIRP) as so many other developed nations now have given that the impact on huge money market funds is unknown. “The US is not close to considering NIRP,” concluded JPMorgan economists in a report. “However, if recession risks were realised, the need for substantial additional policy support would likely push the Fed towards NIRP.” However, disconcertingly, the Fed’s latest stress test includes just that scenario, Mr Wood says. Meanwhile, JPMorgan late last week predicted that both the Bank of Japan and the ECB are likely to ease more in coming weeks. It is an odd world where the failure of unconventional monetary policies leads to more rather than less of the same. There will be worse to come.

Read more …

Worshipping idols.

• Markets Putting Faith in QE4? (WSJ)

Since the medieval church clamped down on the sale of indulgences, it has been hard to put a price on religious faith. Not so with central banks. The value of trust in the world’s leading policy makers is calculated second by second, and stood at about $1,209 an ounce on Monday. The gold price is far from a perfect measure of belief—or lack of it—in policy makers. But its 14% rise supports one popular explanation for this year’s tumbling markets: Investors have lost faith that the central bankers know what they are doing. The supporting evidence seems pretty convincing. The most obvious comes from moves in currencies and from banks, which suffer when they cannot pass on negative interest rates to most of their customers.

Currencies haven’t moved as expected. Negative rates ought to weaken a currency by making it less attractive to hold, one reason that central banks in the eurozone, Japan, Switzerland, Sweden and Denmark are so keen on them. But when the Bank of Japan surprised economists by cutting to negative rates for the first time at the end of January, the yen had just one weak day before strengthening back to be worth more than it was before the cut. Against the dollar, it is now worth 4% more than before the cut. Sweden faced the same problem last week, as its central bank, the Riksbank, cut its main policy rate more than expected to minus 0.5%. By the next morning, the krona was in fact stronger than before the action.

Both cases seem to show that investors fear negative rates more than they respect their power to stimulate. Part of this is down to the effect on the banking system, particularly in Europe. Banks haven’t been able to pass on negative rates to customers, hurting their margins even as bondholders worry that corporate defaults are set to rise. If central banks were trusted to boost the economy, higher demand for loans and fewer bad debts should amply offset negative rates’ effects on bank profits. Bank shares suggest otherwise. In Japan, bank shares fell more than 40% in three months, before Monday’s nearly 9% rally. This is their third-worst three-month drop since 1983, behind only the postbubble crash in the early 1990s and the 2008 Lehman Brothers panic.

Read more …

We don’t see nearly enough on Japanese banks. “..Japanese bank shares have slumped by as much as 30%..”

• BOJ Launches Negative Rates, Already Dubbed A Failure By Markets (Reuters)

The Bank of Japan’s negative interest rates came into effect on Tuesday in a radical plan already deemed a failure by financial markets, highlighting Tokyo’s lack of options to spur growth as global markets sputter. The central bank, which announced the shock decision on Jan. 29, will charge banks 0.1% for parking additional reserves with the BOJ to encourage banks to lend and prompt businesses and savers to spend and invest. While the announcement briefly drove down the yen and buoyed Japanese share prices, markets quickly went into reverse. “It’s getting clearer that Abenomics is a paper tiger,” said Seiya Nakajima, chief economist at Office Niwa, a consultancy, referring to Prime Minister Shinzo Abe’s policy mix of monetary easing, spending and reform.

“The impact of monetary easing is similar to currency intervention. The first time they do it, there’s a huge impact. But as they repeat it, the impact will wane,” said Nakajima. Though senior BOJ officials were at pains to say they had calibrated only a minor impact on Japanese banks, their stock prices plunged, contributing to a global market sell-off, particularly in financial shares. The problem was partly bad timing, as global markets were already in a tailspin over concerns about China’s slowdown, U.S. rate hikes and tumbling oil prices. But the reaction leaves BOJ Governor Haruhiko Kuroda’s assertion that his policy is having its intended effects looking increasingly threadbare. “It seems as though the BOJ’s action triggered the market moves,” said Yoshinori Shigemi, global market strategist at JPMorgan Asset Management. “But a better explanation would be that concerns elsewhere overwhelmed the BOJ action.”

In the 11 days since the BOJ board’s announcement, the benchmark Nikkei index has fallen 8.5%, despite a sharp rebound on Monday, while the yen has climbed 6.5% against the dollar. Japanese bank shares have slumped by as much as 30% as they are unlikely to pass on negative rates to savers, who already get negligible interest on their deposits but would baulk at paying to save. Negative rates could push down bank operating profits by 8-15%, Standard and Poor’s said. The 10-year Japanese government bond yield nitially fell below zero on the easing – a first among Group of Seven economies. But it has recovered from minus 0.035% last week to 0.090% above zero, with Japanese markets becoming more unstable as investors are at a loss on how to reckon fair value.

Read more …

“This is the equivalent of drinking whiskey and taking aspirin at the same time..”

• China’s Problems ‘Just Gargantuan’ (CNBC)

Despite China’s yuan hitting its highest level this year against the U.S. dollar Monday, the country’s fundamental problems are “just gargantuan”, Stewart Paterson, portfolio manager at Tiburon Partners, told CNBC. “They (the Chinese) have deflation, they have a slowing economy,” said Paterson, “To say there is no downward pressure on the RMB (Renminbi) or no fundamental reason for it to weaken, I think is very disingenuous and symptomatic of the fact that the Chinese population themselves are starting to lose confidence in their own currency.” The Chinese authorities are bolstering the yuan, in part, by selling off chunks of their foreign currency reserves and dumping dollars in the market. Nonetheless, the money stock in China is growing about twice the pace of its economy, at about 14% year-on-year.

“If using your foreign exchange reserve is just a way of tightening monetary policy, as you support your own exchange rate… [then] the POBC (People’s Bank of China) are easing monetary policy by handing money out to the monetary market,” said Paterson. “This is the equivalent of drinking whiskey and taking aspirin at the same time… what you’re doing with one hand is counteracting the effects of what you’re doing with the other.” Paterson believes the yuan could devalue by a further 35%. However, economist George Magnus does not believe China will devalue the yuan in ways “that people think it will be forced or choose to.” “Instead, and if pushed by the capital flight that’s bleeding its reserves, China’s basic instinct will be to carry on tightening capital controls, and punishing those that try to breach them,” he wrote in a note on Friday.

And what is happening in China is having repercussions across the world, not least Europe, said Paterson. “If a country could just print as much money as it wanted, and at the same time, preserve the external purchasing power of its currency, clearly there would be no poverty in the world…we would have all done this,” he said. “The failure of Europe to generate nominal GDP (gross domestic product) growth is why the leverage is so damaging. The credit risk is rising in the risk-free sovereigns, which the banks are all up to their eyeballs in … and so a deflationary shock from China that makes nominal GDP growth in Europe an ever more distance prospect , of course that manifests itself in real stress in the European financial system,” he said.

Read more …

Diminishing returns. [That’s half a QE3 in one month]

• China Created A Record Half A Trillion Dollars Of Debt In January (ZH)

Yes, you read that right. Amid a tumbling stock market, plunging trade data, weakening Yuan, and soaring volatility, China’s aggregate debt (so-called total social financing) rose a stunning CNY3.42 trillion (or an even more insane-sounding $520 billion) in January alone. In fact, since October, China has added over 1 trillion dollars of credit… and has nothing but margin calls, ghost-er cities, and over-supplied commodity-warehouses to show for it… oh and even-record-er debt-to-GDP ratio. This is what the unprecedented addition of half-a-trillion dollars in one month looks like – Hyman Minsky called, he wants his chart back. [That’s half a QE3 in one month]

In the process of this gargantuan debt creation, China has smashed its recently record debt/GDP of 346% pushing it to even more ridiculous levels. Why is China doing this? Because as we showed three years ago, China needs ever greater stimuli to achieve the same effect: This is what else we said back in April 2013 which by now seems painfully (and plainfully) obvious: “What should become obvious is that in order to maintain its unprecedented (if declining) growth rate, China has to inject ever greater amounts of credit into its economy, amounts which will push its total credit pile ever higher into the stratosphere, until one day it pulls a Europe and finds itself in a situation where there are no further encumberable assets (for secured loans), and where ever-deteriorating cash flows are no longer sufficient to satisfy the interest payments on unsecured debt, leading to what the Chinese government has been desperate to avoid: mass corporate defaults.”

This could be the end as the last bubble standing (in China corporate debt) has begun to burst amid the over-supply of credit. What happens next?

Read more …

A) They’re lowballing. B) It’s not much use to look at China NPL without including shadow banks.

• China’s Bad Loans Rise to Highest in a Decade (BBG)

Soured loans at Chinese commercial banks rose to the highest level since June 2006 as the nation’s economic expansion slowed to the weakest pace in a quarter century. Nonperforming loans rose 7% from September to 1.27 trillion yuan ($196 billion) by December, the slowest quarterly increase in two years, data from the China Banking Regulatory Commission showed Monday. Including “special-mention” loans, where future repayment is at risk but yet to become nonperforming, the industry’s total troubled loans swelled to 4.2 trillion yuan, representing 5.46% of total advances. Concern over borrowers’ ability to service debt has weighed on Chinese lenders, with shares of the nation’s four largest banks trading at valuations at least 35% below a gauge of their emerging-nation peers. China’s economy grew last year at its slowest pace since 1990.

“The slower quarterly increase in NPLs are likely to be results of stepped-up efforts by banks to recollect loans, more aggressive write-offs, and some relaxation in their bad-loan recognition standards,” said Chen Shujin at DBS Vickers Hong Kong. “We don’t expect to see any turnaround of asset quality until the end of this year.” Separately, the People’s Bank of China reported Tuesday that new credit surged in January to a record 3.42 trillion yuan, almost double the amount in December and exceeding the median forecast of 2.2 trillion yuan in a Bloomberg survey of analysts. The increase was linked to a seasonal binge as banks front-loaded lending and Chinese borrowers refinanced foreign-denominated debt. The CBRC data comes amid speculation that soured loans could be much larger than indicated by official data.

Kyle Bass, a hedge fund manager who successfully bet against mortgages during the subprime collapse, said earlier this month that the Chinese banking system may see losses of more than four times those suffered by U.S. lenders during the 2008 credit crisis. That claim has been disputed by DBS’s Chen and analysts at China International Capital Corp and Macquarie. Should the Chinese banking system lose 10% of its assets because of nonperforming loans, the nation’s banks will see about $3.5 trillion in their equity vanish, Bass, the founder of Dallas-based Hayman Capital Management, wrote this month in a letter to investors obtained by Bloomberg. Larry Hu, a China economist at Macquarie in Hong Kong, said in a research note on Monday that Bass’s estimate could be too large as it implied a true bad-loan ratio for China banks at 28 to 30%.

Read more …

Scapegoats are easy to find in a central control system. But the system at the same time always points upward when it comes to blame.

• Chinese Premier Faults Regulators’ Handling of Stocks, Yuan Rout (BBG)

Chinese Premier Li Keqiang took the nation’s financial regulators to task for the way they handled a rout in stocks and the yuan, making him the most senior official to date to fault the response to the turmoil. Regulators didn’t respond actively to declines and some even have management problems, Li said in a State Council meeting on Monday, according to a Beijing News report carried on the government’s website. Li didn’t specify the regulators at fault and defended the decision to intervene in equity and foreign-exchange markets as necessary to head off systemic risks and “defuse some bombs.” “Looking back, the major responsible departments took inadequate actions and had internal management issues,” Li said.

The China Securities Regulatory Commission has drawn criticism recently over a series of steps such as as the circuit-breaker system that had to be rescinded just four days after it was introduced in January. The CSRC’s chairman, Xiao Gang, blamed factors including incomplete trading rules and an inappropriate regulatory system, and said officials will learn from their mistakes. The benchmark Shanghai Composite Index has tumbled more than 40% since a June high even after state funds spent billions of dollars to prop up equities. The government also tightened capital controls and spent almost $300 billion of its foreign exchange reserves in the last three months to prop up the exchange rate. The yuan posted its biggest advance in more than a decade on Monday in Shanghai after central bank Governor Zhou Xiaochuan voiced his support for the currency.

Read more …

Beijing tries to impress by showing it can raise the yuan. We are not impressed.

• China Favors Flexibility in Managing Yuan (WSJ)

China’s yuan had its biggest jump against the dollar in more than a decade on Monday, as Beijing keeps markets off guard with a shifting approach to managing its currency. The central bank is keeping its options open, swinging between its pledge to attach the yuan’s value to the currencies of its major trading partners and, when that works against it, repegging it to the dollar. Since mid-January, the People’s Bank of China has quietly rehitched the yuan’s value to a weakening dollar, despite vowing just a month earlier to use multiple currencies as the yuan’s reference points. For investors, China’s opportunistic approach sows confusion, which has led to volatile trading. On Monday, the central bank suddenly guided the yuan sharply higher.

Chinese officials and advisers close to the central bank said the move was aimed at shoring up dwindling confidence in the Chinese currency, also known as the renminbi, that has led businesses and individuals to rush to move capital out of the country. Analysts estimate China’s capital outflows ranged between $500 billion and $1 trillion last year. “The central bank wants to be flexible,” one of the officials said. “The goal is to reference the renminbi, instead of strictly pegging it, to the basket.” In published remarks over the weekend, China’s central-bank governor, Zhou Xiaochuan, gave a hint of Beijing’s desire to be opportunistic in remaking its exchange-rate regime. Speaking to Caixin, a prominent Chinese magazine, Mr. Zhou said China would proceed with the reform of referencing the yuan to the currency basket when there is “a window” of opportunity and will be “pragmatic and patient” when there is not.

“The direction is clear, but the path to reform won’t be a straight line,” Mr. Zhou said. Returning to what some analysts call a quasi-dollar peg has helped Beijing at a time when the dollar has weakened sharply against the yen and the euro as expectations for interest-rate increases in the U.S. fade. That has allowed the yuan to ride down with the dollar and discreetly depreciate against the currencies of China’s trading partners. “Things right now are working in the central bank’s favor,” said David Loevinger, a managing director and emerging-market sovereign analyst at TCW Group, with $180.7 billion of assets under management. “For the moment, that’s taken a lot of the pressure from the Chinese yuan. There’s less need for them to have the yuan depreciate against the dollar.” But it isn’t clear how long the favorable winds will blow for China. Monday’s currency movements gave an indication of the complexity of China’s gambit.

Read more …

We are not impressed. “The PBOC might like to flex its muscles by pegging the yuan higher but this has considerable costs if it continues to use up its reserves in the process.”

• Capital Flight Signals Investors Still Bracing For China To Devalue Yuan (MW)

While China’s currency had a strong jump after the lunar new year holidays, it is moves by capital, not moves by policy makers, that investors should pay attention to. At the weekend People’s Bank of China Gov. Zhou Xiaochuan ended his silence to make his first comments in a number of months, reiterating that there was no intention to devalue the yuan, while also ruling out imposing capital controls. He added that the PBOC would be cautious when using resources to fight international speculators, while also saying he supported a more flexible yuan. A slide in the dollar last week likely contributed to this more sanguine tone, with the central bank moving to set the yuan almost 1% stronger at 6.5118 to the dollar on Monday.

But any suggestion the troubled yuan is now at a turning point still looks decidely premature. For one thing, no central banker would decisively flag in advance an intention to move off an effective currency peg as this would be an open invitation to speculators. Indeed, some have commented that this was exactly the problem with the PBOC’s surprise and poorly explained devaluation last August. Further, China is still burning through its foreign reserves at an alarming pace to support the yuan after they fell another $99.47 billion to US$3.23 trillion in January. Hedge funds that have been targeting the yuan are betting that Beijing will eventually tire of intervention if currency outflows persist as it contracts the money supply and piles more pain on the economy.

The PBOC might like to flex its muscles by pegging the yuan higher but this has considerable costs if it continues to use up its reserves in the process. In a recent report, BMI Research explained that using reserves to backstop the onshore yuan market contradicts the policy goal of supporting economic growth and easing credit conditions. The key pain point is the extremely large stock of debt, which is becoming increasingly difficult for local governments and corporates to service as economic growth slows. This underpins their view that the central bank would eventually have to relent and allow the yuan to weaken. Societe Generale is also forecasting a weaker yuan and in a recent report looks at what will happen if Beijing succumbs to a one-off devaluation or moves to a free float by the end of the year.

Read more …

Anything close to China will see fallout.

• A Massive Banking Crisis Is Brewing In Singapore, Says Zulauf (SBR)

The three biggest banks are losing capital. A crisis of staggering proportions is looming in China, and tiny Singapore will be caught right in the middle of the storm once the disaster finally erupts. Speaking at the annual Barron’s roundtable, Swiss billionaire investor Felix Zulauf warned that Singapore’s largest banks are at risk of massive capital outflows if the Chinese economy experiences a hard landing, which he expects will happen this year. “We are in a down cycle that will end with crisis and calamity. China in today’s cycle is what US housing was during the financial crisis in 2008,” Zulauf warned. Zulauf warned that capital outflows in China will continue, prompting regulators to devalue the yuan by as much as 15% to 20% within the year.

When this happens, Asian economies which are heavily dependent on China—particularly Singapore—will suffer because Chinese corporates will cut their imports even more, while indebted Chinese companies will be placed at greater risk of default. “I expect the situation the deteriorate to a point where we will witness a banking crisis in Asia that will hit Singapore and Hong Kong particularly hard,” Zulauf said. “It is conceivable that Singapore, which has attracted a lot of foreign capital over the years because of its image as a strong-currency state, will be extremely exposed to the situation in China. Singapore’s banking-sector loans have grown dramatically in the past five or six years. Singapore is now losing capital, which means the banking industry is losing deposits,” Zulauf said.

He said that such a situation will cause carry trades to go awry, which will result in steep losses for heavily-leveraged traders. “I mentioned the potential for a banking crisis in Singapore. I don’t recommend shorting Singapore bank stocks, but rather the EWS, or iShares MSCI Singapore ETF. In this case, an investor will benefit from both declining local stock prices and a decline in the Singapore dollar against the U.S. dollar,” said the report.

Read more …

“You can’t just miss coupon payments. It’s called insolvency.”

• Keiser: Deutsche Bank ‘Technically Insolvent’, Running A ‘Ponzi Scheme’ (RT)

Max Keiser hit out against Deutsche Bank in the latest episode of his RT program Keiser Report, saying the bank was “technically insolvent” despite assurances from German Finance Minister Wolfgang Schaeuble that he had “no concerns” over his country’s biggest bank. Deutsche Bank shares are down 40% since the beginning of the year, falling below their price at the time of the 2008 financial crisis. The bank suffered record losses of €6.8 billion in 2015. With a balance sheet now eclipsing JP Morgan’s, Keiser warned that the bank will sooner or later have to admit to insolvency and say “we need either a huge bailout or we gotta close up shop.” However, German Finance Minister Wolfgang Schaeuble dismissed concerns over Germany’s biggest lender, telling Bloomberg he was not worried about its future.

Deutsche Bank CEO John Cryan also played down the concerns in a published letter to staff on February 9, describing the bank as “absolutely rock-solid” and “strong”. “On Monday, we took advantage of this strength to reassure the market of our capacity and commitment to pay coupons to investors who hold our Additional Tier 1 capital,” Cryan wrote. “This type of instrument has been the subject of recent market concern. The market also expressed some concern about the adequacy of our legal provisions but I don’t share that concern. We will almost certainly have to add to our legal provisions this year but this is already accounted for in our financial plan.” The bank’s contingent convertible (CoCo) bonds also plunged in value this year. CoCo bonds are designed to be converted to equity when the bank gets into trouble.

They have no maturity date and come with no promise to investors that they will get their money back. Coupon payments on the bond are contingent on the bank’s ability to keep its capital above certain thresholds. If the bank does not make a coupon payment, investors cannot call for a default. Deutsche Bank said last week that they would likely be able to make its coupon payment for 2016, after telling investors last month that it couldn’t make its 2015 payments. Keiser described the move as a ponzi scheme saying, “You can’t just miss coupon payments. It’s called insolvency.”

Read more …

“..European institutions are girding yet again for another round of restructuring. [..] So much so that analysts in London call them “building sites..”

• The Never-Ending Story: Europe’s Banks Face a Frightening Future (BBG)

If you had to pick the moment when European banking reached the point of no return, which would you choose? The July day in 2012 when Bob Diamond resigned as Barclays’s chief executive officer amid the Libor rigging scandal? Or the fall morning later that year when UBS announced it was pulling out of fixed income and firing 10,000 employees? How about Sept. 12, 2010, when Basel III’s raft of costly capital requirements started upending the economics of global finance? All signature events, to be sure. But try May 21, 2015. That’s when Deutsche Bank stockholders filed into the dome-shaped Festhalle arena in Frankfurt to take part in one of the most venerated and, let’s be honest, boring rituals in corporate life: casting a vote on management’s strategy and performance.

It wasn’t dull this time. Almost 40% of the bank’s investors gave co-CEOs Anshu Jain and Jürgen Fitschen a big thumbs down. While winning six out of 10 votes is a landslide in politics, it’s a crushing blow at a publicly traded company. By the end of June, Jain was out and Fitschen had agreed to leave the company by May of this year. Investors are running out of patience with European bank chieftains, and no wonder. Since the fall of Lehman Brothers in September 2008, eight of Europe’s biggest banks have announced layoffs adding up to about 100,000 employees, paid $63 billion in legal penalties, and lost $420 billion in market value. In 2015, Deutsche Bank lost a record €6.8 billion ($7.6 billion).

In mid-February the industry suffered an epic selloff as subzero interest rates, China’s slowdown, the oil crash, and looming regulatory and litigation costs triggered an outbreak of fear not seen since the fall of 2008. Just last year new CEOs took over at Barclays, Credit Suisse, Deutsche Bank, and Standard Chartered. Now they have to find a way to prosper in a marketplace that’s being reshaped simultaneously by strict new capital regulations and myriad financial technology startups that don’t have to abide by them. While American banks appear to have turned the corner since that gut-churning autumn nearly eight years ago, European institutions are girding yet again for another round of restructuring.

So much so that analysts in London call them “building sites,” Bloomberg Markets magazine reports in its forthcoming issue. Credit Suisse’s new CEO, Tidjane Thiam, is “right-sizing” the investment bank and pushing for a 61% jump in pretax income from his international wealth management unit over the next two years. At Barclays, Jes Staley wasted no time cutting 1,200 investment banking jobs and closing offices in Asia and Australia after taking charge in December. Meanwhile, John Cryan, the British executive who replaced the India-born Jain, is pursuing an unprecedented overhaul of Deutsche Bank’s entire information technology infrastructure to shore up shaky risk-management systems.

Read more …

Creatively broke.

• Low Oil Prices Claim New Victim, an Offshore Driller From Texas (NY Times)

Yet another oil company has filed for bankruptcy, as the energy industry and its lenders brace for a prolonged slump. Paragon Offshore, which operates offshore drilling rigs from the Gulf of Mexico to the North Sea, filed for Chapter 11 bankruptcy protection Sunday evening, the latest filing in a painful shakeout buffeting the oil industry. Over the last 16 months, about 60 oil and gas companies have filed for bankruptcy as commodity prices slide, and that figure is expected to double in the coming months if prices remain low. All told, analysts say as much as a third of the sprawling oil and gas industry in the United States could be consolidated as a result of the downturn. Paragon, based in Houston, was one of the more fortunate companies that has contemplated bankruptcy.

The company was able to negotiate a deal with its lenders — a mix of bondholders and banks — ahead of its bankruptcy filing. The so-called prepackaged bankruptcy agreement sealed last week allowed Paragon to cut its $2.7 billion of debt by about $1.1 billion and to keep operating. For other energy companies, the swift drop in oil prices from $100 a barrel in late 2014 to just around $30 last week has drained cash reserves so quickly they have not been able to agree on an out-of-court debt restructuring, which is likely to lead to a series of drawn-out and messy bankruptcies. Unlike other recent oil restructurings, which have all but wiped out equity holders, Paragon’s existing equity investors will retain 65% of the company.

Paragon, which traces its roots to the Great Depression and now employs about 2,900 people around the world, had not run out of cash when it filed, but company executives determined that it could not hold out forever, said Lee M. Ahlstrom, Paragon’s senior vice president for investor relations, strategy and planning. Paragon’s biggest customers for its drilling services, including the Mexican oil giant Pemex and Petrobras of Brazil, have been cutting back on new projects as the global supply remains high. In the shale oil fields of the United States, there are very few wells that are profitable to drill at current prices. With large producers like Saudi Arabia showing no signs of cutting back production and the global economy slowing, oil executives and investors expect the market to remain in turmoil until 2017.

Read more …

This is going to hurt. NZD=0.66USD

• Sellers Of Auckland Houses Want $100,000 More Than They Did Last Year (Stuff)

Auckland house-sellers now want more than $100,000 more for their houses than they did in January last year. Trade Me Property has released its data for the month, showing the national average asking price across the country fell to $541,900 in January, down 2% from December. But the average was still up 9% on the same time in 2015. The Auckland average asking price dropped 0.5%, to $801,400 – up more than $107,000 or 15.4% on January 2015. Head of Trade Me Property Nigel Jeffries said that over the past 18 months the average asking price of a property in Auckland had surged up in “an almost unbroken run” from $641,500 to $801,400.

“We’ve seen a staggering $160,000 added to the average asking price of a house in Auckland over the past year and half, which is an average rise of over $8,500 per month. And if we look back to January 2011, we’ve seen the average asking price up 60% or a shade below $300,000.” The Bay of Plenty continued to power ahead with average asking prices rising 12.2% over the past 12 months, edging closer to Auckland’s 15.4% increase. “While Auckland has started to take its foot off the gas, the Bay of Plenty remains solidly in overdrive. Outside these two, no other region is showing a double-digit rise. In the past 12 months the asking price in the Bay of Plenty has risen by $55,300 and pushed the five-year increase beyond 30% for the first time,” Jeffries said.

Read more …

“.. it appears for now that America is fixing to elect either a primal screamer or a road-tested grifter..”

• Repricing Reality (Jim Kunstler)

It ought to be a foregone conclusion that Mr. Obama’s replacement starting January 20, 2017 will preside over conditions of disorder in everyday life and economy never seen before. For the supposedly thinking class in America, the end of reality-optional politics will come as the surprise of their lives. Where has that hypothetical thinking class been, by the way, the past eight years? Don’t look for it in what used to be called “the newspapers.” The New York Times has become so reality-averse that the editors traded in their blue pencils for Federal Reserve cheerleader pompoms after the Lehman incident of 2008. Every information-dispensing organ has followed their lede: The Recovery Continues! It’s a sturdy plank for promoting the impaired asset known as Hillary.

Don’t look for the thinking class in the universities. They’ve surrendered their traditional duties to a new hybrid persecution campaign that is equal parts Mao Zedong, the Witches of Loudon, and the Asylum at Charenton. For instance the President of Princeton, Mr. Eisgruber, was confronted with a list of demands that included 1) erasure of arch-segregationist Woodrow Wilson’s name from everything on campus, and 2) creation of a new all-black (i.e. segregated) student center. He didn’t blink. Note: nobody in the media asked him about this apparent contradiction. That’s how we roll these days. Don’t look for the thinking class in business. The C-suites are jammed with people still busy buying back stock in their own companies at outlandish prices with borrowed money. Why?

To artificially boost share price and thus their salaries and bonuses. Does it do anything for the fitness of enterprise? No, in fact it makes future failure more likely. Why is their no governance of their insane behavior? Because they’ve also bought and paid for boards of directors composed of a rotating cast of praetorian shills, with fresh recruits entering the scene weekly through the fabled “revolving door” between business and government regulators. Oh, and then there’s government. Anyone viewing the boasting-and-defamation contests that the cable TV networks call “debates” knows that these spectacles are based on the opposite of thinking. They are not only reality-optional, they’re thought-optional. Hence, it appears for now that America is fixing to elect either a primal screamer or a road-tested grifter to preside over the epochal collapse of our hobbled, exhausted, way of life.

Read more …

Bit late perhaps?

• German Minister Asks For Half A Billion To Create Jobs For Refugees (EA)

Federal Minister of Labour and Social Affairs Andrea Nahles has called for €450 million to help integrate refugees into the labour market. EurActiv Germany reports. Nahles has asked for nearly half a billion euros from Minister of Finance Wolfgang Schäuble in order to provide better access to jobs, according to German media. Nahles told the Funke Mediengruppe that the current budget is not sufficient. In order to create 100,000 new jobs for new arrivals to Germany, she needs at least €450 million extra per year. “So far, people have had to sit around doing nothing for 12 months at a time,” she said. “This creates tension for everyone. We must act as quickly as possible, but I can only do this with the support of the Finance Minister.” However, Nahles warned against taking the money from the long-term unemployed, as this would “stoke the fires of fear” and create even more tension.

Negotiations with the Finance Ministry have started already. Nahles expects the number of recipients of unemployment benefits, under the so-called Hartz IV system, to rise to 270,000 this year. Of these, about 200,000 are fit for work. The arrival of over 1 million refugees last year has put a strain on nearly every aspect of German society, with the health, education and employment sectors all struggling to cope with the influx of people. Germany’s situation is paralleled In Turkey, where legislation has been passed to allow Syrians to work legally in the country. Turkish Ambassador Selim Yenel told EurActiv in an interview that this measure will have a knock-on effect for education, where Syrian teachers will now be able to work legally and help educate the significant number of Syrian children that have arrived in the country.

Read more …

How bad is this going to get for Greece?

• Greek Minister: Hungary Has Sent Nothing, Not Even A Blanket (EA)

Athens blamed Hungary for not contributing to the country’s efforts to tackle the refugee crisis and for its “political decision” to help Macedonia build a fence at the Greek border. In an interview with Hungary’s Népszabadsàg, Greece’s Alternate Foreign Minister for European Affairs, Nikos Xydakis, wondered why Budapest wanted to tell others what to do with the refugee crisis. “We have never criticized the policy of the Hungarian Premier, Victor Orbán,” Xydakis said. The leaders of the ‘Visegrad Four’ (also known as V4) are meeting today in Prague for a mini-summit ahead of the 18-19 February EU Council meeting. The Visegrad leaders seek a possible “plan B” in case of a collapse of the Schengen system and in particular an exit of Greece from the group. In particular, they want to make sure that the borders between Bulgaria and Greece and Macedonia and Greece are sealed and effectively stop the migration flows.

Earlier this month, the Greek government said that the Visegrad Four were pressing Athens not to abide by the international rules, and to stop rescuing refugees at sea. Athens, also, noted that the Visegrad leaders urged the EU to shut the Greek borders. “It’s weird that from Budapest – which is attacking Athens – we have not received a single blanket or a tent within the EU Civil Protection Mechanism until the end of January,” the minister said. The Civil Protection Mechanism was established in 2001 as a means of fostering cooperation among national civil protection authorities across Europe. The Greek official stressed that other EU member states helped and had already provided equipment to take care of the refugees. “Lithuania -which is quite far from the Mediterranean zone crisis, sent two patrol ships,” Xydakis said.

Read more …

“It doesn’t matter if it’s your job. It breaks your heart.”

• Unknown Dead Fill Lesbos Cemetery For Refugees Drowned At Sea (Reuters)

She drowned trying to reach Europe, but her headless body was never identified. Her tombstone will bear no name. Like others buried beside her in an olive grove on the Greek island of Lesbos, the marble plaque on her unmarked grave will proclaim the victim “Unknown”. Her epitaph an identification number, the date she washed ashore, and her presumed age: one. Sixty-four earthen graves have been dug in this land plot for refugees and migrants who drowned crossing the Aegean Sea trying to reach Europe. Just 27 of those are named. The others state plainly: “Unknown Man, Aged 35, No 221, 19/11/2015;” “Unknown Boy, Aged 7, No 40, 19/11/2015;” “Unknown Boy, Aged 12, No 171, 19/11/2015.”

[..] In 2015, the deadliest year for migrants and refugees crossing the Mediterranean, more than 3,700 people are known to have drowned or gone missing, the International Organization for Migration says. The actual number is believed to be higher. Hundreds have drowned in Greece since arrivals surged last summer. So many, in fact, that the section of one Lesbos cemetery designated for refugees and migrants has long run out of space. Locals conclude that entire families have drowned in the same shipwreck, leaving no survivors to identify the victims. They recall bodies found severely decomposed after days at sea, or dismembered from crashing against the rocks of the island’s long coastline. “It doesn’t feel right, seeing a child of unknown identity, an unknown child, a child of ‘roughly this age’,” said Alekos Karagiorgis, a caretaker who has transported hundreds of corpses from beaches across the island to the morgue since summer. “It doesn’t matter if it’s your job. It breaks your heart.”

[..] In October, following a nighttime shipwreck from which more than 200 were rescued but dozens died, the St. Panteleimon cemetery ran out of space to bury the dead and the island’s morgue had to bring in a container to keep the bodies. That prompted local authorities to set aside a plot of land in one village for burials. There Mustafa Dawa, a boyish-looking 30-year-old from Egypt in Greece since his 20s, has taken on the unofficial role of washing, shrouding and burying the dead, their heads faced towards Mecca. “I did 57 funerals in seven days. In one day I did 11,” he said, recalling spending a few minutes crouched in the grave of the headless child, weighed down by emotion. Dawa says it’s the least he can do. “I can’t stop the war there, I can’t make them cross (to Europe) legally. All I can do is bury them.”

Read more …

Feb 152016
 
 February 15, 2016  Posted by at 9:05 am Finance Tagged with: , , , , , , , , ,  8 Responses »


John M. Fox Garcia Grande newsstand, New York 1946

• Japan’s Economy Shrinks 1.4% As Abenomics Is Blown Off Course (Guardian)
• China Imports Plunge -18.8% YoY In January, Exports Fall -11.2% (FT)
• Yuan Rises Most Since 2005 as PBOC Voices Support, Raises Fixing (BBG)
• PBoC Governor Zhou Breaks Long Silence (BBG)
• Chinese Start to Lose Confidence in Their Currency (NY Times)
• China Markets Brace for Wild Swings in Year of the Monkey (WSJ)
• Selloff Plus A Market Holiday Make China Stocks Look Even More Expensive (BBG)
• Hong Kong Land Price Plunges Nearly 70% in Government Tender (BBG)
• Pakistan Default Risk Surges as $50 Billion Debt Bill Coming Due (BBG)
• ECB In Talks With Italy Over Buying Bundles Of Bad Loans (Reuters)
• Italy’s Banking Crisis Spirals Elegantly out of Control (WS)
• Nuclear Fuel Storage in South Australia Seen as Economic Boon (BBG)
• Oil Resumes Drop as Iran Loads Europe Cargo (BBG)
• Condensate Vs Crude Oil: What’s Actually in Those Storage Tanks? (Westexas)
• Renewables: The Next Fracking? (JMG)

So Nikkei up 7%, more mad stimulus expected.

• Japan’s Economy Shrinks 1.4% As Abenomics Is Blown Off Course (Guardian)

Japan’s economy shrank at an annualised rate of 1.4% in the last quarter of 2015, new figures showed on Monday, dealing a further blow to attempts by the prime minister, Shinzo Abe, to lift the country out of stagnation. Last quarter’s contraction in the world’s third largest economy was bigger than the 1.2% decline that had been forecast, as slow exports to emerging markets failed to pick up the slack created by weak demand at home. The economy shrank 0.4% in October-December from the previous quarter, according to cabinet office figures. Slower exports and weak domestic demand were largely to blame for the contraction – a sign that Abe’s attempts to boost spending is failing to deliver.

Private consumption, the driving force behind 60% of GDP, slumped by 0.8% between October and December last year, a bigger fall than the median market forecast of 0.6%. Some analysts, though, expect domestic spending to pick up ahead of a planned rise on the consumption (sales) tax, from 8% to 10%, in April 2017. “However, this should be short-lived, as activity will almost certainly slump once the tax has been raised,” said Marcel Thieliant of Capital Economics. “The upshot is that the Bank of Japan still has plenty of work to do to boost price pressures.” The Nikkei benchmark index opened sharply higher on Monday, gaining more than 3% off the back of gains on Wall Street and in Europe on Friday, as well as encouraging US retail sales figures.

Read more …

Not much in imports left after 15 months in a row. Do note difference between dollar- and yuan terms.

• China Imports Plunge -18.8% YoY In January, Exports Fall -11.2% (FT)

China’s exports and imports suffered larger-than-expected drops in the first month of this year in both renminbi- and dollar-denominated terms. Exports fell 6.6% year-on-year in January to Rmb1.14tn, following a 2.3% gain in December. Economists expected a gain of 3.6%. It was the biggest fall in exports since an 8.9% drop in July last year. The drop was even more pronounced measured in US dollars, with exports crashing 11.2% year-on-year last month to $177.48bn. That was from a 1.4% drop in December, and versus expectations for a 1.8% slide. It was the biggest drop since a 15% fall in March last year. The import side of the equation fared worse in both renminbi- and dollar-terms. Shipments to China cratered by 14.4% year-on-year to Rmb737.5bn in January. That’s from a 4% drop in December, and versus expectations for a 1.8% rise.

In dollar terms, imports plunged 18.8% last month to $114.19, from a 7.6% drop in January and versus an expected drop of 3.6%. This was the biggest monthly drop in imports since last September and also means shipments have contracted year-on-year for the past 15 months straight. The general weakness in the renminbi, which fell 1.3% in January and had weakened by 2.2% in the final quarter of 2015, is likely playing a part, by making overseas goods more expensive. However, exports have yet to receive a boost from the currency’s depreciation. China’s trade surplus grew to Rmb496.2bn last month from Rmb382.1bn in December. Economists expected it to inch higher to Rmb389bn. In dollar terms, China’s trade surplus rose to $63.29bn from $60.09 in December and versus expectations of $60.6bn.

Read more …

Whatever it takes revisited.

• Yuan Rises Most Since 2005 as PBOC Voices Support, Raises Fixing (BBG)

China’s yuan surged by the most in more than a decade, catching up with dollar declines during a week-long holiday, after the central bank chief voiced support for the exchange rate and set its fixing at a one-month high. The currency advanced 0.9%, the most since the nation scrapped a peg to the dollar in July 2005, to 6.5170 a dollar as of 10:50 a.m. in Shanghai. The offshore yuan fell 0.16% to 6.5186 to almost match the onshore rate, compared with a 1% premium last week when mainland Chinese markets were shut for the Lunar New Year holidays. The People’s Bank of China on Monday raised its daily fixing against the greenback, which restricts onshore moves to a maximum 2% on either side, by 0.3%, the most since November, to 6.5118. A gauge of dollar strength declined 0.8% last week, while the yen rose 3% and the euro advanced 0.9%.

China’s balance of payments position is good, capital outflows are normal and the exchange rate is basically stable against a basket of currencies, PBOC Governor Zhou Xiaochuan said in an interview published Saturday in Caixin magazine. The nation’s foreign-exchange reserves shrank by $99.5 billion in January, the second-biggest decline on record, as the central bank sold dollars to fight off yuan depreciation pressure. An estimated $1 trillion of capital left China last year. “In the near term, the stronger fixing and Zhou’s comments reflect the PBOC’s consistent view of stabilizing the yuan,” said Ken Cheung at Mizuho. “Containing yuan depreciation expectations and capital outflows remain top-priority tasks. Mild depreciation could be allowed, but that would be done only after stabilizing depreciation expectations.”

Read more …

What is this, some sort of reverse psychology? By now nobody trusts him anymore.

• PBoC Governor Zhou Breaks Long Silence (BBG)

China’s central bank has stepped up efforts to restore stability to the nation’s currency and economy, with Governor Zhou Xiaochuan breaking his long silence to argue there’s no basis for continued yuan depreciation. The nation’s balance of payments is good, capital outflows are normal and the exchange rate is basically stable against a basket of currencies, Zhou said in an interview published Saturday in Caixin magazine. That’s an escalation in verbal support after such comments have been left in recent months to deputies and the central bank research department’s chief economist. Zhou dismissed speculation that China plans to tighten capital controls and said there’s no need to worry about a short-term decline in foreign-exchange reserves. The country has ample holdings for payments and to defend stability, he said.

“He’s desperately trying to make sure that all of his work in the past few years on capital liberalization does not go to waste,” said Victor Shih, a professor at the University of California at San Diego who studies China’s politics and finance. “He’s trying hard to instill investor confidence in the renminbi so that the Chinese government does not have to resort to the extreme measure of unwinding all of the progress on offshore renminbi in the past few years.” The comments come as Chinese financial markets prepare to reopen Monday after the week-long Lunar New Year holiday. The weakening exchange rate and declining Chinese share markets have fueled global turmoil and helped send world stocks to their lowest levels in more than two years. The PBoC set the daily fixing against the dollar, which restricts onshore moves to a maximum 2% on either side, 0.3% higher at 6.5118, the strongest since Jan. 4. The Shanghai Composite Index dropped 2.3% as of 9:39 a.m. local time.

Lost amid the angst over China’s stocks, currency and sliding foreign exchange reserves is the flush liquidity situation at home. The People’s Bank of China has been putting its money where its mouth is, pumping cash into the financial system to offset record capital outflows amid fears the yuan could weaken further. Data that could come as soon as Monday is expected to show China’s broadest measure of new credit surged in January on a seasonal uptick in lending, and as companies borrowed to pay off foreign debt. Aggregate financing likely grew 2.2 trillion yuan ($335 billion), according to the median forecast of a Bloomberg survey of economists. [..] Even as foreign exchange reserves have declined since mid 2014 – to a four-year low of $3.23 trillion in January – M1 money supply has continued to rise.

Read more …

No-one has a clue where it’ll be in a week, a month.

• Chinese Start to Lose Confidence in Their Currency (NY Times)

As the Chinese economy stumbles, wealthy families are increasingly trying to move large sums of money out of the country, worried that the value of the currency will fall and their savings will be worth less. To get around the country’s cash controls, individuals are asking friends or family members to carry or transfer out $50,000 apiece, the annual legal limit in China. A group of 100 people can move $5 million overseas. The practice is called Smurfing, named after the blue, mushroom-dwelling cartoon characters, and it is part of an exodus of capital that is casting doubt on China’s economic prospects and shaking global markets. Over the last year, companies and individuals have moved nearly $1 trillion from China.

Some methods are perfectly legal, like investing in real estate elsewhere, buying businesses overseas and paying off debts owed in dollars. Others, like Smurfing, are more dubious, and in certain cases, outright illegal. Chinese customs officials caught a woman last year trying to leave the mainland with $250,000 strapped to her chest and thighs and hidden inside her shoes. If the government cannot keep citizens from rushing to the financial exits, China’s outlook could darken. The swell of outflows is a destabilizing force in China’s slowing economy, threatening to undermine confidence and hurt a banking system that is struggling to deal with a decade-long lending binge. The capital flight is already putting significant pressure on the country’s currency, the renminbi.

The government is trying to prevent a free fall in the currency by stepping into the markets and tapping its huge cash hoard to shore up the renminbi. But a deep erosion of those reserves may set off further outflows and create turbulence in the markets. China is also trying to put the brakes on outflows, by tightening its grip on the country’s links to the global financial system. The government, for example, just started to clamp down on people’s use of bank cards to buy overseas life insurance policies. Such moves have trade-offs. The limits create concerns that the government is pulling back on reform efforts that China needs to keep growth humming in the decades to come. But the near-term pressure also requires serious attention, given the global shock waves.

“The currency has become a very near-term threat to financial stability,” said Charlene Chu, an economist at Autonomous Research. Navigating such problems is fairly new for China. For years, China soaked up much of the world’s investment money, as the economy grew at annual rates in the double digits. A largely closed financial system kept China’s own money corralled inside the country. Now, with growth slowing, money is gushing out of the country. And the government has a looser grip on the spigot, because China dismantled some currency restrictions to open up its economy in recent years. “Companies don’t want renminbi and individuals don’t want renminbi,” said Shaun Rein, the founder of the China Market Research Group. “The renminbi was a sure bet for a long time, but now that it’s not, a lot of people want to get out.”

Read more …

Huh? What is that?: “There will be an incredible amount of strong psychological pessimism in China this week..”

• China Markets Brace for Wild Swings in Year of the Monkey (WSJ)

Investors in Chinese stocks are facing a tumultuous return to action Monday after a weeklong holiday in mainland markets for the Lunar New Year shielded them from the global market turmoil. Chinese shares are already among the world’s worst-performing this year, with the main benchmark Shanghai Composite Index down 21.9% at 2763.49. The market has almost halved in value since its peak last June, dropping some 47% since then. But analysts say both the Shanghai and Shenzhen stock exchanges could face further sharp losses at Monday’s open, as they catch up with the past week’s mostly gloomy global markets. Japanese stocks sank 11% last week and the yen shot up, defying a recent move by the Bank of Japan to introduce negative interest rates, partly designed to keep the local currency weaker and help Japanese exporters.

Markets in Europe and the U.S. whipsawed as investors lost faith in banking stocks, while Australian shares entered bear market territory, having fallen more than 20% since their most recent peak in late April. Meanwhile, Chinese stocks trading in Hong Kong lost 6.8% and the city’s benchmark Hang Seng Index fell 5% in the two days markets were open here at the end of last week. “There will be an incredible amount of strong psychological pessimism in China this week,” said Richard Kang at Emerging Global Advisors. “[Global assets] are going up and down together, it’s very macro-driven right now.” China was at the epicenter of market mayhem at the start of 2016, as shares fell sharply and the country’s currency, the yuan, dipped in value. Before last summer, Chinese market slumps had little impact beyond the country’s borders, mainly because stock-buying there remains largely driven by local retail investors.

Foreign investors still account for a small amount of stock ownership in China. But the Chinese selloff early this year was met with a confused response from Beijing policy makers, who flip-flopped on new measures to stem the market bleeding and were criticized for failing to communicate clearly a change in currency strategy. That contributed to a perception among global investors that Chinese leaders have lost their grip on the country’s economy. The nervousness in markets around the world has now taken on new dimensions. Central banks are struggling to boost growth, despite the Bank of Japan joining the European Central Bank in setting negative interest rates for the first time. Bank profits face a squeeze as the margin between what they pay out on deposits and what they make on lending narrows.

Read more …

Not a small detail.

• Selloff Plus A Market Holiday Make China Stocks Look Even More Expensive (BBG)

For once, it wasn’t China’s fault. With the country’s markets closed for lunar new year holidays last week, global equity investors found plenty of other reasons to sell – everything from sliding oil prices to shrinking bank profits and crumbling faith in global monetary policy. The MSCI All-Country World Index plunged 2.6%, entering bear-market territory for the first time in more than four years. While the rout may help Communist Party officials counter perceptions that China is the biggest risk for global markets, investors in yuan-denominated A shares will find little to cheer about as trading resumes Monday. Valuations in the $5.3 trillion market, already inflated by a record-breaking bubble last year, now look even more expensive versus their beaten-down global peers.

The Shanghai Composite Index trades at a 34% premium to MSCI’s emerging-markets index – up from an average gap of 10% over the past five years – and equities in the tech-heavy Shenzhen market are almost four times more expensive than their developing-nation counterparts. Shares with dual listings, meanwhile, are valued at a 46% premium on the mainland relative to Hong Kong, near the widest gap since 2009. “There’s been a lot of embedded selling pressure in the A-share market,” said George Hoguet at State Street Global Advisors, which has $2.4 trillion under management. “I don’t think the market is fully cleared yet.” While the Shanghai Composite has dropped 22% in 2016, the gauge is still up 31% over the past two years, a period when the MSCI Emerging Markets Index sank 22%.

The Chinese stock measure is valued at 15 times reported earnings, versus 11 for the developing-nation gauge. Chinese markets will be volatile when they reopen as investors determine where they “sit in the global marketplace,” Garrett Roche, a global investment strategist at Bank of America Merrill Lynch, said by phone from New York. The firm oversees $2.5 trillion in client assets. “From the Chinese perspective, we are relatively nervous about it anyway, so it won’t change our view that the selloff hurts,” he said. Investors shouldn’t read too much into what happens in global markets when assessing the outlook for Chinese equities because the country still has a relatively closed financial system, said Eric Brock at Clough Capital Partners. The Shanghai Composite’s correlation with the MSCI All-Country index over the past 30 days was less than half that of the Standard & Poor’s 500 Index.

Read more …

Stick a fork in it?!

• Hong Kong Land Price Plunges Nearly 70% in Government Tender (BBG)

In the latest sign that Hong Kong’s property correction is deepening, a piece of land sold by the government in the New Territories sold for nearly 70% less per square foot than a similar transaction in September. The 405,756 square foot (37,696 square meter) parcel of land in Tai Po sold for HK$2.13 billion ($274 million) or HK$1,904 per square foot, in a tender that closed on Feb. 12, according to the Hong Kong Lands Department website. The buyer was Asia Metro Investment, a subsidiary of China Overseas Land & Investment.

The plunge in the price of land comes amid weaker appetite from Hong Kong developers against the backdrop of a nearly 11% drop in housing prices since their September high, according to the Centaline Property Centa-City Leading Index. In January, sales of new and secondary homes reached their lowest monthly level since Centaline started tracking data in January 1991. Hong Kong home prices surged 370% from their 2003 trough through the September peak before the correction began, spurred by a rising supply of housing and a slowdown in China. Lower prices paid for land could eventually lead to cheaper home prices down the road, and are viewed as a leading indicator of the negative sentiment on the market.

Read more …

Asia’s troubles are sure to spread. Reporting on it is slow, that’s all.

• Pakistan Default Risk Surges as $50 Billion Debt Bill Coming Due (BBG)

Bets are rising that Pakistan will default on its debt just as it starts to revive investor interest with a reduction in terrorist attacks. Credit default swaps protecting the nation’s debt against non-payment for five years surged 56 basis points over the past week amid the global market sell-off, the steepest jump after Greece, Venezuela and Portugal among more than 50 sovereigns tracked by Bloomberg. About 42% of Pakistan’s outstanding debt is due to mature in 2016 – roughly $50 billion, equivalent to the size of Slovenia’s economy. Prime Minister Nawaz Sharif has worked to make Pakistan more investor-friendly since winning a $6.6 billion IMF loan in 2013 to avert an external payments crisis. The economy is forecast to grow 4.5%, an eight-year high, as a crackdown on militant strongholds helps reduce deaths from terrorist attacks.

“Pakistan’s high level of public debt, with a large portion financed through short-term instruments, does make the sovereign’s ability to meet their financing needs more sensitive to market conditions,” Mervyn Tang, lead analyst for Pakistan at Fitch said by e-mail. Since Sharif took the loan, Pakistan’s debt due by end-2016 has jumped about 79%. He’s also facing resistance in meeting IMF demands to privatize state-owned companies, leading to a strike this month at national carrier Pakistan International Airlines. The bulk of this year’s debt, some $30 billion, is due between July and September, and repayments will get tougher if borrowing costs rise more. The spread between Pakistan’s 10-year sovereign bond and similar-maturity U.S. Treasuries touched a one-year high on Thursday.

Read more …

Making it up as they go along. Not a confidence booster.

• ECB In Talks With Italy Over Buying Bundles Of Bad Loans (Reuters)

The ECB is in talks with the Italian government about buying bundles of bad loans as part of its asset-purchase program and accepting them as collateral from banks in return for cash, the Italian Treasury said. The move could give a big boost to a recently approved Italian scheme aimed at helping banks offload some of their €200 billion ($225 billion) of soured credit and free up resources for new loans. Nonetheless, it would likely fuel a debate in other countries about whether the ECB is taking on too much risk by buying asset-backed securities (ABS) based on loans that have not been repaid for roughly three months. Italian Treasury officials told reporters the ECB may buy these securities as part of its €1.5 trillion asset-purchase program or accept them as collateral from banks in return for cash, in so called repurchase agreements.

In November last year, an ECB source said that buying rebundled non-performing loans could be an extreme option if the euro zone’s economic situation became “really bad”. The bank has been struggling to revive inflation and is likely to cut its deposit rate again next month. Italy’s high stock of bad loans has been a drag on the euro zone’s third-largest economy and is a growing concern for investors, who have been selling shares in Italian banks heavily since the start of the year. The ECB has been buying an average of €1.19 billion of ABS every month since November 2014, Datastream data showed, and prefers securities backed by performing loans. Under existing rules, the ECB can buy ABS as long as they have a credit rating above a certain threshold, thereby ensuring it only buys high-quality securities.

Read more …

Nothing stops the ECB, least of all its own rules.

• Italy’s Banking Crisis Spirals Elegantly out of Control (WS)

Italy, the Eurozone’s third largest economy, is in a full-blown banking crisis. Four small banks were rescued late last year. The big ones are teetering. Their stocks have crashed. They’re saddled with non-performing loans (defined as in default or approaching default). We’re not sure that the full extent of these NPLs is even known. The number officially tossed around is €201 billion. But even the ECB seems to doubt that number. Its new bank regulator, the Single Supervisory Mechanism, is now seeking additional information about NPLs to get a handle on them. Other numbers tossed around are over €300 billion, or 18% of total loans outstanding. The IMF shed an even harsher light on this fiasco. It reported last year that over 80% of the NPLs are corporate loans. Of them, 30% were non-performing, with large regional differences, ranging from 17% in some of the northern regions to over 50% in some of the southern regions. The report:

High corporate NPLs reflect both weak profitability in a severe recession as well the heavy indebtedness of many Italian firms, especially SMEs, which are among the highest in the Euro Area. This picture is consistent with corporate survey data which shows nearly 30% of corporate debt is owed by firms whose earnings (before interest and taxes) are insufficient to cover their interest payments.

The reason these NPLs piled up over the years is because banks have been slow to, or have refused to, write them off or sell them to third parties at market rates. Recognizing the losses would have eaten up the banks’ scarce capital. Reality would have been too ugly to behold. The study found that the average time for writing off bad loans has jumped to over six years by 2014. And this:

In 2013, on average less than 10% of bad debt, despite already being in a state of insolvency, was written off or sold. The bad debt write-off rate varies significantly across the major banks, with banks with the highest NPL ratios featuring the lowest write-off rates. The slow pace of write-offs is an important factor in the rapid buildup of NPLs.

Now, to keep the banks from toppling, the ECB has an ingenious plan: it’s going to buy these toxic assets or accept them as collateral in return for cash. That’s what the Italian Treasury told reporters, according to Reuters. Oh, but the ECB is not going to buy them directly. That would violate the rules; it can only buy assets that sport a relatively high credit rating. And this stuff is toxic. So these loans are going to get bundled into structured Asset Backed Securities (ABS) and sliced into different tranches. The top tranches will be the last ones to absorb losses. A high credit rating will then be stamped on these senior tranches to make them eligible for ECB purchases, though they’re still backed by the same toxic loans, most of which won’t ever be repaid.

The ECB then buys these senior tranches of the ABS as part of its €62.4-billion per-month QE program that already includes about €2.2 billion for ABS (though it has been buying less). Alternatively, the ECB can accept these highly rated, toxic-loan-backed securities as collateral for cash via so-called repurchase agreements. But buying even these senior tranches would violate the ECB’s own rules, which specify:

At the time of inclusion in the securitisation, a loan should not be in dispute, default, or unlikely to pay. The borrower associated with the loan should not be deemed credit-impaired (as defined in IAS 36).

Hilariously, the NPLs, by definition, are either already in “default” or “unlikely to pay,” most of them have been so for years, and the borrower is already “deemed credit impaired” if the entity even still exists. But hey, this is the ECB, and no one is going to stop it. Reuters: “The move could give a big boost to a recently approved Italian scheme aimed at helping banks offload some of their €200 billion of soured credit and free up resources for new loans.” But the scheme would limit ECB purchases to only the top tranches, and thus only a portion of the toxic loans. So there too is a way around this artificial limit.

Read more …

Might as well move out now. There is no safe storage for nuclear waste.

• Nuclear Fuel Storage in South Australia Seen as Economic Boon (BBG)

The storage and disposal of nuclear waste in South Australia would probably deliver significant economic benefits to the state, generating more than A$5 billion ($3.6 billion) a year in revenue, according to the preliminary findings by a royal commission. Such a facility would be commercially viable, with storage commencing in the late 2020s, the Nuclear Fuel Cycle Royal Commission said in its tentative findings released Monday. It doesn’t make economic sense to generate electricity from a nuclear power plant in the state in the “foreseeable future” due to costs and demand, the report found. “The storage and disposal of used nuclear fuel in South Australia would meet a global need and is likely to deliver substantial economic benefits to the community,” the commission said. “

Such a facility would be viable and highly profitable under a range of cost and revenue assumptions.” South Australia, where BHP Billiton operates the Olympic Dam mine, set up the commission last year to look at the role the state should play in the nuclear industry — from mining and enrichment to energy generation and waste storage. While Australia is home to the world’s largest uranium reserves, it has never had a nuclear power plant. Concerns over climate change have prompted debate about whether to reverse Australia’s nuclear policy. Longer term, “Australia’s electricity system will require low-carbon generation sources to meet future global emissions reduction targets,” the commission said in its report. “Nuclear power may be necessary, along with other low carbon generation technologies.”

Read more …

A ways to go.

• Oil Resumes Drop as Iran Loads Europe Cargo (BBG)

Oil resumed its decline below $30 a barrel as Iran loaded its first cargo to Europe since international sanctions ended and Chinese crude imports dropped from a record. West Texas Intermediate futures fell 0.5% in New York after surging 12% on Friday, while Brent in London slid 0.2%. A tanker for France’s Total was being loaded Sunday at Kharg Island while vessels chartered for Chinese and Spanish companies were due to arrive later the same day, an Iranian oil ministry official said. Chinese imports in January decreased almost 20% from the previous month, according to government data. “Iran is going to add headwinds to the market,” David Lennox, an analyst at Fat Prophets in Sydney, said. “We still have 500 million barrels of U.S. inventories and shale producers are still pumping. Until there are significant cuts to output, the rally is not sustainable.”

Oil in New York is down 21% this year amid the outlook for increased Iranian exports and BP Plc predicts the market will remain “tough and choppy” in the first half as it contends with a surplus of 1 million barrels a day. Speculators’ long positions in WTI through Feb. 9 rose to the highest since June, according to data from the U.S. Commodity Futures Trading Commission. WTI for March delivery slid as much as 49 cents to $28.95 a barrel on the New York Mercantile Exchange and was at $29.28 at 2:50 p.m. Hong Kong time. The contract gained $3.23 to close at $29.44 on Friday after dropping 19% the previous six sessions. Total volume traded was about 12% above the 100-day average. WTI prices lost 4.7% last week. Brent for April settlement declined as much as 69 cents, or 2.1%, to $32.67 a barrel on the ICE Futures Europe exchange. The contract climbed $3.30 to close at $33.36 on Friday. The European benchmark crude was at a premium of $1.59 to WTI for April.

Read more …

Our old friend and oil expert Jeffrey Brown with an interesting take.

• Condensate Vs Crude Oil: What’s Actually in Those Storage Tanks? (Westexas)

After examining available regional and global production data (using EIA, OPEC and BP data sources), in my opinion actual global crude oil production – generally defined as 45 API Gravity or lower crude oil – has probably been on an “Undulating Plateau” since 2005. At the same time, global natural gas production and associated liquids, condensate and natural gas liquids (NGL), have so far continued to increase. Schlumberger defines condensate as: “A low-density, high-API gravity liquid hydrocarbon phase that generally occurs in association with natural gas.” The most common dividing line between crude oil and condensate is 45 API Gravity, but note that the upper limit for WTI crude oil is 42 API Gravity. However, the critical point is that condensate is a byproduct of natural gas production.

Note that what the EIA calls “Crude oil” is actually Crude + Condensate (C+C). When we ask for the price of oil, we generally get the price of either WTI or Brent crude oil, which both have average API gravities in the high 30’s, and the maximum upper limit for WTI crude oil is 42 API Gravity. However, when we ask for the volume of oil, we get some combination of crude oil + partial substitutes, i.e., condensate, NGL and biofuels. From 2002 to 2005, as annual Brent crude oil prices approximately doubled from $25 in 2002 to $55 in 2005, global natural gas production, global NGL production and global C+C production all showed similar rates of increase. For example, from 2002 to 2005 global natural gas production increased at a rate of 3.2%/year, as global C+C production increased at a rate of 3.3%/year.

From 2005 to the 2011 to 2013 time frame, annual Brent crude oil prices doubled again, from $55 in 2005 to an average of $110 for 2011 to 2013 inclusive, remaining at $99 in 2014. From 2005 to 2014, global natural gas production increased at 2.4%/year, while global C+C production increased at only 0.6%/year. Given that condensate production is a byproduct of natural gas production, the only reasonable conclusion in my opinion is that increasing global condensate production accounted for all, or virtually all, of the post-2005 slow rate of increase in global C+C production [..]

Read more …

Haha! So glad Greer does it for us, so we don’t get the hate mail. But he’s right, obviously. Only thing is, he forgets a whole group of people. He says there are those who believe in renewables vs those who actually live with them. A third group are those who plan to make a killing off of renewables. And they drive the discussion.

• Renewables: The Next Fracking? (JMG)

I’d meant this week’s Archdruid Report post to return to Retrotopia, my quirky narrative exploration of ways in which going backward might actually be a step forward, and next week’s post to turn a critical eye on a common but dysfunctional habit of thinking that explains an astonishing number of the avoidable disasters of contemporary life, from anthropogenic climate change all the way to Hillary Clinton’s presidential campaign. Still, those entertaining topics will have to wait, because something else requires a bit of immediate attention. In my new year’s predictions a little over a month ago, as my regular readers will recall, I suggested that photovoltaic solar energy would be the focus of the next big energy bubble. The first signs of that process have now begun to surface in a big way, and the sign I have in mind—the same marker that provided the first warning of previous energy bubbles—is a shift in the rhetoric surrounding renewable energy sources.

Broadly speaking, there are two groups of people who talk about renewable energy these days. The first group consists of those people who believe that of course sun and wind can replace fossil fuels and enable modern industrial society to keep on going into the far future. The second group consists of people who actually live with renewable energy on a daily basis. It’s been my repeated experience for years now that people belong to one of these groups or the other, but not to both. As a general rule, in fact, the less direct experience a given person has living with solar and wind power, the more likely that person is to buy into the sort of green cornucopianism that insists that sun, wind, and other renewable resources can provide everyone on the planet with a middle class American lifestyle.

Conversely, those people who have the most direct knowledge of the strengths and limitations of renewable energy—those, for example, who live in homes powered by sunlight and wind, without a fossil fuel-powered grid to cover up the intermittency problems—generally have no time for the claims of green cornucopianism, and are the first to point out that relying on renewable energy means giving up a great many extravagant habits that most people in today’s industrial societies consider normal. Debates between members of these two groups have enlivened quite a few comment pages here on The Archdruid Report. Of late, though—more specifically, since the COP-21 summit last December came out with yet another round of toothless posturing masquerading as a climate agreement—the language used by the first of the two groups has taken on a new and unsettling tone.

Climate activist Naomi Oreskes helped launch that new tone with a diatribe in the mass media insisting that questioning whether renewable energy sources can power industrial society amounts to “a new form of climate denialism.” The same sort of rhetoric has begun to percolate all through the greenward end of things: an increasingly angry insistence that renewable energy sources are by definition the planet’s only hope, that of course the necessary buildout can be accomplished fast enough and on a large enough scale to matter, and that no one ought to be allowed to question these articles of faith.

Read more …

Feb 092016
 
 February 9, 2016  Posted by at 9:53 am Finance Tagged with: , , , , , , , , , ,  10 Responses »


Arthur Rothstein Going to church to pray for rain., Grassy Butte, North Dakota Jul 1936

• ‘Panic Situation’ As Asia Stocks Tumble Amid Fears Of New Global Recession (G.)
• Global Bond Rally Near ‘Panic’ Level With Japan Yield Below Zero (BBG)
• Japan’s 10-Year Yield Falls Below Zero for the First Time (BBG)
• US Bank Stocks And Bonds Clobbered By Recession Worry (Reuters)
• Investors Dump Stocks, Seek Safe Havens As Bank Fears Flare (Reuters)
• Banks Bonds Are “The Epicenter Of Growth Concerns Globally” (BBG)
• Goldman Sachs Sees Near-Zero Risk Of UK Recession Despite Market Tantrum (AEP)
• Chesapeake Energy Plunges On Bankruptcy Fears (Forbes)
• 150 Oil And Gas Companies “At Risk Of Bankruptcy” As Prices Fall (BBG)
• US Oil Industry Woes Grow As Storage Levels Hit ‘Critical Level’ (MW)
• Jim Rogers: “The Market Knows It’s Over” (SHTF)
• Can Hobbit Tourism Save New Zealand’s Troubled Dairy Farmers? (BBG)
• Turkey’s Erdogan Threatened To Flood Europe With Migrants (Reuters)
• 35 Refugees Die Off Turkish Coast (Guardian)

Panic.

• ‘Panic Situation’ As Asia Stocks Tumble Amid Fears Of New Global Recession (G.)

Japan’s Nikkei index plummeted more than 950 points on Tuesday, its biggest intraday loss since May 2013, and the yen briefly soared to a 14-month high against the US dollar, as continued fears over the health of the global economy saw a continuation of the previous day’s selloff in Europe and the US. The Nikkei dived 5.1% to 16,132.25 in morning trading and extended losses into the afternoon, while Australia’s S&P/ASX 200 fell 2.6% to 4,946.70. Markets were also down in the Philippines, Indonesia, Thailand and New Zealand. The MSCI’s index of Asia-Pacific shares outside Japan fell 1% and might have fallen further had several Asian markets not been closed.

Markets in China, Hong Kong, Taiwan and South Korea were closed for Lunar New Year holidays. Most markets in the region will re-open from Wednesday, with Chinese markets returning next week. The volatility affecting global markets last month appears set to continue amid concern about Chinese economic growth, falling oil prices and speculation that the US federal reserve could change course with interest rates. “The combination of concerns that the United States could be heading toward a recession and the global stock sell-off is curbing risk appetite and is sending investors to the safe-haven yen,” Takuya Takahashi at Daiwa Securities told Kyodo News.

After hovering around the 117-yen line on Monday, the Japanese currency briefly rose to the upper 114 zone to its strongest level against the dollar since November 2014. Investors regard the yen as a “save haven” currency when global markets are hit by the kind of turmoil witnessed in recent weeks. The yen is expected to make further gains – a trend that eats into the repatriated profits of Japanese auto and other exporters. Three-month dollar/yen implied volatility – which indicates how much currency movement is expected in the months ahead – reached 12.137% its highest since September 2013. Responding to the yen’s rise, Japan’s finance minister, Taro Aso, told reporters: “It is clear that recent moves in the market have been rough. We will continue to carefully monitor developments in the currency market.”

Read more …

And more panic.

• Global Bond Rally Near ‘Panic’ Level With Japan Yield Below Zero (BBG)

Sovereign bonds surged, sending the Japanese benchmark 10-year yield below zero for the first time, as investors seeking the safest assets gorged on government debt. Treasury yields dropped to a one-year low in the rush to refuge from a worldwide stock rout. Traders pared the odds the Federal Reserve will raise interest rates this year to 30%, before Chair Janet Yellen begins her two-day testimony to Congress on Wednesday. The yield on the Bank of America Merrill Lynch World Sovereign Bond Index tumbled to 1.29%, the least in data that go back to 2005. “It’s almost like a panic,” said Hideo Shimomura, the chief fund investor in Tokyo at Mitsubishi UFJ Kokusai Asset Management. “The flight to quality is exaggerated.”

The benchmark 10-year Treasury yield tumbled six basis points to 1.69% as of 2:31 p.m. in Tokyo, according to Bloomberg Bond Trader data. The price of the 2.25% security due in November 2025 rose 17/32, or $5.31 per $1,000 face amount, to 105. Japan’s 10-year yield fell to minus 0.01%, an unprecedented low for such a maturity in a Group-of-Seven economy. Australia’s dropped to 2.38%, a level not seen since April. Investors rushed to bonds as the MSCI Asia Pacific Index of stocks slid 2.8% and Japan’s Topix Index plunged 5.7%. “It’s hard to find a reason to short Treasuries,” said Tomohisa Fujiki at BNP Paribas in Tokyo, referring to bets that a security will fall. Turmoil “is now affecting equity markets in developed countries as well — and commodities and emerging markets have not stabilized yet.” BNP is one of the 22 primary dealers that underwrite the U.S. debt.

Read more …

BoJ buys them all anyway.

• Japan’s 10-Year Yield Falls Below Zero for the First Time (BBG)

The yield on Japan’s benchmark 10-year government bonds fell below zero for the first time, an unprecedented level for a Group-of-Seven economy, as global financial turmoil and the Bank of Japan’s adoption of negative interest rates drive demand for the notes. The 10-year yield has tumbled from 0.22% before the BOJ surprised markets with the decision on Jan. 29 to introduce a minus 0.1% rate on some of the reserves financial institutions park at the central bank. It fell 7 1/2 basis points to a record minus 0.035% as of 3:05 p.m. in Tokyo. Japanese bonds are also climbing as sovereign securities rally worldwide. Global stocks have dropped 10% this year on concern growth is slowing in China, and as slumping oil prices undermine policy makers efforts to revive inflation.

About 29% of the outstanding debt in the Bloomberg Global Sovereign Bond index was yielding less than zero as of 5 p.m. in New York on Monday. Swiss 3% notes due in 2018 were offering the lowest yield in the index, according to data compiled by Bloomberg. “It was just a matter of time before 10-year yields went negative, so it wasn’t a surprise,” said Yusuke Ikawa at UBS. Five-year yields dropped seven basis points to minus 0.25%, while two-year yields slid five basis points to minus 0.245%. Both were record lows. A basis point is 0.01 percentage point. The expected price volatility for Japanese debt over a 60-day period soared to 3.13% on Monday, the highest level since June, according to data compiled by Bloomberg.

Read more …

Banks across the globe are under fire.

• US Bank Stocks And Bonds Clobbered By Recession Worry (Reuters)

U.S. bank stocks and bonds took a pounding on Monday as recession fears compounded concern about their exposure to the energy sector and expectations that global interest rates are unlikely to rise quickly. The S&P 500 financial index, already the worst performing sector this year, fell 2.6% and now stands more than 20% from its July 2015 high, confirming the sector is in the grip of a bear market. Shares of Morgan Stanley slid 6.9% in their largest one-day drop since November 2012, while rival Goldman Sachs fell 4.6%. Both stocks closed at their lowest since the spring of 2013. Meanwhile, bonds issued by U.S. banks extended their decline, with the yield premium demanded by investors to hold these securities, rather than safer U.S. Treasury debt, climbing to the highest in three-and-a-half years, according to BofA Fixed Income Index data.

“Investors’ attitudes seem to be worsening relative to the likelihood of a global recession. I think that’s what financials are reflecting – that their net interest margins are going to be further compressed under collapsing (sovereign) bond yields,” said Mark Luschini, chief investment strategist at Janney Montgomery Scott in Philadelphia. Yields on sovereign bonds from so-called safe-haven issuers such as the United States, Germany and Japan have tumbled recently as investors increasingly doubt central banks in these countries will be able to raise interest rates any time soon. The U.S. Federal Reserve late last year pulled off its first rate increase in nearly a decade, but interest rate futures markets now assign just a 1-in-4 chance of another one this year. And the Bank of Japan last month cut rates into negative territory for some bank reserves.

Monday’s drop in U.S. bank stocks follows concern over stress in the financial sector in Europe, where the cost of insuring the European financial sector’s senior debt against default climbed to its highest level since late 2013. Credit default swaps on several U.S. banks have followed suit. The cost for a five-year CDS contract on Morgan Stanley debt, for instance, has rocketed by more than 27% since last Thursday and now stands at its highest since October 2013, data from Markit shows. Citigroup’s CDS, likewise, is at the highest since June 2013.

Read more …

“Japanese Finance Minister Taro Aso felt moved enough to warn the yen’s rise was “rough”..”

• Investors Dump Stocks, Seek Safe Havens As Bank Fears Flare (Reuters)

Asian share markets were scorched on Tuesday as stability concerns put a torch to European bank stocks and sent investors stampeding to only the safest of safe-haven assets. As fear overwhelmed greed, yields on longer-term Japanese bonds fell below zero for the first time, the yen surged to a 15-month peak and gold reached its most precious since June. Japanese Finance Minister Taro Aso felt moved enough to warn the yen’s rise was “rough”, something of an understatement as the Nikkei nosedived 5.4%. MSCI’s broadest index of Asia-Pacific shares outside Japan fell 1.2%, with Australian shares hitting 2-1/2-year closing low, and would have been lower if not for holidays in many centres.

Spread-betters see another weak session in European shares, where German DAX is seen falling 0.7% and Britain’s FTSE 0.5%. S&P 500 e-mini futures fell more than 1% at one point. “Sentiment towards risk assets remained extremely bearish and price action reflected a market that may be capitulating,” said Jo Masters, a senior economist at ANZ. All of which magnified the stakes for U.S. Federal Reserve Chair Janet Yellen’s testimony this week. “She needs to come across as optimistic without being too hawkish and cautious without being negative,” said Masters. “Hawkishness or dovishness could easily exacerbate the current sell-off, tightening financial conditions further.”

Wall Street pared losses but still ended deep in the red. The Dow lost 1.1%, while the S&P 500 fell 1.42% and the Nasdaq 1.82%. The rout began in Europe on Monday, when the FTSEurofirst 300 index shed 3.4% to its lowest since late 2013, led by a near 6% dive in the banking sector. Deutsche Bank alone sank 9.5% as concerns mounted about its ability to maintain bond payments. Late Monday, the German bank said it has “sufficient” reserves to make due payments this year on AT1 securities. The cost of insuring bank debt against default also climbed to its highest since late 2013. Borrowing costs in Spain, Portugal and Italy jumped as investors demanded a fatter risk premium over safer German paper, where two-year yields hit record lows at minus 52 basis points.

Read more …

“..additional Tier 1 bonds..” Sounds solid?!

• Banks Bonds Are “The Epicenter Of Growth Concerns Globally” (BBG)

Last year’s sure thing in credit markets is quickly becoming this year’s nightmare for bond investors. The riskiest European bank debt generated returns of about 8% last year, according to BofAML index data, beating every type of credit investment globally. In less than six weeks this year, those gains have been all but wiped out, even after interest payments. Investors are increasingly concerned that weak earnings and a global market rout will make it harder for banks to pay the interest on at least some of these securities, or to buy them back as soon as investors had hoped. The bonds allow banks to skip interest payments without defaulting, and they turn into equity in times of stress. Deutsche Bank may struggle to pay the interest on these securities next year, a report from independent research firm CreditSights earlier on Monday said. The bank took the unusual step of saying that it has enough capacity to pay coupons for the next two years.

“The worries about these bonds represent real fears that the European banking system may be weaker and more vulnerable to slowing growth than a lot of people originally thought,” said Gary Herbert at Brandywine Global Investment Management. “It’s the epicenter of growth concerns globally. And it doesn’t look pretty,” he added. Money managers’ concerns are spreading even to safer bank bonds, underscoring how investors are running away from risk across a broad range of assets now, from stocks to commodities to corporate bonds. The cost of protecting against defaults on safer U.S. and European financial debt known as senior unsecured notes has jumped to the highest level since 2013. European banks are looking less solid since their last earnings reports.

Deutsche Bank for example last month posted its first full-year loss since 2008, and its shares have plunged. Credit Suisse’s shares plunged to their lowest level since 1991 after the Swiss bank posted its biggest quarterly loss since the crisis. Banks have issued about €91 billion of the riskiest notes, called additional Tier 1 bonds, since April 2013. The problem is the securities are untested and if a troubled bank fails to redeem them at the first opportunity or halts coupon payments investors may jump ship, sparking a wider selloff in corporate credit markets. “It’s the first thing that gets cut from portfolios,” said David Butler, a portfolio manager at Rogge Global Partners, which oversees about $35 billion of assets. “When the wider credit market turns, it leaves investors exposed.”

Read more …

Feel better now? “For those “brave enough to defy Mr Market’s gloomy prognosis”, this may be an ideal time to jump back into the stock market, said Mr Hatzius.”

• Goldman Sachs Sees Near-Zero Risk Of UK Recession Despite Market Tantrum (AEP)

Britain is extremely unlikely to face an economic recession over the next two years and is on safer ground than any other major country in the developed world, according to a new crisis-study by Goldman Sachs. The US investment bank said the global stock market rout and the credit tremors this year are sending off false signals, insisting that underlying indicators of economic health show little sign of a sudden rupture in Europe, the US or across the OECD bloc of rich states. An array of “alarm” indicators – based on the experience of 20 countries since 1970 – suggest that the current business cycle is still in full swing and far from exhaustion, even if risks have been ratcheting up over recent months. Credit ratios are high but they have not been spiking higher in most OECD states, and there is still plenty of slack left in the economy.

This allows central banks to take their time before having to slam on the brakes – the time-honoured cause of recessions. Jan Hatzius, Goldman’s chief US economist, cited a string of episodes where markets were gripped by fear and emotion yet the storm passed without doing much damage. These included the 1987 stock market crash, the 1994 bond rout, Mexico’s Tequila crisis, the failure of the giant hedge fund Long-Term Capital Management and the Asian crisis in 1998, the corporate credit squeeze from 2002-2003 at the onset of the Iraq War and the eurozone sovereign debt crisis. “In each case, at least some financial markets were priced for significant recession risk, if not an outright slump,” he said. Yet Goldman cautioned that it would be a “grave error” to ignore the latest market tantrum altogether.

The US Federal Reserve was able to slash interest rates and flush the international financial system with liquidity to weather the 1987 and 1998 storms, something that would be much harder to pull off today. Mounting worry over China – and its linkages through the commodity nexus – has put everybody’s nerves on edge this time. “Financial markets now signal a high probability of another recession. High-yield spreads are at levels almost never seen outside of recessions,” said Mr Hatzius. “The message from the equity market is less clear-cut, but there are only a few non-recessionary instances over the past three decades in which the S&P 500 (index of US equities) performed as poorly as it did over the past year,” he said. That said, Britain appears rock-solid under the Goldman Sachs model with a mere 3pc risk of losing its footing over the next eight quarters, followed by Sweden, Denmark and South Korea.

Read more …

“Basically they’re maxxing out their credit cards before the banks can cut them off.”

• Chesapeake Energy Plunges On Bankruptcy Fears (Forbes)

Shares in Chesapeake Energy were halted in mid-morning trading after selling off more than 50% to new lows on a report from Debtwire that the company had hired restructuring specialists Kirkland & Ellis . Seeking to stem the panic, Chesapeake issued a statement saying it “has no plans to pursue bankruptcy” and that Kirkland & Ellis had been one the company’s law firms since 2010. Chesapeake also reportedly hired restructuring specialists Evercore Partners back in December. After trading resumed, shares recovered some of their ground, jumping from $1.50 to $2.25, though still off 27% on the day so far. At these levels, all of Chesapeake’s equity could be had for $1.4 billion. Shares traded above $30 in 2014, and north of $60 in 2008, when natural gas prices hit record highs.

Naturally, holders of Chesapeake debt are shooting first and asking questions later. Its nearest-term bond matures March 15; it traded as high as 95 cents on the dollar late last week, but plunged this morning to 73.75 cents. After the announcement the bonds recovered above 80 cents, according to FINRA data. Investors are concerned that Chesapeake will be unwilling or unable to roll the debt. According to a report this morning from Troubled Company Reporter, some of Chesapeake’s longer dated issues are trading below 30 cents. Chesapeake has been looking for options to improve liquidity. Late last year amended its $4 billion bank revolver, changing it from an unsecured line to secured. It also did a distressed-debt-exchange offer, taking in $3.8 billion in notes in exchange for $2.4 billion in second-lien debt. It recently canceled dividend payments on its preferred stock.

A big problem for Chesapeake and many other exploration and production companies: their oil and gas hedges are rolling off, meaning that the little protection they used to have against low commodity prices is evaporating. As billionaire natural gas trader John Arnold tweeted this morning: “The wave of E&P bankruptcies starts now. CHK alone has nearly $1 billion less in hedging gains in ’16 than ’15 at today’s prices.” I talked to a well-placed banker over the weekend who says restructuring advisors at shops like Lazard and Kirkland & Ellis had been advising his clients to begin drawing down any cash remaining on their bank revolvers in order to maximize liquidity to get them through the next few months. Basically they’re maxxing out their credit cards before the banks can cut them off. That’s exactly what Linn Energy said last week that it had done; with more than $4 billion in credit facilities maxxed. Shares in LINE fell 50% on Friday and are off another 24% today. Linn’s debt is trading below 20 cents.

Read more …

“We need to close that gap. And the way that that will happen is the rest of those bankruptcies will go forward.”

• 150 Oil And Gas Companies “At Risk Of Bankruptcy” As Prices Fall (BBG)

About 150 oil and gas companies tracked by energy consultant IHS Inc. may go bust as a supply glut pressures prices and punishes revenues. The number of companies at risk is more than twice the 60 producers that have already filed for bankruptcy, Bob Fryklund, chief upstream analyst at IHS, said in an interview. A further shake out would help stimulate deals that have been on hold because buyers and sellers have disagreed on asset values, he said. Oil has collapsed about 70% over the past two years as U.S. shale producers boosted output and OPEC flooded the market with crude to drive out higher-cost suppliers. More bankruptcies would be one signal that energy prices have reached a bottom and would help kick off deals for the $230 billion worth of oil and gas assets currently up for sale, according to Fryklund.

“Nobody is buying because there is a mismatch between expectations,” Fryklund said in an interview in Tokyo. “We need to close that gap. And the way that that will happen is the rest of those bankruptcies will go forward.” Companies that plan to make investments are likely to wait for prices to gain for six months because they want to be confident in a recovery, according to Fryklund. “It usually happens as we begin to come back up on price,” he said. “There is always a little lag on timing.” The global oil surplus that fueled crude’s decline to a 12-year low will shift to a deficit as output falls and a new bull market begins before the year is out, Goldman Sachs said in January.

U.S. production will drop by 620,000 barrels a day, or about 7%, from the first quarter to the fourth, according to the Energy Information Administration. Low prices are also spurring greater efficiency, according to IHS. Operating costs on a per barrel basis declined about 35% last year in North America and have dropped about 20% globally, according to the consultant. Crude output from North Dakota rose through most of last year and some producers in the Permian Basin in western Texas can break-even drilling oil at $35 a barrel, he said.

Read more …

88% full is about as full as it can get. Tanks at Cushing are used for blending too. Can’t do that if they get even fuller.

• US Oil Industry Woes Grow As Storage Levels Hit ‘Critical Level’ (MW)

The storage tanks at Cushing, Okla., the delivery point for the New York Mercantile Exchange crude contract, are edging closer to their limits, raising a new set of problems for an industry that has already suffered from a 70% drop in prices in the past year and a half. Cushing, which represents about 13% of the nation’s oil storage, has a working capacity of about 73.014 million barrels of crude oil, according to data from Sept. 2015, the latest available from the EIA. As of the week ended Jan. 29, there was 64.174 million barrels of oil in storage at Cushing, so it is at about 88% full. “Where inventories count the most—at the Nymex terminal complex in Cushing, Oklahoma—storage is already at a critical level,” said Stephen Schork, in The Schork Report published Monday.

“Approximately 6 out of 7 barrels available storage capacity at the Nymex hub are now full.” The report highlighted an article from Reuters that discussed delays in crude deliveries from storage tanks at Cushing because there wasn’t enough room to drain existing tanks to blend oil to meet West Texas Intermediate crude specifications. Cushing serves as a blending station, where crude oil from the midcontinent is mixed to the specific grades required by different refineries, according to StateImpact Oklahoma. “We soon might be in a situation that we have so much oil, that we don’t have enough of the right kind of oil,” Schork said.

But that’s not the only problem. Richard Hastings, macro strategist at Seaport Global Securities, said building more tanks would take time and there would be questions over how the cost of tanks would be shared across the supply chain. Meanwhile, the market is dealing with a “constant high volume” of crude oil coming from the floating storage at the Gulf Coast, the Canadian crudes coming by rail to the U.S. and domestic production, said Hastings. “If the volumes get too high, then the intermediate delivery steps—moving large volumes from tanks to pipelines—could be difficult if the local hub’s pipeline capacity is constrained,” he said.

Read more …

“..no matter how much P.R. or whitewashing they use, the market knows this is over and we’re not going to play this game anymore.”

• Jim Rogers: “The Market Knows It’s Over” (SHTF)

Back in the 1970’s as recession gripped the world for a decade, stocks stagnated and commodities crashed, investor Jim Rogers made a fortune. His understanding of markets, capital flows and timing is legendary. As crisis struck in late 2008, he did it again, often recommending gold and silver to those looking for wealth preservation strategies – move that would have paid of multi-fold when precious metals hit all time highs in 2011. He warned that the crash would lead to massive job losses, dependence on government bailouts, and unprecedented central bank printing on a global scale. Now, Rogers says that investors around the world are realizing that the jig is up. Stocks are over bloated and central banks will have little choice but to take action again. But this time, says Rogers in his latest interview with CrushTheStreet.com, there will be no stopping it and people all over the world are going to feel the pain, including in China and the United States.

We’re all going to suffer… I can think of very few places that won’t suffer. But most people are going to suffer the next time around. Central banks will panic. They will do whatever they can to save the markets. It’s artificial… it won’t work… there comes a time when no matter how much money you have, the market has more money. [..] I don’t know if they’ll even call it QE (Quantitative Easing) in the future… who knows what they’ll call it to disguise it… they’re going to try whatever they can… printing more money or lowering interest rates or buying more assets… but unfortunately, no matter how much P.R. or whitewashing they use, the market knows this is over and we’re not going to play this game anymore.

The entire world is about to get hammered and the average person on the street is the one who will pay the price, as is usually the case. We can expect more losses in markets, more losses in jobs and more losses to freedom as governments and central banks point the finger at everyone but themselves.

Read more …

If that’s your sole alternative…

• Can Hobbit Tourism Save New Zealand’s Troubled Dairy Farmers? (BBG)

New Zealand farmer Ian Diprose used to count on the dairy industry for most of his income. Today, he relies on tourism. As plunging milk prices push dairy farms into the red and hurt rural businesses, Diprose and wife Joy are making more money accommodating tourists than other farmers’ cows. That’s because their grazing property in Waikato, New Zealand’s dairying heartland, is about 16 kilometers (10 miles) from Hobbiton, a life-sized imitation of Bilbo Baggins’ Shire created for Peter Jackson’s Lord of the Rings and Hobbit movies. “A lot of the people who come through here are Hobbiton-crazy,” said Diprose, 73, whose De Preaux Lodge in Matamata offers bed, breakfast, a home-cooked meal and an authentic New Zealand farm experience for NZ$175 ($120) a night. “In our little town, we have something like 30 cafes or places to eat because of the tourists coming through.”

The Diproses started offering accommodation five years ago as a hobby to augment income from agisting cattle. Today, it’s their main business. Four out of five dairy farmers in New Zealand, the world’s biggest dairy exporter, will operate at a loss this season as the global slump in milk prices enters its third year, according to the central bank. That’s curbing farmers’ spending and damping economic growth, even as a tourism boom helps to soften the blow. “I’ve reduced my grazing prices to one of my customers quite drastically because she’s a young farmer and I know she’s struggling,” said Diprose, who has two sons dairying. “The impact it’s having on them is crippling. The financial situation of the dairy farmers, I weigh that up every day in my heart.” As farmers tighten their belts, demand for fertilizer to veterinary services has fallen, and retailers in rural towns are feeling the pinch.

At Giltrap AgriZone, which sells hay balers and tractors at three outlets around Waikato, sales are down 30% from a year ago, said Managing Director Andrew Giltrap. “We’re on a roller coaster and we just have to ride it out,” he said. New Zealand, once known as the country with 10 times more sheep than people, has stepped up investment in dairy farming in the past decade. The nation now boasts 5 million cows, more than its 4.5 million human population, while sheep numbers have declined 26% since 2006 to 29.5 million. The strategy made sense when milk prices surged to a record in 2007 and neared that peak again in 2013. Since then, a global oversupply and waning demand for milk powder from a slumping China have seen prices crash. With plunging oil prices now sapping milk purchases by Russia and other energy-producing nations, dairy prices are approaching the 12-year low they hit in August.

Read more …

But they’ll let him, want to bet? Europe’s rudderless. He has a demand or two in Syria as well.

• Turkey’s Erdogan Threatened To Flood Europe With Migrants (Reuters)

Turkish President Tayyip Erdogan threatened in November to flood Europe with migrants if EU leaders did not offer him a better deal to help manage the Middle East refugee crisis, a Greek news website said on Monday. Publishing what it said were minutes of a tense meeting last November, the euro2day.gr financial news website revealed deep mutual irritation and distrust in talks between Erdogan and the EU’s two top officials, Jean-Claude Juncker and Donald Tusk. The EU officials were trying to enlist Ankara’s help in stemming an influx of Syrian refugees and migrants into Europe. Over a million arrived last year, most crossing the narrow sea gap between Turkey and islands belonging to EU member Greece.

Tusk’s European Council and Juncker’s European Commission declined to confirm or deny the authenticity of the document, and Erdogan’s office in Ankara had no immediate comment. The account of the meeting, in English, was produced in facsimile on the website. It does not state when or where the meeting took place, but it appears to have been on Nov. 16 in Antalya, Turkey, where the three met after a G20 summit there. “We can open the doors to Greece and Bulgaria anytime and we can put the refugees on buses … So how will you deal with refugees if you don’t get a deal? Kill the refugees?” Erdogan was quoted in the text as telling the EU officials. It also quoted him as demanding €6 billion over two years. When Juncker made clear only half that amount was on offer, he said Turkey didn’t need the EU’s money anyway.
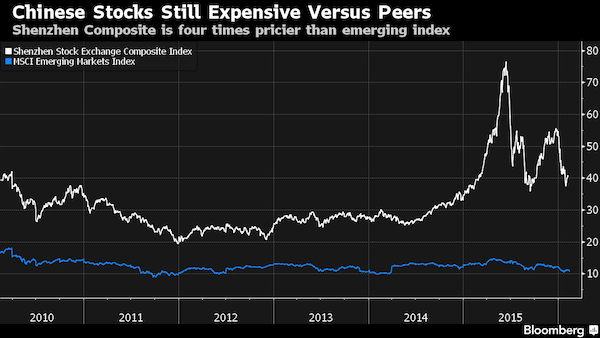
The EU eventually agreed a €3 billion fund to improve conditions for refugees in Turkey, revive Ankara’s long-stalled accession talks and accelerate visa-free travel for Turks in exchange for Ankara curbing the numbers of migrants pouring into neighboring Greece. In heated exchanges, Erdogan often interrupted Juncker and Tusk, the purported minutes show, accusing the EU of deceiving Turkey and Juncker personally of being disrespectful to him.The Turkish leader was also quoted as telling Juncker, a former prime minister of tiny Luxembourg, to show more respect to the 80-million-strong Turkey. “Luxembourg is just like a little town in Turkey,” he was quoted as saying.The tense dialogue highlighted the depth of mutual suspicion at a time when the EU is banking on Turkish help to alleviate its worst migration crisis since World War Two.

The EU says the flow of people from Turkey, which hosts more than 2.5 million Syrian refugees, has not decreased in any significant way since the bloc’s joint summit with Ankara in November, when they had agreed the fund for refugees there.The report prompted a member of the European Parliament from the Greek centrist party To Potami to ask the European Commission to confirm the purported talks.”If the relevant dialogues between the EU officials and the Turkish President are true, it seems that there are aspects of the deal between Ankara and the EU which were concealed on purpose,” Miltos Kyrkos said in the question he submitted to the Commission. “We want immediately an answer on whether these revelations are true and where the Commission’s legitimacy to negotiate, using Turkey’s accession course as a trump card, is coming from,” Kyrkos said.

Read more …

Sweet Jesus.

• 35 Refugees Die Off Turkish Coast (Guardian)

At least 35 people have died after two boats carrying refugees sank off Turkey’s Aegean coast, according to reports. The Turkish coastguard said 24 drowned when a boat capsized in the Bay of Edremit, near the Greek island of Lesbos, while the Dogan news agency reported that the bodies of 11 people were found after a separate accident further south, near the Aegean resort of Dikili. The deaths came as Angela Merkel, the German chancellor, met the Turkish prime minister, Ahmet Davutoglu, for more talks on reducing the influx of refugees to Europe.

Turkey is central to Merkel s diplomatic efforts to reduce the flow. Germany saw an unprecedented 1.1 million asylum seekers arrive last year, many of them fleeing conflicts in Syria, Iraq and Afghanistan. In her weekly video message on Saturday, Merkel said European Union countries agree that the bloc needs to protect its external borders better, and that that is why she is seeking a solution with Turkey. She added that, if Europe wants to prevent smuggling, “we must be prepared to take in quotas of refugees legally and bear our part of the task”. “I don t think Europe can keep itself completely out of this”, Merkel said.

Read more …

Jan 312016
 
 January 31, 2016  Posted by at 10:07 am Finance Tagged with: , , , , , , , , , ,  2 Responses »


Edwin Rosskam Shoeshine, 47th Street, Chicago’s main Negro business street 1941

• A Chinese Banker Explains Why There Is No Way Out (ZH)
• China GDP Growth 4.3%, Or Lower, Chinese Professor Says (WSJ)
• Yuan Vs. Yen: How China Figures Into Japan’s Negative Rates (WSJ)
• IPO Market Comes to a Standstill (WSJ)
• Greece’s Lenders To Start Bailout Review On Monday (Reuters)
• Milk Collapse Brings a 45% Pay Cut to England’s Dairy Farmers (BBG)
• ‘Peak Stuff’ And The Search For Happiness (Guardian)
• Merkel Says Refugees Must Return Home Once War Is Over (Reuters)
• 10,000 Refugee Children Are Missing, Says Europol (Observer)
• Aegean Sea Refugee Crossings Rise 35 Fold Year-On-Year In January (Guardian)
• Greeks Worry Threatened Closure Of EU Border ‘Definition Of Dystopia’ (Guar.)
• Europe’s Immigration Bind: Morals vs Votes (Guardian)
• 39 Greece-Bound Refugees Drown Off Turkish Coast (AP)

“It’s not difficult to issue more loans, but let’s say in a years time when the loan is due, if the borrower defaults, then I won’t just see a pay cut, I’ll be fired, and still be responsible for loan recovery.”

• A Chinese Banker Explains Why There Is No Way Out (ZH)

Friday’s adoption of NIRP by Japan, which send the US Dollar soaring, has only made any upcoming future Chinese devaluation even more likely. But whether China devalued or not, one thing is certain: it is next to impossible for China – under the current socio economic and financial regime – to stop the relentless growth in NPLs, which even by conservative estimates at in the trillion(s), accounting for at least 10% of China’s GDP. Sure enough, a cursory skimming of news from China reveals that even Chinese bankers now “admit the NPL situation is dire, but will keep on lending” anyway. As the Chiecon blog notes, NPL “ratios might be closer to 10%… supported by revelations in this article, where Chinese bankers complain of missing performance targets, spiraling bad loans, and end of year pay cuts.”

“Right now, we’ve nowhere to issue new loans” said Mr. Zhang, a general manager in charge of new loans at one of the listed commercial bank branches. Zhang believes NPL ratios have yet to peak, with SME loans the worst hit area. Ironically this has forced Zhang to direct lending back to the LGFVs, property developers and conglomerates, industries which the Chinese government had previously instructed banks to restrict lending to, based on oversupply and credit risk fears.

But the main reason why China is now trapped, and on one hand is desperate to stabilize its economy and stop growing its levereage at nosebleed levels, while on the other hand it is under pressure to issue more loans while at the same time it is unwilling to write off bad loans, can be found in the following very simple explanation offered by Mr. Zhou, a junior banker at a Chinese commercial bank.

“If I don’t issue more loans, then my salary isn’t enough to repay the mortgage, and car loan. It’s not difficult to issue more loans, but let’s say in a years time when the loan is due, if the borrower defaults, then I won’t just see a pay cut, I’ll be fired, and still be responsible for loan recovery.”

And that, in under 60 words, explains why China finds itself in a no way out situation, and why despite all its recurring posturing, all its promises for reform, all its bluster for deleveraging, China’s ruling elite will never be able to achieve an internal devaluation, and why despite its recurring threats to crush, gut and destroy all the evil Yuan shorts, ultimately it will have no choice but to pursue an external devaluation of its economy by way of devaluing its currency presumably some time before its foreign reserves run out (which at a $185 billion a month burn rate may not last for even one year). However, before it does, it will make sure that it also crushes every Yuan short, doing precisely what the Fed has done with equity shorts in the US over the past 7 years.

Read more …

While still ‘assuming the official agriculture and service sector growth figures are correct’.

• China GDP Growth 4.3%, Or Lower, Chinese Professor Says (WSJ)

As growth in the world’s second-largest economy slows, the spotlight has intensified over the accuracy of China’s growth figures. This week, Xu Dianqing, an economics professor at Beijing Normal University and the University of Western Ontario, joined the debate with an estimate that China’s GDP growth rate might just be between 4.3% and 5.2%. China’s official growth rate in 2015 was 6.9%, the slowest pace in more than two decades, allowing the government to hit its target of around 7%. But longstanding questions over China’s statistical methodology have spurred a cottage industry in alternate growth indicators. Many of these analyze other measures believed to be less subject to political pressure in estimating actual growth, including indices compiled by economists at Capital Economics, Barclays Bank, the Conference Board and Oxford Economics.

Most peg China’s annual growth in the 4% to 6% range. Mr. Xu told reporters at a briefing this week that the focus of his concern is the growth rate for China’s manufacturing sector, which according to official figures grew 6.0% last year and accounts for 40.5% of the economy. A closer look at underlying indicators, however, including thermal power generation, railway freight volume, and output from the iron ore, plate glass, cement and steel industries released monthly by the National Bureau of Statistics paint a different picture, he said. Of some 60 major industrial products, nearly half saw output contract in the January to November period, while railway cargo volume fell 11.9% for all of last year, according to official sources.

Given weaker industrial output in China and more than three years of industrial deflation, a 6% expansion for manufacturing in 2015 is questionable “no matter how the number is counted,” said Mr. Xu, who added that he believes it’s more probable that industry and construction grew at most by 2% last year and perhaps not at all. That translates into economic growth that tops out at 5.2% last year and perhaps something in the 4s, assuming the official agriculture and service sector growth figures are correct, he said. Mr. Xu said it’s unlikely that the service sector– sometimes cited as an explanation for growth rate discrepancies – did better than reported by authorities.

Read more …

Twins.

• Yuan Vs. Yen: How China Figures Into Japan’s Negative Rates (WSJ)

Japan’s move to negative interest rates is the latest step in a dangerous dance between the world’s second and third largest economies. The problem is currencies. China’s moves to bring down the value of the yuan have rattled markets this year, sparking a flight from risky assets that has sent investors into safer havens like the yen. The stronger yen in turn has threatened to tip Japan’s economy back into deflation, which the central bank has struggled to vanquish. The rising yen has also put more pressure on corporate profits and helped push Japanese stocks into bear market territory last week. So when the Bank of Japan announced its plan to lower interest rates below zero for the first time Friday, it makes sense that Governor Haruhiko Kuroda named just one country among the risks facing its economy China.

Now it’s China s turn to sweat. The yen fell as much as 2.1% after the announcement, which will make Chinese exports more expensive relative to Japanese products. The two countries, and most of their neighbors, are struggling against a tide of money outflows and weak trade. While governments in the rest of Asia have far more room to stimulate their economies than Japan does, a decline in the yen could spur them to try to push down their own currencies. Were China to follow and the central bank has already allowed the yuan to fall it would ignite another round of fear, which could push up the yen and force the Bank of Japan to act again. So far, the yen’s ups and downs have left it about where it was a year ago, so the risk of a cycle of competitive devaluation is limited.

In addition, the drop in the yen would have been a bigger problem for China when the yuan was pegged to the dollar. The government’s recent switch to a basket of currencies that includes the yen means the move up won’t be as big. But it still will push the currency in the wrong direction for the slowing economy. There’s another reason China does’ t want the yen to fall. Right now, thousands of Chinese are planning their Lunar New Year’s holidays in Japan early next month, hoping to take advantage of the cheap yen. During the October Golden Week, China’s other big travel week of the year, Chinese tourists descended on Japan, spending more than $830 million on shopping, according to the state-run China Daily.

China is suffering an epic capital flight in which hundreds of billions of dollars are leaving the country. A weaker yen will send more Chinese into Tokyo’s department stores and further drain China’s currency reserves. The economic fates of China and Japan are closely connected. Until their economies get on stronger footing, moves to boost growth in one country could hurt the other and risk retaliation. As the world economy stays weak, the interaction between China and Japan could play an increasingly important role both in Asia and globally.

Read more …

Zero.

• IPO Market Comes to a Standstill (WSJ)

A frigid January for initial public offerings is pointing to a hard winter for fledgling biotechnology firms and other private companies. There were no U.S. IPOs in January, the first such month since the eurozone crisis in September 2011, according to data provider Dealogic. Investors and analysts attribute the dearth to the global stock-market rout of the first two weeks of the year, which signaled a broad retreat from risk by investors. If sustained, the reversal threatens to send ripples through global financial markets. Many analysts and traders view a healthy IPO sector as a necessary precondition for a sustainable advance in the broad stock indexes, as dozens of private companies have built their plans around raising cash in the public markets.

In recent years, markets were “wide open and companies that wanted to raise capital could,” said Eddie Yoon, portfolio manager of the Fidelity Select Health Care Portfolio, with $9 billion in assets. But now some companies, both public and private, could face being shut out for an extended period, as many investors seek to reduce risk by focusing on firms with histories of steady profitability and revenue growth. Several new share offerings by already-public biotech companies have floundered this year, not only pricing at steep discounts, but also falling even further the session after pricing. So far this year, new-share offerings by biotech companies have dropped 15% from the time of the announcement of the deal to the end of trading after the sale, according to data from Dealogic. “If the market does reopen, it will be for higher quality companies,” said Mr. Yoon.

Read more …

France wants debt relief?!

• Greece’s Lenders To Start Bailout Review On Monday (Reuters)

Greece’s official lenders will start a review on Monday of what progress the country has made in implementing the economic reforms agreed under its third bailout, a necessary step towards debt relief talks, a finance ministry official said on Saturday. Greece’s international lenders are the IMF and the euro zone bailout fund. The reforms that Greece has to implement in exchange for loans are also reviewed by the ECB and the European Commission. “The first phase will last a few days as there will be a break at the end of next week, after which the institutions will return to conclude the negotiations,” the official said, declining to be named. Athens is keen for a speedy completion of the review, which was expected to begin late last year, and hopes a positive outcome will help boost economic confidence and liquidity.

To secure a positive result from the review Athens needs to pass legislation on pension reforms to render its social security system viable, set up a new privatization fund and come up with measures to attain primary budget surpluses for 2016-2018. A successful conclusion of the performance review will open the way for debt relief talks. The head of the bailout fund, the European Stability Mechanism (ESM), has ruled out a haircut for Greece’s debt but extending debt maturities and deferring interest are options that could be used to make it more manageable. French Finance Minister Michel Sapin told Kathimerini debt relief talks must start soon to help restore Greece’s financial stability. “France’s view is that the sooner the first review is completed, the faster we will be able to tackle the issue of debt sustainability and this will be better for everyone – for Greece as well as the entire euro zone,” Sapin told the paper.

Read more …

Stories from NZ have been bad for a while now.

• Milk Collapse Brings a 45% Pay Cut to England’s Dairy Farmers (BBG)

England’s dairy farmers will see income fall by almost half this year, evidence that the global milk crisis is far from over. Earnings will average 46,500 pounds ($66,500) per farm in England for the 2015-16 season that started in March, the Department for Environment, Food & Rural Affairs said in a report Thursday. That figure, which includes European Union aid payments, is 45 percent below the prior season and the lowest in 9 years. Dairy farmers across Europe are struggling with a collapse in prices after a global oversupply of milk was compounded by slowing demand in China and Russia’s ban on EU dairy in retaliation for sanctions.

Protests over low prices broke out in France this week as more than 100 farmers, many of them livestock breeders, blocked roads and used tractors and burning tires to stop access to the port city La Rochelle. “There’s too much milk in the world,” said Robbie Turner, head of European markets at Rice Dairy International, a risk management advisory firm in London. “There are people who are hard for cash,” and prices are likely to remain low for at least the next six months, he said. On Thursday, Fonterra, the world’s largest dairy exporter, cut its milk price forecast to a nine-year low. The Auckland-based company doesn’t expect a sharp recovery in Chinese demand any time soon.

Read more …

Luckily we’re maxed out.

• ‘Peak Stuff’ And The Search For Happiness (Guardian)

On Monday, Walmart will start paying a minimum of $10 an hour to its 1.4 million skilled staff in America – in conventional economists’ terms, a ludicrous and unnecessary transfer of income from capital to labour. But, facing the same retail environment as Apple and Ikea, Walmart wants to motivate its frontline staff into being more engaged and innovative. Consumers want some help in understanding and interpreting their particularities, help in answering the question of what, in a profound sense, their spending is for. When you have enough, what need is being served by having more?

Economists are not equipped to address such phenomena. Faltering growth in consumer demand in all western countries is understood wholly in traditional economic terms: the story is that consumers are indebted and uncertain, they lack confidence and want to rebuild their savings. Rightwing, anti-state economists, so influential in the Republican and Conservative parties, peddle tax cuts as the universal panacea. Like Pavlov’s dog, consumers will flock back to the shops once they are emboldened by a tax cut. Obviously, there would be some increase in spending, but far less than there used to be. More fundamental forces are holding back spending .

There is a quest for meaning, aided and abetted by the knowledge and information revolutions, that is not answered by traditionally scale-produced goods and services. Economist Tomas Sedlacek, who has won an international following for his book Economics of Good and Evil, insists that contemporary societies have become slaves to a defunct economistic view of the world. When western societies were poorer, it was reasonable for economics to focus on how to produce more stuff – that was what societies wanted. Now, the question is Aristotelian: how to live a happy life – or “humanomics”, as Sedlacek calls it. Aristotle was clear: happiness results from deploying our human intelligence to act creatively on nature. To inquire and successfully to quest for understanding is the root of happiness.

Yet most people today, says Sedlacek, work in jobs they do not much like, to buy goods they do not much value – the opposite of any idea of the good life, Aristotelian or otherwise. What we want is purpose and a sense of continual self-betterment, which is not served by buying another iPhone, wardrobe or a kitchen. Yet purpose and betterment need a social context: purpose is a shared endeavour and self-betterment is to act on the world better with others. An individualistic society such as our own makes it much harder to find others with whom to make common cause.

Read more …

Well, stop the war then.

• Merkel Says Refugees Must Return Home Once War Is Over (Reuters)

German Chancellor Angela Merkel tried on Saturday to placate the increasingly vocal critics of her open-door policy for refugees by insisting that most refugees from Syria and Iraq would go home once the conflicts there had ended. Despite appearing increasingly isolated, Merkel has resisted pressure from some conservatives to cap the influx of refugees, or to close Germany’s borders. Support for her conservative bloc has slipped as concerns mount about how Germany will integrate the 1.1 million migrants who arrived last year, while crime and security are also in the spotlight after a wave of assaults on women in Cologne at New Year by men of north African and Arab appearance.

The influx has played into the hands of the right-wing Alternative for Germany (AfD), whose support is now in the double digits, and whose leader was quoted on Saturday saying that migrants entering illegally should, if necessary, be shot. Merkel said it was important to stress that most refugees had only been allowed to stay for a limited period. “We need … to say to people that this is a temporary residential status and we expect that, once there is peace in Syria again, once IS has been defeated in Iraq, that you go back to your home country with the knowledge that you have gained,” she told a regional meeting of her Christian Democratic Union (CDU) in the state of Mecklenburg-Western Pomerania.

Merkel said 70 percent of the refugees who fled to Germany from former Yugoslavia in the 1990s had returned. Horst Seehofer, leader of the Christian Social Union (CSU), the CDU’s Bavarian sister party, has threatened to take the government to court if the flow of asylum seekers is not cut. Merkel urged other European countries to offer more help “because the numbers need to be reduced even further and must not start to rise again, especially in spring”. Fabrice Leggeri, the head of the European Union’s border agency Frontex, said a U.N. estimate that up to a million migrants could try to come to Europe via the eastern Mediterranean and Western Balkans next year was realistic. “It would be a big achievement if we could keep the number … stable,” he told the magazine Der Spiegel.

Read more …

Europe doesn’t care for kids.

• 10,000 Refugee Children Are Missing, Says Europol (Observer)

At least 10,000 unaccompanied child refugees have disappeared after arriving in Europe, according to the EU’s criminal intelligence agency. Many are feared to have fallen into the hands of organised trafficking syndicates. In the first attempt by law enforcement agencies to quantify one of the most worrying aspects of the migrant crisis, Europol’s chief of staff told the Observer that thousands of vulnerable minors had vanished after registering with state authorities. Brian Donald said 5,000 children had disappeared in Italy alone, while another 1,000 were unaccounted for in Sweden. He warned that a sophisticated pan-European “criminal infrastructure” was now targeting refugees.

“It’s not unreasonable to say that we’re looking at 10,000-plus children. Not all of them will be criminally exploited; some might have been passed on to family members. We just don’t know where they are, what they’re doing or whom they are with.” The plight of unaccompanied child refugees has emerged as one of the most pressing issues in the migrant crisis. Last week it was announced that Britain would accept more unaccompanied minors from Syria and other conflict zones. According to Save the Children, an estimated 26,000 unaccompanied children entered Europe last year. Europol, which has a 900-strong force of intelligence analysts and police liaison officers, believes 27% of the million arrivals in Europe last year were minors.

“Whether they are registered or not, we’re talking about 270,000 children. Not all of those are unaccompanied, but we also have evidence that a large proportion might be,” said Donald, indicating that the 10,000 figure is likely to be a conservative estimate of the actual number of unaccompanied minors who have disappeared since entering Europe. In October, officials in Trelleborg, southern Sweden, revealed that some 1,000 unaccompanied refugee children who had arrived in the port town over the previous month had gone missing. On Tuesday a separate report, again from Sweden, warned that many unaccompanied refugees vanished and that there was “very little information about what happens after the disappearance”.

Read more …

But they think they can stop it.

• Aegean Sea Refugee Crossings Rise 35 Fold Year-On-Year In January (Guardian)

More than 52,000 refugees and migrants crossed the eastern Mediterranean to reach Europe in the first four weeks of January, more than 35 times as many as attempted the crossing in the same period last year. The daily average number of people making the crossing is nearly equivalent to the total number for the whole month of January as recently as two years ago, according to the International Organisation for Migration. More than 250 people have died attempting to make the crossing this month, including at least 39 who drowned in the Aegean Sea on Saturday morning after their boat capsized between Turkey and Greece. Turkish coastguards rescued 75 others from the sea near the resort of Ayvacik on Saturday, according to the Anadolou news agency.

They had been trying to reach the Greek island of Lesbos. The eastern route into Europe, via Greece, has overtaken the previously popular central Mediterranean route from north Africa over the past year. Refugees have continued to use the route all winter, despite rough seas and strong winds. “An estimated 52,055 migrants and refugees have arrived in the Greek islands since the beginning of the year,” the IOM said. “This is close to the total recorded in the relatively safe month of July 2015, when warm weather and calm seas allowed 54,899 to make the journey.” Turkey, which is hosting at least 2.5 million refugees from the civil war in neighbouring Syria, has become the main launchpad for migrants fleeing war, persecution and poverty.

Ankara struck a deal with the EU in November to halt the flow of refugees, in return for €3bn (£2.3bn) in financial assistance to help improve the refugees’ conditions. This week the IOM reported that a survey of migrants and refugees arriving in Greece showed 90% were from Syria, Iraq or Afghanistan. People of those nationalities are allowed to leave Greece and enter Macedonia en route to western Europe as asylum seekers. But on Wednesday the Idomeni border crossing from Greece to Macedonia remained closed from midday to midnight. Macedonian officials blamed congestion at the border with Serbia.

Read more …

“Why is Greece guilty? Because it doesn’t let them drown?”
• Greeks Worry Threatened Closure Of EU Border ‘Definition Of Dystopia’ (Guar.)

With Brussels contemplating drastic measures to stem the flow, calls are mounting to seal the Greek-Macedonian border, raising fears of hundreds of thousands being stranded in Greece, the country now perceived to be the continent’s weakest link. The prospect of migrants being trapped in a member state that financially is also Europe’s most fragile may once have seemed extreme, even absurd. Its economy ravaged by six years of internationally mandated austerity and record levels of unemployment, Greece’s coping strategies are markedly strained. But as EU policymakers seek ever more desperate ways to deal with what has become the largest mass movement of people since the second world war, it is an action plan being actively worked on by mandarins at the highest level.

Like so much else in the great existential crisis facing Europe, a proposed policy that was once seen as bizarre now looks like it could become real. Last week Athens was also given a three-month ultimatum to improve the way it processes arrivals and polices its borders – at nearly 8,700 miles the longest in Europe – or face suspension from the passport-free Schengen zone. Closure of the Greek-Macedonian frontier would effectively cut it out of that fraternity. Those who have watched Greece’s rollercoaster struggle to keep insolvency at bay are united in their conviction that the move would be catastrophic. “It would place a timebomb under the foundations of Greece,” says Aliki Mouriki at the National Centre of Social Research. “Hundreds of thousands of refugees trapped in a country that is bankrupt, that has serious administrative and organisational weaknesses, with a state that is unable to provide for their basic needs?”
The question hangs in the air while she searches for the right word. “What we would witness,” she adds, “would be the definition of dystopia.” Like the mayors who have been forced to deal with the emergency on Greece’s eastern Aegean isles, federal politicians believe Turkey is the root of the problem. “With all due respect for a country that is hosting 2 million refugees, it is Turkey that must do something to stop the organised crime, the smugglers working along its coast,” Yannis Mouzalas, the minister for migration policy, told the Observer. “These flows are not Greece’s fault even if, it is true, we have been slow to set up hotspots and screening was not always what it should have been,” he said. “It is Turkey that turns a blind eye to them coming here. It is Turkey that must stop them. Why is Greece guilty? Because it doesn’t let them drown?”

Read more …

Morals? Europe?

• Europe’s Immigration Bind: Morals vs Votes (Guardian)

The dream of free movement within the EU has also spawned paranoia about the movement of people into the EU. The quid pro quo for Schengen has been the creation of a Fortress Europe, a citadel against immigration, watched over by a hi-tech surveillance system of satellites and drones and protected by fences and warships. When a journalist from Germany’s Der Spiegel magazine visited the control room of Frontex, the EU’s border agency, he observed that the language used was that of “defending Europe against an enemy”. Many of the policies enacted over the past year give a sense of a continent at war. In June, an emergency EU meeting came up with a 10-point plan that included the use of military force “to capture and destroy” the boats used to smuggle migrants.

Soon afterwards, Hungary and other east European countries began erecting razor-wire fences. Germany, Austria, France, Sweden and Denmark suspended Schengen rules and reintroduced border controls. In November, the EU struck a deal with Turkey, promising it up to $3.3bn in return for clamping down on its borders. This month, Denmark passed a law allowing it to seize valuables from asylum seekers to pay for their upkeep. Despite the sense that the crisis is unprecedented, there is nothing new in it or the incoherence of the EU’s response. People have been trying to enter the EU, and dying in the attempt, for a quarter of a century and more.

Until 1991, Spain had an open border with North Africa. Migrant workers would come to Spain for seasonal work and then return home. In 1986, the newly democratic Spain joined the EU. As part of its obligations as a EU member, it had to close its North African borders. Four years after it did, it was admitted into the Schengen group. The closing of the borders did not stop migrant workers trying to enter Spain. Instead, they took to small boats to cross the Mediterranean. On 19 May 1991, the first bodies of clandestine migrants were washed ashore. Since then, it is estimated that more than 20,000 people have perished in the Mediterranean while trying to enter Europe.

Read more …

Every day.

• 39 Greece-Bound Refugees Drown Off Turkish Coast (AP)

Turkey’s state-run news agency says at least 39 people, including five children, have drowned in the Aegean Sea after their Greece-bound boat capsized off the Turkish coast. Anadolu Agency says coast guards rescued 75 others from the sea Saturday near the resort of Ayvacik en route to the Greek island of Lesbos. The agency has identified the survivors as natives of Afghanistan, Syria and Myanmar. The International Organization for Migration says 218 people have died this year while trying to cross by sea from Turkey to Greece. Turkey is hosting an estimated 2.5 million refugees from Syria. In November, Turkey agreed to fight smuggling networks and stem the flow of migrants into Europe. In return, the EU has pledged €3 billion to help improve the refugees’ conditions.

Read more …