Jun 012018
 
 June 1, 2018  Posted by at 1:01 pm Finance Tagged with: , , , , , , , , , , , , ,  1 Response »


Nikolay Dubovsky Became Silent 1890


“European Stocks Surge Celebrating New Spanish, Italian Governments”, says a Zero Hedge headline. “Markets Breathe Easier As Italy Government Sworn In”, proclaims Reuters. And I’m thinking: these markets are crazy, and none of this will last more than a few days. Or hours. The new Italian government is not the end of a problem, it’s the beginning of many of them.

And Italy is far from the only problem. The new Spanish government will be headed by Socialist leader Pedro Sanchez, who manoeuvred well to oust sitting PM Rajoy, but he also recently saw the worst election result in his party’s history. Not exactly solid ground. Moreover, he needed the support of Catalan factions, and will have to reverse much of Rajoy’s actions on the Catalunya issue, including probably the release from prison of those responsible for the independence referendum.

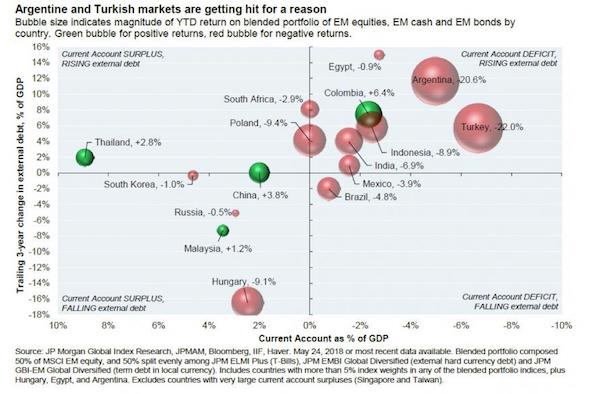
Nor is Spain exactly economically sound. Still, it’s not in as bad a shape as Turkey and Argentina. A JPMorgan graph published at Zero Hedge says a lot, along with the commentary on it:

The chart below, courtesy of Cembalest, shows each country’s current account (x-axis), the recent change in its external borrowing (y-axis) and the return on a blended portfolio of its equity and fixed income markets (the larger the red bubble, the worse the returns have been). This outcome looks sensible given weaker Argentine and Turkish fundamentals. And while Cembalest admits that the rising dollar and rising US rates will be a challenge for the broader EM space, most will probably not face balance of payments crises similar to what is taking place in Turkey and Argentina, of which the latter is already getting an IMF bailout and the former, well… it’s only a matter of time.


And now Erdogan has apparently upped the ante once more yesterday. Last week he called on the Turkish population to change their dollars and euros into lira’s, last night he ‘suggested’ they bring in their money from abroad (to profit from ‘beneficial tax rules’). Such things have, by and large, one effect only: the opposite of what he intends. He just makes his people more nervous than they already were.

It’s June 1, and the Turkish elections are June 24. Will Erdogan be able to keep things quiet enough in the markets? It’s doubtful. He has reportedly already claimed that the US and Israel are waging an economic war on Turkey. And for once he may be right. A few weeks ago Erdogan called on all member states of the Organisation of Islamic Cooperation to boycott all Israeli products (and presumably America products too).

On April 30, the IMF warned that the Turkish economy is showing “clear signs of overheating”. On May 1, Standard & Poor’s downgraded the Turkish economy to double-B-minus. Economic war? Feels a bit more like a political war. Erdogan has three weeks left to win that election. Don’t expect things to quieten down before then. But as the graph above shows, Turkey itself is the problem here first and foremost.

Expect Erdogan to say interest rates -usury- are immoral in Muslim countries. Expect much more pressure from the west on him. Erdogan has also been busy establishing Turkish ‘enclaves’ in Syria’s Afrin territory (where he chased out the original population) and in the Turkish-occupied northern part of Cyprus (where he added 100s of 1000s of Turks).

No, the West wouldn’t mourn if the man were defeated in the vote. They can add a lot more pressure in three weeks, and they will. Will it suffice? Hard to tell.


Back to Italy. Where the optimism comes from, I can’t fathom. The M5S-Lega coalition has never made a secret of its program and/or intentions. Just because pronounced eurosceptic Paolo Savona was shifted from Finance to EU minister doesn’t a summer make. New Finance minster Tria may be less outspoken than Savona, but he’s no europhile, and together the two men can be a woeful pain in Europe’s behind. This is Italy. This is not Sparta.

The essence of the M5S-Lega program is painfully simple: they reject austerity as the basics of economic policy. And austerity is all that Europe’s policy has been based on for the past decade at least. That spells collision course. And there is zero indication that the new coalition is willing to give an inch on this. Tsipras may have in Greece, but Italy’s sheer size means it has a lot more clout.

To begin with, the program wants to do away with the Eurozone’s 3% deficit rule. It speaks of a 15-20% flat tax, and a €780 basic income. These two measures would cost between €109 billion and €126 billion, or 6 to 7% of Italian GDP. As Italy’s public debt stand at €2.4 trillion, 132% of GDP.

“The government’s actions will target a programme of public debt reduction not through revenue based on taxes and austerity, policies that have not achieved their goal, but rather through increased GDP by the revival of internal demand,” the program says. Yes, that is the opposite of austerity.

The parties want a roll-back of previously announced pension measures to a situation where the sum of a person’s age and years of social security contributions reach 100. If someone has worked, and contributed to social security for 40 years, they will be able to retire at 60, not at 67 as the present plans demand.

In an additional plan that will make them very popular at home amongst the corrupt political class, the parties want to slash the number of parliamentarians to 400 MPs (from 630) and 200 senators (from 318). They would be banned from changing political parties during the legislature.


And then there are the mini-Bots, a parallel currency system very reminiscent of what Yanis Varoufakis proposed for Greece. Basically, they would allow the government to pay some of its domestic obligations (suppliers etc.) in the form of IOUs, which could then in turn be used to pay taxes and -other- government services. They would leave what is domestic, domestic.

There’s a lot of talk about this being a first step towards leaving the euro, but why should that be so? The main ‘threat’ lies in the potential independence from Brussels it may provide a country with. But it’s a closed system: you can’t pay with mini-Bots for trade or other international obligations.

Italy, like an increasing number of Eurozone nations, is looking for a way to get its head out of the Brussels/Berlin noose that’s threatening to suffocate it. If the EU doesn’t react to this, and soon, and in a positive manner it will blow itself up. Yes, if Italy started to let its debt balloon, the European Commission could reprimand it and issue fines. But the Commission wouldn’t dare do that. This is Italy. This is not Sparta.

Anyway, risk off, as the markets suggest(ed) this morning? Surely you’re joking. And we haven’t even mentioned Trump’s trade wars yet. Risk is ballooning.


May 282018


Brassaï La Bande du Grand Albert 1931-32


President Mattarella Of Italy: From Moral Drift To Tactical Blunder (Varoufakis)
Italy President Vetoes Savona As Economy Minister, May Mean New Election (R.)
Italy’s President Calls In Former IMF Official Amid Political Turmoil (R.)
First Greece, Now Italy, Portugal Next? (ZH)
Corporate Debt Soars While Credit Ratings Fall (Harry Dent)
Fed Relies On Biased Data That Makes ‘B- Economy’ Look Like ‘A+’ – Bianco (CNBC)
Blowing Up the Iran Deal Brings Eurasia Closer to Integration (Pieraccini)
Sudden Chaos In Spanish Politics (Spain Report)
Spain Struggling To Deal With Escalating Migration Crisis (G.)
Google, Facebook Hit With $8.8 Billion In Lawsuits on New EU Privacy Rules (ZH)
US Congressman: F-35s Could Be ‘Used Against Greece’ If Sold To Turkey (K.)
Huge Rise In Food Redistribution To People In Need Across UK (G.)
In Britain, Austerity Is Changing Everything (NYT)
‘We’re Gonna Keep Riding Till We Get Everybody Back Home, From All Wars’ (AFP)


“The formation of another ‘technical’ government, under a former IMF apparatchik, is a fantastic gift to Mr Salvini.”

President Mattarella Of Italy: From Moral Drift To Tactical Blunder (Varoufakis)

I concede that there are issues over which I would welcome the Italian President’s use of constitutional powers that (in my humble opinion) he should not have. One such issue is the outrageous policy of the Lega and the promise of its leader, Mr Salvini, to expel five hundred thousand migrants from Italy. Had President Mattarella refused Mr Salvini the post of Interior Minister, on the basis that he rejects such a monstrous project, I would be compelled to support him. But, no, Mr Mattarella had no such qualms. Not even for a moment did he consider vetoing the formation of a 5S-Lega government on the basis that there is no place in a European country for scenes involving security forces rounding up hundreds of thousands of people, caging them, and forcing them into trains, buses and ferries before expelling them goodness knows where.

No, Mr Mattarella vetoed the formation of a government backed by an absolute majority of lawmakers for another reason: His disapproval of the Finance Minister designate. And what was this disapproval based on? The fact that the said gentleman, while fully qualified for the job, and despite his declaration that he would abide by the EU’s eurozone rules, has in the past expressed doubts about the eurozone’s architecture and has favoured a plan of euro exit just in case it is needed. It was as if President Mattarella were to declare that reasonableness in a prospective Finance Minister constitutes grounds for his or her exclusion from the post!

Let’s face it: There is no thinking economist anywhere in the world who does not share a concern about the eurozone’s faulty architecture. And there is no prudent finance minister who does not have a plan for euro exit; indeed, I have itr on good authority that the German finance ministry, the ECB, every major bank and corporation have plans in place for the possible exit from the eurozone of Italy, even of Germany. Is Mr Mattarella telling us that only the Italian Finance Minister is not allowed to imagine having such a plan? Beyond his moral drift (as he condones Mr Salvini’s industrial-scale misanthropy while vetoing a legitimate concern about the eurozone’s capacity to let Italy breathe in its midst), President Mattarella has made a major tactical blunder.

In short, he fell right into Mr Salvini’s trap. The formation of another ‘technical’ government, under a former IMF apparatchik, is a fantastic gift to Mr Salvini. Mr Salvini is secretly salivating at the thought of another election – one that he will fight not as the misanthropic, divisive populist that he is but as the defender of democracy against the Deep Establishment. Already last night hescaled the high moral with the stirring words: “Italy is not a colony, we are not slaves of the Germans, the French, the spread or finance.”

Read more …

More than half of Italy feel utterly betrayed by their own president.

Italy President Vetoes Savona As Economy Minister, May Mean New Election (R.)

Italy’s president rejected Prime Minister-designate Giuseppe Conte’s pick for the economy ministry, a political source said on Sunday, a veto that may lead to another election this year.Conte, a little-known law professor with no political experience, took his list of ministers to President Sergio Mattarella, but the president rejected Conte’s candidate to the Economy Ministry, the 81-year-old eurosceptic economist Paolo Savona. Before Conte or Mattarella had finished their meeting, far-right League leader Matteo Salvini said that the only option now was to hold another election, probably later this year, without directly confirming the president’s veto.

“In a democracy, if we are still in democracy, there’s only one thing to do, let the Italians have their say,” Salvini said in a fiery speech to supporters in central Italy. Salvini and 5-Star leader Luigi Di Maio had met Mattarella informally on Sunday to try to find a solution. “The problem is Savona,” the coalition source said, explaining that the economist had not sufficiently softened some of his more eurosceptic positions. On Sunday, Savona tried to allay concerns about his views in his first public statement on the matter. Savona has been a vocal critic of the euro and the EU, but he has distinguished credentials, including as industry minister in the early 1990s. “I want a different Europe, stronger, but more equal,” Savona said in a statement.

Read more …

Another technocrat. That won’t go well this time around.

Italy’s President Calls In Former IMF Official Amid Political Turmoil (R.)

Italy’s president is expected to ask a former IMF official on Monday to head a stopgap government amidst political and constitutional turmoil, with early elections looking inevitable. President Sergio Mattarella has called in Carlo Cottarelli after two anti-establishment parties angrily abandoned their plans to form a coalition in the face of a veto from the head of state over their choice of economy minister. In a televised address, Mattarella said he had rejected the candidate, 81-year-old eurosceptic economist Paolo Savona, because he had threatened to pull Italy from the single currency. “The uncertainty over our position has alarmed investors and savers both in Italy and abroad,” he said, adding: “Membership of the euro is a fundamental choice. If we want to discuss it, then we should do so in a serious fashion.”

Financial markets tumbled last week on fears the coalition being discussed would unleash a spending splurge and dangerously ramp up Italy’s already huge debt, which is equivalent to more than 1.3 times the nation’s domestic output. After Mattarella’s move, the euro gained ground, adding 0.6% against the Japanese yen and ticking up against other major trading partners as well. The far-right League and anti-establishment 5-Star Movement, which had spent days drawing up a coalition pact aimed at ending a stalemate following an inconclusive March vote, responded with fury to Mattarella, accusing him of abusing his office.

5-Star leader Luigi Di Maio called on parliament to impeach the mild-mannered Mattarella, while League chief Matteo Salvini threatened mass protests unless snap elections were called. “If there’s not the OK of Berlin, Paris or Brussels, a government cannot be formed in Italy. It’s madness, and I ask the Italian people to stay close to us because I want to bring democracy back to this country,” Salvini told reporters. [..] Cottarelli would be a calming choice for the financial markets, but any technocratic administration would likely only be a short-term solution because the majority of parliamentarians have said they would not support such a government.

Read more …

Portugal is supposed to be the Prince of the PIIGS.

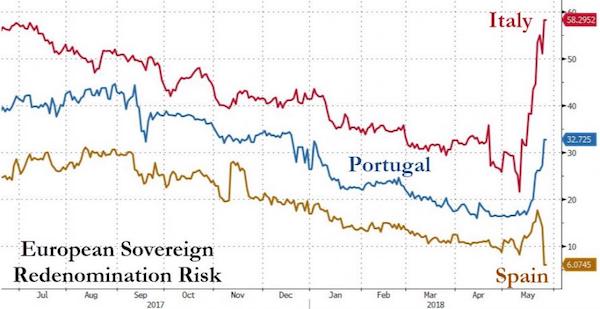
First Greece, Now Italy, Portugal Next? (ZH)

While most investors are focused on Italian politics – the parallel currency ‘mini-BoT’ fears and potential for a constitutional crisis – Spain is now facing its own political crisis amid calls for a no-confidence vote against Rajoy. However, ‘Spaxit’ remains a distant concern for investors as another member of the PIIGS peripheral problems is starting to signal concerns about ‘Portugone’?

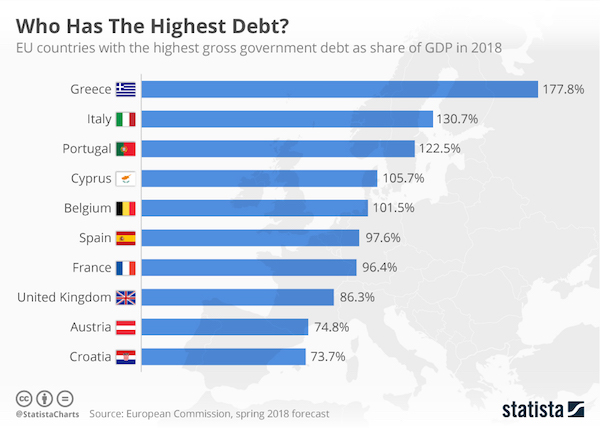
And the fundamental data confirms Portugal is next in line for a debt crisis… As Statista’s Brigitte van de Pas notes, on average, European Union countries had a gross government debt of roughly 81% of GDP in 2018. This average disguises real differences between EU countries. Whereas Greece had a government debt of 177.8% in 2018, Estonia had a debt of only 8.8% – the lowest in the entire EU zone.

While, the high Greek debt is well-known, a number of other countries however also have a debt that is higher than their own GDP. The Italian debt, for example, is lower than the Greek but still significant, at over 130% of GDP. Portugal, in third place, had a debt of 122.5%. One small positive note though: all three countries had even higher debts in 2017, and the European Commission forecasted a slow, but further decrease of their government debt in 2019. Whether this holds true for Italy, with their newly-elected government of Movimento 5 Stelle and Lega remains to be seen.

Read more …

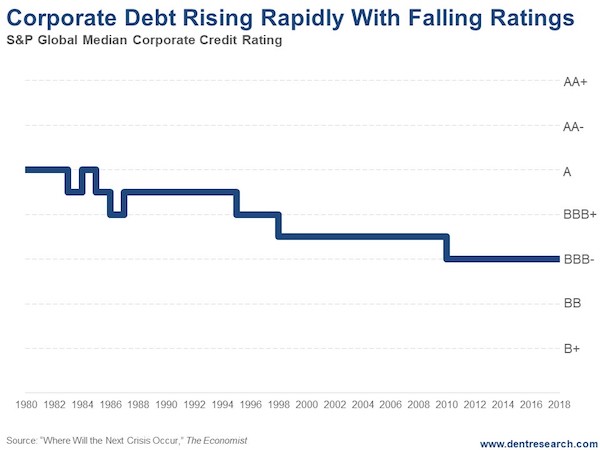
“U.S. corporate debt has risen from $40 trillion to $70 trillion since the top of the last bubble in 2007. That’s 63% in 10 years. It’s risen 135% since 2000! [..] China is the worst by far, going from $6 to $36 trillion or a 500% increase!”

Corporate Debt Soars While Credit Ratings Fall (Harry Dent)

[First], Congress’s approving a bill to roll back the Dodd-Frank Act. If this passes, smaller financial institutions will find relief from the strict rules that have applied to Wall Street banks since after the 2008 crisis. This is sheer idiocy! It will not end well. The second is the U.S. corporate debt is suffering one of its worst sell-offs since 2000. This is another disaster in the making. U.S. corporate debt has risen from $40 trillion to $70 trillion since the top of the last bubble in 2007. That’s 63% in 10 years. It’s risen 135% since 2000! Only government debt has risen faster, from $35 to $64 trillion, or 83%. China is the worst by far, going from $6 to $36 trillion or a 500% increase! Of course, many of these bonds are simply financial engineering to buy back stock to increase earnings per share.

Uber-low long-term interest rates thanks to QE have allowed companies to do this cheaply. The problem is these long-term rates have been rising since just July 2016. They’ve gone from 1.38% to 3.10%. That’s an increase of 172 basis points in the risk-free 10-year Treasury bond. That naturally reverberates up through the risk spectrum from investment grade corporate bonds to junk bonds. You see, here’s the thing…Governments have artificially pushed down bond yields for so long that companies have embraced speculation rather than productive investment (i.e. they’re not spending money on productive assets that will serve them and the economy well in the long-term). This mentality only creates financial asset bubbles that burst.

When companies buy back their own shares at historically high valuations, they’re speculating, just like an investor or hedge fund. When stocks crash ahead, shareholders will demand to know why these corporations used the money they will need to survive the crisis to speculate in their own stock… at the highest prices in history! Well, as the numbers are now showing, this corporate bond bubble is starting to burst, and of course that will ultimately hit junk bonds the worst… then stocks and real estate. But the real story here is that we’ve been in this bond bubble since 1981. And the quality of this corporate debt has been falling for nearly 40 years now. QE has only accelerated the decline. We’re now at the point where the median corporate bond rating is borderline junk…

Read more …

You don’t say…

Fed Relies On Biased Data That Makes ‘B- Economy’ Look Like ‘A+’ – Bianco (CNBC)

A veteran market researcher is out with a warning — saying the Federal Reserve is relying too heavily on economic surveys skewed by social media to mold their policies. According to Bianco Research President James Bianco, most economists mistakenly believe that leading indicators are signaling an “A+” economy that can withstand rising interest rates. “It’s more like a B- economy,” he told CNBC’s “Trading Nation” on Friday. “It’s not this screaming home run that everybody thinks it is based on the survey data.” Bianco said social media is creating the bandwagon effect among survey respondents, a psychological phenomenon characterized by people following the herd.

“The advent of social media is allowing us basically to be inundated with financial news or economic news,” he said, adding the bulk of the news about the world’s largest economy has been largely favorable. “When somebody is asked ‘what do you think about the economy,” they are not answering ‘what do you think about the economy,’ Bianco said. “They are answering ‘What have you read about the economy?'” Bianco fears the Fed will make a policy error based on respondents’ answers. “Economists like at the Fed say ‘Wow, look at that data. It’s even better than we thought. We have to raise rates even faster,'” he said, adding that the tightening could derail the bull market. “The 10-Year [yield] could very well be at 3% by the end of next year with a 3% funds rate,” Bianco said. “[That’s when] you get an inverted yield curve.”

Read more …

Nobo’s popular at home anymore. Except for Putin.

Blowing Up the Iran Deal Brings Eurasia Closer to Integration (Pieraccini)

Washington finds itself increasingly isolated in its economic and military policies. Merkel’s visit to Russia reaffirms the desire to create an alternative axis to the one between Brussels and Washington. The victory in Italy of two parties strongly opposed to new wars and the annulment of the JCPOA, and especially the sanctions against Russia, serves to form a new alliance, accentuating internal divisions within Europe. Macron, Merkel and May are all grappling with a strong crisis of popularity at home, which does not aid them in their decision-making. Exactly the same problems affect MbS, Trump, and Netanyahu in their respective countries. These leaders find themselves adopting aggressive policies in order to alleviate internal problems.

They also struggle to find a common strategy, often displaying schizophrenic behavior that belies the fact that they are meant to be on the same side of the barricades in terms of the desired world order. In direct contrast, China, Russia, Iran, and now India, are trying to respond to Western madness in a rational, moderate, and mutually beneficial way. And as a result, Europeans may perhaps begin to understand that the future lies not in piggybacking on Israel, Saudi Arabia and the United States. Trump seems to have offered the perfect occasion for European leaders to assert their sovereignty and start to move away from their traditional servility shown towards Washington.

Read more …

“This, as the saying goes, could be it.”

Sudden Chaos In Spanish Politics (Spain Report)

PSOE leader Pedro Sánchez really wants to be Prime Minister. The Socialist Party has been mostly flat in the polls for months, slowly trending down from 23% at the beginning of the year to 19% in the Metroscopia poll in El País on May 13. Articles had recently appeared wondering if Mr. Sánchez had anything relevant to say at all. His only notable intervention of late had been a meeting with Mariano Rajoy at Moncloa, the Prime Minister’s office, to agree on a joint response to the challenge posed by Quim Torra, the new separatist First Minister of Catalonia, whom Mr. Sánchez then decided to frame as “Spain’s Le Pen”, “a racist and a supremacist”.

With the publication of the Gürtel fraud case judgement on Thursday, the Socialist Party, which holds 84 out of 350 seats in Congress, has seized on an opportunity to move back into the political spotlight and oust the Popular Party from power with a motion of no confidence. Mariano Rajoy, famously unresponsive as political scandals erupt and opponents die off, wants to stay on as Prime Minister, of course, but this is a serious crisis: El País has characterised it as a “national emergency”. It is such a big mess that the PM felt he had to cancel his trip to Kiev to watch Real Madrid in the Champions League final.

He gave an unscheduled press conference on Friday afternoon, accompanied by his ministers, and accused Mr. Sánchez of wanting to destabilise Spain and wreck the country’s economic recovery. Moncloa sent out an unsigned, unofficial, unstamped “economic report” on Saturday, warning that the socialist motion of no confidence would cost €5 billion and 6,500 jobs. PP spokesman Fernando Martínez Maíllo said Mr. Sánchez would become the “Judas of Spanish politics” if he did a deal with Catalan separatists to take power. The Popular Party and Mr. Rajoy himself—also sliding inexorably downwards in the polls—sense real danger in the PSOE’s move. This, as the saying goes, could be it.

Read more …

“By early May this year, 4,409 people had reached Spain and 217 people had died in the attempt.”

Spain Struggling To Deal With Escalating Migration Crisis (G.)

Spain’s maritime rescue service has rescued hundreds of people trying to cross the Mediterranean into Europe this weekend amid growing concerns that the country is struggling to cope with the migration crisis. The service said its crews had rescued 293 people from nine boats on Saturday. On Sunday, a further 250 migrants were rescued from eight boats, three of which were in poor condition and later sank, they added. The migrants were from various countries in North and sub-Saharan Africa. On a single day in August last year, Spanish rescuers saved 593 people from 15 small paddle boats – including 35 children and a baby – after they attempted to cross the seven-mile Strait of Gibraltar.

According to statistics from the International Organisation for Migration (IOM) 21,468 migrants and refugees arrived in Spain by sea in 2017, with 224 people dying on the journey. The arrival figures showed a threefold increase on 2016, when 6,046 people reached Spain and 128 people died en route. By early May this year, 4,409 people had reached Spain and 217 people had died in the attempt. The UN refugee agency, UNHCR, has already warned that Spain is facing “another very challenging year” when it comes to helping and protecting those arriving on its shores.

Read more …

His case looks solid. But we’re talking the heart of these companies’ business models.

Google, Facebook Hit With $8.8 Billion In Lawsuits on New EU Privacy Rules (ZH)

Accusing Facebook, Google, WhatsApp, and Instagram of “intentionally” violating Europe’s strict new privacy rules that officially went into effect on Friday, Austrian lawyer and privacy activist Max Schrems filed four lawsuits against the tech companies arguing they are still “coercing users into sharing personal data” despite rolling out new policies ostensibly aimed at complying with the new regulations.

Titled the General Data Protection Regulation (GDPR), the new rules require companies to explicitly and clearly request consent from users before mining their data, and Schrems argues in his complaints – which seek fines totaling $8.8 billion – that Google, Facebook, and the Facebook-owned Instagram and WhatsApp are still utilizing “forced consent” strategies to extract users’ data when “the law requires that users be given a free choice unless a consent is strictly necessary for provision of the service,” TechCrunch explains. “It’s simple: Anything strictly necessary for a service does not need consent boxes anymore. For everything else users must have a real choice to say ‘yes’ or ‘no,'” Schrems wrote in a statement.

“Facebook has even blocked accounts of users who have not given consent. In the end users only had the choice to delete the account or hit the ‘agree’-button—that’s not a free choice.” While Facebook—which is currently embroiled in international controversy following the Cambridge Analytica scandal—insists that its new policies are in compliance with Europe’s new regulatory framework, Schrems argues that Facebook and Google aren’t even attempting to follow the new law. “They totally know that it’s going to be a violation, they don’t even try to hide it,” Schrems told the Financial Times. Schrems believes that courts can curtail companies’ ability to poke around in our private lives and wean them off their idea that, “ ‘We’re Silicon Valley, we know what’s right for everybody else.’ ”

Read more …

Strong lobby for this in Washington.

US Congressman: F-35s Could Be ‘Used Against Greece’ If Sold To Turkey (K.)

The United States should freeze the sale of the Lockheed Martin F-35 fighter jets to Turkey because they are more likely to used against Greece than against terrorists, Democratic US Congressman Brad Sherman told US Secretary of State Mike Pompeo, during a Foreign Affairs Hearing on May 23. “I hope that the administration will oppose and prevent the sale of F-35s [to Turkey]. They are not a weapon to be used against terrorists. They are a weapon to be used against Greece,” he said.

A US Senate committee passed earlier this week a defense policy bill that includes a measure to prevent Turkey from purchasing the F-35s, citing the country’s detention of US citizen Andrew Brunson and its agreement with Russia to buy its weapons systems in December. Sherman also called on the State Department not to block a House resolution on genocidal campaigns committed by the Ottoman Empire. “I hope the State Department will at least be neutral should Congress consider, as we are considering, the remembrance of the millions of Armenian, Greek, Assyrian, Chaldean and Syriac victims of the Ottoman Empire at the beginning of the last century,” he added.

Read more …

Fastest growing industry.

Huge Rise In Food Redistribution To People In Need Across UK (G.)

The UK’s largest food redistribution charity is helping to feed a record 772,000 people a week – 60% more than the previous year – with food that would otherwise be , new figures reveal. One in eight people in the UK go hungry every day – with the most needy increasingly dependent on – yet perfectly good food is wasted every day through the food production supply chain. FareShare said it was now redistributing food that otherwise would have been wasted with an annual value of £28.7m, up from £22.4m last year. “Three years ago we were helping to feed 211,000 people a week – today it’s three-quarters of a million,” said FareShare’s chief executive, Lindsay Boswell. “We reported in 2015 that we provided food across 320 towns and cities – now it’s 15,000. It’s not rocket science to see there has been a massive hike in demand for food from frontline charities.”

FareShare currently redistributes about 13,500 tonnes of surplus food every year donated by supermarkets, wholesalers and suppliers to 9,653 charities including hospices, homeless shelters, care homes and women’s refuges, but its annual target is 100,000 tonnes. Demand for surplus food has soared against a background of growing dependence on food banks and rising in the UK. FareShare says it has the capacity – and a waiting list of charities wanting help – but needs access to more food. Its solution is a government fund that would cover the costs of storage and transport. Available to any charity or producer that incurs the costs of redistributing food, it would also save charities and other beneficiaries £150m by making free food available to them. A public petition supporting this move attracted more than 16,000 signatures, which guarantees a government response.

Read more …

People will start leaving in droves sson.

In Britain, Austerity Is Changing Everything (NYT)

For a nation with a storied history of public largess, the protracted campaign of budget cutting, started in 2010 by a government led by the Conservative Party, has delivered a monumental shift in British life. A wave of austerity has yielded a country that has grown accustomed to living with less, even as many measures of social well-being — crime rates, opioid addiction, infant mortality, childhood poverty and homelessness — point to a deteriorating quality of life. When Ms. Lewis and her husband bought their home a quarter-century ago, Prescot had a comforting village feel. Now, core government relief programs are being cut and public facilities eliminated, adding pressure to public services like police and fire departments, just as they, too, grapple with diminished funding.

By 2020, reductions already set in motion will produce cuts to British social welfare programs exceeding $36 billion a year compared with a decade earlier, or more than $900 annually for every working-age person in the country, according to a report from the Center for Regional Economic and Social Research at Sheffield Hallam University. In Liverpool, the losses will reach $1,200 a year per working-age person, the study says. “The government has created destitution,” says Barry Kushner, a Labour Party councilman in Liverpool and the cabinet member for children’s services. “Austerity has had nothing to do with economics. It was about getting out from under welfare. It’s about politics abandoning vulnerable people.”

Read more …

They should do that for all Americans stationed abroad today. Bring the living ones home while they’re still alive.

‘We’re Gonna Keep Riding Till We Get Everybody Back Home, From All Wars’ (AFP)

Wearing bandanas, cowboy hats or gleaming helmets, tens of thousands of bikers descended on Washington Sunday to parade in honor of US soldiers missing in action in foreign wars, a now 30-year-old tradition known as “Rolling Thunder.” “We’re gonna keep riding until we get everybody back home, from all wars,” said Jack Richardson, who at 73 crossed the country from California for the 13th time to participate in the annual Memorial Day weekend spectacular. Dressed in a leather jacket emblazoned with patches, this Vietnam War veteran had assembled with thousands of other bikers in a parking lot near the Pentagon, awaiting the start of the parade.

The route will take them into the center of official Washington, past the monuments on the National Mall and the austere black marble memorial engraved with the names of the nearly 60,000 US soldiers killed during the Vietnam War. “Still there are families waiting back home here in the United States that have not found out where their dads, their fathers, their brothers – they don’t know where they are,” said Richardson, a retired Los Angeles police officer who served two tours in Vietnam in the 1960s. “They don’t know if they’re still in Vietnam, they don’t know if they’re still alive, they don’t know if they’re dead, they don’t know if they’re captured,” he said.

According to organizers, more than 85,000 US soldiers remain unaccounted for in conflicts as far back as World War I. Most are from World War II, but 1,598 of the missing are from the war in Vietnam, a conflict still fresh in the memories of older veterans. The parade was begun in 1988 with some 2,500 motorcycles under the motto “We will never forget” to press for an accounting of the Vietnam missing. It has grown every year since into a rumbling, roaring extravaganza that organizers say attracts over a million people, including spectators. Besides the missing, the bikers also come to remember their fallen comrades.

Read more …

May 252018


René Magritte The therapeutist 1937


The Spanish government is about to fall after the Ciudadanos party decided to join PSOE (socialist) and Podemos in a non-confidence vote against PM Rajoy. Hmm, what would that mean for the Catalan politicians Rajoy is persecuting? The Spanish political crisis is inextricably linked to the Italian one, not even because they are so much alike, but because both combine to create huge financial uncertainty in the eurozone.

Sometimes it takes a little uproar to reveal the reality behind the curtain. Both countries, Italy perhaps some more than Spain, would long since have seen collapse if not for the ECB. In essence, Mario Draghi is buying up trillions in sovereign bonds to disguise the fact that the present construction of the euro makes it inevitable that the poorer south of Europe will lose against the north.

Club Med needs a mechanism to devalue their currencies from time to time to keep up. Signing up for the euro meant they lost that mechanism, and the currency itself doesn’t provide an alternative. The euro has become a cage, a prison for the poorer brethren, but if you look a bit further, it’s also a prison for Germany, which will be forced to either bail out Italy or crush it the way Greece was crushed.

Italy and Spain are much larger economies than Greece is, and therefore much larger problems. Problems that are about to become infinitely more painful then they would have been had the countries been able to devalue their currencies. If you want to define the main fault of the euro, it is that: it creates problems that would not have existed if the common currency itself didn’t. This was inevitable from the get-go. The fatal flaw was baked into the cake.


And if you think about it, today the need for a common currency has largely vanished anyway already. Anno 2018, people wouldn’t have to go to banks to exchange their deutschmarks or guilders or francs, they would either pay in plastic or get some local currency out of an ATM. All this could be done at automatically adjusting exchange rates without the use of all sorts of middlemen that existed when the euro was introduced.

Americans and British visiting Europe already use this exact same system. Governments can make strong deals that make it impossible for banks and credit card companies to charge more than, say, 1% or 0.5%, on exchange rate transactions. This would be good for all cross-border trade as well, it could be seamless.

Technology has eradicated the reason why the euro was introduced in the first place, and made it completely unnecessary. But the euro is here, and it is going to cause a lot more pain and mayhem. Any country that even thinks about leaving the system will be punished hard, even if that’s the by far more logical thing to do.

Europe is not ready to call for the end of the experiment. Because so much reputation and ego has been invested in it, and because the richer nations and their banks still benefit -hugely- from the problems the poorer face. The one country that got it right was Britain, when it decided to stay out of the eurozone.

But then they screwed up the next decision. And found themselves with the most incompetent ever group of ‘chosen few’ to handle the outcome. Still, anyone want to take out a bet on who’s going to be worse off when the euro whip comes down, Britain or for instance Italy or France? Not me. Close call is the best I can come up with.


The euro was devised and introduced, ostensibly, to solve problems. Problems with cross border trade between European nations, with exchange rates. But instead it has created a whole new set of problems that turn out to be much worse than the ones it was supposed to solve. That’s how and why M5S and the League got to form Italy’s government.

In Spain, if an election is called, and it looks that way, you will either get a left wing coalition or more of the Rajoy-style same. Left wing means problems with the EU, more of the same means domestic problems; the non-confidence vote comes on the heels of yet another corruption scandal for Rajoy’s party.

And let’s not forget that all economic numbers are being greatly embellished all over the continent. If you can claim with a straight face that the Greek economy is growing, anything goes. Same with Italy. It’s only been getting worse. And yeah, there’s a lot of corruption left in these countries, and yeah, Europe could have helped them solve that. Only, it hasn’t, that is not what Brussels focuses on.

Italy for now is the big Kahuna. The EU can’t save it if the new coalition is serious about its government program. But it also can’t NOT save it, because that would mean Italy leaving the euro. And perhaps the EU.

If Italian bonds are sufficiently downgraded by the markets, Mario Draghi’s ECB will no longer be permitted to purchase them. And access to other support programs would depend on doing the very opposite of what the M5S/League program spells out, which is to stimulate the domestic economy. Is that a bad idea? Hell no, it’s just that the eurozone rules forbid it.


The euro has entirely outlived its purpose, and then some. But it exists, and it will be incredibly painful to unravel. The new game for the north will be to unload as much of that pain as possible on the south.

Europe would have been much better off of it had never had the euro. But it does. The politicians and bankers will make sure they’re fine. But the people won’t be.

The euro will disappear because the reasons for it not to exist are much more pressing than for it to do. At least that bit is simple. The unwind will not be.


May 182018


Leonard Misonne Waterloo Place, London 1899


Let me start by saying I have nothing against the English newspaper The Guardian. They publish some good things, on a wide range of topics. But they also produce some real stinkers. And lately they seem to publish quite a few of those. On Wednesday there was an entire series of hit pieces on Julian Assange, which I wrote about in I Am Julian Assange.

And apparently they’re not done. As I said on Wednesday, the relationship between Assange and the paper has cooled considerably, after The Guardian’s initial cooperation with Wikileaks on files Assange had shared with them. But does that excuse hit pieces, personal attacks, innuendo, suggestive and tendentious writing, in bulk?

There was one more article in the hit pieces series on Wednesday:

Assange ‘Split’ Ecuador And Spain Over Catalan Independence

Julian Assange’s intervention on Catalan independence created a rift between the WikiLeaks founder and the Ecuadorian government, which has hosted Assange for nearly six years in its London embassy, the Guardian has learned. Sources who spoke on condition of anonymity said Assange’s support for the separatists, including a meeting in November, led to a backlash from Spain, which in turn caused deep concern within Ecuador’s government. While Assange’s role in the US presidential election has been an intense focus of US prosecutors, his involvement in Spanish politics appears to have caused Ecuador the most pain.

The Ecuadorians cut Assange’s internet connection and ended his access to visitors on 28 March, saying he had breached an agreement at the end of last year not to issue messages that might interfere with other states. Quito has been looking to find a solution to what it increasingly sees as an untenable situation: hosting one of the world’s most wanted men.

In November 2017, Assange hosted two supporters of the Catalan independence movement, whose push for secession from Spain had plunged the country into its worst political crisis since returning to democracy. Assange has said he supported the right to “self-determination” and argued against “repression” from Madrid.

He was visited by Oriol Soler, a Catalan businessman and publisher, and Arnau Grinyó, an expert in online communications campaigns. Their meeting, which was reported by the Spanish press, took place a little over a month after the unilateral Catalan independence referendum, and 13 days after the Spanish government responded to the unilateral declaration of independence by sacking the administration of the then Catalan president, Carles Puigdemont, and assuming direct control of the region.

I think that’s we call ‘leading’. Terminology like “..Assange’s role in the US presidential election..”, “..one of the world’s most wanted men..”, “..unilateral referendum..”, “..unilateral declaration of independence..”, are suggestive, they are meant to paint a picture in the reader’s head. What’s missing is any and all mention of the brutal violence in Catalunya on referendum day. That, too, has a purpose.

Assange has been a vocal critic of Madrid’s handling of the Catalan crisis and described the independence movement as “the redefinition of the relationship between people and state”, and “the most disciplined Gandhian project since Gandhi”. A Spanish diplomat told the Guardian that Spain “conveyed a message” to Ecuadorian authorities that Assange was using social media to support the secessionist movement and sending out messages “that are at odds with reality”.

A billion people have been critics of what happened around the referendum. So why not Assange? For what reason did he need to be shut up? Everyone can speak their mind, but not him? We no longer have freedom of speech? Isn’t that something a newspaper, most of all, first of all, should stand up for? An embassy of a democratic nation? No, not a word.

[..] “Spain has, on a number of occasions, informed the Ecuadorian authorities of its concerns over the activities that Julian Assange has engaged in while in the Ecuadorian embassy in London.” [..]In December, Ecuador’s president, Lenín Moreno, reminded Assange that he should refrain from trying to intervene in Ecuadorian politics.

US intelligence agencies and Spanish authorities have separately claimed that Russia has had a hand in their domestic affairs. US agencies have accused WikiLeaks of working with Russian intelligence to try to disrupt the US election by releasing hacked emails from Hillary Clinton’s 2016 presidential campaign, and Spanish officials have suggested that much of the messaging on social media about the Catalan crisis originated in Russia.

Obviously, Assange has never interfered in Ecuadorian politics. That’s just utter nonsense. But that last bit takes the cherry. There is no proven link between Assange and Russia. There is no proven link between Russia and US elections. There is no proven link between Russia and hacked emails. There is no proof the emails were hacked. And as for Russia interfering in the Catalan referendum: oh, please.

Is this just very very bad journalism, or is it something more? You be the judge. But beware that almost all of this stuff consists of insinuations. It’s an affront to journalism.

Glenn Greenwald interviewed Former Ecuadorian President Rafael Correa after the Guardian pieces came out:

Ecuador’s Ex-President Denounces Treatment of Julian Assange as “Torture”

Former Ecuadorian President Rafael Correa, in an exclusive interview with The Intercept on Wednesday morning, denounced his country’s current government for blocking Julian Assange from receiving visitors in its embassy in London as a form of “torture” and a violation of Ecuador’s duties to protect Assange’s safety and well-being. Correa said this took place in the context of Ecuador no longer maintaining “normal sovereign relations with the American government — just submission.”

Correa also responded to a widely discussed Guardian article yesterday, which claimed that “Ecuador bankrolled a multimillion-dollar spy operation to protect and support Julian Assange in its central London embassy.” The former president mocked the story as highly “sensationalistic,” accusing The Guardian of seeking to depict routine and modest embassy security measures as something scandalous or unusual.

[..] Correa continues to believe that asylum for Assange is not only legally valid, but also obligatory. “We don’t agree with everything Assange has done or what he says,” Correa said. “And we never wanted to impede the Swedish investigation. We said all along that he would go to Sweden immediately in exchange for a promise not to extradite him to the U.S., but they would never give that. And we knew they could have questioned him in our embassy, but they refused for years to do so.” The fault for the investigation not proceeding lies, he insists, with the Swedish and British governments.

But now that Assange has asylum, Correa is adamant that the current government is bound by domestic and international law to protect his well-being and safety. Correa was scathing in his denunciation of the treatment Assange is currently receiving, viewing it as a byproduct of Moreno’s inability or unwillingness to have Ecuador act like a sovereign and independent country.

Maybe we should suggest that somebody may have interfered in Ecuador’s presidential elections?! You know, to get to Assange?!

Then today we read in the Guardian that in the aftermath of its hit series, Ecuador has dismissed security for Assange. Is this when MI6 and the CIA get to move in?

Ecuador To Remove Julian Assange’s Extra Security From London Embassy

The president of Ecuador, Lenin Moreno, has ordered the withdrawal of additional security assigned to the Ecuadorian embassy in London, where WikiLeaks founder Julian Assange has remained for almost six years. The move was announced a day after an investigation by the Guardian and Focus Ecuador revealed the country had bankrolled a multimillion-dollar spy operation to protect and support Assange, employing an international security company and undercover agents to monitor his visitors, embassy staff and even the British police.

Over more than five years, Ecuador put at least $5m (£3.7m) into a secret intelligence budget that protected him while he had visits from Nigel Farage, members of European nationalist groups and individuals linked to the Kremlin.

[..] Ecuador suspended Assange’s communication systems in March after his pointed political comments on Twitter. Assange had tweeted messages challenging Britain’s accusation that Russia was responsible for the poisoning of a Russian former double agent and his daughter in Salisbury.

What? Ecuador muted Assange because he challenged Britain’s accusation -unfounded as far as we can tell- that Russia poisoned the Skripals? But wait. I thought they cut him off because of Spain? Or the US? Now it’s Britain? Everyone and their pet hamster is suspicious of that Skripal story. But again, Assange is not allowed to be?

Oh, and all the terrible, and terribly suspicious, people that came to see him. “Nationalists” and “individuals linked to the Kremlin.” Leading, suggestive, truly repugnant “journalism”.

But then, also today, that same Guardian gives the floor to Melinda Taylor, one of Assange’s lawyers. Do they think that giving her a voice makes up for all the damage they’ve done to Assange, to themselves, to freedom of speech and to journalism? One might be tempted to think so.

Julian Assange Is Suffering Needlessly. Why Not Report That?

Breaking news: a series of articles has been published by the Guardian concerning Julian Assange, splashed over the front pages. The big reveal? That after the UK threatened to invade the Ecuadorean embassy, Ecuador beefed up its security and surveillance at said embassy. And that this costs money. And there is pressure to find a solution to a situation that has been described by the United Nations as illegal and arbitrary detention.

Lost in the lede was this: that Ecuador appears to be hoping “that Assange’s already uncomfortable confinement will become intolerable”. The Oxford dictionary defines “intolerable” as “unbearable, insufferable, unsupportable, insupportable, unendurable, beyond endurance, unacceptable, impossible, more than flesh and blood can stand, too much to bear, past bearing, not to be borne, overpowering (…)”.

Isn’t the headline story that the editor-in-chief of WikiLeaks remains detained without access to fundamental healthcare? And since March this year, has been cut off from the outside world, bar meetings with his lawyers, which have apparently been surveilled?

Assange has won numerous awards for publishing information that has exposed egregious violations of human rights and abuses of state power. He has also won the more dubious prize of being placed in the crosshairs of US government attempts to silence free speech by silencing the publications and publishers that dare to speak freely.


And if only the ongoing Julian Assange tragedy was the only affront to news gathering. But no, there’s still always the Skripals. It looks like the gag order has been lifted. Yesterday, the Sun, which at least doesn’t pretend to be a quality paper, ran this:

Sergei Skripal Still Being Questioned Over Salisbury Nerve Agent Attack

Detectives are still questioning poisoned spy Sergei Skripal as he recovers in hospital, nearly 10 weeks after being attacked with a nerve agent, Sky News has learned. They are trying to piece together the Russian former double agent’s life in retirement in Britain, as more details emerged of his recent activities. They want to know more about his regular train journeys to London, his trips abroad, and his monthly meetings with his alleged former MI6 handler in a Salisbury restaurant. It was reported this week that the 66-year-old had been briefing intelligence agencies in the Czech Republic and Estonia on Russian spies and their methods, giving one lecture as recently as 2016.

Would that activity, years after arriving in Britain in a spy swap with Moscow, have been motive enough for the murder attempt on him and his daughter Yulia? The government insists the Kremlin was responsible for the attack, in which the deadly nerve agent novichok was smeared on the front door handle of Mr Skripal’s Salisbury home. But former KGB officer and espionage historian Alexander Vassiliev said it was more likely the work of the Russian mafia, out to embarrass Vladimir Putin’s regime.

Mr Vassiliev said: “It wasn’t the reason to kill him. I’m sure when Putin released him, and pardoned him, he knew Skripal would be co-operating with British secret services and other European espionage agencies. “All defectors are doing it, they work as consultants, they give lectures, they write books – it’s a normal thing. He had to earn his living somehow – he wouldn’t have been a taxi driver. “Skripal was arrested in 2004 – that was a long time ago and he didn’t know specific details about current objectives or operatives. The Russian government had no reason to kill Skripal – he was nobody and he wasn’t a danger.

Now, that’s funny. He’s been briefing Czech intelligence. The Czech Republic, we learned recently, is one of a group of countries that have the formula for novichok AND have produced small quantities of it. The “it could only have been Russia” narrative is, based on what we know, dead as a door handle.

That was yesterday. And lo and behold, this morning the Guardian writes that Skripal has been discharged from hospital. They got all the info they wanted out of him?

Sergei Skripal Discharged From Salisbury Hospital

The Russian ex-spy Sergei Skripal, who was exposed to a nerve agent, has been discharged from Salisbury district hospital, health officials have said. Skripal’s release follows that of his daughter, Yulia, and DS Nick Bailey, who were also exposed to novichok in March. The hospital said: “While these patients have now been discharged, their right to patient confidentiality remains and limits us from giving detailed accounts of the treatment these individuals received. “However, treating people who are so acutely unwell, having been poisoned by nerve agents, requires stabilising them, keeping them alive until their bodies could produce more enzymes to replace those that had been poisoned.”

Yup, we’re sticking with the ‘novichok from Russia’ story. We’re not going to provide any proof, you will have to believe us. I think that’s the frame we must see this last article in, easily one of the weirdest things I’ve read in a while. And again it’s from the Guardian. “As if” to emphasize the dark and massive threat that is hanging over Britain. Create an atmosphere, paint a picture. Julian Assange and the Russians (and Trump!) against Spain, the US and Britain, those staunch defenders of human rights and ‘our values’.

Almost 100 Police Have Received Psychological Help After Salisbury Attack

Almost 100 Wiltshire police officers and staff have sought psychological support after the nerve agent attack in Salisbury, the Guardian can reveal. Among those who have asked for help were officers who initially responded to the collapse of the former Russian spy Sergei Skripal and his daughter, Yulia, and those who were at or close to the various investigation sites in subsequent days and weeks. Some reported feeling disorientated and anxious while others were concerned about the possible long-term health effects on the public.

Wiltshire’s chief constable, Kier Pritchard, told the Guardian that officers – including himself and other police personnel continued to receive help more than two months after the attack. Pritchard took up the role of head of the force on the day of the attempted murders and said he had personally received the “best support” as he worked through the implications for him and his family of being a high-profile figure in the response to a state-sponsored attack.

One police officer, DS Nick Bailey, spent more than two weeks in hospital after being exposed to the novichok nerve agent and when he was discharged said life would never be the same again.


You know who might have helped us try to find out what really happened to the Skripals? Julian Assange. But he’s been silenced. Where do we turn now? How do we find the truth anymore? Have we effectively all been silenced?


Oct 092017
 
 October 9, 2017  Posted by at 9:04 am Finance Tagged with: , , , , , , , , ,  3 Responses »


Joan Miro The tilled field 1924


CEO Stock Buybacks Parasitize the Economy (Ralph Nader)
The Economy Is Humming. Bankers Are Cheering. What Could Go Wrong? (NYT)
Flatliners (NT)
Schäuble: Another Financial Crisis Is Coming Due To Spiraling Global Debt (ZH)
EU Plan To Prevent Bank Runs Could Backfire, Create Panic (BBG)
Hackers And Fraudsters Are Causing Cryptocurrency Chaos (Ind.)
Is This The Geopolitical Shift Of The Century? (OP)
Tensions Rise As US, Turkey Halt Visitor Visas, Send Lira Tumbling (BBG)
Sanctions Against Russia Have Cost European Union €30 Billion (RT)
Spain is the Blueprint for How All Governments Will Act (Martin Armstrong)
Catalans Call for Talks as Spain Enters Crunch Week (BBG)
Greece Foreclosures Target Seems Unattainable (K.)
Nearly There, But Never Further Away (FP)


And the parasite is killing its host.

CEO Stock Buybacks Parasitize the Economy (Ralph Nader)

The monster of economic waste—over $7 trillion of dictated stock buybacks since 2003 by the self-enriching CEOs of large corporations—started with a little noticed change in 1982 by the Securities and Exchange Commission (SEC) under President Ronald Reagan. That was when SEC Chairman John Shad, a former Wall Street CEO, redefined unlawful ‘stock manipulation’ to exclude stock buybacks. Then after Clinton pushed through congress a $1 million cap on CEO pay that could be deductible, CEO compensation consultants wanted much of CEO pay to reflect the price of the company’s stock. The stock buyback mania was unleashed. Its core was not to benefit shareholders (other than perhaps hedge fund speculators) by improving the earnings per share ratio. Its real motivation was to increase CEO pay no matter how badly such burning out of shareholder dollars hurt the company, its workers and the overall pace of economic growth.

In a massive conflict of interest between greedy top corporate executives and their own company, CEO-driven stock buybacks extract capital from corporations instead of contributing capital for corporate needs, as the capitalist theory would dictate. Yes, due to the malicious, toady SEC “business judgement” rule, CEOs can take trillions of dollars away from productive pursuits without even having to ask the companies’ owners—the shareholders—for approval. What could competent management have done with this treasure trove of shareholder money which came originally from consumer purchases? They could have invested more in research and development, in productive plant and equipment, in raising worker pay (and thereby consumer demand), in shoring up shaky pension fund reserves, or increasing dividends to shareholders.

The leading expert on this subject—economics professor William Lazonick of the University of Massachusetts—wrote a widely read article in 2013 in the Harvard Business Review titled “Profits Without Prosperity” documenting the intricate ways CEOs use buybacks to escalate their pay up to 300 to 500 times (averaging over $10,000 an hour plus lavish benefits) the average pay of their workers. This compared to only 30 times the average pay gap in 1978. This has led to increasing inequality and stagnant middle class wages. [..] In a review of 64 companies, including major retailers such as JC Penny and Macy’s, these firms spent more dollars in stock buybacks “than their businesses are currently worth in market value”! [..] The scholars concluded that “Buybacks are a way of disinvesting – we call it ‘committing corporate suicide’..

Read more …

How much time do I have?

The Economy Is Humming. Bankers Are Cheering. What Could Go Wrong? (NYT)

For decades, the global economy has been defined by dissonance. There has been the Japanese recession. The financial crises in the United States and Europe. And drama in emerging markets throughout. But as central bankers, finance ministers and money managers descend on Washington this week for the fall meetings of the IMF, they will confront an unusual reality: global markets and economies rising in unison. Never mind political turmoil, populist uprisings and threats of nuclear war. From Wall Street to Washington, economists have been upgrading their forecasts for the global economy this year, with the consensus now pointing to an expansion of more than 3% — up noticeably from 2.6% in 2016. Economists from the IMF are likely to follow suit when the fund releases its biannual report on the global economy on Tuesday.

The rosy numbers are noteworthy. But what’s more startling is that virtually every major developed and emerging economy is growing simultaneously, the first time this has happened in 10 years. “In terms of positive cycles, it is difficult to find very many precedents here,” said Brian Coulton, the chief economist at Fitch, the debt ratings agency. “It is the strongest growth we have seen since 2010.” In Japan, a reform-minded government and aggressive action by the central bank have pushed growth to 1.5% — up from 0.3% three years ago. In Europe, strong domestic demand in Germany and robust recoveries in countries like Spain, Portugal and Italy are expected to spur 2.2% growth in the eurozone. That would be more than double its average annual growth in the previous five years.

Aggressive infrastructure spending by China; bold economic reforms by countries including Brazil, Indonesia and India; and rising commodities prices (helping countries such as Russia) have spurred growth in emerging markets. And in the United States, despite doubts about President Trump’s ability to pass a major tax bill, the economy and financial markets chug along. In fact, one of the few large economies not following an upward path is Britain, whose pending exit from the European Union is taking a toll. Having grown at an average annual pace of just over 2% from 2012 to 2016, the British economy is expanding just 1.5% this year. [..] “We are in a boom today, but we should not forget that the financial system is still relatively unstable,” said Jim Reid, a credit strategist at Deutsche Bank.

Mr. Reid, who spices up his market analyses by regaling clients with pop songs on the piano, recently published a detailed study on what he expects will be the causes of the next global financial crisis. Pick your poison: an abrupt slowdown in China, the rise of populism, debt problems in Japan or an ugly outcome to Britain’s move to leave the European Union. His overriding worry, though, is that investors and policy makers aren’t prepared for what will happen when global central banks put a halt to their easy-money policies. Since the 2008 crisis, Mr. Reid noted, central banks have accumulated more than $14 trillion in assets — an amount that exceeds the annual output of China by $3 trillion. What happens when the central banks all start to sell? “This is unprecedented,” Mr. Reid said. “And no one knows what the outcome will be.”

Read more …

Compressed volatility.

Flatliners (NT)

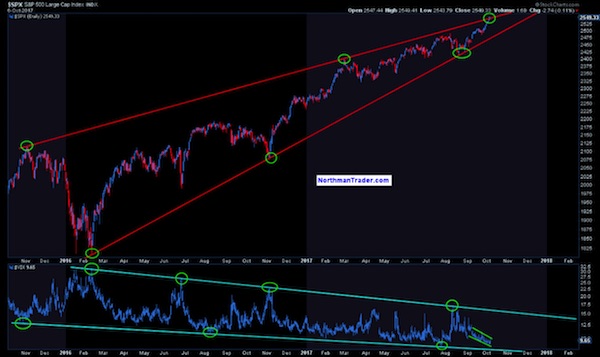
We find ourselves in a very unique point in history and in a world dominated by false narratives. It is a challenge to keep an analytical grip on reality, but I’ll try to tie a few threads together here to put everything in a macro context. Firstly the underlying base reality: Free money, easy money, whatever you want to call it, permeates everything we see in financial markets. Indeed I would argue price appreciation has been paid for with unprecedented and, in my view, unsustainable volatility compression. A couple of charts really highlight this. Most clearly perhaps is the precise trend line tagging we can observe in the correlated picture of price appreciation and volatility compression since the February 2016 lows:

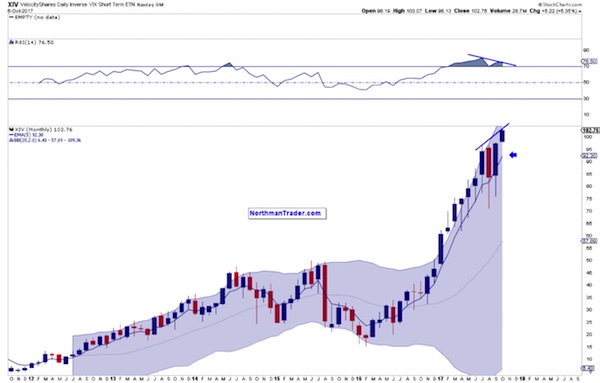
The $VIX’s corollary, the inverse $XIV, embarked on an explosive near one way journey since the US election coinciding with over $2 trillion central bank intervention in just the first 9 months of 2017:

And it has continued to this day and just made another all time high this past week on a massive negative divergence. It is the magnitude of this volatility compression that explains the current trading environment we find ourselves in. Aside from the obvious artificial liquidity avalanche we’ve had speculated about the driver of all this and the answer may simply be the promise of even more free money, specifically tax cuts. As some of you may recall from my analysis over the past year I’ve been very clear that math ultimately will bring out truth in any narrative. In this case that notion that tax cuts pay for themselves is a fantasy. It always has been. Can it result in a short term bump in spending or even growth? Yes it is possible, especially if structured right.

But any historical analysis will show you that tax cuts, especially already coming from a relatively low base, will just add to debt via larger deficits. Recently the White House budget director finally acknowledged this very reality: “a tax plan that doesn’t add to the deficit won’t spur growth” My criticism has been that all this marketing talk is simply a lie and will structurally put the country further at risk of trillion dollar deficits and a massive debt explosion that is already baked in even without tax cuts.

Read more …

But he makes no attempt to apologize?!

Schäuble: Another Financial Crisis Is Coming Due To Spiraling Global Debt (ZH)

Schauble warned that the world was in danger of “encouraging new bubbles to form”. “Economists all over the world are concerned about the increased risks arising from the accumulation of more and more liquidity and the growth of public and private debt. I myself am concerned about this, too,” he said echoing the concern voiced just one day earlier by IMF head Christine Lagarde, said the world was enjoying its best growth spurt since the start of the decade, but warned of “threats on the horizon” from “high levels of debt in many countries to rapid credit expansion in China, to excessive risk-taking in financial markets”. Schäuble also echoed the latest warning from the BIS, which last month said that the world had become so used to cheap credit that higher interest rates could derail the global economic recovery.

Meanwhile, Schäuble defended austerity, saying the word was, “strictly speaking, an Anglo-Saxon way of describing a solid financial policy which doesn’t necessarily see more, or higher deficits as a good thing.” The soon to be former finance minister also took a pot shot at the UK: “The UK always made fun of Rhineland capitalism,” he said, contrasting Germany’s consensus-driven, social market model with Anglo-American free markets and deregulation. “[But] we have seen that the tools of the social market economy were more effective at dealing with the [financial] crisis…than in the places where the crisis arose.”

Of course, Germany’s success – almost entirely a function of the common currency which has effectively kept the Deutsche Mark from soaring – has come at the expense of crisis after crisis among Europe’s southern states. Unfortunately it has resulted in an entire generation of unemployed youth in countries like Greece, Italy and Spain. Still, in keeping with his dour image, Schäuble’s last words were pessimistic: “We have to ensure that we will be resilient enough if we ever face a new economic crisis,” he added. “We won’t always have such positive economic times as we have now” concluded the jolly 75-year-old. Perhaps Wolfi is worrying too much: after all, according to Janet Yellen, “we will not see another crisis in our lifetime.” And if we do, well central banks are primed and ready to injects trillions more to keep the artificial “recovery” and market “all time highs” can kicked just a little bit further.

Read more …

They’ll screw this one up, too.

EU Plan To Prevent Bank Runs Could Backfire, Create Panic (BBG)

Three years since their banking union began to take shape, European Union regulators are seeking fresh powers to deal with lenders in trouble. Their plan would let them stop withdrawals from a failing bank for a few days while they address the problem, with the aim of preventing a run. But this approach could easily have the opposite effect, spreading panic to the whole financial system. There’s a better way. Instead of freezing bank accounts, EU governments should enable regulators to keep a bank going while they restructure it and search for a new owner. This will require EU governments to commit additional resources for the task. The ECB and the euro zone’s Single Resolution Board have been calling for the power to freeze bank accounts – a so-called moratorium – since the swift resolution of Banco Popular in June.

They succeeded in winding down the troubled Spanish lender by selling it to rival Banco Santander, but had to do it on a weekday night with a run on deposits in progress. The regulators say that next time it might be impossible to find a buyer overnight. A moratorium would relieve that pressure and perhaps allow them to sell the bank at a better price. This approach would mirror an arrangement which is currently in place in Germany, and it’s superficially appealing: Closing a bank would certainly stop a run. But it could also have unintended consequences. Depositors may run from a bank in trouble sooner — fearing that if they wait too long they may not be able to withdraw their money. It could also lead depositors to empty their accounts as soon as the bank re-opens. Most dangerous of all, freezing accounts in one bank could spread panic to the rest of the system, as other depositors fear the same will happen to them.

The idea also puts international cooperation on bank resolution at risk. The EU regulators’ plan threatens to disrupt measures put in place after the bankruptcy of Lehman Brothers in 2008. Bank of England economists recently warned in a working paper that adopting the new moratorium might prompt banks to back out of the existing arrangements for handling financial emergencies.

Read more …

An extensive look at crypto. Much better than the headline makes you think.

Hackers And Fraudsters Are Causing Cryptocurrency Chaos (Ind.)

Cryptocurrencies were supposed to offer a secure, digital way to conduct financial transactions but they have been dogged by doubts. Concerns have largely focused on their astronomical gains in value and the likelihood of painful price crashes. Equally perilous, though, are the exchanges where virtual currencies are bought, sold and stored. These exchanges, which match buyers and sellers and sometimes hold traders’ funds, have become magnets for fraud and mires of technological dysfunction, posing an underappreciated risk to anyone who trades digital coins. Huge sums are at stake. As the prices of bitcoin and other virtual currencies have soared this year – bitcoin has quadrupled – legions of investors and speculators have turned to online exchanges.

Billions of dollars’ worth of bitcoins and other cryptocurrencies, which aren’t backed by any governments or central banks, are now traded on exchanges every day. “These are new assets. No one really knows what to make of them,” said David L Yermack, chairman of the finance department at New York University’s Stern School of Business. “If you’re a consumer, there’s nothing to protect you.” Regulators and governments are still debating how to handle cryptocurrencies, and Mr Yermack says the US Congress will ultimately have to take action. Some of the freewheeling exchanges are plagued with poor security and lack investor protections common in more regulated financial markets. Some Chinese exchanges have falsely inflated their trading volume to lure new customers, according to former employees.

There have been at least three dozen heists of cryptocurrency exchanges since 2011; many of the hacked exchanges later shut down. More than 980,000 bitcoins have been stolen, which today would be worth about $4bn. Few have been recovered. Burned investors have been left at the mercy of exchanges as to whether they will receive any compensation. Nearly 25,000 customers of Mt. Gox, once the world’s largest bitcoin exchange, are still waiting for compensation more than three years after its collapse into bankruptcy in Japan. The exchange said it lost about 650,000 bitcoins. Claims approved by the bankruptcy trustee total more than $400m.

Read more …

Not without China, no.

Is This The Geopolitical Shift Of The Century? (OP)

The geopolitical reality in the Middle East is changing dramatically. The impact of the Arab Spring, the retraction of the U.S. military, and diminishing economic influence on the Arab world – as displayed during the Obama Administration – are facts. The emergence of a Russian-Iranian-Turkish triangle is the new reality. The Western hegemony in the MENA region has ended, and not in a shy way, but with a long list of military conflicts and destabilization. The first visit of a Saudi king to Russia shows the growing power of Russia in the Middle East. It also shows that not only Arab countries such as Saudi Arabia and the UAE, but also Egypt and Libya, are more likely to consider Moscow as a strategic ally.

King Salman’s visit to Moscow could herald not only several multibillion business deals, but could be the first real step towards a new regional geopolitical and military alliance between OPEC leader Saudi Arabia and Russia. This cooperation will not only have severe consequences for Western interests but also could partly undermine or reshape the position of OPEC at the same time. Russian president Vladimir Putin is currently hosting a large Saudi delegation, led by King Salman and supported by Saudi minister of energy Khalid Al Falih. Moscow’s open attitude to Saudi Arabia—a lifetime Washington ally and strong opponent of the growing Iran power projections in the Arab world—show that Putin understands the current pivotal changes in the Middle East.

Read more …

Direct result of Turkey’s deal with Russia on Syria.

Tensions Rise As US, Turkey Halt Visitor Visas, Send Lira Tumbling (BBG)

The U.S. and Turkey each suspended visa services for citizens looking to visit the other country, a sharp escalation of a diplomatic spat that sent the lira down more than 6% against the U.S. dollar. The moves followed the Oct. 4 arrest of a Turkish national who works at the U.S. consulate in Istanbul for alleged involvement in the July 2016 coup attempt against President Recep Tayyip Erdogan. Hours after the Trump administration halted visa services in Turkey on Sunday, Erdogan’s government responded in kind, even repeating verbatim much of the U.S. statement. Both sides said “recent events” had forced them to “reassess the commitment” of the other to the security of mission facilities and personnel.

Only two weeks ago, U.S. President Donald Trump had heaped praise on Erdogan when they met on the sidelines of the United Nations General Assembly in New York, saying the Turkish leader “is becoming a friend of mine” and “frankly, he’s getting high marks.” The U.S. on Thursday called charges against the man “wholly without merit,” saying it was “deeply disturbed” by the arrest and “by leaks from Turkish government sources seemingly aimed at trying the employee in the media rather than a court of law.” Turkey responded by saying the arrested Turkish citizen wasn’t part of the U.S. Consulate’s staff but a “local employee.” The lira was at 3.7323 per dollar as of 10:37 a.m. in Singapore on Monday, down more than 3% from Friday’s close, and touched as low as 3.8533. The currency is heading for a seventh day of declines, the longest stretch since May 2016.

Relations between Turkey, a NATO member, and some Western countries soured after the failed 2016 coup. Erdogan has accused U.S.-based Turkish preacher Fethullah Gulen of organizing the attempted overthrow, and has become increasingly impatient with the U.S. for not turning him over. “I would expect that there will be some sort of de-escalation at the leadership level – Trump and Erdogan will speak or meet,” said Murat Yurtbilir, who specializes in Turkish affairs at the Australian National University. “But the underlying problems won’t go away: the Gulen issue, Turkey’s slow switch toward Russia’s policy in Syria and the economy. ”

Read more …

But but but….

Sanctions Against Russia Have Cost European Union €30 Billion (RT)

New research by the Austrian Institute of Economic Research (WIFO) suggests the EU’s economic sanctions against Russia introduced three years ago have cost European countries billions of euro. The survey, which was conducted at the request of the European Parliament and published on Friday, showed EU exports to Russia declining annually by 15.7% since 2014. Up to 40% of that decrease was due to sanctions, it said. As a result of the penalties, Russia has lost its place as EU’s fourth largest trading partner and currently ranks fifth behind the US, Switzerland, China, and Turkey. WIFO calculated EU exports to Russia nosedived from €120 billion four years ago to €72 billion in 2016. According to the research, Cyprus was hit most as exports to Russia plunged 34.5% over the past two years. Greece suffered a 23.2% fall; Croatia’s exports were down 21%.

Austrian exports to Russia dropped by almost ten% or by €1 billion, WIFO said. Poland and the UK have lost €3 billion each. The researchers said the impact of sanctions was most damaging during the first year, as “not much progress has been made in switching trade flows to other countries.” EU sanctions against Russia were introduced in 2014 over the country’s alleged involvement in the conflict in eastern Ukraine. The penalties targeted Russia’s financial, energy, and defense sectors, along with some government officials, businessmen, and public figures. Moscow responded by imposing an embargo on agricultural produce and food and raw materials on countries that joined the anti-Russian sanctions. Since then the sides have repeatedly broadened and extended the restrictive measures.

Read more …

“You can always write a law and claim it is unconstitutional to separate. That does not make it legal, moral, or ethical.”

Moreover, it contradicts the UN Charter.

Spain is the Blueprint for How All Governments Will Act (Martin Armstrong)

What is going on in Spain is the blueprint what what other governments will do. The Spanish people themselves outside of Catalonia are deeply divided. Many see this as offensive and others see the government as offensive. We are looking at the breakup of the USA as well and do not forget the civil war to prevent separatists in America. The real issue is that people ban together for creating society and civilization and then government abuses its power and the process of decline begins. This is throughout history and it really does not matter what culture or country. It is all the same. Spain’s Constitutional Court, the puppet of Rajoy, on Thursday ordered the suspension of Monday’s session of the regional Catalan parliament. Rajoy is demonstrating that government will not tolerate losing power.

You can always write a law and claim it is unconstitutional to separate. That does not make it legal, moral, or ethical. Reuters reported: “The suspension order further aggravated one of the biggest crises to hit Spain since the establishment of democracy on the 1975 death of General Francisco Franco. But Spanish markets rose on perceptions the order might ward off, at least for now, an outright independence declaration.” The structure of the EU in attempting to federalize Europe required a single federal debt. That is what they failed to do so you ended up with a half-baked cake. This is why we have the problems in Europe as we do. But make no mistake about it, this is a political problem and what happens in Europe will be a contagion as it was in 1931. This will eventually cause major problems politically in the States as well.

Justice Scalia I greatly admired. However, his letter on the separatist movement in the USA said that the civil war decided there was no right to separate. I disagree with that opinion, but that is my opinion. There are those who object to my writing about Catalonia from the Madrid side. They create a list of hateful names directed at me personally and then say I know nothing of Spain. They are making the same mistake as government. They assume that government and Rajoy is Spain. The people are the sovereign of Spain – not Rajoy nor his Constitutional Court. If you cannot see that government is supposed to be “elected” by the people, they are not to be the ruler of the people as some monarch, they you have missed the entire point of history. You can hate me all you want, but it is your life you are surrendering to government and that of your posterity. We have a choice. We either understand that government when unchecked will go too far and surrender as sheep, or we stand up and try to make the future better for our posterity.

Read more …

Someone better intervene.

Catalans Call for Talks as Spain Enters Crunch Week (BBG)

A senior member of the Catalan administration called for dialogue with Spain, warning that all of Europe faces economic damage unless a resolution is found to his region’s standoff with the central government in Madrid. After a weekend of mass demonstrations in favor of Spanish unity, Raul Romeva, foreign affairs chief for the separatist government in Barcelona, insisted that the door was open for talks if Prime Minister Mariano Rajoy would grasp the chance of dialogue. “We need two to tango, we need the other side to be at the table,” Romeva said in an interview in Barcelona on Sunday. “We’re always going to be at the negotiation table, but to start negotiations we need the other party to negotiate with.”

The hint of an olive branch came as both sides hurtle toward crunch time in a dispute that threatens the breakup of Spain. Catalan President Carles Puigdemont has vowed to press ahead with his independence drive in a declaration due as soon as Tuesday, while Rajoy pledged that “national unity will be maintained” by using all instruments available to him. “The risk of this getting a lot worse, with correspondingly bad market development for Spanish assets, is still too great for my risk appetite,” said Erik Nielsen, chief economist at UniCredit. He predicted at least another week of pressure on Spanish and Catalan debt and assets before “things will eventually normalize.”

[..] Romeva invoked the crisis in the euro area that sent yields soaring on Spanish government debt and curbed access to finance, warning that the economic fallout of any worsening of the situation won’t be limited to Catalonia. “This simply won’t affect the Catalan economy, it’s going to affect the Spanish economy, it’s going to affect the European economy,” Romeva said. He blamed Madrid for causing the political uncertainty that’s prompted a stampede for the exit. “What causes uncertainty is the incapability of the political central state – or the Spanish state – to provide a political solution,” he said.

Read more …

Since Greece entered the bailout mechanism, foreclosures are down by 89%. Good.

Greece Foreclosures Target Seems Unattainable (K.)

Foreclosures, which have been practically frozen for the last eight years, represent the credit system’s Achilles’ heel. The impact from the paralysis of the auction system is already obvious in banks’ financial results on the reduction of nonperforming loans and threatens to undermine the target set for containing nonperforming exposures (NPEs). The ECB’s Single Supervisory Mechanism (SSM) has asked Greek lenders to bring down their NPEs by €11.5 billion through liquidations (property auctions) up to 2019. Meeting this target requires foreclosures worth €5.5 billion per year while takings from auctions have been poor.

The foreclosures scheduled for this year only concern 5,600 properties, worth €1.1 billion. This is the smallest number of auctions in recent years, given that 2016 (when auctions were held for 4,800 properties) was practically wasted due to protracted strikes by Greece’s lawyers and notaries. This year’s figures actually concern mostly auctions demanded by the state or private lenders, while banks have only instigated few auctions, mainly concerning commercial or industrial properties. For comparison purposes, one has to see the statistics from 2009, before Greece entered the bailout mechanism, when foreclosures numbered 52,000 and their value reached €4.2 billion. This means an 89% drop since then.

Read more …

I’ve said it before: the EU is the mafia.

Nearly There, But Never Further Away (FP)

The guard forced the migrants to kneel and began barking orders in Arabic, a language that few of the once-hopeful souls who had traveled to Libya from sub-Saharan Africa spoke. A gaunt, elderly man in ripped jeans and a tattered T-shirt failed to comply. The guard, wearing a crisp new uniform emblazoned with the insignia of Libya’s anti-illegal immigration police division, raised his wooden club and brought it down hard on the man’s back, driving him face down into the ground with the first blow. It was early May, three weeks after the staff at the Triq al-Sikka migrant detention center in the Libyan capital of Tripoli had received human rights training from the International Organization for Migration (IOM). The guard struck the elderly man again on the back and clubbed the back of his legs.

Then he moved methodically down the line of kneeling migrants, beating each man as if he were responsible for his fellow prisoner’s infraction. Cries of pain echoed through the barren, warehouse-like facility, where more than 100 half-starved migrants were locked away in crowded cells. Some had been there for months, enduring regular beatings and surviving on a few handfuls of macaroni and a single packet of juice each day. Others had recently been rounded up off the streets in raids targeting black African migrants. Soon after the beatings began, other guards at the facility noticed my presence and quickly ushered me into a waiting area outside the well-appointed office of Col. Mohamed Beshr, the urbane head of Libya’s anti-illegal immigration police.

Beshr is a key player in recent joint EU-Libyan efforts to halt migration to Europe, including intercepting migrants at sea and detaining them on land. He has welcomed high-level European diplomats and U.N. representatives to the Triq al-Sikka facility, and his office is filled with certificates from workshops run by IOM, the European Union, and Britain’s development agency. Yet Beshr seemed frustrated by my questions about the abuses openly taking place at the detention center he oversaw. To hear him tell it, his European partners cared about only one thing, even if they wouldn’t say it: preventing migrants from showing up on Italy’s shores. “Are they looking for a real solution to this humanitarian crisis?” Beshr asked, smirking and raising his eyebrows. “Or do they just want us to be the place where migrants are stopped?”

Eighteen months after the EU unveiled its controversial plan to curb illegal migration through Libya — now the primary point of departure for sub-Saharan Africans crossing the Mediterranean Sea to Europe — migrants have become a commodity to be captured, sold, traded, and leveraged. Regardless of their immigration status, they are hunted down by militias loyal to Libya’s U.N.-backed government, caged in overcrowded prisons, and sold on open markets that human rights advocates have likened to slave auctions. They have been tortured, raped, and killed — abuses that are sometimes broadcast online by the abusers themselves as they attempt to extract ransoms from migrants’ families.

The detention-industrial complex that has taken hold in war-torn Libya is not purely the result of a breakdown in order or the work of militias run amok in a state of anarchy. Visits to five different detention centers and interviews with dozens of Libyan militia leaders, government officials, migrants, and local NGO officials indicate that it is the consequence of hundreds of millions of dollars in pledged and anticipated support from European nations as they try to stem the flow of unwanted migrants toward their shores.

Read more …

Sep 262017
 
 September 26, 2017  Posted by at 1:21 pm Finance Tagged with: , , , , , , , , ,  7 Responses »


Fan Ho The Evening of Life 1963


“Forget Germany, Spain Is The Real Problem”, reads a headline. Eh… no. Germany is definitely the problem in Europe. Spain is a bit player. That doesn’t mean nothing major could happen in Spain in its fight with Catalonia, and soon, but Spain, like all EU nations, is a de facto province of Germany.

What matters in the end is how Brussels and Merkel deal with Spain. And while it’s tempting to say that perhaps Brussels, the EU, is the main European problem, the European Union is run exclusively by and for Germany, so that doesn’t work either.

The only thing that might work if you really want to find a bigger issue than Germany is if you would point at the role the incessant lies about economic conditions for people play. But that’s not a European issue, that’s global.

The talk about how economies are recovering, how there’s light at the end of the tunnel, and how any day now we’ll be back to where we were at some point in time that many can not even remember. But then, at least when it comes to Europe, that happy talk comes from Germany too, to a large degree. Just wait till Draghi starts cutting his QE.

You can try and tell people that they’re doing just great, using the media you control, and it’ll work for a stretch, if only because they want to believe it, badly, but when these same people can’t even feed their children while you make such claims, you will eventually lose their attention and support. The difference between beliefs and experiences.


If you’re a politician, you try to feed people what they want to hear, invariably an upbeat message, but there comes a time when you have to back it up. You can say that austerity is necessary, inevitable, and the only choice, and it will be beneficial to them, but austerity is one of those things that have a very limited best before date.

If you can only make employment numbers look good by creating a gig economy that takes away all their benefits, and their entire sense of security, they’re going to turn their backs on you. Because you’re lying.

Rising inequality is a one way street right up to the point where it turns into a dead end alley. Inequality breeds more inequality until it no longer can, until people say ‘I want that cake you are having because my kids are hungry. And I brought a pitchfork’.

That is where we’re at, and that is why Merkel lost some 25% of her votes. That is why there’s Trump and Brexit, and why an impossible candidate like Marine Le Pen in France gathered so much attention and support. It’s why eastern European countries will start fighting Brussels and Berlin much harder than they have to date, and why Berlin will fight back harder than it has. Poor Greece.

In the US, there’s only one party, and it divvies up the spoils of very rich campaign contributions. Bernie Sanders tried to circumvent this; not a chance. Trump succeeded. In Britain, there was no difference between left and right for a long time, and no alternative party either. That led to Brexit. In France, Macron started a whole new party from scratch and somehow got it funded (bankers?!). It wiped the left off the map.

The same happened in Holland, where like in France the right wing alternative was judged too unpalatable by too many. No left left. The leaders of Germany’s Alternative für Deutschland do not have the visibility for that yet. In Italy, Five Star have a good shot at the throne. Greece’s Syriza already overtook both left and right. In eastern Europe, right wing parties often didn’t even have to overthrow an existing order, they could just slide in.


The pattern is so obvious only those who stand to lose from acknowledging it end up not seeing it, or telling themselves it’s all just an incident. But it’s not, because the shrinking economies everywhere are not. When left and right, either in public or in practice, rule a country together and their promises don’t hold up, people will look for a way out. If far right is the only way available, they will pick that.

It’s not because they’re all nazis or something like that. But people do lean towards smaller units of organization, decentralization, when they get poorer. And despite all the talk of recovery, that is what most people have seen happen to their lives, while their leaders told them they’re just fine. So you get this kind of headline (and map) for the US (h/t Mish/ZH).

Large Parts Of America Are Being Left Behind

Economic prosperity is concentrated in America’s elite zip codes, but in an interesting report on Distressed Communities, from The Economic Innovation Group, it is increasingly clear that economic stability outside of those communities is rapidly deteriorating. As Axios noted, this isn’t a Republican or Democratic problem. At every level of government, both parties represent distressed areas. But the economic fortunes of the haves and have-nots have only helped to widen the political chasm between them, and it has yet to be addressed by substantial policy proposals on either side of the aisle. Economic Prosperity Quintiles.


And a very similar headline appears in the Guardian in a report about the German election.


‘A Lot of People Feel Left Behind’: Voters on the Far-Right Surge in Germany

Sarah, 37, teacher, Bonn: “A lot of people feel left behind. They are looking for scapegoats. It is the easy way to deal with problems. The AFD makes use of this feeling. With the grand coalition, there was no real debating culture left. The CDU went too much into the middle, leaving the right out. Just like the SPD under Schröder left the left-wing out.”

Perhaps a lot of those who voted for Trump, and Brexit, Le Pen, Wilders, the AfD, are not so much looking for scapegoats, they’ve identified those as their incumbent politicians; they’re instead looking for a way away from them. All these people who feel left behind base that feeling primarily on their deteriorating economic circumstances. And if the only alternative they have rants, against foreigners and immigrants, they’ll go with that.

Angela Merkel pushed over 1 million refugees and immigrants down the German population’s throats. She never asked their opinion. But many Germans are not doing any better than many Americans or French or British. So the consequences of such things are predictable. You have to explain, you have to communicate with your people. Just saying ‘we can do this’ is not enough. No more than ‘change we can believe in’ was. It’s just hollow.

Merkel lost ‘only’ 25% of her votes. Because Germans know what right wing is, and what it can do. Germany is not full of nazis, no more than America is. Both countries just have a lot of people who feel trapped in a web of lies, and their existing and alleged democratic systems offer no way out of that web.

All these countries, the people and their politicians, have the tendency to see their situations as somehow unique, but they’d be much better off looking at what they have in common with others.

The only solution is to tell people the truth, that the incumbent political class has screwed up badly because of limited brain capacity and unlimited greed, and that they should elect people next time who are both smarter and less sociopathic. But that is not something that comes voluntarily, that takes a battle. And it tends to end careers, and lives.

That is what we can expect. In many different shapes and forms, but all for the same underlying reasons. You can’t fool all of the people all of the time, you can’t even fool a majority for long. You can only fool a limited number of them for a limited amount of time.

Well, time’s up.


Aug 182017
 
 August 18, 2017  Posted by at 8:53 am Finance Tagged with: , , , , , , , , ,  6 Responses »


Edward S. Curtis Slow Bull Dakota Sioux Medicine Man In Prayer 1907


Never Doubt Regression To The Mean (Rosso)
The Stock Market Bubble is So Big Even the Fed’s Talking About It (Phoenix)
Ice-Nine: The Plan To Freeze The Financial System (Rickards)
Neoliberalism: The Idea That Changed The World (G.)
So When Will China’s Debt Bubble Finally Blow Up? (WS)
Charlene Chu Lays Out China’s “Doomsday” Scenario (ZH)
China’s New Problem: Frenzy Of Consumer Lending Creates Debt Explosion (CNBC)
‘Simply Doesn’t Cut It’: Elizabeth Warren Slams Wells Fargo Board Changes (BI)
Deutsche Bank, Bank of America Settle Agency Bond Rigging Lawsuits (R.)
Who Is Lobbying Mike Pence And Why? (IBT)
Mr. President: Close Down More “Advisory Councils” (Rossini)
Spain Lacks Capacity To Handle Migration Surge – UNHCR (G.)


After a week of senseless violence and rhetoric, we could sure do with a medicine man praying for peace. I know, they say this is what the Fourth Turning looks like. But I don’t have to like it. Seeing some of the pictures of traumatized people in Barcelona I couldn’t help thinking how much they looked like those I’ve seen from Syria and Libya. Senseless violence.


Part of a longer piece on retirement distributions. Very strong graph.

Never Doubt Regression To The Mean (Rosso)

Since 1877, secular bull years have totaled 80 vs. 52 for bears, which is a 60/40 ratio. Surprised? Bear markets happen more often than investors are led to believe. They usually occur at times of overvaluation which makes recent retirees or those close to retirement at greater risk of experiencing negative or poor future returns. Bad luck or rotten timing. Either way, it’s going to be important to remain cognizant of portfolio distribution rates, place renewed priority on risk management, and adjust spending accordingly perhaps over the next ten years. Those who were proactive to minimize stock and high-yield bond portfolio risk (like several of the writers for Real Investment Advice), and redeployed capital into stocks at 13x earnings in the summer of 2009, helped new retirees at that time meet their retirement objectives. In addition, they have experienced a cyclical tailwind in stocks that has allowed greater distribution rates. Great luck!

Stock market cycles are vast and span decades. Don’t stumble into a Recency Bias trap where you believe current complacent market conditions lay the path to a smooth, high-return future. Markets are mean reverting mechanisms. Cycles indeed change. Usually, markets are more volatile with periods of 5% pullbacks occurring every 3-4 months. As investors, this year we’ve witnessed shallow retracements followed up by buys on the dips. An environment like this fosters overconfidence. Volatility may excite traders and be helpful to those who are seeking lower prices to purchase risk assets. For those in retirement distribution mode, volatility and corrections have potential to place portfolio longevity in jeopardy.

Read more …

“Remember, we’re talking about the Fed here… a group of people who go above and beyond to ignore risks in order to maintain the status quo…”

The Stock Market Bubble is So Big Even the Fed’s Talking About It (Phoenix)

The Fed confirmed yesterday that stocks are in a bubble. Lost amidst the usual Fed-speak about inflation and other items were the following nuggets. 1) “Equities” (read: stocks) were the primary reason the Fed discussed financial stability risks. 2) The Fed raised its assessment of financial stability from “notable” to “elevated.” 3) The Fed discussed “stock valuations.” This is simply incredible. Remember, we’re talking about the Fed here… a group of people who go above and beyond to ignore risks in order to maintain the status quo. Put another way, the stock market bubble is now so massive that even THE FED is talking about it. Indeed, the Fed is even openly states that the bubble might cause financial instability (read: a CRASH). It’s not difficult to see what the Fed is talking about. Based on their cyclical adjusted price to earnings ratio (CAPE) stocks are in CLEAR bubble territory.

As you can see, stocks are currently as overpriced as they were at the 1929 peak. Indeed, the only time stocks were MORE expensive was the Tech Bubble: the single largest stock market bubble in history. They say you don’t ring a bell at the top. But what the Fed did yesterday is DARN close. So what happens when the markets wake up to the fact that yet another massive bubble is beginning to burst?

Read more …

Freeze it before the collapse.

Ice-Nine: The Plan To Freeze The Financial System (Rickards)

In my book The Road to Ruin, I discuss a phenomenon called “ice-nine.” The name is taken from a novel, Cat’s Cradle, by Kurt Vonnegut. In the novel, a scientist invents a molecule he calls ice-nine, which is like water but with two differences. The melting temperature is 114.4 degrees Fahrenheit (meaning it’s frozen at room temperature), and whenever ice-nine comes in contact with water, the water turns to ice-nine and freezes. The ice-nine is kept in three vials. The plot revolves around the potential release of ice-nine into water, which would eventually freeze the rivers and oceans and end all life on Earth. Cat’s Cradle is darkly comedic, and I highly recommend it. I used ice-nine in my book as a metaphor for financial contagion.

If regulators freeze money market funds in a crisis, depositors will take money from banks. The regulators will then close the banks, but investors will sell stocks and force the exchanges to close and so on. Eventually, the entire financial system will be frozen solid and investors will have no access to their money. Some of my readers were skeptical of this scenario. But I researched it carefully and provided solid evidence that this plan is already in place — it’s just not well understood. But the ice-nine plan is now being put into practice. Consider a recent Reuters article that admitted elites would likely shut down the entire system when the next financial crisis strikes. The article claimed that the EU is considering actions that would temporarily prevent people from withdrawing money from banks to prevent bank runs.

“The desire is to prevent a bank run, so that when a bank is in a critical situation it is not pushed over the edge,” said one source. Very few people are aware of these developments. They get a brief mention in the media, if they get mentioned at all. But people could be in for a shock when they try to get their money out of the bank during the next financial crisis. Think of it as a war on currency or a war on money. Even the skeptics can see how the entire financial system will be frozen solid in the next crisis. The only solution is to have physical gold, silver and bank notes in private storage. The sooner you put your personal ice-nine protection plan in place, the safer you’ll be.

Read more …

“..the ideal of society as a kind of universal market (and not, for example, a polis, a civil sphere or a kind of family) and of human beings as profit-and-loss calculators (and not bearers of grace, or of inalienable rights and duties)..”

Neoliberalism: The Idea That Changed The World (G.)

Last summer, researchers at the IMF settled a long and bitter debate over “neoliberalism”: they admitted it exists. Three senior economists at the IMF, an organisation not known for its incaution, published a paper questioning the benefits of neoliberalism. In so doing, they helped put to rest the idea that the word is nothing more than a political slur, or a term without any analytic power. The paper gently called out a “neoliberal agenda” for pushing deregulation on economies around the world, for forcing open national markets to trade and capital, and for demanding that governments shrink themselves via austerity or privatisation. The authors cited statistical evidence for the spread of neoliberal policies since 1980, and their correlation with anaemic growth, boom-and-bust cycles and inequality.

Neoliberalism is an old term, dating back to the 1930s, but it has been revived as a way of describing our current politics – or more precisely, the range of thought allowed by our politics. In the aftermath of the 2008 financial crisis, it was a way of assigning responsibility for the debacle, not to a political party per se, but to an establishment that had conceded its authority to the market. For the Democrats in the US and Labour in the UK, this concession was depicted as a grotesque betrayal of principle. Bill Clinton and Tony Blair, it was said, had abandoned the left’s traditional commitments, especially to workers, in favour of a global financial elite and the self-serving policies that enriched them; and in doing so, had enabled a sickening rise in inequality. Over the past few years, as debates have turned uglier, the word has become a rhetorical weapon, a way for anyone left of centre to incriminate those even an inch to their right. (No wonder centrists say it’s a meaningless insult: they’re the ones most meaningfully insulted by it.)

But “neoliberalism” is more than a gratifyingly righteous jibe. It is also, in its way, a pair of eyeglasses. Peer through the lens of neoliberalism and you see more clearly how the political thinkers most admired by Thatcher and Reagan helped shape the ideal of society as a kind of universal market (and not, for example, a polis, a civil sphere or a kind of family) and of human beings as profit-and-loss calculators (and not bearers of grace, or of inalienable rights and duties). Of course the goal was to weaken the welfare state and any commitment to full employment, and – always – to cut taxes and deregulate. But “neoliberalism” indicates something more than a standard rightwing wish list. It was a way of reordering social reality, and of rethinking our status as individuals.

Still peering through the lens, you see how, no less than the welfare state, the free market is a human invention. You see how pervasively we are now urged to think of ourselves as proprietors of our own talents and initiative, how glibly we are told to compete and adapt. You see the extent to which a language formerly confined to chalkboard simplifications describing commodity markets (competition, perfect information, rational behaviour) has been applied to all of society, until it has invaded the grit of our personal lives, and how the attitude of the salesman has become enmeshed in all modes of self-expression. In short, “neoliberalism” is not simply a name for pro-market policies, or for the compromises with finance capitalism made by failing social democratic parties. It is a name for a premise that, quietly, has come to regulate all we practise and believe: that competition is the only legitimate organising principle for human activity.

Read more …

I’m still convinced that people will react shocked if China is the first domino. But though Charlene Chu is right that China controls most of its system, its control over Chinese obligations abroad isn’t nearly that strong. Xi knows this, and that’s why Chinese purchases abroad are shrinking. China has become part of the global financial system with monopoly money. And sure, it has dollars and Treasuries, but they’re neither limitless nor limitlessly fungible. Weakest point? Local governments who have borrowed from foreign sources. Or from domestic ones that get their credit from foreigners. Shadow banks.

So When Will China’s Debt Bubble Finally Blow Up? (WS)

Corporate debt in China has soared to $18 trillion, or 169% of GDP, the largest pile of corporate debt in the world, according to the worried BIS. The OECD has warned about it earlier this year. The New York Fed warned about this debt boom in February and that it could lead to a “financial crisis,” but that authorities have many tools to control it. The IMF regularly warns about China’s corporate debt, broken-record-like, and did so again a few days ago, lambasting the authorities for their reluctance to tamp down on the growth of debt. The “current trajectory,” it said, “could eventually lead to a sharp adjustment.” The Chinese authorities – the government and the central bank, supported by the state-owned megabanks – have allowed some bonds to default, rather than bail them out, to make some kind of theoretical point, and they have been working furiously on a balancing act, tamping down on the credit growth that fuels the economy and simultaneously stimulating the economy with more credit to keep the debt bubble from imploding.

A misstep could create a global mess. “Everyone knows there’s a credit problem in China, but I find that people often forget about the scale; it’s important in global terms,” Charlene Chu told the FT. Back in 2011, when she was still a China banking analyst at Fitch Ratings, she went out on a limb with her radical estimates that there was much more debt than disclosed by the central bank, particularly in the shadow banking system, that banks were concealing risky loans in off-balance-sheet vehicles, and that this soaring opaque debt could have nasty consequences. Her outlandish views at the time have since then become the consensus. And this pile of debt is in much worse shape than officially acknowledged, she says in her latest report, cited by the FT. She’s now with Autonomous Research.

She figured that by the end of 2017, bad debt in China could hit 51 trillion yuan, or $7.6 trillion. Or about 68% of GDP! It would take the bad-debt ratio to an astronomical 34% of all loans, and way above the 5.3% that the authorities are proffering. And the authorities – the government, the central bank, supported by the state-owned banks – are now pulling all levers to keep this under control. “What I’ve gotten a greater appreciation for is how everything is so orchestrated by the authorities,” she said. “The upside is that it creates stability. The downside is that it can create a problem of proportions that people would think is never possible. We’re moving into that territory.”

Read more …

More Chu. Remarkable how she says “.. the ability to avoid recognizing losses only delays the inevitable day of reckoning as problems fester for longer, and grow larger than in an economy where actors respond purely to market incentives.” Remarkable because that describes America as much as it does China.

Charlene Chu Lays Out China’s “Doomsday” Scenario (ZH)

The first time we laid out the dire calculations about what is perhaps the biggest mystery inside China’s financial system, namely the total amount of its non-performing loans, by former Fitch analyst Charlene Chu we called it a “neutron bomb” scenario, because unlike virtually every other rosy forecast the most dire of which topped out at around 8%, Chu argued that the amount of bad debt in China was no less than a whopping 21% of total loans. While traditional bank loans are not Chu’s prime focus – she looks at the wider picture, including shadow banking – she says her work suggests that nonperforming loans may be at 20% to 21%, or even higher. The chart below shows just how much of an outlier Chu’s stark forecast was in comparison to her peers, and especially the grotesquely low and completely fabricated official number released by the banks and the government.

Recall that one of the biggest scandals in China in 2014 was the realization (as many had warned previously) that millions of tons of commodities were rehypothecated countless times, and thus “pledged” as collateral to numerous counterparties, and that as a result these same counterparties were unable to make sense of who owns what at one of China’s largest ports, Qingdao. In this context, it is safe to assume that loss given default rates in China are if not 100% (or more, which is impossible in theoretical terms but in practice is quite possible, as another curious side effect of unlimited collateral rehypothecation), then as close to it as possible.

Fast forward to today, when Charlene Chu, described by the FT as “one of the most influential analysts of China’s financial system” is back with a revised estimate that the bad debt in China has now reached a stunning $6.8 trillion above official figures and warns that the government’s ability to enforce stability has allowed underlying problems to go unchecked. [..] So if Chu held the wildly outlier view nearly two years ago that China’s NPLs amount to 21% of total, what is her latest estimate? The number is a doozy: in her latest report, Chu estimates that bad debt in China’s financial system will reach as much as Rmb51 trillion , or $7.6 trillion, by the end of this year, more than five times the value of bank loans officially classified as either non-performing or one notch above.” That estimate implies a bad-debt ratio of 34%, orders of magnitude above the official 5.3% ratio for those two categories at the end of June.

One factor that has foiled countless shorts over the years is that Beijing can simply order state-owned banks to keep lending to a lossmaking zombie company or to a smaller lender that relies on short-term interbank funding to stay liquid, and that’s precisely what has been happening, when looking at the various non-conventional credit pathways in China in recent years, which include Wealth Management Products, Bank Loans to Non-Bank Institutions, Shadow Banking, Repos and Certificates of Deposit.

But Chu said the ability to avoid recognizing losses only delays the inevitable day of reckoning as problems fester for longer, and grow larger than in an economy where actors respond purely to market incentives. That said, the recent spike in corporate bankruptcies indicates that even Beijing is slowly shifting to a more “market” driven stance. “What I’ve gotten a greater appreciation for is how everything is so orchestrated by the authorities,” she said. “The upside is that it creates stability. The downside is that it can create a problem of proportions that people would think is never possible. We’re moving into that territory.” Finally, putting it all in context is the following chart showing the total size of China’s financial sector, which as of the latest quarter has grown to $35 trillion, double the size of the US.

Read more …

Subtle tactics from Xi. Shift the debt but keep it high. What do you think the odds are that after the Party Congress China will withdraw into itself?

China’s New Problem: Frenzy Of Consumer Lending Creates Debt Explosion (CNBC)

The Chinese government is moving to tackle high debt levels, but the country is still borrowing more, Deutsche Bank said in a report released Thursday. That’s because short-term consumer debt in China has begun to surge as authorities try to alleviate the high levels of corporate indebtedness. The redistribution comes as Beijing is trying to strike a balance between stability and strength in its economy. Household debt in China is growing “very fast” and has accelerated in the last three to four months, according to Deutsche Bank: “If we focus purely on the consumer lending … then China has been undergoing something akin to a consumer lending frenzy.” According to Deutsche Bank, corporate credit has fallen to 45% of net new credit, down from 65% in the last 10 years. Instead, Beijing is allowing households and governments to borrow more to fund growth, which is targeted for around 6.5% in 2017, said the analysts.

Now, short-term consumer credit is growing 35% year-over-year, and may hit about 40% year-over-year by the end of December at the current trend, Deutsche Bank said. The bank said it isn’t yet clear where exactly the short-term consumer credit is being deployed, although 70 to 80% of that debt has historically been credit card-related. Overall household credit growth in China, the analysts noted, is growing around 24% year-over-year. At the end of the first half of 2017, corporate the debt-to-GDP ratio fell to 165% from the peak of 169% in the first quarter of 2016. That was “more of a ‘stabilization’ than a significant reduction,” Deutsche Bank said, calling it an “explosion” of growth. Meanwhile, household and government debt however rose by 8 to 9% of GDP. “So when viewed in aggregate China is still leveraging up apace,” the Deutsche Bank report concluded.

Read more …

Maybe somoneone should explain to Warren what the Fed is and does. Or Washington for that matter.

‘Simply Doesn’t Cut It’: Elizabeth Warren Slams Wells Fargo Board Changes (BI)

Wells Fargo’s effort to turn the page on consumer fraud scandals is falling short. That’s according to Massachusetts senator Elizabeth Warren, who has requested the Federal Reserve remove the bank’s board members who served between May 2011 and July 2015 in response to a series of vast consumer fraud scandals. The bank, already in hot water for creating millions of unauthorized accounts, recently admitted to also selling auto insurance without customers’ knowledge. Wells Fargo’s response? It has promoted an ex-Fed board governor, Elizabeth Duke, to chairwoman of the board. Duke, a champion of community banks while at the Fed, became a Wells Fargo director in 2015 and was named vice chair last year after the first round of scandals broke and led to the resignation of then-CEO John Stumpf.

Business Insider contacted Senator Warren to get her reaction. “Letting a few board members retire early and shuffling around current board members simply doesn’t cut it,” Warren said in an email. “The Fed should remove all remaining board members who served during the fake-accounts scandal.” Warren also renewed her call for board members’ removal with a new letter to Fed chairman Janet Yellen dated August 16, and voicing her dissatisfaction at what she sees as central bank inaction. “Instead of taking steps to remove the responsible Wells Fargo Board members, the Federal Reserve has actually sought to reduce their obligations and the obligations of other directors at the country’s biggest banks,” the letter said. In July, Warren repeatedly pressed Fed Chair Janet Yellen on the issue during recent Congressional testimony but Yellen would only say the central bank had the power to remove the directors — not that it had any inclination to do so.

Read more …

More free rides for bankers. Warren! Oh wait, your own party takes their contributions.

Deutsche Bank, Bank of America Settle Agency Bond Rigging Lawsuits (R.)

Deutsche Bank and Bank of America agreed to pay a combined $65.5 million to settle investor litigation accusing large banks of rigging the roughly $9 trillion government agency bond market over a decade. Preliminary settlements totaling $48.5 million for Deutsche Bank and $17 million for Bank of America were filed on Thursday with the U.S. District Court in Manhattan, and require a judge’s approval. Both banks denied wrongdoing. The settlements were the first in litigation accusing 10 banks of engaging in a “brazen conspiracy” to rig the market for U.S. dollar-denominated supranational, sub-sovereign and agency (SSA) bonds, court papers show. The investors are led by the Iron Workers Pension Plan of Western Pennsylvania, KBC Asset Management, and the Sheet Metal Workers Pension Plan of Northern California.

They accused banks of communicating by phone, chatrooms and instant messaging to share pricing data and function as a collective “super-desk,” while letting traders coordinate their strategies, to boost profit. This collusion allegedly ran from 2005 to 2015, and forced customers to accept unfair prices on bonds they bought and sold, court papers show. BNP Paribas, Citigroup, Credit Agricole, Credit Suisse, HSBC, Nomura, Royal Bank of Canada and Toronto-Dominion Bank were also sued, and all sought dismissals. U.S. regulators have also examined possible manipulation in the SSA bond market. The Manhattan court is home to a slew of private litigation accusing big banks of conspiring to rig various financial markets, interest rate benchmarks and commodities. Late Wednesday night, another group of investors sued six banks, claiming they rigged the more than $1 trillion stock lending market.

Read more …

Simply how all of Washington works.

Who Is Lobbying Mike Pence And Why? (IBT)

Mike Pence has been among the Trump administration’s most prominent voices pressing to replace the Affordable Care Act, repeal post-crisis financial regulations, privatize American infrastructure and promote fossil fuels. Those positions would benefit the industries that have been directly lobbying Pence since he was elected vice president, according to federal documents reviewed by International Business Times. Amid speculation that Pence could mount his own presidential bid — or replace Trump if he leaves office early — the former Indiana governor and U.S. congressman has been directly lobbied by major health care and drug companies, Wall Street firms, oil and gas interests and industry groups interested in shaping a federal infrastructure privatization initiative.

Pence’s office has also been lobbied by his former congressional chief of staff on behalf of insurance, defense contracting and telecommunications companies — and that lobbying revolved around health care policy, defense spending and net neutrality. Pence has enthusiastically backed the policies by the lobbying firms. While other vice presidents have been the target of lobbying in the past, Pence has been viewed as one of the most powerful vice presidents in recent history. He is a longtime politician serving a president with no experience in elected office, and during his vice-presidential selection process, Trump was reportedly offering potential running mates a vast policy portfolio to oversee. Pence also oversaw Trump’s White House transition, which shaped the administration’s personnel decisions and many of its policy proposals.

Companies that have lobbied the vice president have spent tens of millions of dollars in total federal lobbying so far this year. Here is a deeper look at the major industries lobbying him — and what exactly they have been pushing for in their efforts to influence the vice president. Despite his onetime support for expanding Obamacare subsidies in his home state, Pence has reversed course and led the Trump administration’s legislative bid to repeal the Affordable Care Act — just as health insurers have been lobbying him in 2017.

“If you’re one of those Americans who want to see Obamacare repealed and replaced, we literally are days, or maybe just weeks, away from being able to accomplish that historic objective,” he told conservative talk radio host Rush Limbaugh last month. “We believe if they can’t pass this carefully crafted repeal and replace bill — we do those two things simultaneously — we ought to just repeal only and then have enough time built into that legislation to craft replacement legislation.” The Pence-led repeal effort could be a financial boon to health insurers like Blue Cross and Blue Shield, as well as UnitedHealthcare Group — both which have been in direct contact with Pence, according to records reviewed by IBT.

Read more …

Libertarian view.

Mr. President: Close Down More “Advisory Councils” (Rossini)

So President Trump closed down his “Manufacturing Council” and no one cheered? What a shame. Why was there a “Manufacturing Council” to begin with? It’s not the job of the president to meddle with our economy. His job description says nothing about benefitting “manufactures” or “scientists” or “Silicon Valley” or anyone else. These “Councils” are breeding grounds for the cronyism that has virtually destroyed the American Dream. If a CEO has the ear of the president, do you think he’s going to “advise” the president to do anything that will hurt his own business? On the other hand, would the CEO be tempted to advise the president to hurt his competitors, both foreign and domestic? Would the CEO advise the president to make it hard for start-ups and entrepreneurs to compete?

Would he advise for subsidies? Strict licensing laws? The president doesn’t need Advisory Councils, Czars, or any other destroyer of our economic liberties. Let the CEO’s be “counciled” themselves by free market prices. Let them deal with economic reality as it is, not massage the president for unconstitutional interventions. Let them stand on their own. Either satisfy consumers profitably, or fold up so that other people can. The president, at the same time, should stop pretending that he can push buttons and pull levers to make the economy run. Nothing could be further from the truth. Government intervention only stifles the economy.

The economy continues to function despite the political intrusions that exist. Fortunately, entrepreneurs are creative enough to always find ways around so-called government “regulations”. There’s always a loophole somewhere. But why make it hard on entrepreneurs to begin with? Just get the heck out of the way! But alas, the government and multi-national corporations are attached at the hip. One scratches the back of the other. Mr. President, close down all the “Advisory Councils,” and keep your hands off the economy.

Read more …

Spain’s views on this may have changed last night.

Spain Lacks Capacity To Handle Migration Surge – UNHCR (G.)

Spain lacks the resources and capacity to protect the rising number of refugees and migrants reaching it by sea, the UN refugee agency has said. The warning from UNHCR comes as the Spanish coastguard said it rescued 593 people in a day from 15 small paddle boats, including 35 children and a baby, after they attempted to cross the seven-mile Strait of Gibraltar. The number of refugees and migrants risking the sea journey between Morocco and Spain has been rising sharply, with the one-day figure the largest since August 2014, when about 1,300 people landed on the Spanish coast in a 24-hour period. About 9,300 migrants have arrived in Spain by sea so far this year, while a further 3,500 have made it to two Spanish enclaves in north Africa, Ceuta and Melilla, the EU’s only land borders with Africa.

María Jesús Vega, a spokeswoman for UNHCR Spain, said police were badly under-resourced and there was a lack of interpreters and a shortage of accommodation for the new arrivals. “The state isn’t prepared and there aren’t even the resources and the means to deal with the usual flow of people arriving by sea,” she said. “Given the current rise, we’re seeing an overflow situation when it comes to local authorities trying to cope at arrival points.” Vega said the agency was seeing a very high number of vulnerable people including women, victims of people-trafficking, and children. “What we’re asking is for there to be the right mechanisms in place to ensure people are treated with dignity when they come,” she said.

Read more …

Jul 062016
 
 July 6, 2016  Posted by at 8:35 am Finance Tagged with: , , , , , , , ,  Comments Off on Debt Rattle July 6 2016


Arnold Genthe San Francisco, “Grant Avenue at Sacramento Street.” 1930

British Pound Sterling Plunges As Brexit Fears Continue To Swirl (CNBC)
Asia Markets Tumble As Investors Scurry Into Safe-Haven Plays (CNBC)
Third London Asset Manager Suspends Trading in Property Fund (BBG)
The Big Unravel: US Commercial Bankruptcies Skyrocket (WS)
In London, Banker Bonuses Are Set To Disappear (ZH)
Deutsche Bank: The Downfall Of An Institution (Deutsche Welle)
Inequality, Debt and Credit Stagnation (Steve Keen)
Eurosceptic 5 Star Movement Biggest Party In Italy: Survey (EP)
EU Commission: CETA Should Be Approved By National Parliaments (DW)
The Beauty Beneath Brexit’s Bedwetting (Welsh)
Spain’s Social Security Program Will Go Bust in 2018 (Mish)
In Clinton Case, Obama Administration Nullifies 6 Criminal Laws (Zuesse)
FBI Director Comey Preempts Justice Department (Intercept)
The Department Of “Just Us” (Martin Armstrong)


It’s just a bubble popping.

British Pound Sterling Plunges As Brexit Fears Continue To Swirl (CNBC)

The British pound plunged to fresh 31-year lows on Wednesday, swamped by continued fears over the U.K. leadership vacuum and the country’s potential exit from the EU. The pound tumbled as low as $1.2796 during Asia trade on Wednesday, it’s lowest since 1985, after ending Tuesday’s trade around $1.2960. The U.K. currency later recovered to trade around $1.2881 at 12:27 p.m. SIN/HK. Analysts were concerned that the continued political uncertainty will hurt capital inflows and spur companies to delay investments, potentially tipping the economy into a recession. The Bank of England (BOE) had begun taking preemptive steps to protect the British economy in the wake of June 23 U.K. referendum vote to leave the European Union (EU).

On Tuesday, BOE Governor Mark Carney sent a clear message to Britain’s cautious bankers: They needed to start lending more money. The central bank cut the amount of capital it required banks to hold in reserve, which freed up an extra 150 billion pounds ($196 billion) for lending. Carney had previously signaled more monetary easing would likely be put in place in the near term. But that wasn’t assuaging the market much, analysts said. “As Carney as put it himself, there isn’t so much he can do. Monetary policy, which the Bank of England is in charge of, cannot fix structural issues. It’s very apparent with Brexit that investors will stay away from the U.K. because of the certainty,” Axel Merk, chief investment officer at Merk Investments, told CNBC’s “Rundown” on Wednesday.

He noted that not only has the U.K. yet to invoke Article 50 of the Lisbon Treaty, which will formally start negotiations for an exit from the EU, it wasn’t clear who the country’s next leader would be. The ruling Conservative party is in the midst of finding a successor to Prime Minister David Cameron, who resigned after his “remain” camp lost the referendum. “You’re not going to make a big investment decision if you don’t have that sort of certainty,” Merk said. “The only thing the Bank of England can do obviously is provide the ability of banks to lend, but if there are no takers, it doesn’t help all that much.”

Read more …

And if one bubble pops….

Asia Markets Tumble As Investors Scurry Into Safe-Haven Plays (CNBC)

Markets in Asia were sharply lower on Wednesday, as investors scurried into safe-haven plays on global growth concerns, sending bond yields to record lows. Renewed Brexit jitters also sent the British pound tumbling to a fresh 31-year low. The British pound dropped to a fresh 31-year low early Wednesday amid Brexit concerns, trading at $1.2860 as of 11:04 a.m. HK/SIN, after dropping as low as $1.2796 earlier. The tumble began overnight as investors flocked to safe-haven assets such as U.S. Treasurys, the yen and the greenback after three U.K. real estate funds halted selling and the Bank of England relaxed regulations to encourage banks to lend out more money.

Japan’s Nikkei 225 dropped 2.96%, after earlier tumbling some 3.2% on the back of fresh yen strength. The Japanese yen, a safe-haven asset, traded at 100.71 against the dollar as of 11:04 a.m. HK/SIN, compared with levels near 103 on Friday. “There’s a high level of complacency in dollar/yen trade as the markets have no defined direction other than chasing risk sentiment,” said Stephen Innes, a senior trader at OANDA. “I expect further probes lower as the latest Brexit sell-off is simply the tip of the iceberg.” The yen strength saw Japanese exporters tumble, with shares of Honda off 5.9%, Toyota down 3.09% and Nissan down 3.82%.

Read more …

What? I can’t have Schadenfreude? First they blow a giant bubble and when it pops they all come to mama? Know what I think? “Someday a real rain will come and wash all this scum off the streets..”

“The problem these funds face is that it takes time to sell commercial property to meet withdrawals, and the cash buffers built up by the managers have been eroded by investors heading for the door.”

Third London Asset Manager Suspends Trading in Property Fund (BBG)

Three of the U.K.’s largest real estate funds have frozen almost £9.1 billion ($12 billion) of assets after Britain’s shock vote to leave the European Union sparked a flurry of redemptions. M&G Investments, Aviva Investors and Standard Life Investments halted withdrawals because they don’t have enough cash to immediately repay investors. About £24.5 billion is allocated to U.K. real estate funds, according to the Investment Association. “The dominoes are starting to fall in the U.K. commercial property market,” said Laith Khalaf, a senior analyst at Hargreaves Lansdown. “The problem these funds face is that it takes time to sell commercial property to meet withdrawals, and the cash buffers built up by the managers have been eroded by investors heading for the door.”

The pound fell to its weakest level in three decades against the dollar Tuesday, surpassing lows reached in the aftermath of the Brexit vote, as the freezing of the property funds spooked global markets. Bank of England Governor Mark Carney pledged to shore up financial stability on a day when a survey showed a plunge in U.K. business confidence. The rush by private investors to withdraw money prompted M&G, which held 7.7% in cash before the vote, to suspend its £4.4 billion Property Portfolio fund and Aviva Investors to freeze its £1.8 billion Property Trust on Tuesday. Standard Life halted trading on its£ 2.9 billion U.K. real estate fund on Monday. The cash position for Aviva and Standard Life’s funds at the end of May was 9.3% and 13.1% respectively, documents showed.

Read more …

“Total US commercial bankruptcy filings in June soared 35% from a year ago..”

The Big Unravel: US Commercial Bankruptcies Skyrocket (WS)

This year through June, there have been 91 corporate defaults globally, the highest first-half total since 2009, according to Standard and Poor’s. Of them, 60 occurred in the US. Some of them are going to end up in bankruptcy. Others are restructuring their debts outside of bankruptcy court by holding the bankruptcy gun to creditors’ heads. In the process, stockholders will often get wiped out. These are credit fiascos at larger corporations – those that pay Standard and Poor’s to rate their credit so that they can sell bonds in the credit markets. But in the vast universe of 19 million American businesses, there are only about 3,025 companies, or 0.02% of the total, with annual revenues over $1 billion; they’re big enough to pay Standard & Poor’s for a credit rating.

About 183,000 businesses, or less than 1% of the total, are medium-size with sales between $10 million and $1 billion. Only a fraction of them have an S&P credit rating, and only those figure into S&P’s measure of defaults. The rest, the vast majority, are flying under S&P’s radar. About 99% of all businesses in the US are small, with less than $10 million a year in revenues. None of them are S&P rated and none of them figure into S&P’s default measurements. So how are these small and medium-size businesses doing – the core of American enterprise? Total US commercial bankruptcy filings in June soared 35% from a year ago, to 3,294, the eighth month in a row of year-over-year increases, the American Bankruptcy Institute (in partnership with Epiq Systems) reported today.

During the first half, commercial bankruptcy filings soared 29% to 19,470. Among the various filing categories: Chapter 11 filings (company “restructures” its debt at the expense of stockholders and unsecured creditors by shifting ownership to creditors, but continues to operate) soared 36% to 499 in June and 25% in the first half to 3,220. Chapter 7 filings (company throws in the towel and “liquidates” by selling its assets and distributing the proceeds to creditors) jumped 28% in June to 1,909, and 25% in the first half to 11,211.

Read more …

Then so will the bankers.

In London, Banker Bonuses Are Set To Disappear (ZH)

Not only will Brexit be used as an excuse for companies to lower earnings guidance and for central banks to provide more quantitative easing, but it may also be a scapegoat for banker bonuses in London being slashed – everyone can let out their collective gasp now. As we have been covering, banker jobs have been getting cut for quite some time now, most recently with RBS announcing it will be cutting another 900 jobs. Times have been difficult for banks leading up to Brexit, but now, as Bloomberg reports, the message London’s investment banks are giving staff this year is that in the aftermath of Brexit, just be thankful to have a job, and forget a fat bonus at the end of the year.

“It’s a great opportunity to blame Brexit, giving people the message ‘you’re lucky enough to have a job'” said Stephane Rambosson, managing partner at DHR executive search firm in London, adding that bonuses could fall 30% or more in some areas. Jason Kennedy, CEO of recruitment firm Kennedy Group in London said “Reality is going to kick in, today it’s about job preservation, rather than bonuses. Things are going to change, and some people shouldn’t expect any bonuses.”

Jon Terry, a partner at PricewaterhouseCoopers in London, at least admits that things were falling apart even before Brexit: “If we hadn’t had the referendum results, this year was looking pretty tough anyway. We haven’t seen an end to various fines and compensation related to payment protection insurance and Libor. There are still billions of pounds being charged to the accounts. Ever since the financial crisis, there has been a need for reshaping the spend on compensation costs. Brexit is possibly one of the biggest catalysts for the next stage of reduction.”

Read more …

From a German source, no less. Throw that towel!

Deutsche Bank: The Downfall Of An Institution (Deutsche Welle)

It has been nearly a year since John Cryan assumed the leadership of Germany’s still-largest bank. He took the reins from Anshu Jain, who was chosen to realize his own predecessor Josef Ackermann’s dream of 25% returns. Jain did what he was expected to do. And the bank is still dealing with the consequences. 7,800 lawsuits have been carried out against the bank worldwide. Most of them are pretty manageable, some were settled for billions upon billions. But a few still carry a destructive power that would cost the bank its existence – money laundering accusations in Russia, for example, or investigations by the SEC over peculiar dealings with mortgage-backed securities.

Cryan is making a tremendous effort, portraying himself at times as the man behind the wrecking-ball, at others as the chief builder. He has almost completely replaced the bank’s leadership. With an iron broom, he has swept away many of his inherited messes, accepting record losses of over $6 billion in the process. But his efforts have yet to yield any success. Deutsche’s share price has halved itself once again this year. Employee moral is in the cellar. Even the technology is breaking down – in June, double-bookings were recorded on three million accounts, ATMs stopped giving out cash, card purchases weren’t going through. Meanwhile the bank keeps talking away about an “image problem.”

So it’s clear that things continue to get worse. Cryan stresses over and over that he doesn’t see the bank as a takeover candidate. Certainly oversight authorities would take a very close, very skeptical look at such a deal. But even if a competitor from the US or China were able to afford Deutsche Bank out of pocket, they likely wouldn’t want anything to do with it in its current condition. As of now, that’s the only real insurance against an acquisition.

Read more …

Pretty funny too.

Inequality, Debt and Credit Stagnation (Steve Keen)

This was my keynote speech at the French Association for Political Economy (AFEP) annual conference in Mulhouse, France (the other keynote was given–in French–by my good friend Marc Lavoie, who is now based at the University de Paris 13). In this presentation, I:
• Disparage the “secular stagnation” explanation that Larry Summers has regurgitated for the tepid level of economic growth today. As did Hansen in the 1930s, Summers ponders “why growth would remain anaemic in the absence of major financial concerns?“, when financial concerns are obvious if you understand credit;
• Explain why credit plays a crucial role in both aggregate demand and aggregate income, once you understand that banks originate loans rather than act as financial intermediaries; and
• Show that my 1992 complex systems model of Minsky’s “Financial Instability Hypothesis” can be derived by working from strictly true macroeconomic identities, in an alternative to Lucas’s “microfoundations” approach to building macroeconomic models.

Read more …

Beppe!

Eurosceptic 5 Star Movement Biggest Party In Italy: Survey (EP)

Beppe Grillo‘s movement would be the first Italian party, overtaking PD (Socialists) with 32% of consensus, according to a new survey by Demos. 5 Star Movement won in two of the most important Italian cities (Rome and Turin) in the last administrative election in Italy.

Demos for Repubblica:
• 5 Star Movement (EFDD): 32%
• Partito Democratico (S&D): 30%
• Lega Nord (ENF): 11,8%
• Forza Italia (EPP): 11,5%
• Fratelli d’Italia (-): 3%

With the new electoral system, the runoff would see 5 Star Movement winning against PD (54,7% vs. 45,3%)

Read more …

Down goes Jean-Claude. He ain’t no Van Damme.

EU Commission: CETA Should Be Approved By National Parliaments (DW)

European Commission chief Jean-Claude Juncker is expected to scrap plans to fast-track a trade agreement with Canada through the EU. After pressure from Germany and France, Juncker appears to be backtracking. Juncker will reportedly propose a mixed agreement – one that requires both the approval of the European parliament and national legislatures – at an European Commission meeting on Tuesday. Last week he was reported saying he “personally couldn’t care less” whether lawmakers get to vote on the deal. A report in the Financial Times noted that Germany and France wanted their national parliaments to be involved, which would inevitably lengthen the process.

The deal was scheduled to be signed at the end of October during a summit in Brussels with Canadian Prime Minister Justin Trudeau, and it was due to be implemented in 2017. Trade ministers in Germany, France, Italy, the Netherlands and UK have reportedly said they will support the Comprehensive Economic and Trade Agreement, or CETA. CETA is similar to the agreement under negotiation between the EU and US and has drawn strong criticism in EU countries. Canadian and EU leaders concluded CETA in 2014, but implementation was delayed due to last-minute objections in Europe. This was related to an investment protection system to shield companies from government intervention.

With opposition to the EU’s impending free trade deal with Canada apparently growing, German Chancellor Angela Merkel said recently that the German parliament should be consulted on the EU’s free trade deal with Canada. “It is a highly political agreement that has been widely discussed,” said Merkel, adding that the “Bundestag is allowed to be involved of course… in national decisions”. German Economy Minister Sigmar Gabriel told the Tagesspiegel daily that Juncker’s comment was “incredibly stupid” and “would stoke opposition to other free trade deals,” including with the US. German media has also described Juncker’s position as badly timed given the growing skepticism among European voters about the EU.

Read more …

“The end result is a mess, but a strangely inevitable and even curiously beautiful one.”

The Beauty Beneath Brexit’s Bedwetting (Welsh)

If democratic aliens came down from Mars and looked at the EU referendum result, they’d be compelled to take the view that the UK, hopelessly fragmented by de-industrialisation and neoliberalism, is now finished as a political entity. The debate will rage on about the extent to which leave voters gave the smug, complacent neoliberal establishment a kicking, or were duped by toytown fascists into swallowing the same policies of the past 30 years, only significantly amped up. Whatever side you come down on, the process has bolstered a toxic, chauvinistic right wing, not just in England, but also Europe and beyond. The EU referendum redesignated the United Kingdom of Great Britain and Northern Ireland as Little England.

Scottish voters, favouring the emotional and practical investment in the European ideal, decisively rejected this approach. The end result is a mess, but a strangely inevitable and even curiously beautiful one. We live in an era of great turbulence, with economic decline running in paradoxical tandem with technological advance. It is only to be expected that our antiquated institutions haven’t been able to keep up, and our nation states, political parties and supranational bodies are starting to unravel. Politicians now seem perennially in the business of chaos management, and the suspicion must be that this process has only just begun. The inevitable chorus of voices crying out for “a period of stability” sadly misses the point: we aren’t at that place in our history, and trying to impose inertia on those fluid times may only be inviting further discord.

As has been postulated, with much hand-wringing, it was obvious to many that the leave campaign didn’t believe it would win, merely wishing to register a protest, and was thus left thinking: what have we done? But let’s remember that no democrat can defend the commission-led EU, and nobody in the remain camp had a serious reforming vision of Europe, any more than those in leave offer much of clue as to what they’ll do with their increasingly hollow-looking victory. Remain’s leaders would have kept us straitjacketed into the EU’s current death-by-a-thousand-cuts version of corporate neoliberalism. At least now, shed of that distraction, we have our governmental elites much more clearly in our sights.

Read more …

The shape of things to come.

Spain’s Social Security Program Will Go Bust in 2018 (Mish)

Spain’s Social Security system is expected to go broke by 2018. In the US, concerns over such matters are virtually nonexistent. But Spain cannot print Euros, and is already deep in the hole on meeting budget deficit targets. Via translation from El Confidencial, Spain’s Social Security Reserve Fund Exhausted by 2018:

The Social Security reserve fund will run out of money in 2018. The cause in bonus payments to pensioners, which consumes every six months (in December and July) over €8.5 billion. Revenue from social security contributions are not sufficient to meet the payment obligations. Starting in 2018, only an extraordinary contribution by the State would make it possible for Social Security can meet its commitments.

The financial problems of Social Security are not a temporary problem. The government itself expects that this year the public pension system will register equivalent to 1.1% of GDP deficit (about 11 billion euros ), while in 2017 planned is an imbalance equivalent to 0.9% of GDP. In 2016, revenues from social security contributions recorded an accumulated a deficit of 12.24% compared to expectations. The deviation is even higher than the already recorded in 2015.

Spain has missed watered down budget deficit targets a half-dozen times. Spain is already under pressure from Brussels to cut spending or hike taxes, by 8 billion euros. Something has to give.

Read more …

Extremely damning.

In Clinton Case, Obama Administration Nullifies 6 Criminal Laws (Zuesse)

There can be no excuse for Obama’s depriving the public, via a grand jury decision, of the right to determine whether a full court case should be pursued in order to determine in a jury trial whether Hillary Clinton’s email system constituted a crime (or several crimes) under U.S. laws. The Obama Administration’s ‘finding’ that “clearly intentional and willful mishandling of classified information” would need to have been proven, in order for her to have been prosecuted under any U.S. criminal law, is a flagrant lie: none of the above six U.S. criminal laws requires that, but the only way to determine whether even that description (“clearly intentional and willful mishandling of classified information”) also applies to Clinton would be to go through a grand jury (presenting the above-cited six laws) and then to a jury case (to try her on those plus possibly also the charge that there was “clearly intentional and willful mishandling of classified information”).

But now, those six laws are effectively gone: anyone who in the future would be charged with violating any one of those six laws could reasonably cite the precedent that Ms. Clinton was not even charged, much less prosecuted, for actions which clearly fit the description provided in each one of those U.S. criminal laws. Anyone in the future who would be charged under any one of these six laws could prove discriminatory enforcement against himself or herself. (In the particular case discussed there, discriminatory enforcement was ruled not to have existed because the enforcement of the criminal law involved was judged to have been random enforcement, but this condition would certainly not apply in Clinton’s case, it was clearly “purposeful discrimination” in her favor, and therefore enforcement of the law against anyone else, where in Clinton’s case she wasn’t even charged — much less prosecuted — for that offense, would certainly constitute discriminatory enforcement.) So: that’s the end of these six criminal laws.

The U.S. President effectively nullified those laws, which were duly passed by Congress and signed into law by prior Presidents. And that’s the end, the clear termination, of a government “of laws, not of men”.

Read more …

Yeah, that is strange. Why go public with that unless you want to influence opinion? Which is not your job…

FBI Director Comey Preempts Justice Department (Intercept)

FBI Director James Comey took the unprecedented step of publicly preempting a Justice Department prosecution when he declared at a press conference Tuesday that “no reasonable prosecutor” would bring a case against Hillary Clinton for her use of a private email server. The FBI’s job is to investigate crimes; it is Justice Department prosecutors who are supposed to decide whether or not to move forward. But in a case that had enormous political implications, Comey decided the FBI would act on its own. “Although the Department of Justice makes final decisions on matters like this, we are expressing to Justice our view that no charges are appropriate in this case,” he said. Prosecutors could technically still file criminal charges, but it would require them to publicly disagree with their own investigators.

One of Comey’s likely motivations was avoiding the appearance that Department of Justice lawyers had biased the investigation due to their desire to avoid prosecuting a major party’s presidential nominee. He repeatedly assured the audience that “no outside influence of any kind was brought to bear.” Comey’s announcement also satisfied the public’s desire for a resolution sooner rather than later. But Matthew Miller, who was a spokesman for the Department of Justice under Attorney General Eric Holder, called Comey’s press conference an “absolutely unprecedented, appalling, and a flagrant violation of Justice Department regulations.” He told The Intercept: “The thing that’s so damaging about this is that the Department of Justice is supposed to reach conclusions and put them in court filings. There’s a certain amount of due process there.”

Legal experts could not recall another time that the FBI had made its recommendation so publicly. “It’s not unusual for the FBI to take a strong positions on whether charges should be brought in a case,” said University of Texas law professor Steve Vladeck. “The unusual part is publicizing it.”

Read more …

“James Comey was the chief prosecutor in the Southern District of New York between 2003 and 2005. He had no problem keeping me in Federal Prison on contempt of court without any charges, indictment, or a civil complaint..”

The Department Of “Just Us” (Martin Armstrong)

To indict someone, the criteria is supposed to be “intent.” Comey has used that to pretend there is no evidence that Hillary “intentionally” erased anything. Comey also stated that Hillary’s lawyers erased her emails using a keyword search program and they did not “read” the emails. He added that he would not recommend charges against Hillary or her aides. “Although we did not find clear evidence that Secretary Clinton or her colleagues intended to violate laws governing the handling of classified information, there is evidence that they were extremely careless in their handling of very sensitive, highly classified information,” Comey declared.

It was Comey who indicted Frank Quattrone for claiming he instructed his people to erase emails in his technology-industry banking group at Credit Suisse Group’s Credit Suisse First Boston, based upon a single email that read “clean up those files” in December 2000. That was more than enough for his “intent” requirement to obstruct justice. This further illustrates the double standard of justice for them vs. us.

[..] James Comey was the chief prosecutor in the Southern District of New York between 2003 and 2005. He had no problem keeping me in Federal Prison on contempt of court without any charges, indictment, or a civil complaint describing any crime whatsoever that they even admitted openly in court. There were never any charges or complaint filed, and they publicly stated, “[T]here is no description of criminal liability.” Yet, Comey allowed me to be held in prison, entirely arbitrarily, with absolutely nothing whatsoever; Comey completely violated my civil rights, those of my family, and all 240 employees. So he is not someone who upholds the Constitution when it goes against government or the banks. As they say, the Department of Justice is really “Just Us” in reality. He has proven that once again.

Read more …

Feb 032016
 
 February 3, 2016  Posted by at 11:19 am Finance Tagged with: , , , , , , , ,  Comments Off on Debt Rattle February 3 2016


DPC Jai alai hall, Havana, Cuba 1904

Recession Risks Warn Of ‘Severe’ Drop In The Stock Market (MW)
Exxon Faces First Downgrade in 86 Years (BBG)
Iraq Sells Oil At $22, Fiscal Cliff Looms (BI)
Goldman Sachs Questions Capitalism (BBG)
Eurozone Manufacturing & Service Industries Cut Prices (BBG)
Plan To Increase The Yuan’s Trading Flexibility Gains Momentum (BBG)
Spring Festival Travel A One-Way Journey For Many Chinese (CNBC)
Buying A Home Is Overrated (MW)
The Bank of Japan Is Selling Out Its People (Gefira)
Hedge Funds, Wall Street not Happy with the New Spain (Don Quijones)
Thousands Of Greek Firms Flee To Bulgaria (Kath.)
Australian Asylum Ruling Paves Way For Deportation Of Infants (Reuters)
Greek Military To Oversee Response To Refugee Crisis (Kath.)
More Than 62,000 Migrant Arrivals In Greece Last Month (Reuters)
UN Says One-Third Of Refugees Sailing To Europe Are Children (Guardian)
Nine Migrants, Including Two Babies, Drown En Route To Greece (Reuters)

That graph feels so scary it gives me the shivers. And Deutsche sees ‘healthy’ growth return later this year? Who are they kidding?

Recession Risks Warn Of ‘Severe’ Drop In The Stock Market (MW)

Another brokerage firm has used the “R” word on Tuesday, warning investors to wake up to the idea that rising risks of a recession could send the stock market over a steep cliff. Based on current valuations, the prices of most stocks don’t appear to have factored in a recession scenario, “hence the downside should we see a recession could be rather severe,” RBC Capital Markets’ global equity team wrote in a research note to clients. Applying a stress test to their coverage universe, using worst-case, price-to-earnings valuations seen during the 2008-to-2009 recession, RBC analysts said they believe the shares of most companies could still fall another 50% or more from current levels. The concern for RBC analysts stems from the recently volatility in the stock market, caused by macro weakness, softness in China and commodity market challenges.

On Monday, Deutsche Bank strategist David Bianco said the second-half of 2015 was “clearly a profit recession” for S&P 500 companies, and suggested it probably won’t be until the second half of this year that “healthy” growth returns. Nearly half of S&P 500 companies have now reported fourth-quarter results through Tuesday morning, and earnings-per-share is headed for a 5.8% decline on the year, according to FactSet, compared with an estimated 5.7% decline as of Friday. That’s the data provider’s blended growth rate, which combines those companies that have reported with the estimates for the rest. That would be the third-straight quarter of an EPS decline, the longest such streak since the Great Recession. Among Tuesday’s culprits for the earnings decline, Exxon Mobil reported a 58% profit plunge and Pfizer reported a 50% earnings drop. Royal Caribbean Cruises reported earnings that nearly doubled, but the stock plunged 16% after the company provided a weak first-quarter outlook.

Read more …

We write history.

Exxon Faces First Downgrade in 86 Years (BBG)

Exxon Mobil, one of three U.S. companies with Standard & Poor’s highest rating, is facing its first downgrade in 86 years as the worst crude-market collapse in a generation strangles oil producers of cash. For Exxon, that would be a historic event: the global explorer that traces its roots to the 19th century and John D. Rockefeller’s Standard Oil Trust has been rated AAA by S&P since 1930. The oil giant was placed on credit watch with negative implications because its credit measures probably will remain weak through 2018, S&P said Tuesday.

“We get value from our AAA credit rating in our business,” Exxon’s Vice President of Investor Relations Jeffrey Woodbury said during a conference call with analysts before the credit review was announced. “Whether it be access to financial markets or access to resources, there is a benefit that we get from it, and we see it as being important.” The world’s five largest oil explorers had their credit ratings cut or threatened with downgrade as the market crash undermines their ability to pay debts, dividends and rig leases. For most of the oil industry, slashing drilling budgets and other cost-cutting “are insufficient to stem the meaningful deterioration expected in credit measures over the next few years,” S&P said.

In a sweeping review that also included many of the top U.S. shale drillers, Chevron had its rating cut by S&P, to AA- from AA, for the first time in almost 30 years, a day after Shell’s rating was reduced to the lowest since S&P began coverage in 1990. Exxon, Totaland BP may be next, the rating company said. S&P said it’ll decide whether to downgrade Irving, Texas-based Exxon within 90 days. If it does cut the rating, it’ll probably only be by a single notch, S&P said. Shell’s long-term credit rating was reduced on Monday by one level to A+, the fifth-highest investment grade, from AA-, and was placed on watch for another possible reduction, the ratings company said Tuesday. S&P also assigned negative outlooks to BP, Eni, Repsol, Statoil and Total.

Read more …

Bail out.

Iraq Sells Oil At $22, Fiscal Cliff Looms (BI)

The plunge in oil prices is already having far-reaching effects on countries whose economies are dependent on oil exports. But in Iraq, the stakes of cheap oil are even higher than in Saudi Arabia, which is instituting unprecedented taxation and austerity, or in Nigeria, which is now asking for an $11 billion World Bank loan. What little remains of Iraq’s government and social order might collapse if oil remains in its current price trough — with dire consequences. According to a Monday AFP report, Iraq is now selling oil at half of the country’s apparent fiscal break-even price. Right now, Iraq is selling its oil at around $22 a barrel, half of what it would need to fetch for the country to be able to fund the upcoming year of government budgetary obligations, the report said.

But Iraq’s situation is actually even worse. As recently as the 2014 fiscal year, Iraq was formulating its national budget on the assumption that oil would remain at around $90 a barrel and that the country’s oil exports would continue to climb (which they have). Iraqi government revenue experienced dramatic annual increases between 2009 and 2013, almost entirely because of oil. That’s all over, now that oil is expected to stay under $40 a barrel through the end of the year. Though Iraqi oil is comparatively cheap to extract, it also contains unusually high levels of sulfur, meaning that it typically sells for around 10% less than Brent crude, the global price benchmark.

The Iraqi government is still making money pumping oil — just not nearly enough to fund the country’s anticipated national budget. Such a daunting fiscal cliff would be challenging for a stable or politically coherent country. But it’s potentially disastrous in a place like Iraq, where the majority of territory is split between the terrorist group ISIS and the Kurdistan Regional Government. Even the areas still under some semblance of federal control are fought over by a constellation of militia groups with ties to recognized political parties.

Read more …

Shouldn’t they question the Fed instead?

Goldman Sachs Questions Capitalism (BBG)

One of the most heated debates among investors is the question of whether corporate profit margins can maintain their elevated level, or whether they will inevitably mean revert. Here’s a quick look at S&P 500 profit margins, for example, going back over 25 years. They remain high by by historical standards.

A new note from Goldman Sachs analysts led by Sumana Manohar looks at the bull and bear arguments for the profit margins debate. Manohar argues that profit margins have expanded thanks to three key trends: strong commodities prices, emerging market cost arbitrage (companies making things more cheaply in emerging markets), demand growth from emerging markets, and improved corporate efficiency driven by the use of new technology. Continuing one of its major analytical themes of recent months, Goldman also notes that the market has rewarded companies that have undertaken mergers and share buybacks, compared to companies that have invested internally, further bolstering margins. So will profit margins inevitably roll over?

Goldman goes through both sides of the argument. On the bull side, the bank says that ongoing consolidation in industries, cost deflation, and tighter purse strings help keep a floor under margins. Ultimately though, it thinks that the above trends, coupled with weak demand and general industrial overcapacity, mean that margins are likely to come down. But what if margins stay elevated? That too is possible, and the implications could be unsettling. Goldman writes: “We are always wary of guiding for mean reversion. But, if we are wrong and high margins manage to endure for the next few years (particularly when global demand growth is below trend), there are broader questions to be asked about the efficacy of capitalism.”

In other words, profit margins should naturally mean-revert and oscillate. The existence of fat margins should encourage new competitors and pricing cycles that cause those margins to erode while conversely, at the bottom of the cycle, low margins should lead to weaker players exiting the business and giving stronger companies more breathing space. If that cycle doesn’t continue, then something strange is taking place. Needless to say, it’s not every day you see a major investment bank say they might have to start asking broader questions about capitalism itself.

Read more …

Deflation’s in the driver’s seat, and there’s nothing anyone can do. Cutting prices is just one step in the process.

Eurozone Manufacturing & Service Industries Cut Prices (BBG)

The euro area’s manufacturing and services industries cut prices at the fastest pace in almost a year in January, underlining concerns about weak inflation in the region. Markit Economics said its composite Purchasing Managers Index for January was “disappointing” and raises the prospect that the ECB will once again pump up its stimulus program. The PMI declined to 53.6 – a 4-month low – from 54.3 in December, and the measure of output prices dropped to the lowest since March. “Most worrying of all from a policy maker’s perspective is the intensification of deflationary pressures.,” said Chris Williamson, chief economist at Markit in London. “This raises the question of whether existing stimulus has simply been insufficient, or whether monetary policy is proving ineffective.”

ECB President Mario Draghi has said the Governing Council will review its stimulus in March amid signs that falling oil prices will push the euro region’s inflation rate back to zero. The Bank of Japan has already responded to the deteriorating outlook with negative interest rates and investors see a slower pace of tightening by the Federal Reserve. In the euro area, Markit said the PMI had some “mildly positive signs,” with rising levels of employment and backlogs of work. The headline composite number was also marginally better than the initial estimate, and it remains above the key 50 level that divides expansion from contraction. The services index slipped to 53.6 from 54.2, matching the preliminary reading. The composite report continued to point to divergences in the 19-nation economy, with Spain and Germany leading growth. France offered a disappointing reading, with the index at just 50.2, lower than the 50.5 initial estimate.

Read more …

They sent them a what? “The PBOC didn’t immediately reply to a fax seeking comment.”

Plan To Increase The Yuan’s Trading Flexibility Gains Momentum (BBG)

A proposal to fix the yuan’s quandary is gaining momentum among some economists. The plan, put forward by at least three analysts, calls for China to let the yuan fluctuate freely against a basket of currencies within a trading band. Outside the range – which would be as narrow as 4% or as wide as 15% under different versions of the proposal – the central bank will intervene in the market. Similar to what Singapore has adopted, the plan could be China’s get-out-of-jail card after a slew of changes in its opaque currency policy since August whipsawed investors and cost the central bank more than $500 billion in reserves, said the economists, including a former central bank adviser and a visiting scholar from the IMF.

Under the current system, the yuan is allowed to trade 2% above or below a reference rate versus the dollar set by the People’s Bank of China. Critics say that the regime fixates investors’ attention on the dollar-yuan exchange rate, even as the authorities aim to break its tie to the strengthening U.S. currency. The lack of transparency on how it sets the reference rate, or fixing, keeps investors guessing about the intentions of policy makers. “They are sort of stuck, I don’t think the market knows what exactly the policy is,” Tamim Bayoumi, a senior fellow at Peterson Institute for International Economics and an economist at the IMF since 1988, said from Washington. “The proposal is one way out of that,” said Bayoumi, who pitched the idea in a blog in December, favoring a 4% trading band.

By targeting a broader range of currencies and a wider band, the proposed system attempts to give market forces more sway in determining the exchange rates, save foreign reserves while shifting investors’ focus away from the dollar and provide clarity on policy. The PBOC didn’t immediately reply to a fax seeking comment. Chinese policy makers have been struggling to restore calm in the yuan since August when it revamped its currency system to make it more flexible. While the authorities have repeatedly said they aim to keep the exchange rate stable against a basket of currencies even if it falls versus the dollar, they have had little success convincing investors. The onshore yuan’s 5.6% slide versus the dollar over the past six months fueled expectations for a further depreciation and boosted capital outflows.

Read more …

I see a lot of unhappy people in our future.

Spring Festival Travel A One-Way Journey For Many Chinese (CNBC)

A giant annual human migration is underway in China, and it’s a bonanza for some but a painful process for others. Some 2.9 billion trips are expected to be undertaken between the start of China’s annual travel season on January 24 and the end on March 3, according to China’s transport ministry, with this week leading up to Spring Festival or Lunar New Year, which starts on February 8, being the busiest. [..] According to a real-time travel map by Chinese internet giant Baidu, the Beijing-to-Shanghai route on Wednesday afternoon in Asia was the most heavily traveled across all forms of transport, followed by Xian to Beijing and Shenyang to Beijing. For many migrant workers, however, this year’s journey home may be their final one, as slowing growth puts paid to their city dreams.

China’s factory activity skidded to a three-year low point in January, adding to gloom about the state of the world’s second-largest economy. Although growth in the service sector held above the key 50 expansionary level, the January official non-manufacturing purchasing manager’s index slowed to 53.5 from 54.4 in December. Restaurant workers Du Lijuan and Song Yaoguo told CNBC that they would not be among the crush of travelers this week. Both are waiting in Beijing for unpaid salaries of about $1,000 each before heading back home to the countryside, after losing their at a restaurant when it ran into financial difficulties in September. “We have no money to buy tickets, to buy gifts for our family or children,” Du said. “Normally, we spend $650 every Lunar New Year. I am not coming back [to Beijing].”

For years, migrant workers have been the backbone of China’s economic growth, by working in factories and constructing buildings, but many are considering new lives in the countryside after this Spring Festival, because they fear being unable to find jobs if they return to the cities. The migrant population fell by 5.7 million to 247 million in 2015, its first drop in about three decades.

Read more …

It’s the debt, stupid!

Buying A Home Is Overrated (MW)

Is buying a house instead of renting really the best financial decision? It’s a question that’s frequently debated, with traditional thinking being that renting is akin to throwing money out the window. But there are some good reasons to believe that buying a home instead of renting isn’t as great of an investment as Americans once thought. “Housing is overrated as a financial investment,” according to economist Alex Tabarrok, an economics professor at George Mason University and a research fellow at the university’s Mercatus Center, which conducts research on financial markets. He addressed the question of what economists think about buying compared to renting on Marginal Revolution, a blog he runs with fellow economist and George Mason professor Tyler Cowen.

“First, it’s not good to have a significant share of your wealth locked into a single asset,” he wrote. “Diversification is better and it’s easier to diversify with stocks. Second, unless you are renting the basement, houses don’t pay dividends. Stocks do. You can hope that your house will accumulate in value but don’t count on it. Indeed, you should expect that as an investment your house will appreciate less than does the stock market.” Owning a home makes it harder for many people to change locations for new job opportunities, leading to homeowners holding onto homes even while prices fall, Tabarrok said. Still, Americans don’t seem to be giving up on homeownership yet. Sales of existing homes rose 14.7% in December, the biggest monthly increase ever recorded, after depressed sales in November. Sales in 2015 were the best since 2006, at 5.26 million.

Americans are also buying homes that are larger and pricier; average home size was 2,720 square feet in 2015, up from 2,660 square feet in 2014. And the average price of new homes for sale in 2015 was $351,000, up from $100,000 in 2009. (Still, this doesn’t necessarily reflect the housing market’s strength, as new construction has mostly happened in the high-end market.) Of course, there are some benefits to homeownership, and they aren’t just avoiding unexpected rent hikes and unpredictable landlords. Many people simply enjoy interior decorating and entertaining, Tabarrok added. And perhaps more importantly, home ownership is often tied to access to better public schools. The U.S. tax code also subsidizes houses. Still, he cautioned against the seduction of a large home. “Behavioral economics tells us that we quickly get used to big houses, but we never get used to commuting,” he wrote. “So when you have a choice, go for the smaller house closer to work.”

Read more …

h/t ZH

The Bank of Japan Is Selling Out Its People (Gefira)

The Bank of Japan’s unexpected rate cuts to negative are a desperate attempt to help out the FED and to support the dollar at the expense of the aging Japanese population. The negative market reaction to the FED’s rate hike of December shows that investors do not believe an economic recovery in the US is underway. Two reasons make central banks start to raise interest rates. The first is that economy is doing well, and central banks have to prevent an overheated economy. But it is also a signal to investors everything is going well. In this situation, the first reaction of investors will be the opposite as central bankers planned they will and increase their investments and markets will go up. The second reason central banks raise interest rates is the defensive one; the moment the economy is out of control, investors are beginning to abandon the sinking ship.

The continually increasing interest rate has the task of keeping the investors aboard. Central banks in less developed economies raise rates to defend the national currency, thus preventing investors from fleeing. An increase in the interest rate can add fuel to the fire and in many cases has the opposite effect. Investors start smelling angst of the authorities and start abandoning the sinking ship. In such a situation stock markets are coming crashing down because investors withdraw from them. We saw this last pattern happening in the US economy after the December FED’s rate hike. As a result, the dollar-yen exchange rate is starting to decline, with the value of the dollar falling off as Japanese investors start panicking and fleeing the US market. Surely, Japanese investors know that a rate hike without an accompanying economic growth will erode every existing investment.

There is a general misconception according to which countries drive their currency down to generate growth. People adhere to the simplistic belief that a weak currency drives exports and helps the nation to prosper. The fact is that a cheap currency creates growth by giving away real goods in exchange for IOU (I Owe Yous) or paper debt obligations that will never be repaid. The US is the beneficiary or the receiving end of the weak yen policy. Because the US continues to maintain its world hegemony, it needs a strong dollar. A strong dollar makes everything the US empire buys in the world cheap. A strong dollar causes the world to be willing to exchange real goods for printed paper dollars that have no intrinsic value, and that are issued by a country that does not have the industrial capacity to ever repay what it owes its debtors.

The endless trade deficit the US has with Japan shows how the Japanese are prepared to provide the US with real goods without demanding tangible goods in return. Because the international press publishes trade data in dollars, the trade balance deficit seems to have been shrinking over the last years. The actual situation becomes apparent if we look at the trade deficit in yens. The US trade deficit with Japan is growing bigger and bigger year after year, as Japanese producers are giving away a big chunk of their production to US consumers in return for more and more US paper debt. By manipulating the yen, Japanese authorities are giving away a real part of their GDP that they take from their people to the US empire.

Read more …

Very good. Do read the whole thing. The socialists have been asked to form a government.

Hedge Funds, Wall Street not Happy with the New Spain (Don Quijones)

Plunging shares, shrinking profits, and a spate of new regulations and court cases that could end up setting it back billions of euros – that’s what the Spanish banking sector is facing. But now, banks are also grappling with the complete absence of a friendly central government to insulate them from the cruel vagaries of the global economic downturn. And the strain is beginning to show. “The political parties must reach an agreement as soon as possible and form a government that is stable,” pleaded Francisco González, president of Spain’s second biggest bank, BBVA. Such a government must not “think about utopias, which only serve to create frustration,” must be “realistic” and (most important of all) must “continue with the policies of the last three of four years.”

González cautioned that foreign investors “are phoning less often” than before. Those “investors” probably include firms like Blackstone and Goldman Sachs, which made a fortune in the immediate aftermath of Spain’s real estate collapse and EU-funded bailout, by picking up publicly subsidized housing on the cheap and either flipping them or renting them at much higher rates. In those days, the city council was led by Ana Botella, the then Mayor and wife of Spain’s former President José María Aznar. One of the main brokers in the deals struck between the city council’s two housing agencies and international funds like Goldman and Blackstone was José María Aznar Botella – their son!

Despite his lack of investment banking experience, Aznar Botella served as an advisor and go-between at the Madrid-based real estate firm Gesnova Gestión Inmobiliaria Integral, which enjoyed close ties with firms like Blackstone subsidiary Fidere, Lone Star, Apollo, KKR, Goldman’s Madrid-based subsidiary Azora, and U.S. private equity firm Cerberus Capital Management LP, whom Aznar-Botella also serves as an advisor. Here’s how the scheme worked: in the aftermath of Spain’s real estate bust, the Rajoy government set up a bad bank by the name of Sareb, a public-private venture responsible for managing distressed assets transferred from the four nationalized financial institutions BFA-Bankia, Catalunya Banc, NGC Banco-Banco Gallego, and Banco de Valencia.

As soon as the bad bank was operational, global investment firms began flocking to Madrid to pick up the juiciest pieces at the best prices, part-subsidized by Spanish taxpayers. To get their hands on the really good stuff, however, investors needed someone on the inside, which is presumably where the Aznar-Botello mother & son partnership came in. But it’s one thing to sell tranches of unoccupied or foreclosed properties to foreign investors to help put a floor under Spain’s property market; it’s quite another when you start selling huge batches of social housing at a ridiculous discount to some of the biggest financial firms on the planet, in a country that has one of the smallest stocks of social housing in Europe. It didn’t take long before rents began soaring and the police began knocking doors down.

Read more …

The Troika making sure Greece will never recover.

Thousands Of Greek Firms Flee To Bulgaria (Kath.)

According to the president of the Hellenic Confederation of Professionals, Craftsmen and Merchants (GSEVEE), some 6,000 Greek enterprises have emigrated to Bulgaria in the last couple of years alone. At the same time, the GSEVEE chief says, Greeks are behind about 60,000 new tax registrations and bank accounts in the neighboring country. Giorgos Kavathas on Tuesday cited the above figures from an ongoing survey by GSEVEE, adding that the interventions planned for the social security system can only be expected to lead to more Greek firms emigrating. The survey will be presented in the next few days, he noted.

He was speaking at a press conference held jointly by GSEVEE and the Hellenic Confederation of Commerce and Enterprises (ESEE) regarding their participation in tomorrow’s general strike against the government’s planned pension reforms. The two unions warned that manufacturers and merchants will not stop at this strike, and will escalate their industrial action further. “The social security matter is a major national issue and we agree there has to be a reform, although no actuarial study would lead to safe conclusions given the existence of 1.5 million jobless,” argued the president of ESEE, Vassilis Korkidis.

Read more …

Trying to rival the EU in inhumanity.

Australian Asylum Ruling Paves Way For Deportation Of Infants (Reuters)

Australia’s High Court threw out a challenge to offshore immigration detention camps on Wednesday, clearing the way for the deportation of dozens of infants born in Australia to detained asylum seekers. The court rejected a legal test case brought by an unidentified Bangladeshi woman that challenged Australia’s right to deport detained asylum seekers to the tiny South Pacific island nation of Nauru. The detention centre on Nauru houses about 500 people and has been widely criticised by the United Nations and human rights agencies for harsh conditions and reports of systemic child abuse. The Bangladeshi woman was on a boat intercepted by Australian authorities in October 2013. She was detained on Australia’s remote Christmas Island and later sent to Nauru.

She gave birth to a daughter after she was transferred to Australia for medical treatment in 2014 and has remained there with her child. Other families with children born in Australia in similar circumstances are now in line to be returned to the camps. Lawyers from the Human Rights Law Centre (HRLC) acting for the Bangladeshi woman had argued it was illegal for Australia to operate and pay for offshore detention in a third country. “I hope that the immigration minister and the prime minister, just like other decent Australians, can see that there is simply no excuse to take 37 babies, to rip children from their classrooms, and warehouse them on a tiny island,” HRLC Director of Legal Advocacy Daniel Webb told reporters. “Now, the legality may be complex. The politics may be complex. But the morality is simple. It is fundamentally wrong.”

Read more …

It’s all aimed at streamlining the process to move refugees north. But that’s not what Europe wants.

Greek Military To Oversee Response To Refugee Crisis (Kath.)

Defense Minister Panos Kammenos on Tuesday heralded the creation of a central body to oversee and improve Greece’s response to the migration and refugee crisis and ensure the country safeguards its position in the Schengen passport-free area, noting that the new body will be led by a senior military official. Greece’s military is to have the oversight of the “Central Coordinating Body for the Management of Migration” until the Migration Ministry and the Hellenic Police gain the necessary know-how and experience to tackle the problem independently, Kammenos indicated at Tuesday’s press conference.

The center, which is to be operational by February 15, is to be based at the Defense Ministry headquarters and coordinate with the Hellenic Police, Coast Guard, Migration Ministry and nongovernmental organizations working with migrants and refugees. The aim is to increase the efficiency of transferring migrants from the islands to the mainland, to improve the provision of food as well as medical and healthcare to migrants, and to monitor the creation of five screening centers, or hot spots, for migrants on the eastern Aegean islands of Lesvos, Chios, Samos, Kos and Leros. Referring to the growing pressure on the islands of the eastern Aegean that receive thousands of migrants daily from neighboring Turkey, Kammenos explained that the new plan aims to spread the burden.

The five hot spots to be set up on the islands are to accommodate migrants for only 24 hours while two relocation centers, on the outskirts of Athens and Thessaloniki, will host new arrivals for up to 72 hours. The screening and relocation centers are to operate in a similar way to the central body, under a local military official who is to coordinate with police and coast guard officers. As the European Union increases the pressure on Greece to manage its borders more effectively, French Interior Minister Bernard Cazeneuve is due in Athens on Thursday and Friday for talks expected to focus on the migration crisis.

Read more …

Wow! Imagine what spring will bring.

More Than 62,000 Migrant Arrivals In Greece Last Month (Reuters)

The total number of migrants and refugees arriving in Greece in January topped 62,000, the International Organization for Migration said on Tuesday. “(It) is many, many times what we saw a year ago in the previous January,” IOM spokesman Joel Millman said. He added that there were more than 360 deaths among migrants in the waters off Greece, Turkey and Italy during the month.

Read more …

When are we going to get real about this?

UN Says One-Third Of Refugees Sailing To Europe Are Children (Guardian)

Children now make up over a third of the people making the perilous sea crossing from Turkey to Greece, the UN has said, as two more babies drowned off Europe’s shores. For the first time since the start of the migration crisis in Europe, there are also now more women and children crossing the border from Greece to Macedonia than adult males, according to UN children’s agency Unicef. The figures emerged as Europe struggles with its biggest movement of people crisis since the second world war, with more than a million people fleeing war, violence and poverty risking life and limb to reach its shores last year. “Children currently account for 36% of those risking the treacherous sea crossing between Greece and Turkey,” the Unicef spokeswoman Sarah Crowe said.

“Children and women on the move now make up nearly 60%” of those entering from Macedonia, she added. The figures mark a significant shift since June, when 73% of refugees were adult males and only one in 10 were under the age of 18. Marie Pierre Poirier, Unicef’s special coordinator for the refugee and migrant crisis in Europe, said women and children were even more vulnerable to the dangers of trying to travel to Europe. “The implication of this surge in the proportion of children and women on the move are enormous,” she said in a statement. “It means more are at risk at sea, especially now in the winter, and more need protection on land.” Underlining her point, the International Organisation for Migration (IOM) said on Tuesday that one in every five who drowned last month while trying to sail from Turkey to Greece was a child, with minors accounting for 60 of the 272 deaths.

Including January, a total of 330 children have died in those waters over the last five months, many of them just metres from shore, the organisation said. The drownings continue a grim trend that accelerated last year when nearly 4,000 people died trying to reach Europe by sea. The plight of children was brought home last year when the body of Syrian toddler Alan Kurdi was found washed up on the shore close to Bodrum, Turkey, horrifying the international community. The bodies of two more babies were recovered by the Turkish coastguard in the Izmir province on Tuesday along with seven dead adults, just days after another 37 people drowned off another part of the coast.

Read more …

Europe will not be pardoned for this.

Nine Migrants, Including Two Babies, Drown En Route To Greece (Reuters)

The bodies of nine people, including two babies, were found drowned off the coast of western Turkey on Tuesday, after a boat carrying refugees and migrants to Greece partly capsized, the Turkish coast guard said in a statement. The fiberglass vessel partially capsized at 0535 local time (0335 GMT) off the coast of Seferihisar in Izmir province, close to the Greek Island of Samos. Two people were rescued swimming to the shore, the coast guard said. A crackdown on illegal crossing and the dangerous winter conditions has failed to deter tens of thousands from boarding flimsy boats and attempting to cross the Mediterranean waves in the first few weeks of the year.

Read more …

Dec 222015
 
 December 22, 2015  Posted by at 9:06 am Finance Tagged with: , , , , , , , , ,  Comments Off on Debt Rattle December 22 2015


DPC Old Absinthe House, bar, New Orleans 1906


Global Investors Are More Exposed To Interest-Rate Hikes Than Ever (BBG)
The Keynesian Recovery Meme Is About To Get Mugged, Part 1 (Stockman)
Brent Oil Hits 11-Year Low As Global Supply Balloons (Reuters)
US Gas Prices Fall Below $2 – In Some Places Under $1.60 (MarketWatch)
The Real “Death Cross” Of Oil Markets (ZH)
Risk Of Insolvency Hangs Over UK High Street Retailers (Guardian)
UK Economy Concerns As Household Debt Balloons To £40 Billion (PA)
The Bank of Japan’s $2.5 Billion Plan to Buy Non-Existent ETFs (BBG)
China ‘Suspends’ Another Unofficial PMI Data Set For A ‘Major Adjustment’ (ZH)
Zimbabwe To Make Chinese Yuan Legal Currency After Beijing Cancels Debts (AFP)
Russia, EU Trade Talks Fail, Kiev Set To Face Retaliation (Reuters)
Political Uprising In Spain Shatters Illusion Of Eurozone Recovery (AEP)
Portugal Taxpayers Face €3 Billion Loss After 2nd Bank Bailout In 2 Years (ZH)
Christmas Present (Jim Kunstler)
Et Tu, Brute? – How Empires Die (Thomas)
Do We Need The Fed? (Ron Paul)
Apple Says UK Surveillance Law Would Endanger All Customers (BBG)
Half of World’s Coal Must Go Unmined to Meet Paris Climate Target (BBG)
It’s ‘Almost Too Late’ To Stop A Global Superbug Crisis (PA)

Because the entire system is leveraged to the hilt.

Global Investors Are More Exposed To Interest-Rate Hikes Than Ever (BBG)

With any luck, the world economy will eventually be strong enough for central banks to follow the U.S. Federal Reserve in ending what has been an unprecedented period of extremely low interest rates. If and when they do, they’ll run straight into the same issue that the Fed now faces: Raising rates will precipitate unusually large losses for investors. Over the past several years, investors have gone to great lengths in their search for returns in a low-rate environment. They’ve done so in part by buying longer-maturity bonds, which tend to offer higher yields but are also more sensitive to changes in rates. One gauge of this risk is effective duration, which estimates the percentage decline in a bond’s price given a one-percentage-point increase in yield.

The measure is near all-time highs in the U.S., according to a report issued last week by the Office of Financial Research. The situation globally is no less precarious. Consider the effective duration for the BofA Merrill Lynch Global Broad Market Index, which tracks about $45 trillion in investment-grade bonds issued in major currencies – including government, corporate, mortgage and other asset-backed securities. As of last week, it stood at 6.6, meaning that a one-percentage-point increase in yield would wipe almost $3 trillion off the value of all the bonds included in the index. That’s a larger potential loss than at just about any point since the index’s inception in 1996. Here’s how that looks:
The high level of interest-rate risk illustrates a dilemma for central bankers everywhere. The power of traditional monetary stimulus depends in large part on the willingness of people and companies to borrow for new projects and purchases. But as the debt burden grows, it makes markets and the entire economy more susceptible to rate increases. It can also undermine the effect of rate cuts, as borrowers increasingly struggle under the weight of their existing obligations.

Read more …

“These academic pettifoggers are so blinded by their tinker toy macro-model that they can’t even see the flashing red lights warning of recession just ahead.”

The Keynesian Recovery Meme Is About To Get Mugged, Part 1 (Stockman)

Yellen said at least one thing of importance last week, but not in a good way. She confessed to the frightening truth that the FOMC formulates its policies and actions based on forecasts of future economic developments. My point is not simply that our monetary politburo couldn’t forecast its way out of a paper bag; that much they have proved in spades during their last few years of madcap money printing. Notwithstanding the most aggressive monetary stimulus in recorded history – 84 months of ZIRP and $3.5 trillion of bond purchases – average real GDP growth has barely amounted to 50% of the Fed’s preceding year forecast; and even that shortfall is understated owing to the BEA’s systemic suppression of the GDP deflator.
What I am getting at is that it’s inherently impossible to forecast the economic future, but that is especially true when the forecasting model is an obsolete Keynesian relic which essentially assumes a closed US economy and that balance sheets don’t matter. Actually, balance sheets now matter more than anything else. The $225 trillion of debt weighing on the world economy – up an astonishing 5.5X in the last two decades – imposes a stiff barrier to growth that our Keynesian monetary suzerains ignore entirely. Likewise, the economy is now seamlessly global, meaning that everything which counts such as labor supply and wage trends, capacity utilization and investment rates and the pace of business activity and inventory stocks is planetary in nature. By contrast, due to the narrow range of activity they capture, the BLS’ deeply flawed domestic labor statistics are nearly useless. And they are a seriously lagging indicator to boot.

Nevertheless, Yellen & Co. are obsessed with the immeasurable and largely irrelevant level of “slack” in the domestic labor market. They falsely view it as a proxy for the purported gap between potential and actual GDP. Not surprisingly, they are now under the supreme illusion that the labor slack has been largely absorbed and the output gap nearly closed. So they are raising money market rates by a smidgeon to confirm the US economy’s strength and that the Keynesian nirvana of full employment is near at hand. No it isn’t! These academic pettifoggers are so blinded by their tinker toy macro-model that they can’t even see the flashing red lights warning of recession just ahead.

Read more …

Oil went up a whiff overnight. I always look at the spread between WTI and Brent. The smaller it gets, the higher the risks. Usually, it hovers between $2-3. Right now, it’s at 50 cents.

Brent Oil Hits 11-Year Low As Global Supply Balloons (Reuters)

Brent oil cratered to its lowest price in more than 11 years on Monday, as demand for heating oil slumped on warmer-than-normal temperatures and traders tested for a bottom. U.S. crude remained above its 2009 low and settled up a penny a barrel as traders squared positions ahead of the January contract’s expiration. The February contract declined and analysts expect stockpiles to build again this week, signaling further oversupply in already glutted market. Concerns about swelling global crude supply and slow demand sparked by economic weakness in China have been recurring themes during this year’s rout. Analysts said the market was still testing for a bottom. “The key in finding the bottom of the market comes in a tightening of the supply side,” said Gene McGillian, senior analyst at Tradition Energy in Stamford, Connecticut.

OPEC and Russia will keep producing at high volumes, increasing pressure on U.S. producers to throttle back production, he said. “I think we’re getting ready for another round of capex cuts in North America,” he said. Heating oil futures weighed down the crude complex, hitting a new July 2004 low warmer-than-expected temperatures have hit seasonal demand. “The market is waiting for the next announcement,” said Tyche Capital Advisors senior research analyst John Macaluso. “The equity markets are waiting on crude oil, and crude oil is waiting for a bounce before shorts will come back into the market.” Crude short-sellers will be reluctant to return before U.S. crude recovers to $35.50, he said. Global oil production is running close to record highs. With more barrels poised to enter the market from nations such as Iran and Libya, the price of crude is set for its largest monthly percentage decline in seven years.

Read more …

“..1% of stations selling gas at $1.59 a gallon..”

US Gas Prices Fall Below $2 – In Some Places Under $1.60 (MarketWatch)

Christmas came early for U.S. drivers on Monday, as the national average gasoline price fell below $2 a gallon for the first time since March 2009. AAA put the average U.S. gas price at $1.998 per gallon on Monday, while fuel-price tracking service GasBuddy.com calculated the national average at $1.995 a gallon. That’s the lowest price by either measure since March 25, 2009. Unsurprisingly, drivers can credit a global glut of crude oil for the steady pressure on gas prices. Brent crude the global oil benchmark, plumbed levels last seen in 2004 on Monday, while the January contract for the U.S. benchmark CLF6, -0.20% West Texas Intermediate crude, was down 49 cents, or 1.4%, ahead of expiration at $34.24 a barrel on Nymex. The most-active February contract is down 1.3% at $35.58.

“In areas where there are no refinery bottlenecks, we’ve been able to see the falling price of crude oil translated directly into cheaper gas prices,” said Patrick DeHaan, senior petroleum analyst at GasBuddy.com, in a phone interview. Nymex reformulated gasoline futures for January delivery slumped 6.33 cents, or 5%, to $1.2114 a gallon. So how low are gas prices? In much of the country, the price is already well under $2 a gallon, AAA notes, with 1% of stations selling gas at $1.59 a gallon. On a state-by-state basis, Missouri has the lowest average price at $1.77, followed by Oklahoma and South Carolina at $1.78, and Tennessee and Kansas at $1.79.
Read more …

China. That’s all.

The Real “Death Cross” Of Oil Markets (ZH)

The ‘death cross’ of these two energy market indicators is all one needs to know about the oil market… As Bloomberg notes, total industry oil stocks reported by the International Energy Agency rose for a third month, increasing by 0.5% to the highest on record at 2.99 billion barrels. China’s Beige Book, released last week, showed further economic deterioration in one of the world’s largest commodity-consuming nations in the fourth quarter. Until these two indicators change direction, lower-er for longer-er will remain.
Read more …

Lots of last legs there.

Risk Of Insolvency Hangs Over UK High Street Retailers (Guardian)

A string of retailers could face insolvency in the new year with tough trading on the high street in the run-up to Christmas leaving businesses fighting for survival, two influential industry bodies have warned. Widespread discounting and warmer-than-average weather have cranked up the pressure on high street retailers over the festive period. In the last few years a number of high street retailers have called in administrations either just before or after Christmas, including Woolworths, HMV, Zavvi, and Jessops. Retailers generate roughly 40% of their annual profits between October and December, underlining the importance of the period. However, if a high street business struggles during the festive season then its death knell is typically the quarterly rental payment they have to make to landlords at the end of December.

Atradius, one of the world’s largest trade credit insurers, has warned that retailers face a “perfect storm” that could lead to a bleak start to 2016 and a “fresh wave of insolvencies”. The comments from Atradius are significant because if a credit insurer refuses to back a retailer then suppliers will be unable to insure their orders with the business and could decide not to provide it with products. Owen Bassett, senior risk underwriter at Atradius, said: “Those who went into the fourth quarter needing – rather than wanting – a strong performance could be looking at a troubled future. “Experience tells us that when retailers need an exceptional seasonal sales period and then hit financial difficulty, we often see failures in the first quarter. It is not unusual in this sector to be loss-making during Q1 and with the first payment of quarterly rent due in January it can be difficult to survive after a poor Q4.”

Read more …

Private debt. Should have a lot more attention. And not just in Britain.

UK Economy Concerns As Household Debt Balloons To £40 Billion (PA)

Families are expected to run up £40bn of debt this year, sparking fears about Britain’s economic recovery. Labour raised concerns that millions of households would face “serious hardship” if interest rates rise and warned the borrowing trend could harm the economy. The latest Office for Budget Responsibility (OBR) forecasts have found that households have moved from a surplus of £67bn in 2010, the year the coalition took power, to a £40bn deficit this year. Unsustainable borrowing is on course to near the levels reached in the run-up to the 2008 financial crash, according to Labour. Seema Malhotra, the shadow chief secretary to the Treasury, said: “George Osborne is relying on millions of British families going further into debt to hit his growth targets.

“This is risky behaviour from a chancellor whose policy decisions are hurting, not helping, British families. Alarm bells should be ringing. There is a real risk that millions of families will face serious hardship if interest rates start to rise. “Of course families need access to credit and the ability to borrow to invest for the future. George Osborne should be seeking to rebalance the economy away from an over-reliance on borrowing and debt. “Labour is clear about the need for a strong and sustainable economic recovery. Osborne’s short-term political decisions risk real long-term damage to the finances of millions of British families and the nation’s economy.” The former business secretary Sir Vince Cable warned Britain was returning to “old and unhappily discredited” methods of economic growth. He told the Independent: “We’re back on the treadmill of growth being sustained by personal borrowing. Much of it is against an inflating housing stock.

Read more …

Abenomics is a different way of saying anything goes.

The Bank of Japan’s $2.5 Billion Plan to Buy Non-Existent ETFs (BBG)

Haruhiko Kuroda has a new plan. He’s going to buy $2.5 billion of something that doesn’t exist. Markets were roiled Friday after the Bank of Japan unveiled measures including purchasing exchange-traded funds that track companies which are “proactively making investment in physical and human capital.” The central bank will spend 300 billion yen ($2.5 billion) a year from April buying such securities to offset the market impact as it resumes selling stocks purchased earlier from financial institutions. The only problem is such ETFs have never been made in Japan, at least not yet. Even as fund providers start hundreds of so-called “smart beta” products that choose stocks based on everything from dividends to volatility, ETFs that pick companies for how they deploy their cash are rare in global markets.

“These kinds of ETFs don’t exist now. Using capital spending as a factor in deciding what goes in an ETF is quite unusual,” said Koei Imai, who oversees $25 billion of ETFs at Nikko Asset Management Co. in Tokyo. “I think the message from the BOJ is for us to go out and make them.” The central bank is aware such products aren’t yet available and in the meantime will buy ETFs tracking the JPX-Nikkei Index 400, a government-backed equity measure started last year that chooses companies based on return on equity and operating profit. The BOJ also already purchases ETFs linked to the Nikkei 225 Stock Average and Topix index and owns roughly half of the market for ETFs in Japan.
Read more …

How to kill confidence.

China ‘Suspends’ Another Unofficial PMI Data Set For A ‘Major Adjustment’ (ZH)

For the second time in two months, an economic data series that indicate drastically weak performance in China has been “suspended.” Having seen Markit/Caixin’s flash gauge of China’s manufacturing discontinued in October (having plunged notably divergently from the government’s official data), Bloomberg reports that the publishers of the alternative China Minxin PMI will stop updating the series to make a “major adjustment.” Guess which time series was just “suspended”…
As Bloomberg details,

Release of the unofficial purchasing managers index jointly compiled by China Minsheng Banking Corp. and the China Academy of New Supply-side Economics will be suspended starting this month, the Beijing-based academy said in an e-mailed statement Monday, about six hours before the latest monthly data were scheduled for release.

Minxin’s suspension is the second in recent months as policy makers in the world’s second-largest economy struggle to arrest a deceleration in growth. Another early estimate of China’s manufacturing sector, a flash gauge of a purchasing managers index compiled by Markit Economics and sponsored by Caixin Media, was discontinued Oct. 1. Minxin’s PMI readings are based on a monthly survey covering more than 4,000 companies, about 70% of which are smaller enterprises. The private gauges have shown a more volatile picture than the official PMIs in the past year.

The manufacturing PMI declined to 42.4 in November from 43.3 in October, while the non-manufacturing reading fell to 42.9 from 44.2, according the the latest release. The factory gauge fell to a record low of 41.9 in August. China’s official PMI from the National Bureau of Statistics fell to a three-year low of 49.6 in November.

Read more …

Humor?

Zimbabwe To Make Chinese Yuan Legal Currency After Beijing Cancels Debts (AFP)

Zimbabwe has announced that it will make the Chinese yuan legal tender after Beijing confirmed it would cancel $40m in debts. “They [China] said they are cancelling our debts that are maturing this year and we are in the process of finalising the debt instruments and calculating the debts,” minister Patrick Chinamasa said in a statement. Chinamasa also announced that Zimbabwe will officially make the Chinese yuan legal tender as it seeks to increase trade with Beijing. Zimbabwe abandoned its own dollar in 2009 after hyperinflation, which had peaked at around 500bn%, rendered it unusable. It then started using a slew of foreign currencies, including the US dollar and the South African rand.

The yuan was later added to the basket of the foreign currencies, but its use had not been approved yet for public transactions in the market dominated by the greenback. Use of the yuan “will be a function of trade between China and Zimbabwe and acceptability with customers in Zimbabwe,” the minister said. Zimbabwe’s central bank chief John Mangudya was in negotiations with the People’s Bank of China “to see whether we can enhance its usage here,” said Chinamasa. China is Zimbabwe’s biggest trading partner following Zimbabwe’s isolation by its former western trading partners over Harare’s human rights record.

Read more …

Europe’s dumb struggle with Moscow continues.

Russia, EU Trade Talks Fail, Kiev Set To Face Retaliation (Reuters)

The EU failed to allay Russia’s concerns about Ukraine’s free-trade accord with the 28-nation bloc on Monday, leaving Kiev to face Russian retaliation through tighter bilateral trade rules from 2016. Closer ties between Ukraine and the EU, including the free trade deal, were at the heart of a battle for influence between Brussels and Moscow in Russia’s former satellite. When the then-Ukrainian president, Viktor Yanukovich, ditched the accord in early 2014 under pressure from Russia, protests erupted on the street of Kiev leading to a crisis in which he fled power and a pro-Europe leadership took over. The EU and Ukraine delayed implementation of their trade deal by a year out of deference to Moscow’s concerns that it could lead to a flood of European imports across its borders, damaging the competitiveness of Russian exports.

But comments by EU and Russian officials on Monday indicated that numerous meetings between the two sides to try to narrow differences and assuage Moscow’s concerns had failed. EU Trade Commissioner Cecilia Malmstrom raised doubts about the validity of the Russian concerns, saying some were “not real.” “We have been very open in listening to some of the concerns of Russia. Some of them we think are not real in economic terms. Some of them could potentially be real,” Malmstrom told a news conference following final talks in Brussels. Russian Economy Minister Alexei Ulyukayev, speaking in Brussels, said there was no deal and Moscow would scrap trade preferences dating back to 2011 for Ukraine as of 2016, when the bilateral EU-Ukraine deal will be implemented. “An agreement has not been reached. We were left with our concerns on our own and we are forced to safeguard our economic interest unilaterally,” Ulyukayev told reporters.

Read more …
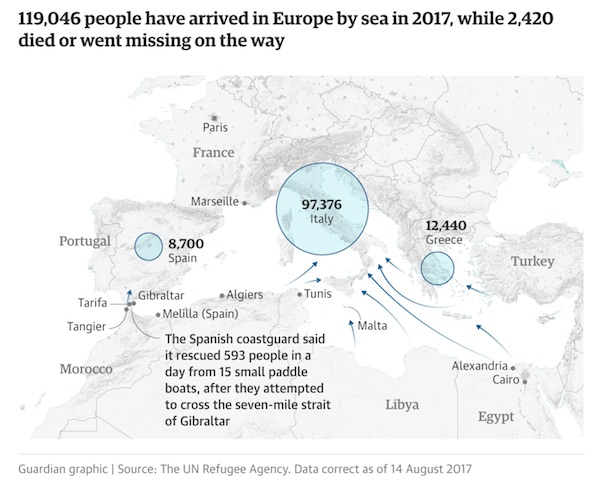
A stalemate that seems to end in either a fragile left government or new elections.

Political Uprising In Spain Shatters Illusion Of Eurozone Recovery (AEP)

Spain risks months of political paralysis and a corrosive showdown with Germany over fiscal austerity after insurgent movements smashed the traditional two-party system, leaving the country almost ungovernable. The electoral earthquake over the weekend in one of the eurozone’s ‘big four’ states has echoes of the shock upsets in Greece and Portugal this year, a reminder that the delayed political fuse from years of economic depression and mass unemployment can detonate even once the worst seems to be over. Bank stocks plummeted on the Madrid bourse as startled investors awoke to the possibility of a Left-wing coalition that included the ultra-radical Podemos party, which won 20.7pc of the votes with threats to overturn the government’s bank bail-out and to restructure financial debt.

Pablo Iglesias, the pony-tailed leader of the Podemos rebellion, warned Brussels, Berlin, and Frankfurt that Spain was retaking control over its own destiny after years of kowtowing to eurozone demands. “Our message to Europe is clear. Spain will never again be the periphery of Germany. We will strive to restore the meaning of the word sovereignty to our country,” he said. The risk spread on Spanish 10-year bonds jumped eight basis points to 123 over German Bunds, though there is no imminent danger of a fresh debt crisis as long as the European Central Bank is buying Spanish bonds under quantitative easing. The IBEX index of equities slid 2.5pc, with Banco Popular and Caixabank both off 7pc. Premier Mariano Rajoy has lost his absolute majority in the Cortes.

Support for the conservative Partido Popular crashed from 44pc to 29pc, costing Mr Rajoy 5m votes as a festering corruption scandal took its toll. The electorate punished the two mainstream parties that have dominated Spanish politics since the end of the Franco dictatorship in the 1970s, and which by turns became the reluctant enforcers of eurozone austerity. The Socialists (PSOE) averted electoral collapse but have lost their hegemony over the Left and risk being outflanked and ultimately destroyed by Podemos, just as Syriza annihilated the once-dominant PASOK party in Greece. It had been widely assumed that Mr Rajoy would have enough seats to form a coalition with the free-market and anti-corruption party Ciudadanos, but this new reform movement stalled in the closing weeks of the campaign.

“There is enormous austerity fatigue and the country as a whole has clearly shifted to the Left,” said sovereign bond strategist Nicholas Spiro. Yet the Left has not won enough votes either to form a clear government. “The issue now is whether Spain is governable. All the parties are at daggers drawn and this could drag on for weeks. I don’t see any sustainable solution. We can certainly forget about reform,” he said. Mr Spiro said Spain has already seen a “dramatic deterioration” in the underlying public finances over the last eighteen months, although this has been disguised by a cyclical rebound, the stimulus of cheap oil and a weak euro, and QE from Frankfurt. “They have simply gone for growth,” he said.

Read more …

Posterchild no more.

Portugal Taxpayers Face €3 Billion Loss After 2nd Bank Bailout In 2 Years (ZH)

Back in August of 2014, Portugal had an idea. Lisbon would use some €5 billion from the country’s Resolution Fund to shore up (read: bailout) Portugal’s second largest bank by assets, Banco Espirito Santo. The idea, basically, was to sell off Novo Banco SA (the “good bank” that was spun out of BES) in relatively short order and use the proceeds to pay back the Resolution Fun. That way, the cost to taxpayers would be zero. You didn’t have to be a financial wizard or a fortune teller to predict what was likely to happen next. Unsurprisingly, the auction process didn’t go so well.

As we recounted in September, there were any number of reasons why Portugal had trouble selling Novo, not the least of which was that two potential bidders – Anbang Insurance Group and Fosun International which, you’re reminded, is run by the recently “disappeared” Chinese Warren Buffett – suddenly became far more risk-averse in the wake of the financial market turmoil in China. Talks with US PE (Apollo specifically) also went south, presumably because no one knows if this “good” bank will actually turn out to need more capital going forward given that NPLs sit at something like 20% while the H1 loss totaled €250 million thanks to higher provisioning for said NPLs. Now, the auction process has been mothballed and will restart in January. This matters because if the bank can’t be sold, the cost of the bailout ends up being tacked onto Lisbon’s budget.

The impact is substantial. In September, when the effort to sell Novo collapsed, the government restated its 2014 deficit which, after accounting for the bailout, ballooned to 7.2% of GDP from 4.5%. Portugal will tell you that this is only “temporary,” but let’s face it, if they haven’t managed to sell it by now, then one has to believe the prospects are grim – at least in terms of fetching anything that looks like a decent price. Well don’t look now, but Portugal’s seventh-largest bank, Banco Internacional do Funchal, now needs a bailout too. Banif (as it’s known) will be split into a “good” and “bad” bank, and its “healthy” assets will be sold to Banco Santander for €150 million. The government will inject up to €2.2 billion the European Commission said on Monday, to cover “future contingencies.”

Hilariously, the bailout was necessary because the bank was unable to repay a previous government cash injection. “The government injected €1.1 billion of fresh capital into the lender in January 2013 to allow it to meet minimum capital thresholds imposed by the banking regulator,” WSJ writes. For its trouble, Lisbon got a 60% stake in the bank and several hundred million worth of CoCos which the bank missed a payment on last year. “That,” WSJ goes on to note, “triggered close scrutiny by the European Commission, which opened an investigation into the legality of the state aid.” “The commission had said that Banif’s restructuring plan might not be enough to allow the bank to repay the state,” Bloomberg adds. “The Bank of Portugal said in the statement on Sunday that a ‘probable’ decision from the commission declaring the state aid illegal would create a shortage of capital at the bank.”

Read more …

“We now enter the “discovery” phase of financial collapse, where things labeled “capital” and “credit” turn out to be mere holograms.”

Christmas Present (Jim Kunstler)

Theory du jour: the new Star Wars movie is sucking in whatever meager disposable lucre remains among the economically-flayed mid-to-lower orders of America. In fact, I propose a new index showing an inverse relationship between Star Wars box office receipts and soundness of the financial commonweal. In other words, Star Wars is all that remains of the US economy outside of the obscure workings of Wall Street — and that heretofore magical realm is not looking too rosy either in this season of the Great Rate Hike after puking up 623 points of the DJIA last Thursday and Friday. Here I confess: for thirty years I have hated those stupid space movies, as much for their badly-written scripts (all mumbo-jumbo exposition of nonsensical story-lines between explosions) as for the degenerate techno-narcissism they promote in a society literally dying from the diminishing returns and unintended consequences of technology.

It adds up to an ominous Yuletide. Turns out that the vehicle the Federal Reserve’s Open Market Committee was driving in its game of “chicken” with oncoming reality was a hearse. The occupants are ghosts, but don’t know it. A lot of commentators around the web think that the Fed “pulled the trigger” on interest rates to save its credibility. Uh, wrong. They had already lost their credibility. What remains is for these ghosts to helplessly watch over the awesome workout, which has obviously been underway for quite a while in the crash of commodity prices (and whole national economies — e.g. Brazil, Canada, Australia), the janky regions of the bond markets, the related death of the shale oil industry, and the imploding hedge fund scene. As it were, all credit these days looks shopworn and threadbare, as if the capital markets had by stealth turned into a swap meet of previously-owned optimism.

Who believes in anything these days besides the allure of fraud? Capital is supposedly plentiful these days — look how much has rushed into the dollar from the nervous former go-go nations with their wobbling ziggurats of bad loans and surfeit of production capacity — but what actually constitutes that capital? Answer: the dwindling faith anyone will pay you back next Tuesday for a hamburger today. We now enter the “discovery” phase of financial collapse, where things labeled “capital” and “credit” turn out to be mere holograms. Fed Chair Janet Yellen herself had a sort of hologramatic look last Wednesday when she stepped onto her Delphic platform to reveal the long-heralded interest rate news. Perhaps Mrs. Yellen is a figment conjured by George Lucas’s Industrial Light & Magic shop (now owned by Disney). What could be more fitting in a smoke-and-mirrors culture?

Read more …

Recognizable patterns.

Et Tu, Brute? – How Empires Die (Thomas)

The state-owned Bank of China has been ordered by an American court to hand over customer information to the US. The bank has refused to comply, as to do so would violate China’s privacy law. The US court has subsequently ordered the Bank of China to pay a fine of $50,000 per day. Any guess as to how this is likely to turn out? China is a sovereign nation, halfway around the globe from the US, yet the US seems to feel that it’s somehow entitled to set the rules for China (as well as the other nations in the world). When China sees fit to develop islands in the South China Sea that it has laid claim to for centuries, it begins to hear threatening noises from the US military. A candidate for US president declares that he would buzz the islands with Air Force One, the Presidential jet, saying, “They’ll know we mean business.”

All over the world, those who live outside the US are increasingly observing that the US has become so drunk with power that they’re threatening both friend and foe with fines, trade restrictions, monetary sanctions, warfare, and invasions. And in so-observing, those of us who have studied the history of empires note that history is once again repeating itself. Time and time again, great empires build themselves up through industriousness and sound economic management only to subsequently decline into debt, complacency, and an entitlement mind-set. Over the millennia, empires as disparate as Persia, Rome, Spain, and Great Britain rose to dominate the world. Of course, we know how those empires turned out and, by extension, we might hazard an educated guess as to how the present American Empire will end.

In the final throes of empire-decline, we invariably observe the more sociopathic trends of a failing power, such as we’re seeing today from the US. First and foremost, any empire declines as a result of economic mismanagement. Decline from within (pandering to the populace with “bread and circuses”) and without (endless conquest and/or maintenance of dominance over far-flung geography) drain even the wealthiest government. Even eighteenth-century Spain, with all its billions in stolen New World gold, could not pay its ever-increasing bills and warfare-driven debt. Typically, the empire of the day enjoys the world’s greatest fighting force/armada/weapons build-up yet, when the money runs out, the war machine simply stops. Soldiers think more about their empty bellies than how much ammunition they have left.

Generals continue to issue orders, but they cease to be followed after the supply lines begin to dry up. And the leaders of a collapsing empire invariably make a fatal mistake: they assume that all the goodwill the empire gained when it was on its rise is permanent – that it will continue, even if the empire behaves like the world’s foremost bully. This is never the outcome. Invariably, as the decline nears its end, allies, without ever saying so, begin to withdraw their support. We see this today, as European leaders (America’s most essential allies) realise that the empire is becoming an arrogant liability and they begin cutting deals with the other side, as European leaders are now doing with Russia and others.

Read more …
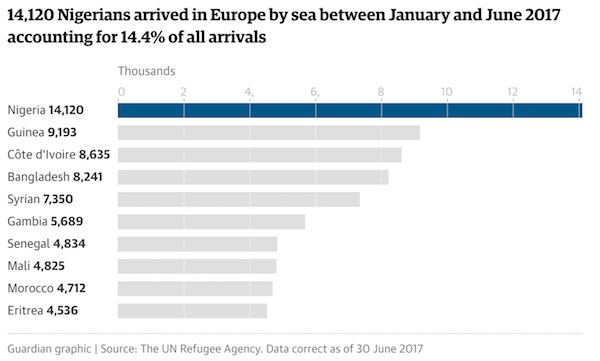
“The only way to avoid future crashes is for the Fed to stop creating inflation and bubbles.”

Do We Need The Fed? (Ron Paul)

Stocks rose Wednesday following the Fed’s announcement of the first interest rate increase since 2006. However, stocks fell just two days later. One reason the positive reaction to the Fed’s announcement did not last long is that the Fed seems to lack confidence in the economy and is unsure what policies it should adopt in the future. At her Wednesday press conference, Fed Chair Janet Yellen acknowledged continuing “cyclical weakness” in the job market. She also suggested that future rate increases are likely to be as small, or even smaller, then Wednesday’s. However, she also expressed concerns over increasing inflation, which suggests the Fed may be open to bigger rate increases. Many investors and those who rely on interest from savings for a substantial part of their income cheered the increase.

However, others expressed concern that even this small rate increase will weaken the already fragile job market. These critics echo the claims of many economists and economic historians who blame past economic crises, including the Great Depression, on ill-timed money tightening by the Fed. While the Federal Reserve is responsible for our boom-bust economy, recessions and depressions are not caused by tight monetary policy. Instead, the real cause of economic crisis is the loose money policies that precede the Fed’s tightening. When the Fed floods the market with artificially created money, it lowers the interest rates, which are the price of money. As the price of money, interest rates send signals to businesses and investors regarding the wisdom of making certain types of investments.

When the rates are artificially lowered by the Fed instead of naturally lowered by the market, businesses and investors receive distorted signals. The result is over-investment in certain sectors of the economy, such as housing. This creates the temporary illusion of prosperity. However, since the boom is rooted in the Fed’s manipulation of the interest rates, eventually the bubble will burst and the economy will slide into recession. While the Federal Reserve may tighten the money supply before an economic downturn, the tightening is simply a futile attempt to control the inflation resulting from the Fed’s earlier increases in the money supply. After the bubble inevitably bursts, the Federal Reserve will inevitability try to revive the economy via new money creation, which starts the whole boom-bust cycle all over again. The only way to avoid future crashes is for the Fed to stop creating inflation and bubbles.

Read more …
The more they can infringe on privacy, the more they will.

Apple Says UK Surveillance Law Would Endanger All Customers (BBG)

Apple outlined its opposition to a proposed U.K. surveillance law, saying threats to national security don’t justify weakening privacy and putting the data of hundreds of millions of users at risk. The world’s most valuable company is leading a Silicon Valley challenge to the proposed U.K. law, called the Investigatory Powers bill, which attempts to strengthen the capabilities of law-enforcement agencies to investigate potential crimes or terrorist attacks. The bill would, among other things, give the government the ability to see the Internet browsing history of U.K. citizens. Apple said the U.K. government already has access to an unprecedented amount of data.

The Cupertino, California-based company is particularly concerned the bill would weaken digital privacy tools such as encryption, creating vulnerabilities that will be exploited by sophisticated hackers and government spy agencies. In response to the U.K. rules, other governments would probably adopt their own new laws, “paralyzing multinational corporations under the weight of what could be dozens or hundreds of contradictory country-specific laws,” Apple said. “The creation of backdoors and intercept capabilities would weaken the protections built into Apple products and endanger all our customers,” Apple said in an eight-page submission to the U.K. committee considering the bill. “A key left under the doormat would not just be there for the good guys. The bad guys would find it too.”

Read more …
And that will not happen.

Half of World’s Coal Must Go Unmined to Meet Paris Climate Target (BBG)

Coal, the fuel that powered the industrial revolution, is in hiding. While the world still has 890 billion tons of reserves, enough to last more than 65 years, about half must stay underground if nations are to meet environmental limits agreed to earlier this month in Paris, Bank of America Corp. said in a report. Burning less coal is the easiest way to lower emissions blamed for climate change, the bank said. The pact reached by 195 nations doesn’t target specific fuels, yet coal remains the world’s largest source of planet-warming carbon dioxide. A global oversupply of the power plant fuel has pushed producers into bankruptcy and sent prices to at least seven-year lows. The Paris agreement only further diminishes prospects for a recovery.

“The latest carbon initiatives are the nail in the coffin for global coal,” Sabine Schels, Peter Helles and Franciso Blanch, analysts at Bank of America said in the Dec. 18 report. If emissions limits take hold, “50% of the world’s current coal reserves may never be dug out.” Coal demand stopped growing in 2014 for the first time since the 1990s as China’s economy cooled, the Paris-based International Energy Agency said Dec. 18. Coal for delivery to Amsterdam, Rotterdam, and Antwerp, an Atlantic benchmark, is trading near an eight-year low. Newcastle coal, a barometer for the Asia-Pacific market, is at the cheapest in records going back to 2008, data compiled by Bloomberg show.

Read more …
Last month, the warning came from China. Now it’s England and Wales.

It’s ‘Almost Too Late’ To Stop A Global Superbug Crisis (PA)

It is “almost too late” to stop a global superbug crisis caused by the misuse of antibiotics, a leading expert has warned. Scientists have a “50-50” chance of salvaging existing antibiotics from bacteria which has become resistant to its effects, according to Dr David Brown. The director at Antibiotic Research UK, whose discoveries helped make more than £20bn ($30bn) in pharmaceutical sales, said efforts to find new antibiotics are “totally failing” despite significant investment and research. It comes after a gene was discovered which makes infectious bacteria resistant to the last line of antibiotic defence, colistin (polymyxins). The resistance to the colistin antibiotic is considered to be a “major step” towards completely untreatable infections and has been found in pigs and humans in England and Wales.

Public Health England said the risk posed to humans by the mcr-1 gene was “low” but was being monitored closely. Performing surgery, treating infections and even travelling abroad safely all rely to some extent on access to effective antibiotics. It is feared the crisis could further penetrate Europe as displaced migrants enter from a war-torn Middle East, where countries such as Syria have increasing levels of antibiotic resistance. Dr Brown told said: “It is almost too late. We needed to start research 10 years ago and we still have no global monitoring system in place. “The issue is people have tried to find new antibiotics but it is totally failing – there has been no new chemical class of drug to treat gram-negative infections for more than 40 years.

Read more …