Jan 272018
 
 January 27, 2018  Posted by at 10:58 am Finance Tagged with: , , , , , , , , , , ,  10 Responses »


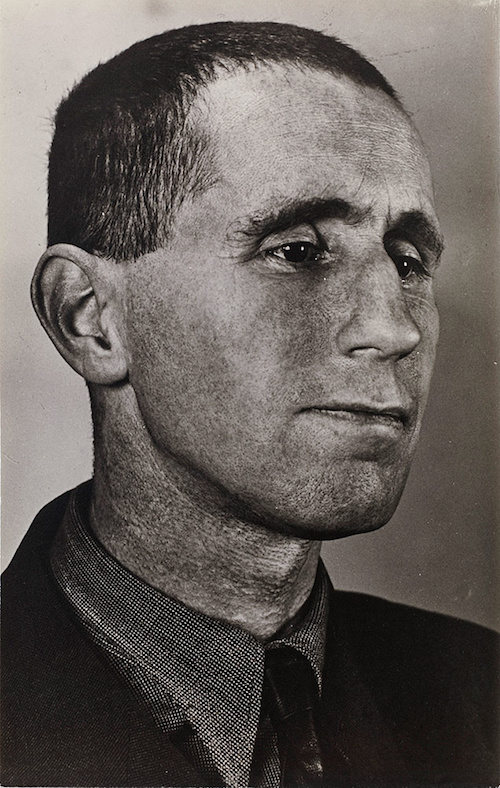
Grete Stern Bertolt Brecht 1934

 

• Bankers, Policy Makers at Davos Revel in ‘Sweet Spot’ Economy (BBG)
• IMF Chief Warns Trump’s Tax Cuts Could Destabilise Global Economy (G.)
• China Set To Lose ‘Emerging Market’ Status As Growth Declines (F.)
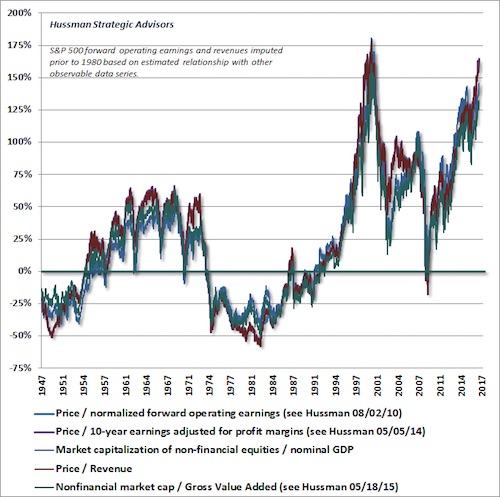
• This was 1987. Start Rebalancing – David Rosenberg (ZH)
• What Could Possibly Go Wrong? (Lance Roberts)
• Equity Allocations At Record Highs As Investor Cash Hits All Time Low (ZH)
• Japanese Cryptocurrency Exchange Loses $535 Million To Hackers (CNBC)
• How Bitcoin Regulation Will Happen, And What It Will Mean (Ind.)
• Bombardier Gets Surprise Win After U.S. Rebuffs Boeing Trade Case (BBG)
• Canada Illegally Subsidized Bombardier: Embraer (R.)
• More Than Half Of New-Build Luxury London Flats Fail To Sell (G.)
• Building More Homes Will Not Solve Britain’s Housing Crisis (Pettifor)
• Brexit Saddles EU With A Huge Budget Problem (CNBC)
• Deal With France ‘Could Bring Hundreds More Child Refugees To UK’ (G.)


Not much longer.

• Bankers, Policy Makers at Davos Revel in ‘Sweet Spot’ Economy (BBG)

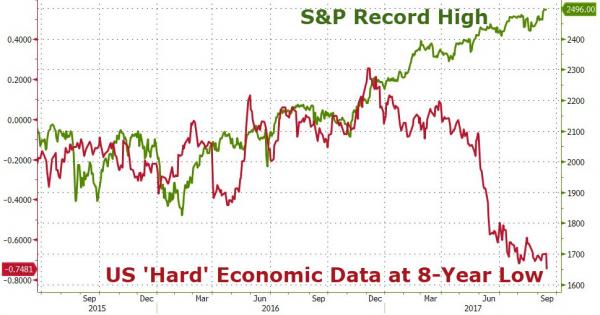
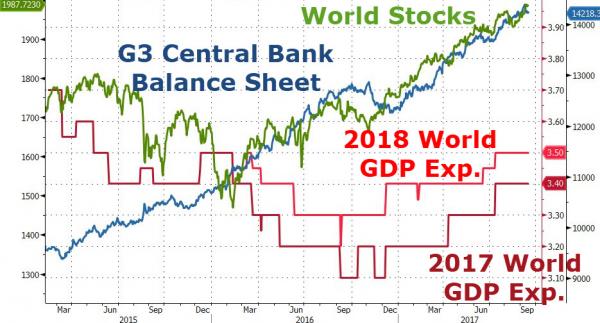
The global elites have rediscovered their animal spirits. As the World Economic Forum drew to a close in the Swiss ski resort, the overarching mood of the executives, policy makers and investors was that their economies are in fine shape and that stock markets have every reason to extend their run. “Let’s celebrate what could go right for the moment because we are in a sweet spot,” IMF Managing Director Christine Lagarde said on the closing panel discussion. The Standard & Poor’s 500 Index has gained about a quarter since the start of 2017 and the IMF is forecasting the strongest worldwide economic growth this year since a brief post-recession bounce in 2011. Some 57% of executives polled by PricewaterhouseCoopers saw the economy improving in 2018, about double the number of a year ago.

The rise of cryptocurrencies was evident in the Swiss town both in conference sessions and on the promenade where companies rent shopfronts to promote their wares. “The greatest worry I’ve heard over the past days in Davos is that there is not enough worry,” Mary Callahan Erdoes, JPMorgan asset-management unit CEO, said on the panel. “It’s O.K. to not be worried, to celebrate how we got here.” Erdoes thanked the policy makers on the stage for working “tirelessly” and “giving all of these government jobs such fabulous prestige and something that I know all of us now perhaps aspire to do.” “Wow,” said Bank of England Governor Mark Carney. “This is fantastic.” Such sentiment led delegates to declare that it was the most upbeat Davos gathering since before the financial crisis. Yet the giddiness also gave some investors pause as they warned against turning too exuberant.

Read more …

Lagarde gets what she wants and then turns against it. Cover all your bases.

• IMF Chief Warns Trump’s Tax Cuts Could Destabilise Global Economy (G.)

Donald Trump’s huge tax cuts are a threat to the stability of the global economy, the managing director of the IMF has warned. Christine Lagarde singled out Trump’s tax reforms as one of three risks that could destabilise the current economic recovery, especially given the boom in stock markets in the past year. “While the US tax reforms certainly will have positive effects in the short term, for the US and other countries around, it might also lead to serious risks,” Lagarde told the World Economic Forum in Davos. “That has an impact on financial vulnerability, particularly given the high asset prices that we see around the world, and the easy financing that it still available,” she added. She was speaking shortly after the US president told Davos that his tax reforms had created “a big, beautiful waterfall” of pay rises for US workers, as American companies passed the tax cut on.

However, the IMF is concerned that cutting taxes will lead to a bigger US budget deficit, and that extra borrowing by the US Treasury will force up long-term American interest rates. As a result, it fears growth could be choked off in the longer term, making the stock market vulnerable to a sudden downward lurch. Lagarde cautioned against people becoming too complacent about the pick-up in global growth reported by the IMF at the start of the WEF’s annual meeting. The IMF raised its forecasts for global expansion to 3.9% this year and in 2019, reporting that all major economies – the US, EU and Japan – are doing better. “I don’t think that we’ve completed the job,” said Lagarde, who fears that the growing economic inequality in many countries is creating “fractures”. “Having growth is good, improving productive is good, but [policymakers should] make sure that the results of that growth are properly allocated,” said the IMF chief, adding that inequality is growing in many advanced economies, and very high in emerging markets.

Read more …

An emerging market that’s stopped emerging.

• China Set To Lose ‘Emerging Market’ Status As Growth Declines (F.)

China has been considered an emerging market for over 25 years due to its rapid reform process. Generally speaking, emerging markets are defined as developing countries moving toward an open market economy. Unfortunately, if one takes a close look at growth levels and reform factors, China has shed some of the key characteristics of an emerging market, due to a sharp slowdown in the reform process, an increasingly state centered economy, and lower levels of true growth. China is an upper middle income country that enjoyed gangbusters growth through the 1990s and 2000s, but that is now suffering from a major economic slowdown that has no end in sight. One major reason for slowing growth is that market forces have been quashed by a a buildup in the state sector and mounting economic and financial risks that would result in economic collapse if the reform process is restarted.

Under President Xi Jinping, China’s economic policy has shifted toward enhancing the organization and financial sources of state owned enterprises, and away from liberalizing the currency and financial sector. Strides that were made toward internationalizing the RMB and bringing about a more market-based financial system have been reversed. A simultaneous over-reliance on easy credit has created plenty of risks in the financial sector that now prevent officials from even considering making the financial sector more market-based. Slow reform of the service sector and strong state presence in service subsectors like health and education have contributed to declining growth.

Read more …

When fear is gone, all that’s left is greed. No balance.

• This was 1987. Start Rebalancing – David Rosenberg (ZH)

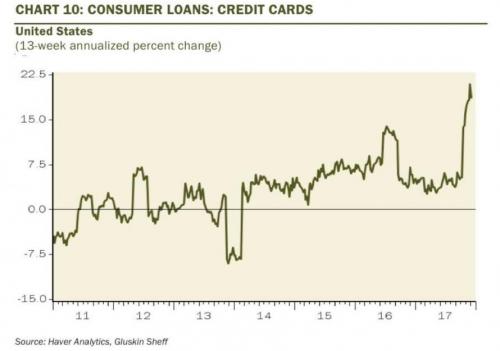
When discussing today’s unexpectedly weak Q4 GDP print, which came in at 2.6%, far below consensus and whisper estimates in the 3%+ range, and certainly both the Atlanta and NY Fed estimates, we pointed out the silver lining: personal spending and final sales, which surged 4.6% Q/Q (vs 2.2% in Q3), although even this number had a major caveat: “as we discussed previously, much of it was the result of a surge in credit card-funded spending while the personal savings rate dropped to levels last seen during the financial crisis.” Indeed, recall the stunning Gluskin Sheff chart we presented a month ago, which showed that 13-week annualized credit card balances in the U.S. had gone “completely vertical” in the last few months of 2017 which we said “should make for some great Christmas.”
Meanwhile, even more troubling was the ongoing collapse in the US personal savings rate, which last month tumbled to the lowest level since the financial crisis as US consumers drained what little was left of their savings to splurge on holiday purchases.
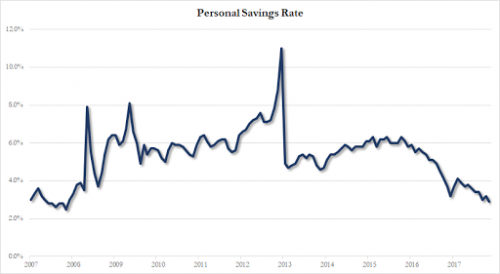
And while we highlighted and qualified two trends as key contributors to the spending surge in Q4 personal spending, Gluskin Sheff’s David Rosenberg – who is once again firmly in the bearish camp – did one better and quantified the impact. Not one to mince words, the former Merrill chief economist described what is going on as “The Twilight Zone Economy” for the following reason: “how many times in the past have we seen a 2.6% savings rate coincide with a 4.1% jobless rate? How about never…huge ETF flows driving equities higher, but these metrics are screaming ‘late cycle’.” He then proceeded to give “some haunting math” from the GDP number: “The savings rate fell from 3.3% to 2.6%. If it had stayed the same, real PCE would have been 0.8% (annualized) instead of 3.8% and GDP would have been 0.6% instead of 2.6%.”

[..] a more troubling development is that the conditions observed ahead of the Black Monday crash are becoming increasingly apparent. Here is Rosenberg’s stark assessment of where we stand: “Rising bond yields. Full employment. Fed tightening. Trade frictions. Weak dollar. Rising twin deficits, spurred by tax reform. Sound familiar? It should. This was 1987. Start rebalancing.”

Read more …

More 1987.

• What Could Possibly Go Wrong? (Lance Roberts)

What goes up, eventually comes down. That is just reality. The bull market that began in 2009, has now entered the final stage of “capitulation” as investors throw caution to the wind and charge headlong into the markets with reckless regard for the consequences.
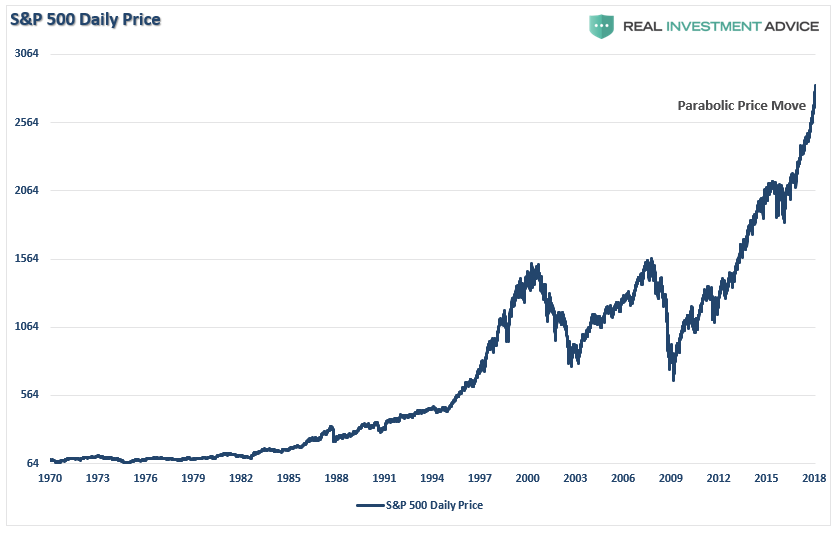
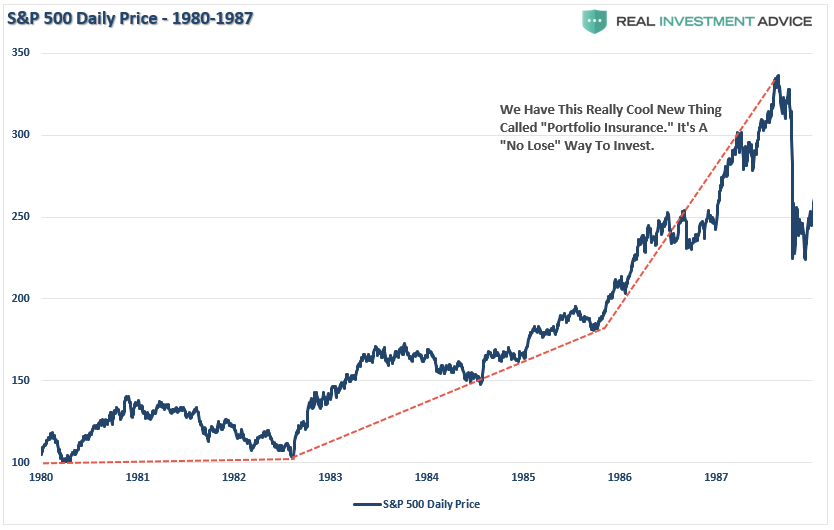
Of course, it isn’t surprising given the massive amounts of liquidity continually injected into the financial markets and global Central Banks have now figured out that continually rising financial markets solve much of the world’s ills. Simply, with enough liquidity, you can cover up bad (credit risks) by guaranteeing holders they will never default. It’s genius. It’s a “no lose” investment scheme. Unfortunately, we have seen this repeatedly in the past. In the 1980’s it was “Portfolio Insurance” – a “no lose” investment program that eventually erupted into the crash of 1987. But not before the market went into a parabolic advance first.
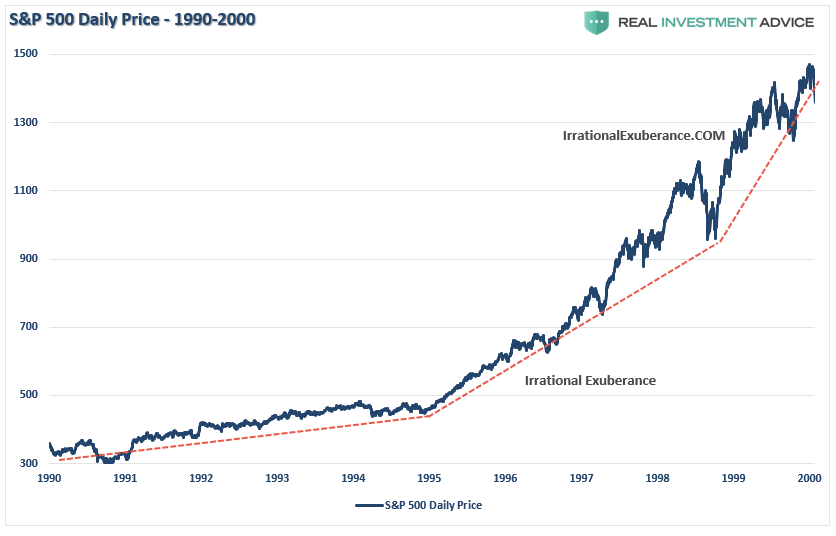
In the 1990’s – it was the dot.com phenomenon which was “obviously” a “no lose” proposition. Even after Alan Greenspan spoke of “irrational exuberance,” two years later the market went parabolic once again.
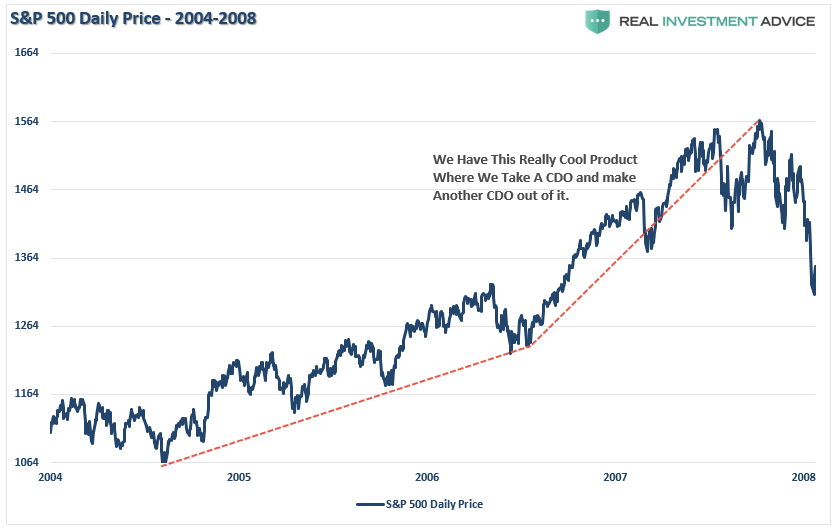
Then in 2006-2007, banks invented the CDO-squared, a collateralized derivative obligation based on other collateralized derivative obligations. It was a genius way to invest with “no risk” because the real estate market had never crashed in history.
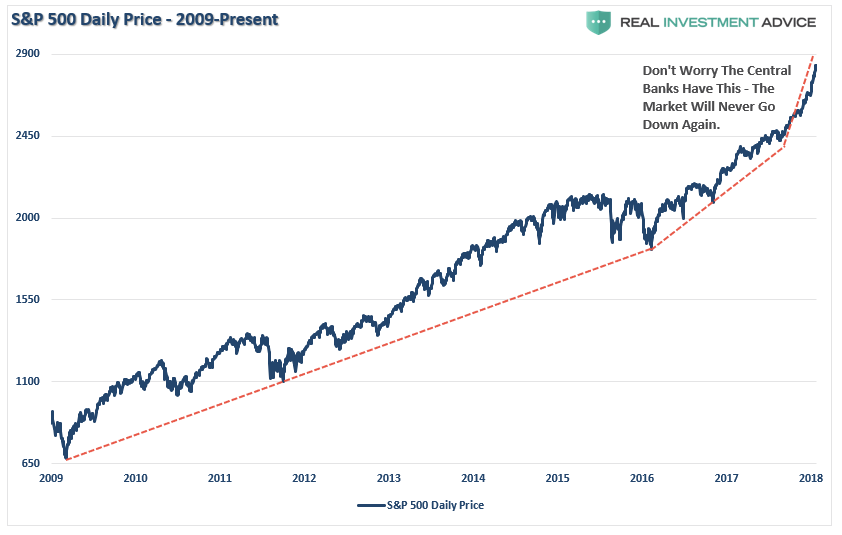
Today, it is once again an absolute “certainty” that markets will rise from here as global Central Banks have it all under control. What possibly could go wrong?
Read more …

Leverage squared.

• Equity Allocations At Record Highs As Investor Cash Hits All Time Low (ZH)

While Bank of America may or may not be right in its forecast that as a result of the market meltup, buying panic and sheer euphoria to get into stocks, which just pushed the bank’s proprietary “Bull and Bear” indicator to a level which on 11 out of 11 prior occasions always presaged a ~12% selloff…
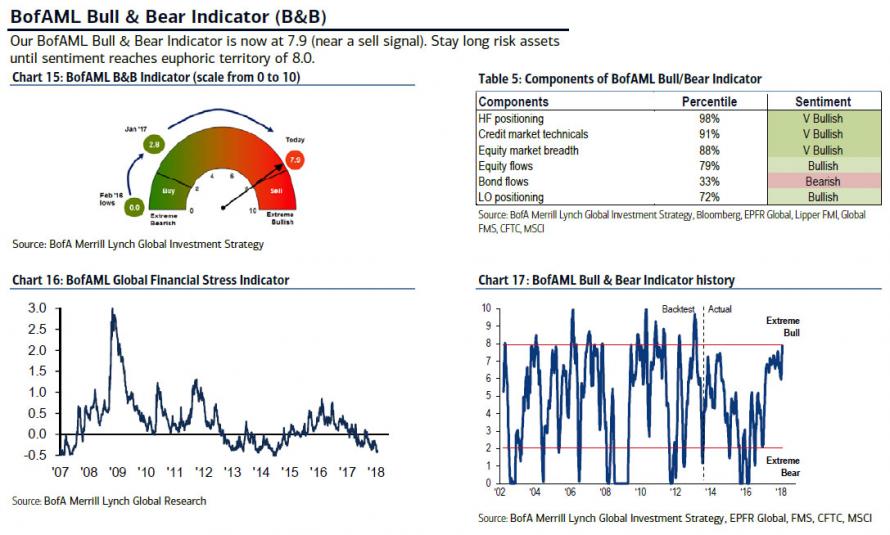
… a market correction or worse is imminent, one thing that is indisputable is the funding status of the Private Clients served by BofA’s Global Wealth and Investment Management (GWIM) team. What it shows is that investor cash allocation has just dropped to a record low of just 10%…
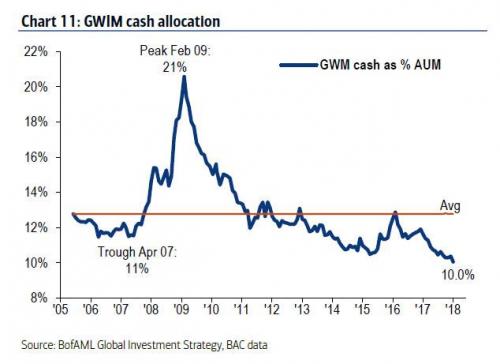
… while investor equity exposure is rising at fastest pace in 10 years.
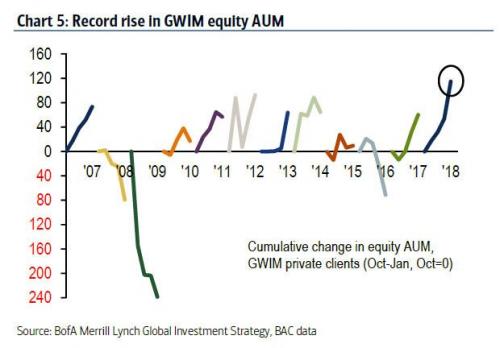
… and total equity allocations are back to record highs.
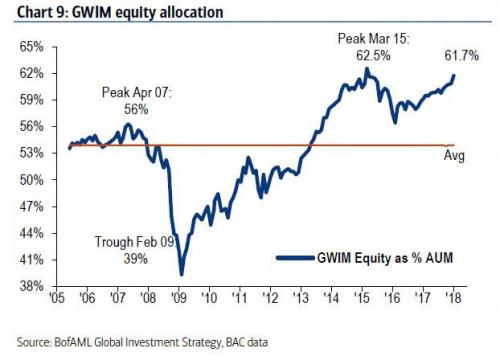
In other words: ‘bear capitulation’ as everyone is now long stocks in what BofA called a “non-stop euphoric cabaret.” When will this stop, or reverse? According to BofA, keep an eye on the dollar, which as long as it keeps sliding is supporting of risk assets, however the risk is once it bounces, to wit, the “US dollar key catalyst; note US-Europe FX spat sparked ’87 crash” and “higher US$ “pain trade” = risk-off coming weeks”

Read more …

Even if cryptos don’t have a security issue, they certainly appear to have one.

• Japanese Cryptocurrency Exchange Loses $535 Million To Hackers (CNBC)

Hackers stole several hundred million dollars’ worth of a lesser-known cryptocurrency from a major Japanese exchange Friday. Coincheck said that around 523 million of the exchange’s NEM coins were sent to another account around 3 a.m. local time (1 p.m. ET Thursday), according to a Google translate of a Japanese transcript of the Friday press conference from Logmi. The exchange has about 6% of yen-bitcoin trading, ranking fourth by market share on CryptoCompare. The stolen NEM coins were worth about 58 billion yen at the time of detection, or roughly $534.8 million, according to the exchange. Coincheck subsequently restricted withdrawals of all currencies, including yen, and trading of cryptocurrencies other than bitcoin. Bloomberg first reported the hack. A CNBC email sent to Coincheck’s listed address bounced back.

Cryptocurrency NEM, which intends to help businesses handle data digitally, briefly fell more than 20% Friday before recovering to trade about 10% lower near 85 cents, according to CoinMarketCap. Most other major digital currencies, including bitcoin, traded little changed on the day. Coincheck management said in the press conference that it held the NEM coins in a “hot” wallet, referring to a method of storage that is linked to the internet. In contrast, leading U.S. exchange Coinbase says on its website that 98% of its digital currency holdings are offline, or in “cold” storage. The Japanese exchange said it did not appear that hackers had stolen other digital currencies.

Read more …

There will never be a global consensus. Just a lot of poorly understood laws.

• How Bitcoin Regulation Will Happen, And What It Will Mean (Ind.)

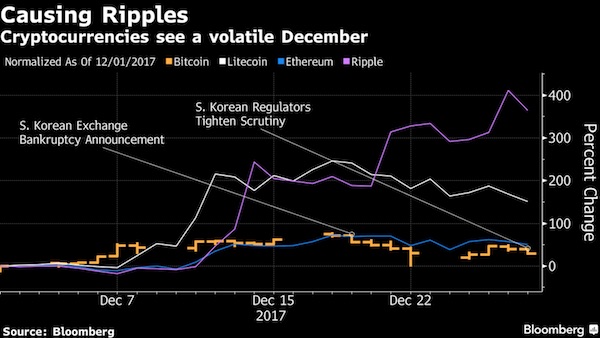
Bitcoin has been surging and falling in recent weeks. And it seems mostly to come down to one thing: regulation. The lack of regulation is, for now, a large part of bitcoin and other cryptocurrencies’ intrigue: they seem to allow people to avoid the traditional restrictions in place in money and other assets. But they’re also part of their bad reputation, with the same anonymity and decentralisation allowing them to be used for crime. Many governments have suggested they could introduce such rules. But it’s still not clear what they’d look like, or how they’d arrive; here’s an attempt to predict what might be to come in that most unpredictable of markets. In recent weeks, bitcoin has plunged after the threat of regulation in South Korea.

But it was part of a much broader trend – countries around the world have already introduced new rules, and those that haven’t are talking about it. The price has mostly levelled out in recent weeks, after regulation brought volatility and a slowly sliding price. But there might be more disruption coming, as countries look towards regulation, worried about the activity and behaviour that bitcoin could be enabling. That was obvious as world leaders arrived in Davos and were asked their opinion. The event could be a preview of far more wide-ranging controls that could be introduced in March, when the G20 governments’ financial and economic leaders meet in Argentina – a number of the countries attending have specifically said they will focus on fixing regulation of cryptocurrencies at that meeting.

They include France and Germany, which are said to be working together on bitcoin regulation. Many other countries have called for the international community to work together to bring regulation to bitcoin. Davos has been a platform for various world leaders to give their opinion on bitcoin. And they all seem to agree on one thing. “My number-one focus on cryptocurrencies, whether that be digital currencies or bitcoin or other things, is that we want to make sure that they’re not used for illicit activities,” said Steven Mnuchin, Donald Trump’s most senior financial policymaker, told the World Economic Forum in Davos, Switzerland. “We encourage fintech and we encourage innovation, but we want to make sure all of our financial markets are safe,” Mnuchin said. “We want to make sure that the rest of the world – and many of the (Group of) 20 countries are already starting on this – have the same regulations.”

Read more …

Airplane makers wars are set to intensify.

• Bombardier Gets Surprise Win After U.S. Rebuffs Boeing Trade Case (BBG)

Bombardier can start shipping C Series jets to Delta Air Lines after a surprise ruling by a U.S. trade panel that said the proposed imports won’t hurt American industry. U.S. companies and workers aren’t being harmed by sales of 100- to-150-seat aircraft from Canada, the International Trade Commission said Friday. The tribunal’s unanimous vote blocks a Commerce Department decision last month to impose duties of almost 300%. Friday’s vote deals a blow to Boeing, which said Bombardier sold the C Series in the U.S. at less than fair value while benefiting from government subsidies. The ruling also opens the door for Montreal-based Bombardier to woo new American customers while potentially easing U.S. trade tensions with Canada and the U.K., where the company builds wings for the aircraft. “I’m shocked,” said Chris Murray, an analyst in Toronto. “This clears the way for the jets being to delivered to Delta,” Murray said. “It also removes any concerns about potential future orders in the U.S.”

Read more …

Bombardier goes from one lawsuit to another. Should have stuck to making skidoos.

• Canada Illegally Subsidized Bombardier: Embraer (R.)

Brazilian planemaker Embraer said on Friday that the U.S. Department of Commerce has shown that the Canadian government “heavily and illegally subsidized” Bombardier and its C Series aircraft, allowing the company to survive and distorting the aviation industry. The statement came just after Bombardier won an unexpected trade victory against U.S. planemaker Boeing when a U.S. agency rejected imposing hefty duties on sales of Bombardier’s new CSeries jet to American carriers.

Read more …

Oh well, there’s plenty homeless people.

• More Than Half Of New-Build Luxury London Flats Fail To Sell (G.)

Developers have 420 towers in pipeline despite up to 15,000 high-end flats still on the market. More than half of the 1,900 ultra-luxury apartments built in London last year failed to sell, raising fears that the capital will be left with dozens of “posh ghost towers”. The swanky flats, complete with private gyms, swimming pools and cinema rooms, are lying empty as hundreds of thousands of would-be first-time buyers struggle to find an affordable home. The total number of unsold luxury new-build homes, which are rarely advertised at less than £1m, has now hit a record high of 3,000 units, as the rich overseas investors they were built for turn their backs on the UK due to Brexit uncertainty and the hike in stamp duty on second homes.

Builders started work last year on 1,900 apartments priced at more than £1,500 per sq ft, but only 900 have sold, according to property data experts Molior London. A typical high-end three-bedroom apartment consists of around 2,000 sq ft, which works out at a sale price of £3m. There are an extra 14,000 unsold apartments on the market for between £1,000-£1,500 per sq ft. The average price per sq ft across the UK is £211. Molior says it would take at least three years to sell the glut of ultra-luxury flats if sales continue at their current rate and if no further new-builds are started. However, ambitious property developers have a further 420 residential towers (each at least 20 storeys high) in the pipeline, says New London Architecture and GL Hearn. Henry Pryor, a property buying agent, says the London luxury new-build market is “already overstuffed but we’re just building more of them”.

Read more …

Building more is the worst of all options. See above. But it’s alos the only option that lets the illusion last a bit longer.

• Building More Homes Will Not Solve Britain’s Housing Crisis (Pettifor)

Everyone – from the government, to housing charities, to housebuilders – has bought into the conventional wisdom that the dysfunction that racks our housing market is a matter of demand and supply. We’re not building enough houses, so house prices have been sent rocketing, taking home-ownership out of reach for growing numbers of young people. But in reality, our housing problems are not a simple feature of supply and demand. Rather, our housing market has a bitcoin problem. What has bitcoin mania got in common with house prices, especially in the capital? For starters, both are speculative bubbles. Vast sums of money have been poured into finite supplies of bitcoins and London property. Both have consequently exploded in value, albeit over different time periods.

And so both have become financialised assets that deliver capital gains far in excess of people’s ability to earn income from work, or from investment in the real economy. And as with bitcoin, so with London property: speculators are convinced that prices will continue to rise for ever. It’s speculation in the property market that is fuelling stratospheric house price rises, not shortage of supply. When the “fuel” of private capital, mortgage credit and cash from the bank of mum and dad is supplemented by government subsidies and tax breaks, house prices rise. Moreover, wealthy global and non-resident buyers have funnelled more than £100bn into London property over recent years, making the problem even worse.

So, rather counterintuitively, building more houses is not the right prescription. House prices won’t fall until the tide of cash flowing into the market abates, for example by tightening mortgage credit, or shrinking the pool of buy-to-let investors. That may already be starting to happen as real incomes continue to fall, the Bank of England toughens up buy-to-let mortgages, and stamp duty rises are phased in for second properties. Despite this, the government pretends the real cause of unaffordable housing is a shortage of new builds. It uses this argument to provide cover for further taxpayer-funded subsidies and tax breaks that benefit its property-owning core voters, its close allies in the construction industry and property market, and its supporters in the City of London.

Read more …

Germany crony Holland wants to pay less toward Brexit because its economy is hit harder than others. It also wants the entire EU budget cut. Juncker wants to raise that budget and buy more Europe. This could blow up. Expect more heavy handedness from Brussels.

• Brexit Saddles EU With A Huge Budget Problem (CNBC)

Brexit is leaving the EU with a big problem on its hands and a “very tough” negotiation ahead, European Commission Vice-President Jyrki Katainen told CNBC on Friday. The U.K. has been one of the main contributors to the European budget, but once it has left the bloc there will be a gap in the EU budget that will have to be worked out somehow, Katainen said. “It is certainly a problem and we have to address it,” he said at the World Economic Forum (WEF) in Davos, Switzerland. “If I should bet something, we need to adjust the budget to a certain extent but also we need fresh money from member states. We also have to look at how money is spent, how we could get more out of less.”

But many EU members do not want to pay more to compensate for the U.K.’s decision to leave the union. Denmark, for example, made it clear last year that it would not step up its financial commitment because of Brexit. Katainen told CNBC that one solution could be using more financial instruments, including equity investments, to finance European projects rather than direct financial contributions. “This is what we are planning or exploring at the moment… it’s going to be a very though negotiation,” he said.

The current EU budget is planned out until 2020. The European Commission is due to come up with proposals on the future of the budget in May. During a speech in September, EC President Jean-Claude Juncker said: “An important element will be the budgetary plans the commission will present in May 2018. Here again, we have a choice — either we pursue the European Union’s ambitions in the strict framework of the existing budget, or we increase the European Union’s budgetary capacity so that it might better reach its ambitions. I am for the second option.”

Read more …

Yeah, the ones they previously promised to take but never did.

• Deal With France ‘Could Bring Hundreds More Child Refugees To UK’ (G.)

Charities working to bring unaccompanied refugee children to safety are optimistic that agreements signed by Theresa May and Emmanuel Macron could lead to hundreds more receiving permission to travel legally to the UK. Details emerging from last week’s summit show that officials agreed to extend an eligibility deadline so that children fleeing conflict and arriving in Europe before last Friday could be considered under the Dubs amendment, the scheme launched in 2016 under which the government agreed to offer a safe and legal route to refugee children travelling alone. Previously, refugee children had to have arrived in Europe before March 2016 to be considered for acceptance under the scheme. This deadline meant large numbers of vulnerable young people who had arrived in France, Germany and Italy more recently were not eligible.

Lord Dubs, the Labour peer who forced the government to commit to helping more young refugees in January 2016, welcomed the development. “We hope dozens more will be transferred, but it is crucial that they get a move on. In France they are sleeping under the trees in very bleak conditions.” Although the May-Macron agreement focused on France, concerns are growing for the large number of unaccompanied refugee children in Greece where there are currently 3,150 refugee children, travelling without families, and only 1,109 spaces in shelters, according to the charity Safe Passage, which has campaigned to bring more young refugees to the UK. The charity hopes that a further 250 could be brought to safety under the Dubs scheme. The government has committed to accommodating 480 refugee children under the scheme, but has so far only transferred about 220.

Campaigners hope the announcement could reduce the number of young refugees killed on roads outside Calais, after a spike in deaths in recent weeks among asylum seekers attempting to climb on to lorries in order to travel illegally to the UK. The UK government also agreed to speed up the time it spends considering applications from young refugees for transfer to the UK, committing to providing an answer in 10 days, and to transferring them within 15 days after that. George Gabriel, at Safe Passage, said: “For those who are awaiting family reunion, these changes will mean that there is a much lower incentive to make a dangerous journey to reunite with a loved one.”
Read more …

Dec 282017
 
 December 28, 2017  Posted by at 10:23 am Finance Tagged with: , , , , , , , , , ,  6 Responses »


Ansel Adams Church, Taos, Pueblo 1942


The Automatic Earth and its readers have been supporting refugees and homeless in Greece since June 2015. It has been and at times difficult and at all times expensive endeavor. Not at least because the problems do not just not get solved, they actually get worse. Because the people of Greece and the refugees that land on their shores increasingly find themselves pawns in political games.

Therefore, even if the generosity of our readership has been nothing short of miraculous, we must continue to humbly ask you for more support. Because our work is not done. Our latest essay on this is here: The Automatic Earth for Athens Fund – Christmas and 2018 . It contains links to all 14 previous articles on the situation.

Here’s how you can help:


For donations to Konstantinos and O Allos Anthropos, the Automatic Earth has a Paypal widget on our front page, top left hand corner. On our Sales and Donations page, there is an address to send money orders and checks if you don’t like Paypal. Our Bitcoin address is 1HYLLUR2JFs24X1zTS4XbNJidGo2XNHiTT. For other forms of payment, drop us a line at Contact • at • TheAutomaticEarth • com.

To tell donations for Kostantinos apart from those for the Automatic Earth (which badly needs them too!), any amounts that come in ending in either $0.99 or $0.37, will go to O Allos Anthropos.


Please give generously.


• S&P 500 Hits Most Overbought Level In 22 Years (MW)
• Peak Good Times? Stock Market Risk Spikes to New High (WS)
• Russia’s Finance Minister Confirms Upcoming Bitcoin Regulations (CCN)
• Bitcoin Tumbles Over Exchange-Closure Fears (BBG)
• Bitcoin’s Surging Price Drives Private Investor Demand For Derivatives (BBG)
• Trump Tax Reform Blew Up The Treasury Market (ZH)
• The Tax Plan Could Change How Wall Street Works (BBG)
• “We’ve Centralized All Of Our Data To A Guy Called Mark Zuckerberg” (HN)
• The Petro-yuan Bombshell (Escobar)
• John McDonnell Warns Over ‘Alarming Increase’ In UK Household Debt (G.)
• Another Fukushima? Tepco Plans To Restart World’s Biggest Nuclear Plant (G.)
• Children Increasingly Used As Weapons Of War – Unicef (G.)


All the lovely things that debt buys.

• S&P 500 Hits Most Overbought Level In 22 Years (MW)

Following a year in which the U.S. stock market hit a record number of records and seen basically nothing in the way of pullbacks or volatility, investors have gone all-in on stocks. Exchange-traded funds, perhaps the most popular way to get exposure to broad parts of the market, have seen record-breaking inflows over the year, with both domestic and foreign-based stock funds seeing heavy interest and no major category seeing outflows. Both retail and institutional investors have gotten in on the action and are positioning in a way that suggests both see further gains ahead. The S&P 500 has rallied about 20% over 2017, on track for its best year since 2013.

According to Torsten Sløk, Deutsche Bank’s chief international economist, “U.S. retail investors say that today is the best time ever to invest in the market,” based on data from the University of Michigan consumer sentiment report, which asks about the probability of an increase in stock prices over the coming year. Younger investors in particular are warming up to equities, according to E*Trade. The latest AAII investor sentiment survey indicates that 50.5% of polled investors are bullish on the market, meaning they expect prices will be higher in six months. That’s the highest level in nearly two years, and significantly above the 38.5% historical average. The number of bullish investors has gone up by 5.5 percentage points in the last week alone, while the percentage of bearish investors has dropped to 25.6%, down 2.5 percentage points over the last week.

Optimism has gotten so high that cash balances for Charles Schwab clients reached their lowest level on record in the third quarter, according to Morgan Stanley, which wrote that retail investors “can’t stay away.” The investment bank noted a similar trend in institutional investors, who it wrote were “loading the boat on risk,” with “long/short net and gross leverage as high as we have ever seen it.”

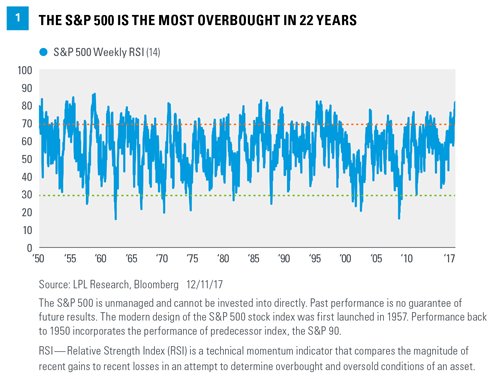
There have been fundamental reasons for this optimism, including a strong labor market and improving economic data. Furthermore, the recently passed tax bill will cut corporate taxes, which should boost corporate profits — which have already been enjoying their fastest year of growth since 2011. However, the incessant buying has pushed valuations to levels that are not only stretched, but stretched to a historic extent. As was recently noted by LPL Financial, the relative strength index, an indicator of technical momentum, is at its highest level since 1995, which indicates the S&P 500 is at its most overbought level in 22 years.

Read more …

Thank your central banker.

• Peak Good Times? Stock Market Risk Spikes to New High (WS)

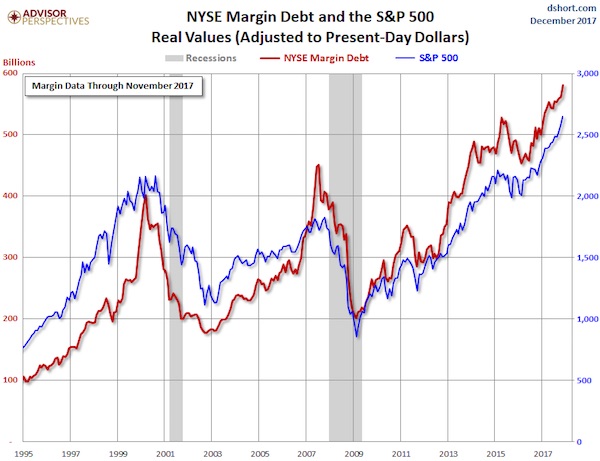
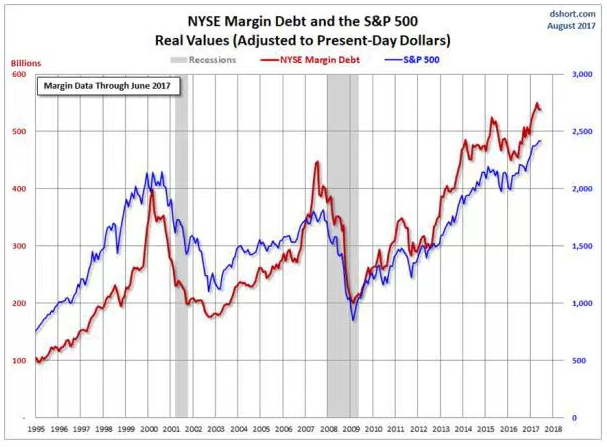
Margin debt is the embodiment of stock market risk. As reported by the New York Stock Exchange today, it jumped 3.5%, or $19.5 billion, in November from October, to a new record of $580.9 billion. After having jumped from one record to the next, it is now up 16% from a year ago. Even on an inflation-adjusted basis, the surge in margin debt has been breath-taking: The chart by Advisor Perspectives compares margin debt (red line) and the S&P 500 index (blue line), both adjusted for inflation (in today’s dollars). Note how margin debt spiked into March 2000, the month when the dotcom crash began, how it spiked into July 2007, three months before the Financial-Crisis crash began, and how it bottomed out in February 2009, a month before the great stock market rally began:

Margin debt, which forms part of overall stock market leverage, is the great accelerator for stocks, on the way up and on the way down. Rising margin debt – when investors borrow against their portfolios – creates liquidity out of nothing, and much of this new liquidity is used to buy more stocks. But falling margin debt returns this liquidity to where it came from. Leverage supplies liquidity. But it isn’t liquidity that moves from one asset to another. It is liquidity that is being created to be plowed into stocks, and that can evaporate just as quickly: When stocks are dumped to pay down margin debt, the money from those stock sales doesn’t go into other stocks or another asset class, doesn’t become cash “sitting on the sidelines,” as the industry likes to say, and isn’t used to buy gold or cryptocurrencies or whatever. It just evaporates without a trace.

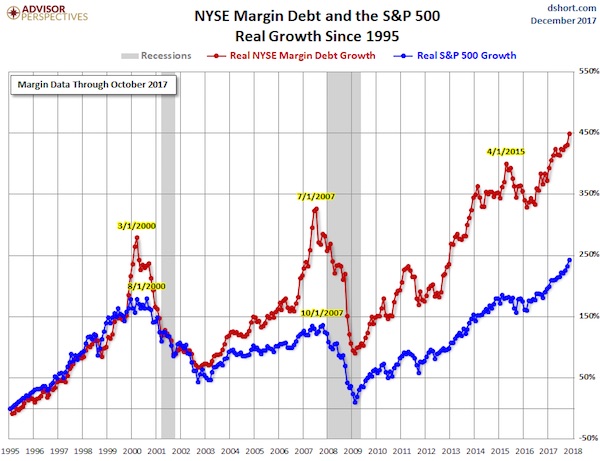
After stirring markets into an eight-year risk-taking frenzy, the Fed is now worried that markets have gone too far. Among the Fed governors fretting out loud over this was Dallas Fed President Robert Kaplan who recently warned about the “record-high levels” of margin debt, along with the US stock market capitalization, which, at 135% of GDP, is “the highest since 1999/2000.” “In the event of a sell-off, high levels of margin debt can encourage additional selling, which could, in turn, lead to a more rapid tightening of financial conditions,” he mused. The growth in margin debt has far outpaced the growth of the S&P 500 index in recent years. The chart below (by Advisor Perspectives) shows the percentage growth of margin debt and the S&P 500 index, both adjusted for inflation:

Read more …

Will Russia set the model for the rest of the world? Don’t be surprised if others follow.

• Russia’s Finance Minister Confirms Upcoming Bitcoin Regulations (CCN)

The Russian Ministry of Finance has prepared a sweeping regulatory law that will cover many facets of cryptocurrencies like bitcoin in Russia. In an interview with state-owned television broadcaster Rossiya 24 over Christmas, Russia’s finance minister Anton Siluanov confirmed the ministry’s draft law on a regulatory framework for cryptocurrencies. The regulation, as expected, will cover bitcoin mining rules, taxation laws for adopters and guidelines for exchanges selling cryptocurrencies. As reported by Russian news source TASS, Siluanov stated: The Ministry of Finance has prepared a draft law, currently under consideration, which will determine the procedure for issuing, taxing, buying and circulation of cryptocurrency. In conjunction, the Ministry of Finance is also reportedly preparing amendments to Russian legislation toward the broader regulation of new financial technologies and digital payments.

The developments are a remarkable contrast to legislation proposed by Russia’s Finance Ministry as recently as March 2016. At the time, the ministry proposed a 7-year prison sentence for bitcoin adopters and users. Earlier in September, Siluanov called for the Russian government to accept and understand “that cryptocurrencies are real.” “There is no sense in banning them,” Siluanov said at the time, “there is a need to regulate them.” The new laws, in its draft, is expected to be submitted to the State Duma (the lower house of the Russian Parliament) tomorrow before its anticipated adoption sometime in March 2018. The new laws were fast-tracked by authorities following Russian President Vladimir Putin’s mandate to develop regulations for cryptocurrencies, mining and initial coin offerings (ICOs). The amendments to existing Russian laws to recognize cryptocurrencies will also aid in the prepping for the launch of Russia’s own national cryptocurrency – the CryptoRuble.

Read more …

Korea may be the first to copy Moscow. This is not action, it’s reaction.

• Bitcoin Tumbles Over Exchange-Closure Fears (BBG)

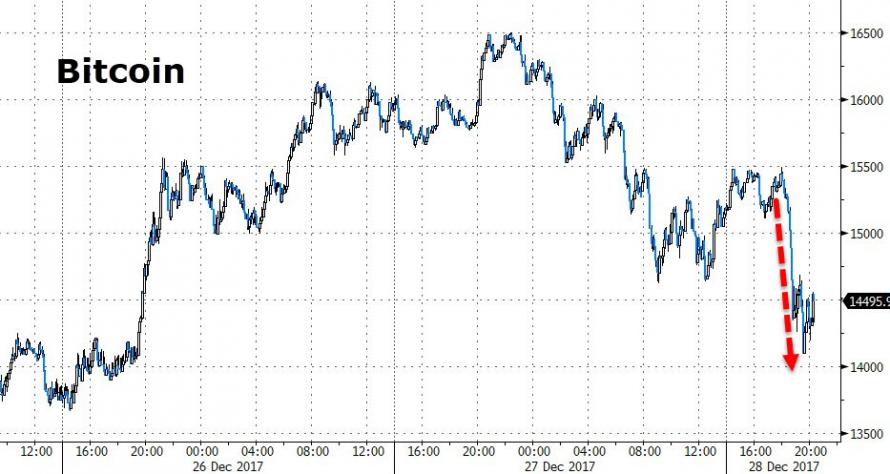
Bitcoin resumed its tumble on Thursday after South Korea said it was eyeing options including a potential shutdown of at least some cryptocurrency exchanges to stamp out a frenzy of speculation. South Korea has been ground zero for a global surge in interest in bitcoin and other cryptocurrencies as prices surged this year, prompting the nation’s prime minister to worry over the impact on Korean youth. While there’s no immediate indication Asia’s No. 4 economy will shutter exchanges that have accounted by some measures for more than fifth of global trading, the news poses a warning as regulators the world over express concerns about private digital currencies. Bitcoin fell as much as 9% to as low as $13,828 in Asia trading, erasing modest gains after the South Korean release, composite Bloomberg pricing shows.

It’s now down about 28% from its record high reached last week. South Korea will require real-name cryptocurrency transactions and impose a ban on the offering of virtual accounts by banks to crypto-exchanges, according to a statement from the Office for Government Policy Coordination. Policy makers will review measures including the closure of crypto-exchanges suggested by the Ministry of Justice and take proper measures swiftly and firmly while monitoring the trend of the speculation. Bitcoin was trading at about a 30% premium over prevailing international rates on Thursday in Seoul – a continuing sign of the country’s obsession, and the difficulty in arbitraging between markets. “Cryptocurrency speculation has been irrationally overheated in Korea,” the government said in the statement, which comes little more than a week after the bankruptcy filing of one South Korean exchange. “The government can’t leave the abnormal situation of speculation any longer.”

Read more …

The combination of crypto and derivatives sends shivers.

• Bitcoin’s Surging Price Drives Private Investor Demand For Derivatives (BBG)

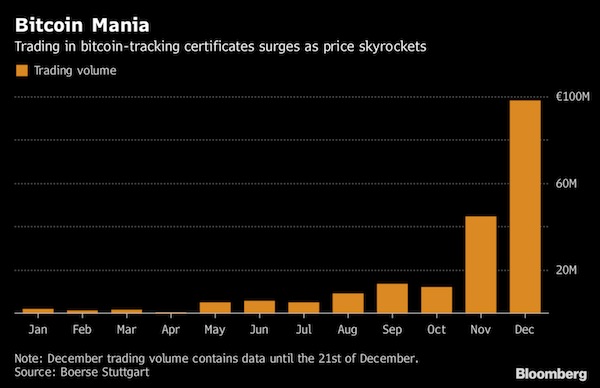
Bitcoin’s surging price has driven private-investor demand for derivatives tracking the virtual currency. Trading in so-called participation notes has skyrocketed this year on Boerse Stuttgart, Europe’s largest exchange for retail derivatives. The number of executed orders jumped 22-fold from 436 in January to almost 10,000 in December.

Read more …

Beware when stirring up a complex system.

• Trump Tax Reform Blew Up The Treasury Market (ZH)

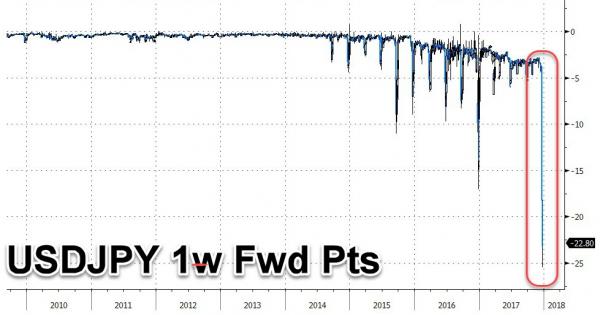
Over the past week we have shown on several occasions that there once again appears to be a sharp, sudden dollar-funding liquidity strain in global markets, manifesting itself in a dramatic widening in FX basis swaps, which – in this particular case – has flowed through in the forward discount for USDJPY spiking from around 0.04 yen to around 0.23 yen overnight. As Bloomberg speculated, this discount for buying yen at future dates widened sharply as non-U.S. banks, which typically buy dollars now with sell-back contracts at a future date, scrambled to procure greenbacks for the year-end. However, as Deutsche Bank’s Masao Muraki explains, this particular dollar funding shortage is more than just the traditional year-end window dressing or some secret bank funding panic.

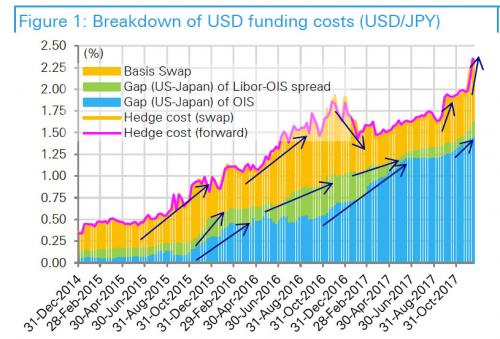
Instead, the DB strategist observes that the USD funding costs for Japanese insurers and banks to invest in US Treasuries – which have surged reaching a post-financial-crisis high of 2.35% on 15 Dec – are determined by three things, namely (1) the difference in US and Japanese risk-free rates (OIS), (2) the difference in US and Japanese interbank risk premiums (Libor-OIS), and (3) basis swaps, which illustrate the imbalance in currency-hedged US and Japanese investments. In this particular case, widening of (1) as a result of Fed rate hikes and tightening of dollar funding conditions inside the US (2) and outside the US (3) have occurred simultaneously. This is shown in the chart below.

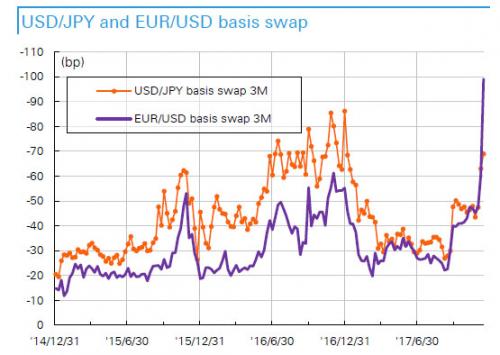
What is causing this? Unlike on previous occasions when dollar funding costs blew out due to concerns over the credit and viability of the Japanese and European banks, this time the Fed’s rate hikes could be spurring outflows from the US, European, and Japanese banks’ deposits inside the US. Absent indicators to the contrary, this appears to be the correct explanation since it’s not just Yen funding costs that are soaring. In fact, at present EUR/USD basis swaps are widening more than USD/JPY basis swaps. [..] According to Deutsche, it is possible that an increase in hedged US investments by Europeans could be indirectly affecting Japan, and that market participants could also be conscious of the risk that the repatriation tax system could spur a massive flow-back into the US, of funds held overseas by US companies In fact, one can draw one particularly troubling conclusion: the sharp basis swap moves appear to have been catalyzed by the recently passed Trump tax reform.

Read more …

More ‘unintended’ consequences?!

• The Tax Plan Could Change How Wall Street Works (BBG)

Leon Black recently posed a question whose answer will determine how profitable the new U.S. tax regime could make Wall Street firms like his Apollo Global Management. Publicly traded partnerships, including private equity firms Apollo, Blackstone and Carlyle Group, are taxed differently than corporations. So should they take advantage of the overhauled tax rules to pay less in taxes? Or should they use this chance to change to an Inc. from an LLC or LP, which would increase tax bills but allow them to attract investments from mutual funds that have previously been out of reach? “We’re still analyzing,’’ Black told the Goldman Sachs U.S. Financial Services Conference Dec. 6. “It’s an uncertain outcome.’’

Either way, it’s most likely a money-making outcome. The tax changes are a boon for firms such as Apollo, where Black is chief executive officer. The new lower corporate rate has made it possible for bigger publicly traded partnerships to consider the change. As it is, management fees, which typically account for 30 percent or more of their earnings, are already taxed at the corporate rate. That will drop. The legislation scarcely touched the 23.8 percent rate paid on incentive fees, also called carried interest, which incur no additional levy when paid out to shareholders. If the partnerships converted to corporations, the incentive fees would be hit with a second layer of tax when they’re paid out. That would push the combined tax rate on incentive income paid out as dividends to nearly 40 percent, according to Peter Furci, co-chair of Debevoise & Plimpton’s global tax practice.

Read more …

I’m sure this guy is smart, but he misses the point here by a mile. What has happened is the data have been centralized to the NSA and CIA and their peers. Zuckerberg is just a conduit.

• “We’ve Centralized All Of Our Data To A Guy Called Mark Zuckerberg” (HN)

At its inception, the internet was a beautifully idealistic and equal place. But the world sucks and we’ve continuously made it more and more centralized, taking power away from users and handing it over to big companies. And the worst thing is that we can’t fix it – we can only make it slightly less awful. That was pretty much the core of Pirate Bay’s co-founder, Peter Sunde‘s talk at tech festival Brain Bar Budapest. TNW sat down with the pessimistic activist and controversial figure to discuss how screwed we actually are when it comes to decentralizing the internet. In Sunde’s opinion, people focus too much on what might happen, instead of what is happening. He often gets questions about how a digitally bleak future could look like, but the truth is that we’re living it.

“Everything has gone wrong. That’s the thing, it’s not about what will happen in the future it’s about what’s going on right now. We’ve centralized all of our data to a guy called Mark Zuckerberg, who’s basically the biggest dictator in the world as he wasn’t elected by anyone. Trump is basically in control over this data that Zuckerberg has, so I think we’re already there. Everything that could go wrong has gone wrong and I don’t think there’s a way for us to stop it.” One of the most important things to realize is that the problem isn’t a technological one. “The internet was made to be decentralized,” says Sunde, “but we keep centralizing everything on top of the internet.”

To support this, Sunde points out that in the last 10 years, almost every up-and-coming tech company or website has been bought by the big five: Amazon, Google, Apple, Microsoft and Facebook. The ones that manage to escape the reach of the giants, often end up adding to the centralization. We don’t create things anymore, instead we just have virtual things. Uber, Alibaba and Airbnb, for example, do they have products? No. We went from this product-based model, to virtual product, to virtually no product what so ever. This is the centralization process going on. Although we should be aware that the current effects of centralization, we shouldn’t overlook that it’s only going to get worse. There are a lot of upcoming tech-based services that are at risk of becoming centralized, which could have a huge impact on our daily lives.

[..] Feeling a bit optimistic, I asked Sunde whether we could still fight for decentralization and bring the power back to the people. His answer was simple. “No. We lost this fight a long time ago. The only way we can do any difference is by limiting the powers of these companies – by governments stepping in – but unfortunately the EU or the US don’t seem to have any interest in doing this.”

Read more …

Right in theory, but…

• The Petro-yuan Bombshell (Escobar)

The website of the China Foreign Exchange Trade System (CFETS) recently announced the establishment of a yuan-ruble payment system, hinting that similar systems regarding other currencies participating in the New Silk Roads, a.k.a. Belt and Road Initiative (BRI) will also be in place in the near future. Crucially, this is not about reducing currency risk; after all Russia and China have increasingly traded bilaterally in their own currencies since the 2014 US-imposed sanctions on Russia. This is about the implementation of a huge, new alternative reserve currency zone, bypassing the US dollar. The decision follows the establishment by Beijing, in October 2015, of the China International Payments System (CIPS). CIPS has a cooperation agreement with the private, Belgium-based SWIFT international bank clearing system, through which virtually every global transaction must transit.

What matters in this case is that Beijing – as well as Moscow – clearly read the writing on the wall when, in 2012, Washington applied pressure on SWIFT; blocked international clearing for every Iranian bank; and froze $100 billion in Iranian assets overseas as well as Tehran’s potential to export oil. In the event Washington might decide to slap sanctions on China, bank clearing though CIPS works as a de facto sanctions-evading mechanism. Last March, Russia’s central bank opened its first office in Beijing. Moscow is launching its first $1 billion yuan-denominated government bond sale. Moscow has made it very clear it is committed to a long term strategy to stop using the US dollar as their primary currency in global trade, moving alongside Beijing towards what could be dubbed a post-Bretton Woods exchange system.

Gold is essential in this strategy. Russia, China, India, Brazil & South Africa are all either large producers or consumers of gold – or both. Following what has been extensively discussed in their summits since the early 2010s, the BRICS are bound to focus on trading physical gold. Markets such as COMEX actually trade derivatives on gold, and are backed by an insignificant amount of physical gold. Major BRICS gold producers – especially the Russia-China partnership – plan to be able to exercise extra influence in setting up global gold prices. [..] The current state of play is still all about the petrodollar system; since last year what used to be a key, “secret” informal deal between the US and the House of Saud is firmly in the public domain.

Even warriors in the Hindu Kush may now be aware of how oil and virtually all commodities must be traded in US dollars, and how these petrodollars are recycled into US Treasuries. Through this mechanism Washington has accumulated an astonishing $20 trillion in debt – and counting. Vast populations all across MENA (Middle East-Northern Africa) also learned what happened when Iraq’s Saddam Hussein decided to sell oil in euros, or when Muammar Gaddafi planned to issue a pan-African gold dinar. But now it’s China who’s entering the fray, following on plans set up way back in 2012. And the name of the game is oil-futures trading priced in yuan, with the yuan fully convertible into gold on the Shanghai and Hong Kong foreign exchange markets.

Read more …

The UK Labour party need to cash in now on the government’s mishandling of Brexit and the country’s economy, or risk being seen as part of that government. Corbyn et al know thay could jump in the polls by denouncing Brexit itself, but they don’t have the courage to do that. So on the no. 1 problem, they’re the same as the Tories.

• John McDonnell Warns Over ‘Alarming Increase’ In UK Household Debt (G.)

John McDonnell has said the UK is in the grip of a personal debt crisis with levels of unsecured borrowing predicted to hit a record of £19,000 per household by the end of this parliament. The shadow chancellor said the increase in debt, to more than £14,000 per household this year, was alarming. Analysis from Labour shows unsecured debt is on course to exceed £15,000 per household next year and could go on to exceed £19,000 per household by 2022 if it follows the current trajectory. It is understood Labour plans to focus on the issue in the new year, warning that the continuing squeeze on wages and the high level of inflation are contributing to high levels of personal debt.

On Wednesday the Resolution Foundation, a thinktank, predicted that the stagnation in real wages was set to continue throughout 2018 and may only begin to lift towards the end of the year. McDonnell said: “The alarming increase in average household debt already means many families in our country are struggling over the Christmas period. The Tories have no real answers to tackle the debt crisis gripping our country and have no solutions to offer those struggling to get by as prices run ahead of wages. “The next Labour government will introduce a £10 per hour real living wage, scrap student fees, end the public sector pay cap and cap interest on consumer credit to build an economy for the many, not the few.”

Read more …

Why go this crazy route? Well, money of course.

• Another Fukushima? Tepco Plans To Restart World’s Biggest Nuclear Plant (G.)

If a single structure can define a community, for the 90,000 residents of Kashiwazaki town and the neighbouring village of Kariwa, it is the sprawling nuclear power plant that has dominated the coastal landscape for more than 40 years. When all seven of its reactors are in operation, Kashiwazaki-kariwa generates 8.2m kilowatts of electricity – enough to power 16m households. Occupying 4.2 sq km of land along the Japan Sea coast, it is the biggest nuclear power plant in the world. But today, the reactors at Kashiwazaki-kariwa are idle. The plant in Niigata prefecture, about 140 miles (225km) north-west of the capital, is the nuclear industry’s highest-profile casualty of the nationwide atomic shutdown that followed the March 2011 triple meltdown at Fukushima Daiichi.

The company at the centre of the disaster has encountered anger over its failure to prevent the catastrophe, its treatment of tens of thousands of evacuated residents and its haphazard attempts to clean up its atomic mess. Now, the same utility, Tokyo Electric Power [Tepco], is attempting to banish its Fukushima demons with a push to restart two reactors at Kashiwazaki-kariwa, one of its three nuclear plants. Only then, it says, can it generate the profits it needs to fund the decommissioning of Fukushima Daiichi and win back the public trust it lost in the wake of the meltdown. This week, Japan’s nuclear regulation authority gave its formal approval for Tepco to restart the Kashiwazaki-kariwa’s No. 6 and 7 reactors – the same type of boiling-water reactors that suffered meltdowns at Fukushima Daiichi.

After a month of public hearings, the nuclear regulation authority concluded that Tepco was fit to run a nuclear power plant and said the two reactors met the stricter safety standards introduced after the 2011 disaster.

Read more …

What hope is there for us, if there’s none for our children? And yes, all children are our children, not just the ones that live in our homes and communities.

• Children Increasingly Used As Weapons Of War – Unicef (G.)

Children caught in war zones are increasingly being used as weapons of war – recruited to fight, forced to act as suicide bombers, and used as human shields – the United Nations children’s agency has warned. In a statement summarising 2017 as a brutal year for children caught in conflict, Unicef said parties to conflicts were blatantly disregarding international humanitarian law and children were routinely coming under attack. Rape, forced marriage, abduction and enslavement had become standard tactics in conflicts across Iraq, Syria and Yemen, as well as in Nigeria, South Sudan and Myanmar. Some children, abducted by extremist groups, are abused again by security forces when they are released.

Others are indirectly harmed by fighting, through malnutrition and disease, as access to food, water and sanitation are denied or restricted. Some 27 million children in conflict zones have been forced out of school. “Children are being targeted and exposed to attacks and brutal violence in their homes, schools and playgrounds,” said Manuel Fontaine, Unicef’s director of emergency programmes. “As these attacks continue year after year, we cannot become numb. Such brutality cannot be the new normal.” Much of the fighting affecting children occurred in long-running conflicts in Africa.

Read more …

Dec 262017
 
 December 26, 2017  Posted by at 11:19 am Finance Tagged with: , , , , , , , , , , ,  4 Responses »


Edward Hopper Christmas card 1928


• Shale Gas Fuels 40% Increase In Funding For Plastics Production (G.)
• Bitcoin Could Crash Financial Markets Because Of Massive Borrowing (MW)
• Was Coinbase’s Bitcoin Cash Rollout A Designed Hit? (Luongo)
• Japan PM Abe Urges Firms To Raise Wages By 3% Or More (R.)
• Japan’s Household Spending Jumps But BOJ Seen Keeping Stimulus (R.)
• Shanghai Sets Population At 25 Million To Avoid ‘Big City Disease’ (G./R.)
• Europe Banks Brace For Huge Overhaul That Opens The Doors To Their Data (CNBC)
• Scotland United In Curiosity As Councils Trial Universal Basic Income (G.)
• UK Asylum Offices ‘In A Constant State Of Crisis’, Say Whistleblowers (G.)
• ‘Normality’ To Be Restored At Moria By End of January – Greek Minister (K.)
• UNHCR Calls For Migrant Transfers, Blames Greece For Grim Conditions (K.)


It’s up to you to refuse plastics. Nothing else will work.

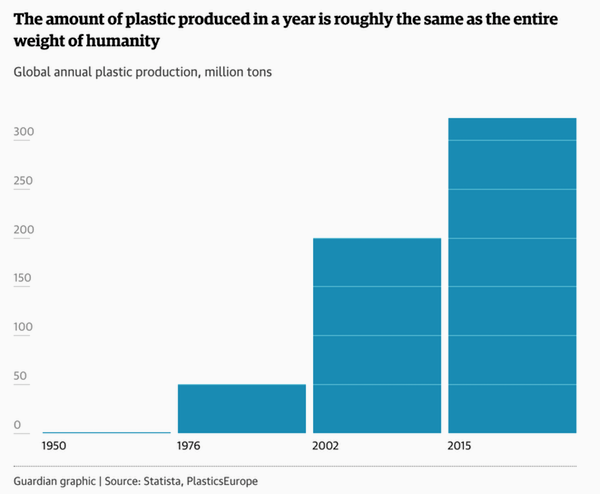
• Shale Gas Fuels 40% Increase In Funding For Plastics Production (G.)

The global plastic binge which is already causing widespread damage to oceans, habitats and food chains, is set to increase dramatically over the next 10 years after multibillion dollar investments in a new generation of plastics plants in the US. Fossil fuel companies are among those who have plooughed more than $180bn since 2010 into new “cracking” facilities that will produce the raw material for everyday plastics from packaging to bottles, trays and cartons. The new facilities – being built by corporations like Exxon Mobile Chemical and Shell Chemical – will help fuel a 40% rise in plastic production in the next decade, according to experts, exacerbating the plastic pollution crisis that scientist warn already risks “near permanent pollution of the earth.”

“We could be locking in decades of expanded plastics production at precisely the time the world is realising we should use far less of it,” said Carroll Muffett, president of the US Center for International Environmental Law, which has analysed the plastic industry. “Around 99% of the feedstock for plastics is fossil fuels, so we are looking at the same companies, like Exxon and Shell, that have helped create the climate crisis. There is a deep and pervasive relationship between oil and gas companies and plastics.” Greenpeace UK’s senior oceans campaigner Louise Edge said any increase in the amount of plastic ending up in the oceans would have a disastrous impact. “We are already producing more disposable plastic than we can deal with, more in the last decade than in the entire twentieth century, and millions of tonnes of it are ending up in our oceans.”

The huge investment in plastic production has been driven by the shale gas boom in the US. This has resulted in one of the raw materials used to produce plastic resin – natural gas liquids – dropping dramatically in price. The American Chemistry Council says that since 2010 this has led to $186bn dollars being invested in 318 new projects. Almost half of them are already under construction or have been completed. The rest are at the planning stage. “I can summarise [the boom in plastics facilities] in two words,” Kevin Swift, chief economist at the ACC, told the Guardian. “Shale gas.”

Read more …

For now, crypto is too small to sink anything at all, but a potential future issue is: If derivatives and leverage play such a big role in crypto, how exactly is it different from all other ‘investments’?

• Bitcoin Could Crash Financial Markets Because Of Massive Borrowing (MW)

Bitcoin mania is starting to look like a religion. I say that because both bitcoin and religion involve faith in the unknowable. Some bitcoin investors believe the cryptocurrency, along with the underlying blockchain technology, will be a vital part of a new, decentralized, post-government society. I can’t prove that won’t happen — nor can bitcoin evangelists prove it will. Like life after death, they can only say it’s out there beyond the horizon. If you believe in bitcoin paradise, fine. It’s your business … until your faith puts everyone else at risk. As of this month, bitcoin is doing it. Is bitcoin in a price bubble? I think so. Asset bubbles usually only hurt the buyers who overpay, but that changes when you add leverage to the equation.

Leverage means “buying with borrowed money.” So when you buy something with borrowed money and can’t repay it, the lender loses too. The problem spreads further when lenders themselves are leveraged. For bitcoin mania to infect the entire financial system, like securitized mortgages did in 2008, buyers would have to use leverage. The bad news is that a growing number do just that. In the U.S., we have a Financial Stability Oversight Council to watch for system-wide vulnerabilities. The FSOC issued its 164-page annual report this month. Here’s its plan on bitcoin and other cryptocurrencies: It is desirable for financial regulators to monitor and analyze their effects on financial stability. Sounds like FSOC is on the case — or at least will be on it, someday. Meanwhile, this month commodity regulators allowed two different U.S. exchanges to launch bitcoin futures contracts.

Oddly, instead of griping about slow regulatory approval, futures industry leaders think the government moved too fast. To get why, you need to understand how futures exchanges work. One key difference between a regulated futures exchange and a private bet between two parties is that the exchange absorbs counterparty risk. When you buy, say, gold futures, you don’t have to worry that whoever sold you the contract will disappear and not pay up. If you close your trade at a profit, the exchange clearinghouse guarantees payment. The clearinghouse consists of the exchange’s member brokerage firms. They all pledge their own capital as a backstop to keep the exchange running. So when the Commodity Futures Trading Commission (CFTC) gave exchanges the green light to launch bitcoin futures, member firms collectively said (I’ll paraphrase here): “WTF?”

Read more …

No matter if crypto surges or collapses in 2018, controversies will be much much bigger than this year. Just getting started.

• Was Coinbase’s Bitcoin Cash Rollout A Designed Hit? (Luongo)

[..] if there is a path to harming Bitcoin and the cryptocurrency market available to the money center banks, then they will always opt for it. I’ve been pretty vocal about the need for having a slow, annoying reserve asset in the cryptocurrency space. I’ve talked about it multiple times (here and here). This doesn’t jibe with Bitcoin Cash proponent and Bitcoin.com CEO Roger Ver’s image of Bitcoin. And that is to Roger’s credit, actually. It’s pretty obvious from a cursory glance at Roger’s Twitter feed that he approaches Bitcoin as a radical libertarian/Austrian Economist would — a purely decentralized, trustless money that can wrest control of the world’s monetary system from rentiers in Government and Banking. Music to my ears. On the other hand is the very shady attitude of Blockstream and the Bitcoin Core group who prevailed in the Segwit 2x fight, which, from Roger Ver’s perspective is actually a mop-up operation, not the decisive battle in the war.

“The reason there is so much hostility from Bitcoin Core towards Bitcoin Cash is because Core knows they have stolen the name but are advocating a completely different system than what was originally described by Satoshi. Bitcoin Cash is Bitcoin” — Roger Ver (@rogerkver) December 19, 2017

The real battle for the soul of Bitcoin happened back in August with the fork that created Bitcoin Cash. Complaining about all of these other forks, to Roger, is like closing the barn door after the horses are gone. By keeping Bitcoin slow and expensive they create the need for new solutions to improve it. Why solve a problem when you can artificially create one and then sell everyone the solution? So, I’m ambivalent about this fight for the soul of Bitcoin, because I want a real digital analogue to Gold which only moves the most important transactions. I don’t want all coins to be all things to all people. But, I also know that with this much money at stake there will be pushback from the ‘powers-that-be.’ The Banks and central banks are staring at an existential threat to their future and are doing what they can to stop it from happening. And that, to them, means gaining control over the Bitcoin blockchain. It also means cutting off the means of entry and exit from the cryptocurrency market for average people.

Read more …

Unemployment in Japan is almost non-existent, but apparently markets don’t work the way they’re supposed to. Tight labor doesn’t lead to higher wages.

• Japan PM Abe Urges Firms To Raise Wages By 3% Or More (R.)

Japanese Prime Minister Shinzo Abe on Tuesday urged companies to raise wages by 3% or more next year, keeping up pressure on firms to spend their huge cash pile on wages to broaden the benefits of his “Abenomics” stimulus policies.“We must sustain and strengthen Japan’s positive economic cycle next year to achieve our long-standing goal of beating deflation,” Abe said in a speech at a meeting of Japan’s biggest business lobby Keidanren. “For that, I’d like to ask companies to raise wages by 3% or higher next spring,” he said. Wages at big companies have been rising slightly more than 2% each year since 2014, government data shows, and an increase of 3% or more next year would help the Bank of Japan to reach its elusive 2% inflation target.

BOJ Governor Haruhiko Kuroda told the same meeting that companies remain hesitant to raise wages because they had become accustomed to prioritising job security over wage hikes during 15 years of deflation. “With consumers remaining reluctant to accept price rises, many firms are concerned about losing customers if they raise prices,” he said. “It seems so difficult for many firms to take the first step to raise their prices, that they wait and see what other firms are doing.” Sadayuki Sakakibara, chairman of Keidanren, made no reference to wages at his speech at the meeting, focusing instead on the need for Japan to get its fiscal house in order. “We’d like to strongly call on the need to restore fiscal health,” as worries over the sustainability of Japan’s social welfare system could discourage consumers to spend, he said.

Read more …

“..due mostly to a boost from rising fuel costs that is seen fading in 2018..”

• Japan’s Household Spending Jumps But BOJ Seen Keeping Stimulus (R.)

Japan’s households spent more than expected in November while consumer inflation ticked up and the jobless rate hit a fresh 24-year low, offering the central bank some hope an economic recovery will drive up inflation to its 2% target. But the increase in prices was due mostly to a boost from rising fuel costs that is seen fading in 2018, keeping the Bank of Japan under pressure to maintain its huge monetary support even as other central banks seek an end to crisis-mode policies. Minutes of the BOJ’s October rate review showed that while most central bank policymakers saw no need to ramp up stimulus, they agreed on the need to sustain “powerful” monetary easing for the time being. “There’s a chance inflation may gradually accelerate toward the fiscal year beginning in April,” as a tightening job market pressures companies to raise wages, said Takeshi Minami, chief economist at Norinchukin Research Institute.

“But inflation remains distant from the BOJ’s 2% target, so the central bank will probably maintain its current policy framework.” Spending was driven by broadbased gains, with households loosening the purse strings for items such as refrigerators, washing machines, and sporting goods and services such as eating-out and travel. Data also showed wage earners’ disposable income rose 1.8% in November from a year earlier, suggesting that higher incomes have encouraged consumers to open their wallets. The nationwide core consumer price index (CPI), which includes oil goods but excludes volatile fresh food prices, rose 0.9% in November from a year earlier, government data showed on Tuesday, marking the 11th straight month of gains. The pace of price growth was just ahead of October’s 0.8% and a median market forecast of the same rate.

Read more …

Illusions of control. China’s no. 1 threat.

• Shanghai Sets Population At 25 Million To Avoid ‘Big City Disease’ (G./R.)

China’s financial hub of Shanghai will limit its population to 25 million people by 2035 as part of a quest to manage “big city disease”, authorities have said. The State Council said on its website late on Monday the goal to control the size of the city was part of Shanghai’s masterplan for 2017-2035, which the government body had approved. “By 2035, the resident population in Shanghai will be controlled at around 25 million and the total amount of land made available for construction will not exceed 3,200 square kilometres,” it said. State media has defined “big city disease” as arising when a megacity becomes plagued with environmental pollution, traffic congestion and a shortage of public services, including education and medical care.

But some experts doubt the feasibility of the plans, with one researcher at a Chinese government thinktank describing the scheme as “unpractical and against the social development trend”. Migrant workers and the city’s poor would suffer the most, predicted Liang Zhongtang last year in an interview with state media, when Shanghai’s target was being drafted. The government set a similar limit for Beijing in September, declaring the city’s population should not exceed 23 million by 2020. Beijing had a population of 21.5 million in 2014. Officials also want to reduce the population of six core districts by 15% compared with 2014 levels. To help achieve this goal authorities said in April some government agencies, state-owned companies and other “non-core” functions of the Chinese capital would be moved to a newly created city about 100 kilometres south of Beijing.

Read more …

Well, actually, your data, that is.

• Europe Banks Brace For Huge Overhaul That Opens The Doors To Their Data (CNBC)

From current accounts to credit cards, established lenders have access to vast amounts of information that financial technology (fintech) competitors could only dream of. In Europe, that could all be about to change. On January 8, banks operating in the European Union will be forced to open up their customer data to third party firms — that is, when customers give consent. EU lawmakers hope that the introduction of the revised Payment Services Directive (PSD2) will give non-banking firms the chance to compete with banks in the payments business and give consumers more choice over financial products and services. Britain’s Competition and Markets Authority (CMA) has set out similar plans to let customers share their data with other banks and third parties.

With customer consent, U.K. banks will be required to give authorized third-party firms access to current account data. Those regulations form part of a conceptual transition known as “open banking.” Under an open banking framework, proponents say, non-banking firms — from corporations as big as Amazon and IBM to start-ups — would be able create new financial products by utilizing the data of banks. Banks will be required to build application programming interfaces (APIs) — sets of code that give third parties secure access to their back-end data. Those APIs serve as channels for developers to get to the data and build their own products and services around it.

Such information could serve as a tool to understand things such as customers’ spending habits or credit history, and could lead to the creation of new services. “In a world of open banking, the customer can choose a provider in each part of the value chain. And each bank has to participate in the value chain as an earners’ right to be there,” Anne Boden, co-founder and chief executive of U.K. mobile-only bank Starling, told CNBC in an interview earlier this year. [..] Some European lenders are giving early signals as to what a post-PSD2 world will look like. Spain’s BBVA, Denmark’s Saxo Bank, Nordic lender Nordea and Ireland’s Ulster Bank have already published open developer portals ahead of the EU legislation.

Read more …

UBI experiments that are poorly designed are real threats to the principle.

• Scotland United In Curiosity As Councils Trial Universal Basic Income (G.)

In Scotland, a country wearily familiar with divisions of a constitutional nature, the concept of a basic income is almost unique in enjoying multi-party favour. Across the four areas currently designing basic income pilots – Glasgow, Edinburgh, Fife and North Ayrshire – the projects have variously been championed by Labour, SNP, Green and, in one case, Conservative councillors. Matt Kerr, who has tirelessly lobbied for the idea through Glasgow city council, said: “Reactions to basic income have not split along the usual left/right party lines. Some people to the left of the Labour party think that it undermines the role of trade unions and others take the opposite view. But there should be room for scepticism; you need that to get the right policy.” Advocates are aware such unity of purpose is precious and worth preserving.

“The danger is that this falls into party blocks,” said Kerr. “If people can unite around having a curiosity about [it] then I’m happy with that. But having the first minister on board has done us no harm at all.” Inevitably, Sturgeon’s declared interest has invited criticism from her opponents. A civil service briefing paper on basic income, which expressed concerns that the “conflicting and confusing” policy could be a disincentive to work and costed its national roll-out at £12.3bn a year, was obtained by the Scottish Conservatives through a freedom of information request in October. The party accused her of “pandering to the extreme left of the [independence] movement”. But advocates argue the figures fail to take into account savings the scheme would bring.

The independent thinktank Reform Scotland, which published a briefing earlier this month setting out a suggested basic income of £5,200 for every adult, has calculated that much of the cost could be met through a combination of making work-related benefits obsolete and changes to the tax system, including scrapping the personal allowance and merging national insurance and income tax. [..] Joe Cullinane, the Labour leader of North Ayrshire council, said: “We have high levels of deprivation and high unemployment, so we take the view that the current system is failing us and we need to look at something new to lift people out of poverty. “Basic income has critics and supporters on the left and right, which tells you there are very different ways of shaping it and we need to state at the outset that this is a progressive change, to remove that fear and allow people to have greater control over their lives, to enter the labour market on their own terms.”

Read more …

“Two whistleblowers claim Home Office departments delay asylum applications for profit..”

• UK Asylum Offices ‘In A Constant State Of Crisis’, Say Whistleblowers (G.)

Staff in the Home Office’s asylum directorate are undertrained, overworked and operating in a “constant state of crisis”, two whistleblowers have claimed, as applicants endure long waits to have their case dealt with due to internal pressures. The Home Office staff have also told the Guardian that asylum case workers are making poor decisions about applications because they are under pressure to focus on more profitable visa applications. Despite a “shocking increase in complaints (from applicants) and MP enquiries questioning delays”, they say caseworkers have been told to brush off all enquires and “just give standard lines” of response when called to account.

A source from the UK Visa and Immigration Unit (UKVI) has alleged that caseworkers have been ordered to kick applications for spousal visas “into the long grass” because they can make more money for the directorate by processing student visas. Spousal visas, also known as settlement visas, cost more than student visas but take much longer to process. The source also claims visa applications are routinely labelled “complex” or ”non-straightforward” by staff – a term which excuses the UKVI from adhering to their standard processing times – it is, the source claimed, “just a euphemism for ‘there’s more profitable stuff we could be doing’”. Paying hundreds of pounds for priority services to try to avoid delays on decisions is a “waste of time”, they warned applicants.

The allegations reflect concerns expressed in a report earlier this year by David Bolt, the Independent Chief Inspector of Borders and Immigration, who said the Home Office is not “in effective control” of its asylum process. [..] Some of the more shocking findings from Bolt’s report included pregnant women being made to wait more than two years for decisions on their immigration applications; an increasing numbers of applicants having their immigration applications registered as “not straightforward” and endlessly delayed; and Home Office employees being “pushed to the limit” by individual targets and threatened with disciplinary action as deadlines approach.

Read more …

At least one more month of utter despair, with little reason to assume any improvement by then. Mouzalas cannot escape his part of the blame.. That said, he’s not lying when he says “Here in Moria we have a problem with unaccompanied minor refugees. We have asked Europe to take a share of these children. It refuses to do so..”

• ‘Normality’ To Be Restored At Moria By End of January – Greek Minister (K.)

Migration Minister Yiannis Mouzalas said Monday authorities were making huge efforts to improve conditions at the Moria camp on the eastern Aegean island of Lesvos, while accusing European officials of “hypocrisy” for failing to shoulder their share of the burden. Speaking after an unannounced visit at the infamous migrant and refugee processing center, Mouzalas said Greek authorities were hoping to restore “normality” at the facility by the end of January. “It all depends on arrivals,” Mouzalas said. “Today it was good weather and a total of 175 arrivals have been recorded on Lesvos as of this morning,” he said.

Responding to criticism over the scenes of misery and squalor documented by foreign media at Moria last week, the leftist minister said: “Europe must put an end to its hypocrisy.” “Here in Moria we have a problem with unaccompanied minor refugees. We have asked Europe to take a share of these children. It refuses to do so,” Mouzalas said. “It’s very easy to act like a prosecutor. Dealing with the situation in a way that helps refugees and migrants is the hard part. And this is what we are expected to do,” he said. “There is no point in wagging your finger. What you need to do is mobilize the procedures and mechanisms in order to improve conditions and solve problems,” he said.

Read more …

And the UNHCR is not beyond blame, either. Pointing fingers at others is always easy, but hard to keep up after two whole years.

• UNHCR Calls For Migrant Transfers, Blames Greece For Grim Conditions (K.)

As temperatures drop, the UN refugee agency (UNHCR) once more urged Greek authorities to swiftly transfer thousands of refugees and migrants living in cramped and unsafe island camps to the mainland where better conditions and services are available. “Tension in the reception centers and on the islands has been mounting since the summer when the number of arrivals began rising,” UNHCR spokeswoman Cecile Pouilly told Voice of America. “In some cases, local authorities have opposed efforts to introduce improvements inside the reception centers,” Pouilly was quoted as saying. More than 15,000 people have been transferred to the mainland over the past year.

Meanwhile, speaking to the New Europe news website, the EU’s special envoy on migration, Maarten Verwey, suggested that Greek authorities were to blame for the grim living conditions inside island migrant camps, as recently documented by American news outlet BuzzFeed and Germany’s Deutsche Welle. “The Commission has made the funding available to ensure appropriate accommodation for all. However, the Commission cannot order the creation or expansion of reception capacity, against the opposition of the competent authorities,” Verwey said, according to New Europe.

Read more …

Nov 232017
 
 November 23, 2017  Posted by at 9:43 am Finance Tagged with: , , , , , , , , , , , ,  8 Responses »


Roger Viollet Great Paris Flood, Avenue Daumesnil 1910


• Fed Fears New Record High Credit Bubble – Danielle DiMartino Booth (USAW)
• Global Debt Is Rising, Especially in Emerging Economies (St. Louis Fed)
• Pressure on US Households Intensifies (DDMB)
• Zombie Firms Roam Europe Because Banks Help Keep Them Undead
• China Is Pumping A Lot Of Cash Into Its Economy To Calm Investors (CNBC)
• Chinese Investors Eye Leverage to Juice U.S. CLO Returns (BBG)
• China’s $3.4 Trillion Corporate Bond Market Faces Rocky 2018 (BBG)
• Worst Growth In Decades Pushes UK To Inject £25bn Into Economy (Ind.)
• Budget Shows Tories Are Unfit For Office – Corbyn (G.)
• Facebook To Let Users See If They ‘Liked’ Russian Accounts (R.)
• Putin Tell Russian Firms To Be Ready For War Production (Ind.)
• PNG Police Move In On Closed Australia Refugee Camp On Manus (AFP)
• Night Being Lost To Artificial Light (BBC)


“I don’t think any of us know what the implications are for a $50 trillion debt build since the great financial crisis (of 2008). It is impossible to say. We have never dealt with anything of this magnitude.”

• Fed Fears New Record High Credit Bubble – Danielle DiMartino Booth (USAW)

Former Federal Reserve insider Danielle DiMartino Booth says the record high stock and bond prices make the Fed nervous because it’s fearful of popping this record high credit bubble. DiMartino Booth says, “The Fed’s biggest fear is they know darn well this much credit has built up in the background, and the ramifications of the un-wind for what has happened since the great financial crisis is even greater than what happened in 2008 and 2009. It’s global and pretty viral. So, the Fed has good reason to be fearful of what’s going to happen when the baby boomer generation and the pension funds in this country take a third body blow since 2000, and that’s why they are so very, very intimidated by the financial markets and so fearful of a correction.”

Why will the Fed not allow even a small correction in the markets? DiMartino Booth says, “Look back to last year when Deutsche Bank took the markets to DEFCON 1. Maybe you were paying attention and maybe you weren’t, but it certainly got the German government’s attention. They said the checkbook is open, and we will do whatever we need to do because we can’t quantify what will happen when a major bank gets into a distressed situation. I think what central banks worldwide fear is that there has been such a magnificent re-blowing of the credit bubble since 2007 and 2008 that they can’t tell you where the contagion is going to be. So, they have this great fear of a 2% or 3% or 10% (correction) and do not know what the daisy chain is going to look like and where the contagion is going to land.

It could be the Chinese bond market. It could be Italian insolvent banks or it might be Deutsche Bank, or whether it might be small or midsize U.S. commercial lenders. They can’t tell you where the systemic risk lies, and that’s where their fear is. This credit bubble is of their making.” In short, the Fed does not know what is going to happen, and according to DiMartino Booth, nobody does. DiMartino Booth contends, “I don’t think any of us know what the implications are for a $50 trillion debt build since the great financial crisis (of 2008). It is impossible to say. We have never dealt with anything of this magnitude.”

“2017 is the record for quantitative easing (money printing) globally. We have never, not even in the darkest days of the financial crisis, central banks have never injected as much money as they have into the markets. . . . I am not a gold bug, but we do know that in times of corrections that there is no place to hide in traditional asset classes that you can get at your Merrill Lynch brokerage. Gold and silver in the precious metals complex are the only places to hide and get true diversification and safety.”

Read more …

They do know what’s going on.

• Global Debt Is Rising, Especially in Emerging Economies (St. Louis Fed)

The world has become used to cheap credit. And the increase in borrowing by emerging economies could pose a risk as monetary policy normalizes. In response to the most recent recession, central banks around the world decreased their main policy rates to almost zero, as seen in the figure below.

[..] The downward trend in short-term and long-term interest rates has made borrowing cheaper over time. As a result, global debt has increased substantially since 2007. According to Bank for International Settlements (BIS) data, total debt of the nonfinancial sector (that is, households, government and nonfinancial corporations) amounted to $145 trillion in the first quarter of 2017, an increase of 40% since the first quarter of 2007. Most of this increase has been driven by an increase in total debt in emerging economies, especially in China, as seen in the following figure.

Furthermore, emerging economies have borrowed heavily in foreign currency, mainly in U.S. dollars, shown in the figure below.

According to the BIS, total dollar-denominated debt outside the U.S. reached $10.7 trillion in the first quarter of 2017, and about a third of this debt is owed by the nonfinancial sector of emerging economies. Analysts have stressed that the rapid accumulation of debt in emerging economies could pose risks for the global economy in the presence of U.S. monetary policy normalization. Market expectations of a rapid increase in the policy rate and the reduction of the Federal Reserve’s balance sheet could lead to higher borrowing costs and an appreciation of the U.S. dollar. This, in turn, would increase the cost of refinancing debt in emerging economies. If these risks materialized, there could be an increase in the demand for safe assets, particularly U.S. Treasuries. This would lead to a decrease in long-term rates. In times of monetary normalization, the yield curve would flatten, and banks profitability could be eroded.

Read more …

After the storms…

• Pressure on US Households Intensifies (DDMB)

The full effects of Hurricanes Harvey and Irma are rapidly showing up in the data. In September, according to Black Knight, the number of mortgages either past due or in foreclosure rose by 214,000, or 9%, compared with August. At 5.1%, the combined rate is far off the previous month’s 4.7% and the most recent low of 4.5% recorded in March 2007. October’s numbers have brought the picture more clearly into focus. More than 229,000 past-due mortgages are tied to the storms. Hurricane Irma accounted for 163,000 and Harvey, 66,000. To place the damage to households in context, before the storms, Florida and Texas ranked 22nd and 20th among non-current mortgage states. As of October, Florida has risen to second place and Texas is in fifth place.

The economy has also enjoyed a rush of car sales as sufficiently-collateralized and insured drivers immediately replaced vehicles destroyed by the storms. According to the latest retail data, car sales slowed to a 0.7% growth rate in October, far below September’s blistering 4.6-percent pace. Nonetheless, the next development could be a further deterioration in auto delinquencies attributed to storm victims. The most recent third-quarter data from the New York Fed suggest struggling households continue to buckle under the strains of their monthly payments. The delinquency rate for subprime loans originated by auto-finance companies, as opposed to banks, hit 9.7% in the three months ended in September.

With one in four auto loans outstanding going to subprime borrowers, the rate has been rising since 2013 and is at a seven-year high. What’s most notable is that these delinquency rates are being recorded outside recession, all but ensuring 2009’s peak of 10.9% will be breached in the next downturn. And while credit-card delinquencies are nowhere near their crisis-era double-digit peaks, the New York Fed noted that serious delinquencies have been on the rise for one year. The serious delinquency rate hit 4.6% in the third quarter, up from 4.4% the prior quarter. Adjusted for inflation, the growth of U.S. credit-card spending has outpaced that of incomes for 26 straight months.

Read more …

Anyone shorting Italy for real yet?

• Zombie Firms Roam Europe Because Banks Help Keep Them Undead

So-called zombie firms – companies that would be out of business or painfully restructured in a competitive economy – have become a key issue for policy makers grappling with sluggish productivity growth in developed economies. The fear is that those “zombies” are sucking up capital that could otherwise go to more productive firms. A new study by the OECD helps explaining how banks favor the spread of zombie firms. It shows that weak companies tend to be connected to weak banks which prefer to roll over or restructure bad loans rather than declaring them delinquent and writing them off. The OECD’s research by Dan Andrews and Filippos Petroulakis lends new urgency to the ECB’s efforts to slash non-performing loans in the region.

Supervisors have asked for detailed plans of how NPLs will be cut and are mulling requiring banks to set aside more capital for soured loans. “In order to facilitate the unwinding of the zombie problem, it is essential that bank balance sheets are strong, underlining the need for fast recapitalizations after crises and other measures to reduce NPLs,” write the authors. “The zombie firm problem in Europe may at least partly stem from bank forbearance.” Weak productivity matters in an ageing continent like Europe, where a shrinking working population is expected to support an ever increasing number of retirees. This can’t happen unless technology and education make it possible to squeeze more and more output from labor and capital.

The OECD has been investigating the impact of living-dead companies for years. It argues that zombification leads to capital misallocation, as weak banks tend to steer less capital to healthier and more productive firms. This in turn leads to low productivity and returns, making it more difficult to get credit even for innovative companies. Andrews and Petroulakis also say that, in addition to forcing banks to work down their NPLs and bolster capital, efficient laws on insolvency are needed. It is not a coincidence that Italy – the European country with the largest NPL problem – overhauled its bankruptcy rules last month to make them quicker and more efficient.

Read more …

Mr. Xi, sir, it’s time to be careful.

• China Is Pumping A Lot Of Cash Into Its Economy To Calm Investors (CNBC)

China has been pumping a lot of cash into its system to lift market sentiment, as the world’s second-largest economy walks a thin line between curbing debt and keeping everything running smoothly. Last week, the People’s Bank of China injected cash totaling 810 billion Chinese yuan ($122.4 billion) in five straight days of daily liquidity management operations. Those actions, which represented the largest weekly net increase since January, were in part a Beijing response to its 10-year sovereign bond yields spiking to multiyear highs, experts said. “Surging Chinese government bond yields hit the nerve of policymakers, so in order to further prevent a greater surge, they injected liquidity into the system to improve market sentiment,” said Ken Cheung, a foreign exchange strategist at Mizuho Bank who focuses on Chinese currencies and monetary policies.

Nomura analysts said last week in a note that the bond rout was due to fears of regulatory tightening from Beijing. Bond yields, which move inversely to prices, briefly hit 4% in China for the first time in three years. A rise in the benchmark government bond yield threatens to drive up overall borrowing costs — and potentially worsen the country’s debt situation. On Monday and Tuesday of this week, the PBOC injected a net 30 billion yuan ($4.5 billion), but it didn’t expand that money supply on Wednesday. Analysts said that pause may have been due to market sentiment seemingly stabilizing, but it may be short-lived. As Chinese 10-year yields are still near the psychologically important 4% level, Cheung told CNBC he expects more injections ahead if necessary, as Beijing needs to “maintain liquidity to please the market.”

Read more …

“It’s dangerous territory. Leveraging BB-rated bonds – is that a good idea?”

• Chinese Investors Eye Leverage to Juice U.S. CLO Returns (BBG)

The last time Asian investors borrowed money to invest in structured-credit products – during the run-up to the financial crisis – it didn’t work out so well. Now, a new set of buyers from China are hoping things turn out differently. Instead of snapping up packages of risky derivatives tied to U.S. home loans, they’re buying collateralized loan obligations that bundle together corporate loans to highly leveraged companies. And while such CLOs weathered the last crisis relatively well, there’s already concern that these investors are being tempted to deploy leverage to amplify their returns. The problem is that even the riskiest pieces of CLOs can yield less than the 8 to 10% targets Chinese investors have grown accustomed to in their markets, according to Collin Chan, a CLO analyst at Bank of America Corp.

So CLOs, the junk-rated slices of which yield just 5.5 percentage points more than Libor, “may not be crazily attractive” to them, said Chan, whose team has trekked to China multiple times this year to pitch the products to investors there. On a recent trip to China, potential new investors expressed interest in the idea of applying leverage for the purchase of CLOs, even at the riskier BB level, Chan said. He estimates levered returns for the BB-rated CLO slice may be almost 20%. Leverage is employed using the repo financing market, where short-term loans allow investors to borrow money by lending securities. It’s the latest evidence of the search for yield that has engulfed credit markets and provided a significant boost for CLO sales this year. China and its many types of financial institutions now look like promising buyers for a product that in Asia has typically been bought by Japanese banks and Korean insurers.

“It wouldn’t be wise for the Chinese to use leverage at this stage,” said Asif Khan, head of CLO origination and distribution at MUFG. “It’s dangerous territory. Leveraging BB-rated bonds – is that a good idea? Any potential use of leverage by Chinese investors could pose potential risk in case of severe volatility.” [..] Chinese investors have yet to enter the CLO market en masse. However signs point to their growing participation. In some cases, investment banks and CLO managers have made as many as five trips to Asia this year, adding on special CLO-focused investor conferences in mainland China for the first time ever to raise the product’s profile. The demand to diversify into dollar assets has grown from a wide range of investors, despite Chinese-government capital controls limiting deployment of capital abroad.

Read more …

$3.4 trillion sounds low.

• China’s $3.4 Trillion Corporate Bond Market Faces Rocky 2018 (BBG)

China’s deleveraging campaign is finally starting to bite in the nation’s corporate-bond market, a shift that will make 2018 a clearer test of policy makers’ appetites to let struggling companies fail. Yields on five-year top-rated local corporate notes have jumped about 33 basis points since the month began, to a three-year high of 5.3%, according to data compiled by clearing house ChinaBond. Government bonds, which have far greater liquidity, had already moved last month as the central bank warned further deleveraging was needed. With more than $1 trillion of local bonds maturing in 2018-19, it will become increasingly expensive for Chinese companies to roll over financing – and all the tougher for those in industries like coal that the nation’s leadership wants to shrink.

Two companies based in Inner Mongolia, a northern province that’s suffered from a debt-and-construction binge, missed bond payments on Tuesday, in a demonstration of the kind of pain that may come. In the long haul, that all may be good for China. Allowing more defaults could see its bond market become more like its overseas counterparts, with a greater differentiation in price. And that could mean it channels funds more productively. “The deleveraging campaign and the new rules on the asset management industry will further differentiate good and bad quality credits, and make the onshore credit market more efficient,” said Raymond Gui at Income Partners Asset Management. “Weaker companies will find it harder to roll over their debts because funding costs will stay high.” Gui predicts yields will keep climbing. The average for top-rated corporate bonds is already 2.2 percentage points above what investors demanded to hold them in October last year.

Read more …

More austerity.

• Worst Growth In Decades Pushes UK To Inject £25bn Into Economy (Ind.)

Britain faces its worst period of economic growth in more than half a century after official data revealed a country hamstrung by feeble productivity and Brexit. Dismal figures released alongside Philip Hammond’s Budget led the Chancellor to announce a £25bn cash injection to strengthen the ailing economy. The major giveaway will see money head towards housebuilding, preparing Whitehall for Brexit, the NHS and boosting the tech sector. But despite the extra cash most government departments will still experience deep cuts over the next five years, as Mr Hammond struggles to get the public finances under control. Mr Hammond tried to put a positive sheen on progress towards reducing net debt and abolishing the deficit, but data suggested Britain would now fail to achieve a budget surplus before 2031.

Forecasts from the Office for Budget Responsibility indicated GDP would grow by 1.5% in 2017, down from the 2% forecast in March. The Government’s official financial auditor said growth would drop to 1.4% next year – as low as 1.3% in 2019 and 2020 – and then pick up to 1.5% in 2021 and 1.6% in 2022. The OBR said the main downward pressure on growth was a big fall in the UK’s projected productivity, intensifying public spending cuts and Brexit uncertainty. The body was established in 2010 by then-Chancellor George Osborne to end a system under which the Treasury produced its own economic growth estimates. The latest predictions are the gloomiest that the auditor has ever given, and they are also smaller than any produced by the Treasury since 1983. Institute for Fiscal Studies director Paul Johnson said the 1.4% average growth forecast over the period was “much worse than we have had over the last 60 or 70 years”.

Read more …

“.. the reality will be – a lot of people will be no better off. And the misery that many are in will be continuing.”

• Budget Shows Tories Are Unfit For Office – Corbyn (G.)

In his response to the budget, Corbyn – it is the leader of the opposition who traditionally speaks rather than the shadow chancellor – said Hammond had completely failed to tackle a national crisis of stagnation and falling wages. “The test of a budget is how it affects the reality of people’s lives all around this country,” the Labour leader said. “And I believe as the days go ahead, and this budget unravels, the reality will be – a lot of people will be no better off. And the misery that many are in will be continuing.” Largely eschewing direct focus on Hammond’s specific announcements in favour of a broader critique of the government’s wider economic approach, Corbyn castigated Hammond for again missing deficit reduction targets, and for a continued spending squeeze on schools and the police.

Speaking about housing, Corbyn said rough sleeping had doubled since 2010, and that this Christmas 120,000 children would be living in temporary accommodation. “We need a large-scale publicly funded housebuilding programme, not this government’s accounting tricks and empty promises.” Summing up, he said: “We were promised a revolutionary budget. The reality is nothing has changed. People were looking for help from this budget. They have been let down. Let down by a government that, like the economy they’ve presided over, is weak and unstable and in need of urgent change. They call this budget ‘Fit for the Future’. The reality is this is a government no longer fit for office.”

Read more …

Mish commented on Twitter he’d be more interested in seeing which CIA propaganda sites he’d liked.

Question is: should we trust Facebook’s assessment of what is Russian and what not? I don’t think so.

• Facebook To Let Users See If They ‘Liked’ Russian Accounts (R.)

Facebook said on Wednesday it would build a web page to allow users to see which Russian propaganda accounts they have liked or followed, after U.S. lawmakers demanded that the social network be more open about the reach of the accounts. U.S. lawmakers called the announcement a positive step. The web page, though, would fall short of their demands that Facebook individually notify users about Russian propaganda posts or ads they were exposed to. Facebook, Alphabet Inc’s Google and Twitter are facing a backlash after saying Russians used their services to anonymously spread divisive messages among Americans in the run-up to the 2016 U.S. elections. U.S. lawmakers have criticized the tech firms for not doing more to detect the alleged election meddling, which the Russian government denies involvement in.

Facebook says the propaganda came from the Internet Research Agency, a Russian organization that according to lawmakers and researchers employs hundreds of people to push pro-Kremlin content under phony social media accounts. As many as 126 million people could have been served posts on Facebook and 20 million on Instagram, the company says. Facebook has since deactivated the accounts. Facebook, in a statement, said it would let people see which pages or accounts they liked or followed between January 2015 and August 2017 that were affiliated with the Internet Research Agency. The tool will be available by the end of the year as “part of our ongoing effort to protect our platforms and the people who use them from bad actors who try to undermine our democracy,” Facebook said.

The web page will show only a list of accounts, not the posts or ads affiliated with them, according to a mock-up. U.S. lawmakers have separately published some posts. It was not clear if Facebook would eventually do more, such as sending individualized notifications to users.

Read more …

NATO is a real threat.

• Putin Tell Russian Firms To Be Ready For War Production (Ind.)

Russian business should be prepared to switch to production to military needs at any time, said Vladimir Putin on Wednesday. The Russian president was speaking at a conference of military leaders in Sochi. “The ability of our economy to increase military production and services at a given time is one of the most important aspects of military security,” Mr Putin said. “To this end, all strategic, and simply large-scale enterprise should be ready, regardless of ownership.” A day earlier, the president had spoken of a need to catch up and overtake the West in military technology. “Our army and navy need to have the very best equipment — better than foreign equivalents,” he said. “If we want to win, we have to be better.”

Since the 2008 Georgian war, which was a difficult operation, the Russian military has undergone extensive modernisation. Ageing Soviet equipment has gone. There is a new testing regime. There are new command structures. The budget has also increased exponentially. This year, military expenses will cross 3 trillion roubles, or 3.3% of GDP. This would be a record were it not for one-off costs in 2016. Over the next two years, spending is forecast to be cut back slightly, to approximately 2.8% of GDP. Though that budget remains less than 30% of the combined Nato budget in Europe, many countries are increasing their military spending in response to the “Russian threat”. Nato military command has also been restructured — it says in response to Russian cyber and military threats.

Read more …

First thing that needs to happen is Australian media reporting on this. Then people must protest. New Zealand recently offered to take a whole group of these people, Australia declined. Many need medical treatment. Australia refuses.

• PNG Police Move In On Closed Australia Refugee Camp On Manus (AFP)

Papua New Guinea police moved into the shuttered Australian refugee camp on the country’s Manus Island Thursday in the most aggressive push yet to force hundreds of men to leave, the Australian government and detainees said. The police operation was confirmed by Australia’s Immigration Minister Peter Dutton, who said Canberra was “very keen for people to move out of the Manus regional processing centre”. “I think it’s outrageous that people are still there,” he told Sydney commercial radio station 2GB. “We want people to move.” Iranian Behrouz Boochani tweeted from inside the camp earlier Thursday, writing that “police have started to break the shelters, water tanks and are saying ‘move, move'”.

“Navy soldiers are outside the prison camp. We are on high alert right now. We are under attack,” he said, adding that two refugees were in need of urgent medical treatment. Other refugees posted photos to social media sites showing police entering the camp, which Australia declared closed on October 31 after the PNG Supreme Court declared it unconstitutional. [..] Australia had shut off electricity and water supplies to the camp and demanded that some 600 asylum-seekers detained there move to three nearby transition centres. Around 400 of the asylum-seekers have refused to leave, saying they fear for their safety in a local population which opposes their presence on the island. They also say the three transition centres are not fully operational, with a lack of security, sufficient water or electricity.

[..] Canberra has strongly rejected calls to move the refugees to Australia and instead has tried to resettle them in third countries, including the United States. But so far, just 54 refugees have been accepted by Washington, with 24 flown to America in September. Despite widespread criticism, Canberra has defended its offshore processing policy as stopping deaths at sea after a spate of drownings.

Read more …

Oh, the lights will go out eventually…

• Night Being Lost To Artificial Light (BBC)

A study of pictures of Earth by night has revealed that artificial light is growing brighter and more extensive every year. Between 2012 and 2016, the planet’s artificially lit outdoor area grew by more than 2% per year. Scientists say a “loss of night” in many countries is having negative consequences for “flora, fauna, and human well-being”. A team published the findings in the journal Science Advances. Their study used data from a Nasa satellite radiometer – a device designed specifically to measure the brightness of night-time light. It showed that changes in brightness over time varied greatly by country. Some of the world’s “brightest nations”, such as the US and Spain, remained the same. Most nations in South America, Africa and Asia grew brighter. Only a few countries showed a decrease in brightness, such as Yemen and Syria – both experiencing warfare.

The nocturnal satellite images – of glowing coastlines and spider-like city networks – look quite beautiful but artificial lighting has unintended consequences for human health and the environment. Lead researcher Christopher Kyba from the German Research Centre for Geoscience in Potsdam said that the introduction of artificial light was “one of the most dramatic physical changes human beings have made to our environment”. He and his colleagues had expected to see a decrease in brightness in wealthy cities and industrial areas as they switched from the orange glow of sodium lights to more energy-efficient LEDs; the light sensor on the satellite is not able to measure the bluer part of the spectrum of light that LEDs emit.

“I expected that in wealthy countries – like the US, UK, and Germany – we’d see overall decreases in light, especially in brightly lit areas,” he told BBC News. “Instead we see countries like the US staying the same and the UK and Germany becoming increasingly bright.” Since the satellite sensor does not “see” the bluer light that humans can see, the increases in brightness that we experience will be even greater than what the researchers were able to measure.


UK, Netherlands, Belgium

Read more …

Oct 172017
 
 October 17, 2017  Posted by at 8:40 am Finance Tagged with: , , , , , , , , ,  4 Responses »


Rembrandt An Old Scholar Near a Window in a Vaulted Room 1631


• Asset Prices & Monetary Policy in an Irrational World (Whalen)
• Central Banks Will Cause An Orgy of Blood (Clarmond)
• Global Central Banking Leadership Flux Looms (R.)
• Kobe Steel Faked Quality Data For Decades (Nikkei)
• China’s Impact on Global Markets is About to Get Much Bigger (BBG)
• China’s Banks Are Bingeing on Bonds Despite Debt Crackdown (BBG)
• China Has Only Taken Baby Steps to Cut Leverage (BBG)
• Investigations of Wall Street Have Disappeared from Corporate Media (Martens)
• MIT Economist Andrew Lo Wants You To Realize That Traders Are Animals (BW)
• Varoufakis Tells Macron To Adopt The ‘Empty-chair’ Tactic (EuA)
• The Kurds Have No Friends But The Mountains (David Graeber)
• Malta Car Bomb Kills Panama Papers Journalist (G.)
• IMF Chief Calls For Implementation Of Greek Program, Debt Relief (K.)
• 2,000 Refugees, Migrants Landed in Greece Since October 1 (GR)


“.. the logical and unavoidable result of the end of QE is that asset prices must fall and excessive debt must be reduced.”

• Asset Prices & Monetary Policy in an Irrational World (Whalen)

[..] Let’s wind the clock back two decades to December 1996. The Labor Department had just reported a “blowout” jobs report. Then-Federal Reserve chairman Alan Greenspan had just completed a decade in office. He made a now famous speech at American Enterprise Institute wherein Greenspan asked if “irrational exuberance” had begun to play a role in the increase of certain asset prices. He said:

“Clearly, sustained low inflation implies less uncertainty about the future, and lower risk premiums imply higher prices of stocks and other earning assets. We can see that in the inverse relationship exhibited by price/earnings ratios and the rate of inflation in the past. But how do we know when irrational exuberance has unduly escalated asset values, which then become subject to unexpected and prolonged contractions as they have in Japan over the past decade? And how do we factor that assessment into monetary policy? We as central bankers need not be concerned if a collapsing financial asset bubble does not threaten to impair the real economy, its production, jobs, and price stability. Indeed, the sharp stock market break of 1987 had few negative consequences for the economy. But we should not underestimate or become complacent about the complexity of the interactions of asset markets and the economy. Thus, evaluating shifts in balance sheets generally, and in asset prices particularly, must be an integral part of the development of monetary policy.”

In the wake of the 2008 financial crisis, the FOMC abandoned its focus on the productive sector and essentially substituted exuberant monetary policy for the irrational behavior of investors in the roaring 2000s. In place of banks and other intermediaries pushing up assets prices, we instead have seen almost a decade of “quantitative easing” by the FOMC doing much the same thing. And all of this in the name of boosting the real economy?

The Federal Reserve System, joined by the Bank of Japan and the ECB, artificially increased assets prices in a coordinated effort not to promote growth, but avoid debt deflation. Unfortunately, without an increase in income to match the artificial rise in assets prices, the logical and unavoidable result of the end of QE is that asset prices must fall and excessive debt must be reduced. Stocks, commercial real estate and many other asset classes have been vastly inflated by the actions of global central banks. Assuming that these central bankers actually understand the implications of their actions, which are nicely summarized by Greenspan’s remarks some 20 years ago, then the obvious conclusion is that there is no way to “normalize” monetary policy without seeing a significant, secular decline in asset prices. The image below illustrates the most recent meeting of the FOMC.

Read more …

Great piece of history.

• Central Banks Will Cause An Orgy of Blood (Clarmond)

The Bank of Japan’s current path provides an ominous reminder of a similar era 80 years ago. These policies, which are also being followed by the other world central banks, will lead to disaster. “One man – one kill” railed Inoue Nissho, leader of the Ketsumeidan (the Blood Pledge Corps), a Japanese ultranationalist group of the 1930s committed to cleansing the country of ‘traitors’ – the leaders of business and government. The first name on their death list was Inoue Junnosuke, a former Finance Minister, an austerity advocate and former governor of the Bank of Japan (BOJ); he was shot as he visited a nursery school. The next name was Dan Takuma, head of the Mitsui Group, the Japanese Goldman Sachs; he was shot in front of his office in the fashionable Nihonbashi district.

Further attacks on the BOJ and Mitsubishi Bank followed but were unsuccessful. The “world of cosmopolitan finance had collided with nationalist resentment.” The liberal elite was stunned, unable to provide answers to the social turmoil of the time; and with the establishment paralysed, the public began to sympathise with the killers’ aims. Enter Finance Minister Takahashi Korekiyo. He placated the nationalists by championing massive deficit financing, via the BOJ, to pull Japan out of its economic morass. Japan’s economy soon embarked on a period of economic growth with stable prices, full employment and humming factories, an “economic nirvana.” Seven decades later these results were heralded a success by another central banker trying a similar trick – Ben Bernanke. Korekiyo’s plan was to fund government spending by having the BOJ directly purchase all the government-issued bonds.

The hope was that, when conditions and inflation improved, the bonds would be sold back into the market. Four years later, the BOJ’s balance sheet was 90% of GDP, and the economy (and for “economy” read military) was totally dependent on government spending financed by the BOJ. As the first modest hint of inflation arrived Korekiyo attempted to sell government bonds publicly, but the auction failed. With this failure it became clear that the bonds which had been stuffed onto the BOJ’s balance sheet could never be sold. Korekiyo’s struggle to ‘cut up the credit card’ culminated in him suffering a similar fate to Junnosuke and being cut up in an attack of army machetes. As the BOJ’s balance sheet crossed 100% of GDP, there could be no turning back, the road to conflict had been primed by the BOJ’s swollen balance sheet and the money that had flooded into the military.

The current Bank of Japan’s balance sheet has now again crossed that fabled 100% of GDP and it is getting close to owning 45% of outstanding government bonds. There is no end in sight with the BOJ buying $60 billion a month of government debt. At this current pace the modern BOJ will by 2019 be the proud owner of 60% of the local bond market. There is no longer a market price for a Japanese Government Bond, it is an asset whose price is set by the BOJ. The key difference between today and the 1930s is that Japan now has an open capital account, therefore the only untethered market price is the currency. The Yen’s continued devaluation will be deep and comprehensive, while Japanese equities will continue to rise, adjusting to the currency loss.

Read more …

Musical chairs. Won’t change a thing.

• Global Central Banking Leadership Flux Looms (R.)

The leaders of the world’s top central banks who risked trillions of dollars and their reputations to rescue the global economy are now set to walk off stage at a time when the lingering effects of the crisis, evolving technology and a combustible political landscape will challenge their successors. The Fed, the Bank of Japan and the People’s Bank of China may all have new bosses in early 2018 and there will be a new head of the ECB the following year. The new leaders will have to deal with the hangover from the 2007-2009 crisis and its immediate aftermath as well as newly emerging risks. Some $10 trillion in assets bought by the Fed, the ECB and the BOJ to prop up their economies remains on the books and will have to be pared back. Stubbornly low global inflation and weak growth complicate the return to more conventional policies.

There are unfinished reforms in China and Europe, while the rise of nationalism could erode central bank independence. Further ahead, the spread of cryptocurrencies and other technologies threatens to weaken central bank control over the financial system. “The bad news is that in a crisis people learn by doing,” said Vincent Reinhart, chief economist at investment firm Standish Mellon and a longtime official at the Federal Reserve. “Will the next set of people have the set of experiences that allows them to do that? Will they have a test?” The changing of the guard could veer in unpredictable directions. China’s president is considering a provincial official to succeed Zhou Xiaochuan, a veteran policymaker who has led the central bank since 2002 and whom analysts regard as a champion of reforms that could falter without his leadership.

Read more …

Even had a fraud manual. This keeps growing by the day.

• Kobe Steel Faked Quality Data For Decades (Nikkei)

Product quality data was falsified for decades at some Kobe Steel plants in Japan, well beyond the roughly 10-year time frame given by the steelmaker, a source with knowledge of the situation said Monday. Employees involved in the data manipulation used the industry term tokusai to refer to shipping of products that did not meet the standards requested by customers, the source said. Though tokusai usually refers to voluntary acceptance of such products, plants sometimes sent substandard goods without customers’ consent. The word was apparently in use at some plants for 40 to 50 years. The cheating procedures eventually became institutionalized in what was essentially a tacit fraud manual, allowing the practice to continue as managers came and went. Data manipulation may have occurred with the knowledge of plant foremen and quality control managers. Some shipments even came with forged inspection certificates.

Kobe Steel has tapped senior officials in the aluminum and copper business – where most of the misconduct took place – to serve on its board. How far up the chain of command knowledge of the fraud may have extended in the past remains an open question. Systemic data falsification took place at four Japanese production sites. The scandal has spread to the manufacturer’s mainstay steel business, with revelations Friday that steel wire was also shipped without inspection or with faked certificates. The number of affected customers has swelled from around 200 to roughly 500. Kobe Steel has said it will complete safety inspections for already shipped products in two weeks or so. A report on the causes of the fraud and measures to prevent a recurrence will come out in a month or so. The steelmaker is conducting a groupwide probe that includes interviews with former senior officials.

Read more …

Yeah, when its Ponzi collapses.

• China’s Impact on Global Markets is About to Get Much Bigger (BBG)

China’s ascension as an economic superstar over the past three-plus decades is out of sync with its heft in global financial markets. But things are starting to change, and investors around the world will feel the difference. China makes up more than one-seventh of the global economy, yet its footprint in international portfolios is ludicrously small, with overseas investors owning less than 2% of its domestic stocks and bonds. But its insulated markets are slowly becoming more integrated, as President Xi Jinping loosens rules on foreign participation. That push could get further backing at the Communist Party’s twice-a-decade congress this month, where the leadership will set policy priorities for the coming five years.

China’s capacity to influence global financial markets has been growing incrementally, but the pivotal moment came in 2015, when the yuan’s unexpected devaluation rocked assets worldwide, showing investors beyond Asia that China’s markets are a force to be reckoned with. The surprise move saw the yuan slide the most in two decades on Aug. 11, 2015, as Beijing sought to shore up economic growth and make China’s exports more competitive. Following on from a Chinese stock rout in mid-2015 that also had a ripple effect globally, the devaluation rattled risk assets for weeks as it was seen as an admission the economy was struggling. Fast forward to 2017, and China’s clout has only expanded, with its lion’s share of global trade making the managed yuan an anchor for currencies throughout Asia.

The nation’s status as both the world’s biggest exporter and the largest market of consumers means policy tweaks in Beijing can affect prices for everything from beef to bitcoin. Trading on Shanghai’s commodity futures market is taking on increasing influence beyond China’s borders. The country’s pivot away from the smokestack industries that have been its growth engine for decades toward high-tech production is already shifting the global landscape for manufacturing and consumption. At the same time, China is looking to draw in more foreign capital by opening conduits to its equity and bond markets, among the largest in the world. That makes the 19th party congress, where Xi will unveil the party’s vision for China over the next five years, key for even the most peripheral of investors.

Read more …

It’s almost funny.

• China’s Banks Are Bingeing on Bonds Despite Debt Crackdown (BBG)

China’s banks are still bingeing on short-term financing, defying analyst predictions that they would wean themselves off such debt as regulators intensify a crackdown on leverage. Sales of negotiable certificates of deposit — a key funding source for medium and smaller banks — surged 49% from a year ago in the third quarter to a record 5.4 trillion yuan ($819 billion), according to data compiled by Bloomberg. While strategists had predicted in June that the NCD market would shrink, it turned out to be one of the few funding channels left as officials drained cash from the interbank market and asked lenders to strengthen risk controls. China’s deleveraging looms large in debt-market dynamics these days, with government bond yields at two-year highs and the one-week Shanghai Interbank Offered Rate not far from the most expensive since 2015.

Still, officials are also trying to keep the economy humming: they’ve tweaked the rules governing NCD issuance, but haven’t shut off the taps as credit growth accelerates. “The short-term debt is an indispensable fundraising channel for smaller banks,” said Shen Bifan, head of research at First Capital Securities Co.’s fixed-income department in Shenzhen. “As other channels get squeezed, and lenders’ books continue to expand, as is the case now amid solid economic growth, it’d be difficult to see the NCD market size shrink.” Net financing – sales minus maturities – through such securities was at 333 billion yuan in the third quarter, versus a total of 1.7 trillion yuan in the first half, data compiled by Bloomberg show. With more than 8 trillion yuan of contracts outstanding, it’s now the fourth-largest type of bond in China, after sovereign, local government and policy bank debt.

Read more …

Xi only talks the talk.

• China Has Only Taken Baby Steps to Cut Leverage (BBG)

China has taken “baby steps” toward cutting leverage as lending from banks slows, but progress has been uneven as borrowing by households and the government has risen, according to S&P Global Ratings. Authorities are adopting both tight and loose policies to try to reduce the country’s dependency on debt without causing a hard landing, analysts led by Christopher Lee wrote in a note dated Oct. 16. S&P last month cut China’s sovereign rating for the first time since 1999, saying it didn’t believe enough was being done to contain credit growth.

The next big test is whether companies can withstand higher funding costs as financial conditions tighten, according to S&P. “Smaller and less-capitalized banks may feel the liquidity squeeze and pressures on their capital, leading to distress; and default risks could also increase for the local government financing vehicles,” the analysts wrote. “Passing the baton of credit-fueled growth in recent years to households also has many obvious risks,” such as a correction in the property market hurting consumption, they said.

Read more …

One system.

• Investigations of Wall Street Have Disappeared from Corporate Media (Martens)

Rupert Murdoch’s News Corp. bought Dow Jones & Company in late 2007 after a century of ownership by the Bancroft family. The purchase just happened to come at a time when the Federal Reserve had secretly begun to funnel what would end up totaling $16 trillion in cumulative low-cost loans to bail out the Wall Street mega banks and their foreign counterparts. In 2011, the Pew Research Center released a study on how front page coverage had changed since the News Corp. purchase of the Wall Street Journal. Pew found that “coverage has clearly moved away from what had been the paper’s core mission under previous ownership—covering business and corporate America. In the past three and a half years, front-page coverage of business is down about one-third from what it had been in 2007, the last year of the old ownership regime.”

What is not down but “up” at the Wall Street Journal is its defense of the Wall Street banking giants’ indefensible practices on its editorial and opinion pages. One of the most striking examples of the changing face of corporate media coverage of Wall Street was an October 20, 2013 editorial in the Wall Street Journal headlined:“The Morgan Shakedown.” The unsigned editorial began with this: “The tentative $13 billion settlement that the Justice Department appears to be extracting from J.P. Morgan Chase needs to be understood as a watershed moment in American capitalism. Federal law enforcers are confiscating roughly half of a company’s annual earnings for no other reason than because they can and because they want to appease their left-wing populist allies.”

Actually, there was a very good reason for the $13 billion settlement – but the intrepid investigative reporting on that subject would be done by Matt Taibbi for Rolling Stone – not by the paper still calling itself the “Wall Street” Journal. Taibbi revealed that the U.S. Justice Department had actually settled on the cheap and had failed to reveal to the public that it had the most credible of eyewitnesses to mortgage fraud at JPMorgan Chase – a securities attorney who worked there and had reported the fraud to her supervisors. The attorney, Alayne Fleischmann, told Taibbi that what she witnessed in JPMorgan’s mortgage operations was “massive criminal securities fraud.”

Taibbi’s in-depth report on the matter made the editorial board at the Wall Street Journal appear naïve or captured by Wall Street. It raised the added embarrassing question as to why the Wall Street Journal was out of touch with the details of the Justice Department’s investigation.

Read more …

This year’s Fauxbel for human behavior, next year’s for animal behavior?

• MIT Economist Andrew Lo Wants You To Realize That Traders Are Animals (BW)

Every reigning theory of finance has holes. The efficient-markets hypothesis says markets are rational and self-regulating, but it doesn’t account for crashes and crises; behavioral finance blames market breakdowns on investors’ short-term thinking, but it fails to account for group dynamics or predict future markets. Andrew Lo spent his early career studying these flaws. Lo, 57, is the Charles E. and Susan T. Harris professor of finance at the MIT Sloan School of Management, but he’s always been a multidisciplinarian. At the Bronx High School of Science, he excelled in biology, physics, chemistry, and mathematics and liked solving broad problems. “I just really enjoyed the dynamics across all these fields,” he says. “I never thought of myself as, I am an economist or I’m a statistician.”

Eighteen years into his research, Lo had a major insight. One day in 1999 his 4-year-old son took off running toward a gorilla cage at the Smithsonian’s National Zoo. “The mother gorilla jumped right in and growled,” he says. “And as soon as she did that, I did the same thing. I ran to my child and brought him back.” The similarity of their reactions startled Lo and caused him to wonder: Could there be other similarities in the way people and animals react to danger and risk? The insight eventually led to the adaptive-markets hypothesis. “Right now, we tend to collect prices and assume that those are the only things that matter” to predict investor behavior, Lo says, whereas an ecologist would try to understand investors as a population—which means accounting for their animal instincts. Lo’s hypothesis says people act in their own self-interest but frequently make mistakes, figure out where they’ve erred, and change their behaviors.

The broader system also adapts. These complex interactions contribute to our booms and busts. Lo’s book-length exploration of the idea, Adaptive Markets, came out in February. Says Ben Golub, a founding partner at BlackRock Inc. and now co-head of the company’s risk and quantitative analysis group: “It makes you realize that at any time in the market, the people who are there are not there by accident.” Some people survived the last financial crisis and might be more risk-averse, and some people who’ve joined since might be more risk-tolerant. “The cautious guys survive for a while and then get pushed out by the more aggressive risk takers, who then get thrown out when the thing blows up in their faces,” Golub says. He’s made the book required reading for many BlackRock employees.

Read more …

“Varoufakis plans to run for the 2019 European elections, even if he says the European Parliament “is not a real parliament.” But he wants to run in Germany, “to show that federalism is possible, and also that Germany’s current politics is harmful for Germans.”

• Varoufakis Tells Macron To Adopt The ‘Empty-chair’ Tactic (EuA)

More than fifty years ago, in 1965, French President Charles de Gaulle withdrew his ministers from the Council of the EU, de facto vetoing all decisions. According to Yanis Varoufakis, former finance minister for Greece, Macron should consider refreshing this tactic – but for the opposite reason. De Gaulle was defending nation states, while Macron wants to push federalism forward. “Macron has got some good ideas, but he already lost, he is done, belittled by Germany” who refuses to create a budget for the Eurozone, according to the economist, who spoke to the French press in Paris. According to him, the success of the far-right party AfD in September’s parliamentary election gives Germany the perfect excuse to retrench on this dossier. And the European Monetary Fund, proposed by Germany as an alternative to a Eurozone budget, is a sham and not a real compromise, according to Varoufakis.

The only way to force Germany into siding with France on relaunching the federalist process is the empty-chair tactic, he says. A form of “constructive disobedience” [..] “Trying to achieve a permanent reduction of the public deficit under 3% of GDP is nonsensical. It is not a problem to run a public deficit: Arizona will always have one, especially if compared to California. In a federation, this happens a lot. But in the case of France, current public spending will condemn the country to permanent stagnation, because the German industry has a monopoly of numerous markets”, he says. The real priority according to him is investment, which should be raised to €500 billion per year. “The Juncker plan is a farce,” he said.

Without a eurozone budget to relaunch the federalist project, the economist proposes that the European Investment Bank (BEI) issue green bonds to finance large infrastructure projects in clean energy and transport – and that the ECB buys them. “We don’t need to change the treaties. It is already feasible – it is just a question of achieving the consensus of the EIB’s board.” On the type of projects that should be financed, Varoufakis echoes Macron who spoke about a way to cross the old continent without polluting: he would like to develop a railway network from the East to the West as well as invest in clean energy. While he sides with Macron’s federalist elements, including a transnational list for the 2019 European elections, Varoufakis is also very critical of his first steps.

“The speech he gave in Greece was pathetic. Coming to tell us that Greece is out of the crisis is an insult, and speaking from [Athens’ Acropolis] where countless dictators spoke to Greeks adds insult to injury,” said the economist. Varoufakis plans to run for the 2019 European elections, even if he says the European Parliament “is not a real parliament.” But he wants to run in Germany, “to show that federalism is possible, and also that Germany’s current politics is harmful for Germans.”

Read more …

Excellent and very educational.

• The Kurds Have No Friends But The Mountains (David Graeber)

“The Kurds have no friends but the mountains” — that’s what Mehmet Aksoy used to say. But Mehmet, who was killed Sept. 26 during an attack by the Islamic State in northern Syria, was my friend, and a tireless advocate of the Kurdish freedom movement. He was working on an essay that began with those words when he died. He often used that adage to explain the plight of his people, who have long been used or mistreated by the very powers that claim to spread democracy and freedom through the world. I first met Mehmet at a Kurdish demonstration in London, where he lived. I had come because of my interest in direct democratic movements like the one the Syrian Kurds were building, but ended up feeling as if I was lurking, out of place at the fringe of the gathering, until he walked up and introduced himself.

I came to know him as I’ve now heard many in the community did, as kind and unassuming but somehow larger than life, always juggling a dozen projects, films, essays, events and political actions. Now I think it’s important to tell people about his last project, his writing on the conflict in Kurdistan, so that more of us understand what’s at stake there. He was writing in the shadow of a referendum taking place in neighboring Iraqi Kurdistan that everyone knew would end with a strong endorsement of an independent Kurdish state. But the Syrian Kurdish freedom movement that Mehmet represents has pursued an entirely different vision from that of the Kurds in Iraq: It does not wish to change the borders of states but simply to ignore them and to build grass-roots democracy at the community level.

It frustrated Mehmet that the endless sacrifices of Kurdish fighters against the Islamic State in cities across Syria are being mistakenly seen as justification of more borders and more divisions rather than for less. Too often in the Western news media, the Kurds are grouped together as one homogeneous people, with Syrian Kurds often an afterthought of late because of the attention the Iraqi Kurds have received for their referendum. But the Kurds in these two countries have built very different political systems. The Syrian Kurds have built a coalition with Arabs, Syriacs, Christians and others in the northern slice of Syria that they call Rojava (or, more officially, the The Democratic Federation of Northern Syria.).

Read more …

RIP. May your courage shine on others.

• Malta Car Bomb Kills Panama Papers Journalist (G.)

The journalist who led the Panama Papers investigation into corruption in Malta was killed on Monday in a car bomb near her home. Daphne Caruana Galizia died on Monday afternoon when her car, a Peugeot 108, was destroyed by a powerful explosive device which blew the vehicle into several pieces and threw the debris into a nearby field. A blogger whose posts often attracted more readers than the combined circulation of the country’s newspapers, Caruana Galizia was recently described by the Politico website as a “one-woman WikiLeaks”. Her blogs were a thorn in the side of both the establishment and underworld figures that hold sway in Europe’s smallest member state.

Her most recent revelations pointed the finger at Malta’s prime minister, Joseph Muscat, and two of his closest aides, connecting offshore companies linked to the three men with the sale of Maltese passports and payments from the government of Azerbaijan. No group or individual has come forward to claim responsibility for the attack. Malta’s president, Marie-Louise Coleiro Preca, called for calm. “In these moments, when the country is shocked by such a vicious attack, I call on everyone to measure their words, to not pass judgment and to show solidarity,” she said. After a fraught general election this summer, commentators had been fearing a return to the political violence that scarred Malta during the 1980s.

In a statement, Muscat condemned the “barbaric attack”, saying he had asked police to reach out to other countries’ security services for help identifying the perpetrators. [..] Caruana Galizia, who claimed to have no political affiliations, set her sights on a wide range of targets, from banks facilitating money laundering to links between Malta’s online gaming industry and the Mafia. Over the last two years, her reporting had largely focused on revelations from the Panama Papers, a cache of 11.5m documents leaked from the internal database of the world’s fourth largest offshore law firm, Mossack Fonseca.

Read more …

This is theater. And it’s empty.

• IMF Chief Calls For Implementation Of Greek Program, Debt Relief (K.)

Managing Director of the IMF, Christine Lagarde, has praised Greece’s progress on reforms while saying that implementation of the adjustment program coupled with an agreement on debt relief are key to leading the debt-wracked country out of the crisis. The IMF chief made the comments after a meeting with Greek Prime Minister Alexis Tsipras in Washington Monday to discuss recent developments in Greece and key issues ahead. “I was very pleased to welcome Prime Minister Tsipras to the IMF today. I complimented him and the Greek people on the notable progress Greece has achieved in the implementation of difficult policies, including recent pension and income tax reforms. We had an excellent and productive meeting,” Lagarde said in a statement after the meeting.

“The IMF recently approved in principle a new arrangement to support Greece’s policy program. Resolute implementation of this program, together with an agreement with Greece’s European partners on debt relief, are essential to support Greece’s return to sustainable growth and a successful exit from official financing next year,” Lagarde said. “The prime minister and I are committed to working together towards this goal,” she said. In his comments, Tsipras said that “after several years of economic recession Greece has turned a page.” The Greek prime minister said that it is in everyone’s interest to wrap up the third bailout review as swiftly as possible.

Read more …

Numbers rising as we speak.

• 2,000 Refugees, Migrants Landed in Greece Since October 1 (GR)

A total of 1,877 migrants and refugees crossed into the northern Aegean islands from the Turkish coast during the first 15 days of October. According to official figures, 1,148 have arrived in Lesvos; 572 in Chios, and 117 in Samos. In addition to this, on Monday morning, 44 people arrived in Lesvos and 157 in Chios. Between October 1 and 13, the Turkish coast guard announced that it had located 25 incidents involving dinghies with migrants and refugees on board, that had attempted to reach the Greek waters. 907 people have been returned back to Turkey.

Read more …

Oct 122017
 
 October 12, 2017  Posted by at 2:26 pm Finance Tagged with: , , , , , , , ,  5 Responses »


Fan Ho East meets west 1963


For those of you who don’t know Andy Xie, he’s an MIT-educated former IMF economist and was once Morgan Stanley’s chief Asia-Pacific economist. Xie is known for a bearish view of China, and not Beijing’s favorite person. He’s now an ‘independent’ economist based in Shanghai. He gained respect for multiple bubble predictions, including the 1997 Asian crisis and the 2008 US subprime crisis.

Andy Xie posted an article in the South China Morning Post a few days ago that warrants attention. Quite a lot of it, actually. In it, he mentions some pretty stunning numbers and predictions. Perhaps most significant are:

“only China can restore stability in the global economy”

and

“The festering political tension [in the West] could boil over. Radical politicians aiming for class struggle may rise to the top. The US midterm elections in 2018 and presidential election in 2020 are the events that could upend the applecart.”

Here are some highlights.


The bubble economy is set to burst, and US elections may well be the trigger

Central banks continue to focus on consumption inflation, not asset inflation, in their decisions. Their attitude has supported one bubble after another. These bubbles have led to rising inequality and made mass consumer inflation less likely. Since the 2008 financial crisis, asset inflation has fully recovered, and then some.

The US household net worth is 34% above the peak in 2007, versus 30% for nominal GDP. China’s property value may have surpassed the total in the rest of the world combined. The world is stuck in a vicious cycle of asset bubbles, low consumer inflation, stagnant productivity and low wage growth.

Let that sink in. If Xie is right, and I would put my money on that, despite all the housing bubbles elsewhere in the world, the Chinese, who make a lot less money than westerners, have pushed up the ‘value’ of Chinese residential real estate so massively that their homes are now ‘worth’ more than all other houses on the planet. Xie returns to this point later in the article, and says: “In tier-one cities, property costs are likely to be between 50 and 100 years of household income. At the peak of Japan’s property bubble, it was about 20 in Tokyo. “.

We’ll get back to that. But it suggests that Chinese, if they spend half their income on housing, which is probably not that crazy an assumption, must work 100 to 200 years to pay off their mortgages. Again, let that sink in.

The US Federal Reserve has indicated that it will begin to unwind its QE assets this month and raise the interest rate by another 25 basis points to 1.5%. China has been clipping the debt wings of grey rhinos and pouring cold water on property speculation. They are worried about asset bubbles. But, if recent history is any guide, when asset markets begin to tumble, they will reverse their actions and encourage debt binges again. [..] most powerful people in the world operate on flimsy assumptions.

Despite low unemployment and widespread labour shortages, wage increases and inflation in Japan have been around zero for a quarter of a century. Western central bankers assumed that the same wouldn’t happen to them, without understanding the underlying reasons. The loss of competitiveness changes how macro policy works.

The mistaken stimulus has the unintended consequences of dissipating real wealth and increasing inequality. American household net worth is at an all-time high of 5 times GDP, significantly higher than the bubble peaks of 4.1 times in 2000 and 4.7 in 2007, and far higher than the historical norm of three times GDP. On the other hand, US capital formation has stagnated for decades. The outlandish paper wealth is just the same asset at ever higher prices.

That is the very definition of a bubble: “The outlandish paper wealth is just the same asset at ever higher prices.” American household net ‘worth’ is in a huge bubble, some 66% higher than the historical average. And that’s in a time when for many their net worth is way below that average, a time when more than half live paycheck to paycheck and can’t afford medical bills and/or car repair bills without borrowing. And that is the very definition of inequality:

The inflation of paper wealth has a serious impact on inequality. The top 1% in the US owns one-third of the wealth and the top 10% owns three-quarters. Half of the people don’t even own stocks. Asset inflation will increase inequality by definition. Moreover, 90% of the income growth since 2008 has gone to the top 1%, partly due to their ability to cash out in the inflated asset market.

An economy that depends on asset inflation always disproportionately benefits the asset-rich top 1%. [..] Germany and Japan do not have significant asset bubbles. Their inequality is far less than in the Anglo-Saxon economies that have succumbed to the allure of financial speculation.

True, largely, but Japan both has major economic troubles today (deflation), and will have worse ones going forward (demographics). While Germany can unload its losses on the EU periphery (and does). Japan can’t ‘afford’ a housing bubble, its people have refused to raise spending for many years, scared as they are through stagnant wages and falling prices. While Germany doesn’t need a housing bubble to keep its economy growing: it exports whatever’s negative about it to its neighbors. China, however, DOES need bubbles, and blows them with abandon:

While Western central bankers can stop making things worse, only China can restore stability in the global economy. Consider that 800 million Chinese workers have become as productive as their Western counterparts, but are not even close in terms of consumption. This is the fundamental reason for the global imbalance.

Note: as we saw before, while the Chinese may not consume as much as Westerners when it comes to consumer products, they DO -on average- put a far higher percentage of their wages into real estate. And that is because Beijing encourages such behavior. The politburo needs the bubbles to keep things moving. And therefore creates them on purpose. Presumably with the idea that incomes will come up so much that all these homes become more affordable compared to wages. That looks like a big gamble.

Property costs of between 50 and 100 years of household income are not manageable, and rising rates and/or an outright crisis will expose that. And then on top of that, the government wants, needs, an ever bigger take of people’s incomes. Because its whole model is based on its investing in the economy, even if a large part of it is not efficient or profitable.

China’s model is to subsidise investment. The resulting overcapacity inevitably devalues whatever its workers produce. That slows down wage rises and prolongs the deflationary pull. [..] Overinvestment means destroying capital. The model can only be sustained through taxing the household sector to fill the gap.

In addition to taking nearly half of the business labour outlay, China has invented the unique model of taxing the household sector through asset bubbles. The stock market was started with the explicit intention to subsidise state-owned enterprises. The most important asset bubble is the property market. It redistributes about 10% of GDP to the government sector from the household sector. The levies for subsidising investment keep consumption down and make the economy more dependent on investment and export.

In order to prevent a huge real estate crash, Beijing will have to make sure wages rise, across the board, and substantially, for hundreds of millions of people. And there we get back to what Xie said above:

The government finds an ever-increasing need to raise levies and, hence, make the property bubble bigger. In tier-one cities, property costs are likely to be between 50 and 100 years of household income. At the peak of Japan’s property bubble, it was about 20 in Tokyo. China’s residential property value may have surpassed the total in the rest of the world combined.

The 800 million pound elephant here is that what Beijing pushes its citizens to put in real estate, they can no longer spend on other things. Their consumption will flatline or even fall. Unless the Party manages to raise their wages, but it would have to raise them by a lot, because it needs more and more taxes to be paid by the same wages.

And here’s where Andy Xie gets most interesting:

How is this all going to end? Rising interest rates are usually the trigger. But we know the current bubble economy tends to keep inflation low through suppressing mass consumption and increasing overcapacity. It gives central bankers the excuse to keep the printing press on.

In 1929, Joseph Kennedy thought that, when a shoeshine boy was giving stock tips, the market had run out of fools. Today, that shoeshine boy would be a genius. In today’s bubble, central bankers and governments are fools. They can mobilise more resources to become bigger fools. In 2000, the dotcom bubble burst because some firms were caught making up numbers. Today, you don’t need to make up numbers. What one needs is stories.

Those are some pretty impressive insights, and they go way beyond China. Today’s fools are not yesterday’s fools. Only, today’s fools have been given the rights, and the tools, to keep blowing ever larger bubbles. The only conclusion can be that when the bubbles burst, it’ll be much much worse than the Great Depression. And this time, China will blow up along with the west. Take cover!

Hot stocks or property are sold like Hollywood stars. Rumour and innuendo will do the job. Nothing real is necessary. In 2007, structured mortgage products exposed cash-short borrowers. The defaults snowballed. But, in China, leverage is always rolled over. Default is usually considered a political act. And it never snowballs: the government makes sure of it.

Can China continue to roll over its leveraged debt when the west is in crisis, is forced to heavily cut its imports, just as Beijing needs more tax revenue to keep its miracle model alive? WIll it be able to export its over-leverage and over-capacity through the new Silk Road project? It looks very doubtful. And we shouldn’t expect the Party Congress this month to address these issues. They know better.

Xie finishes with most original predictions. Class struggle in the US. It sounds like something straight out of Karl Marx, but perhaps we are already seeing the first signs today.

In the US, the leverage is mostly in the government. It won’t default, because it can print money. The most likely cause for the bubble to burst would be the rising political tension in the West. The bubble economy keeps squeezing the middle class, with more debt and less wages. The festering political tension could boil over. Radical politicians aiming for class struggle may rise to the top. The US midterm elections in 2018 and presidential election in 2020 are the events that could upend the applecart.

Maybe class struggle is something we’ll see first in Europe, both at a national and at a pan-European level. Too many countries keep their systems humming not by being productive, but by encouraging their citizens to sink deeper into debt. Low interest rates may be attractive for signing up to new loans, but the ‘trajectory’ gets shorter all the time, because those same low rates absolutely murder savings and pensions.

The only thing that can keep the whole caboodle from exploding would be absolutely stunning economic growth at least somewhere in the world, but every single somewhere is far too deep in debt for that to happen.

Take cover.


Sep 192017
 
 September 19, 2017  Posted by at 12:52 pm Finance Tagged with: , , , , , , , , ,  11 Responses »


Wynn Bullock Child on a Forest Road 1958


A few days ago, former Reagan Budget Director and -apparently- permabear (aka perennial bear) David Stockman did an interview (see below) with Stuart Varney at Fox -a permabull?!-, who started off with ‘the stock rally goes on’ despite a London terror attack and the North Korea missile situation. His first statement to Stockman was something in the vein of “if I had listened to you at any time after the past 2-3 years, I’d have lost a fortune..” Stockman shot back with (paraphrased): “if you’d have listened to me in 2000, 2004, you’d have dodged a bullet”, and at some point later “get out of bonds, get out of stocks, it’s a dangerous casino.” Familiar territory for most of you.

I happen to think Stockman is right, and if anything, he doesn’t go far enough, strong enough. What that makes me I don’t know, what’s deeper and longer than perennial or perma? But it’s Varney’s assumption that he would have lost a fortune that triggered me this time around. Because it’s an assumption built on an assumption, and pretty soon it’s assumptions all the way down.

First, that fortune is not real, unless and until he sells the stocks and bonds he made it with. If he has, that would indicate that he doesn’t believe in the market anymore, which is not very likely for a permabull to do. So Varney probably still has his paper ‘fortune’. I’m using him as an example, of course, of all the permabulls and others who hold such paper.

Presumably, they often also think they have made a fortune, and presumably they also think that means they are smart. But that begs a question: how can it be smart to put one’s money into paper that is ‘worth’ what it is today ONLY because the world’s central banks have been handed the power to save the ailing banks that own them with many trillions of freshly printed QE? And no, there can be no doubt of that.

And there are plenty other data that tell the story. The world’s central banks have blown giant bubbles all over the place. That’s where the bulls’ “fortunes” come from. They are bubble fortunes. It has nothing to do with being smart. And of course, as I’ve said many times before, there are no investors left to begin with, because you can’t be an investor if there are no functioning markets, and for a market to function you need price discovery.

Which is exactly what central banks have killed. No-one has one iota of a clue what anything is really worth, what the difference between ‘price’ and ‘value’ is. Stockman at one point suggests people should hold on to Microsoft, but does he really believe that Bill Gates will remain standing when everyone around him crashes? That tech stocks are immune to the impending crash for some reason? If true, that would seem to indicate that tech stocks represent real value while -virtually- no others do. Hard to believe.

Please allow me to insert a graph. This one is from Tyler Durden the other day, and it paints a clear picture as much as it raises a big question. It suggests that until December 2016 the S&P and the ‘real economy’ were in lockstep. I think not. But one thing’s for sure: ever since January, i.e. the Trump presidency, the gaping gap between the two has grown so fast it’s almost funny.


Not that I would for one moment wish to blame Trump for that; he’s merely caught up in a wave much larger than an election or a White House residency. What is happening to the US -and global- economy goes back decades, not months. Which makes the graph puzzling, too, obviously. Just ask the new-fangled platoons of waiters and greeters with multiple jobs in America. And/or the 50-60-70% who can’t afford a $500 emergency bill, the 97 million who live paycheck to paycheck.. America’s already crashing, it’s just a matter of waiting for the markets to catch up with America’s reality. That’s what price discovery is about. Here’s another, similar, graph. Note: I don’t really want to go and find the best graphs, we’ve posted and re-posted so many of them it would feel like an insult to everyone involved.


But I digress. This was to be about Stuart Varney and the platoons and legions of permabulls out there. As I said, many of them, make that most, will feel they’ve made their fortune because they’re smart. Even if riding a Yellen and Draghi and Abenomics wave has zilch to do with intelligence. But there’s another side to that supposed smartness. And Stockman is on to it.

The large majority of people who think they got rich because they’re smart will also lose their ‘fortunes’ because they think they’re smart. It is inevitable, it’s a mathematical certainty. And not only because the central banks are discussing various forms of tapering. It’s a certainty because those who think they’re smart will hold on to their ‘assets’ too long. Because the markets will become much less liquid. Because the doors through which people will have to pass to escape the fire are too narrow to let them all though at the same time.

Fortunes built on central banks largesses are virtual. You have to sell your assets to make them real. But the same mechanics that blew the bubbles in housing, stocks, bonds et al also keep people from selling them. Until it’s too late. It may seem easier to sell stocks and bonds than homes, and it is, but in a crash it’s harder than one might think. And prices can come down very rapidly in very little time.

So perhaps the right way to look at this is to tell yourself you were not smart at all when you made that fortune, but now you’re going to smarten up. There will be a few people who do that, but only a few. Most will feel confident that they can see the crash coming in time to get out. Because they’re smart enough. After all, they just made a fortune, right?

It’s not just individuals. Pension funds have been accumulating huge portfolios in ever riskier ‘assets’. Which of them will be able to react fast enough if things start unraveling? And for the lucky few that will, what are they going to buy with the money? Bonds, stocks? Gold perhaps? Crypto? Everyone at once?

Don’t let’s forget that one of the main characteristics -and its consequences- of the everything bubble the central banks granted us is far too often overlooked: leverage. Low interest rates have made borrowing stupidly cheap, and so everyone has borrowed. As soon as things start crashing, there will be margin calls, lines of credit will be withdrawn, people and institutions will have to panic sell (everything including crypto) just to try to stay somewhat afloat, it’s all very predictable and we’ve seen it all before.

But yes, you’re right. The rally continues. And we can’t know what will trigger the downfall, nor can we pinpoint the timing. Still, it should be enough to know that it’s coming. Alas, for many it is not. They’re blinded by the light. But even that light is not real. It’s entirely virtual.


Aug 162017
 
 August 16, 2017  Posted by at 8:57 am Finance Tagged with: , , , , , , , , , ,  2 Responses »


Fred Stein Hydrant, New York 1947


• The Greatest Crisis In World History Is About To Be Unleashed (von Greyerz)
• After 100 Months of Buying The Dips – Peak Crazy (Stockman)
• China Has Got To Fix Its Debt Problem, IMF Says (CNBC)
• China Money Supply Growth Slips Again as Leverage Crunch Goes On (BBG)
• UK Risks ‘Losing Its Place As Property-Owning Democracy’
• The New American Dream: Rent Your Home From A Hedge Fund (Black)
• Trump Signs Order to Speed Up Public-Works Permits (BBG)
• German Challenge To ECB QE Asset Buys Sent To European Court (R.)
• Washington’s Long War on Syria (Ren.)
• Fish Confusing Plastic Debris In Ocean For Food (G.)


Debt leads to war.

• The Greatest Crisis In World History Is About To Be Unleashed (von Greyerz)

Totally irresponsible policies by governments and central banks have created the most dangerous crisis that the world has ever experienced. Risk doesn’t arise quickly as the result of a single action or event. No, risk of the magnitude that the world is experiencing today is the result of many years or decades of economic mismanagement. Cycles are normal in nature and in the world economy. And cycles that are the result of the laws of nature normally play out in an orderly fashion without extreme tops or bottoms. “Just take the seasons. They go from summer to autumn, winter and spring, with soft transitions that seldom involve drama or catastrophe. Economic cycles would be the same if they were allowed to happen naturally without the interference of governments.

But power corrupts and throughout history leaders have always hung on to power by interfering with the normal business cycle. This involves anything from reducing the precious metals content of money from 100% to nothing, printing money, leveraging credit, manipulating interest rates, taking total taxes from at least 50% + today from nothing 100 years ago etc, etc. Governments will always fail when they believe that they are gods. But not only governments believe they perform godly tasks but also hubristic investment bankers like the ex-CEO of Goldman Sachs who proclaimed that the bank was doing God’s work. It must be remembered that Goldman, like most other banks, would have gone under if they and JP Morgan hadn’t instructed the Fed to save them by printing and guaranteeing $25 trillion. Or maybe that was God’s hand too?

We now have unmanageable risks at many levels – politically, geopolitically, economically and financially. This is a RISK ON situation that is extremely dangerous and will have very grave consequences. There are numerous risks that can all cause the collapse of the world economy and they all have equal relevance. However, the political situation in the USA is very dangerous for the world. This the biggest economy in the world, albeit bankrupt with debt growing exponentially and real deficits every year since 1960. Before the dollar has collapsed, the US will still be seen as a powerful nation, although a massive economic decline will soon weaken the country burdened by debt at all levels, government, state, and private.

Read more …

“There is absolutely no reason for the stock markets to be at current levels, let alone melting-up day after day.”

• After 100 Months of Buying The Dips – Peak Crazy (Stockman)

Just call it Peak Crazy and move on. There is absolutely no reason for the stock markets to be at current levels, let alone melting-up day after day. The fact that this is happening is a measure of how impaired capital markets have become as a result of massive central bank intrusion. The robo-machines and day traders keep buying the dips because that has “worked” for the last 100 months. There is nothing more to it than residual momentum. Under a regime of honest money and price discovery, the stock market discounts the future. There is no plausible future from here that’s worth 24 times S&P 500 value or 96 times the Russell 2000. Surely the year-ahead earnings boom that Wall Street’s artists have penciled in is not in the slightest bit plausible. With 84% of the S&P 500 reporting Q2 results, LTM earnings are still 1.3% below where they were in September 2014.

Nothing has happened to corporate earnings in the last three years except deflation in the energy, materials and industrial sectors. After hitting $106 per share in September 2014, the global deflation cycle brought them to a low point of $86.44 per share in March 2016 in response to low $30s oil prices. The latter has since recovered to the $50 dollar zone – bringing S&P 500 earnings back to $104.61 during the current quarter. The question remains: How does an aging business cycle and immense global headwinds justify the expectation of a red hot earnings breakout during the next 18 months? Yet that’s what’s happening on Wall Street. We’ve hit nearly $133 per share of GAAP earnings (and $145 of the ex-items variety) for the LTM period ending in December 2018, meaning a prospective surge of 27%.

[..] In this machine driven market, any of these indices could resume their mad momentum based climb. But negative divergences are breaking out everywhere, and that’s usually a sign that the end is near. Margins on debt has again reached an all-time high of $550 billion. The chart below leaves little doubt as to what comes next. After the 2000 peak, margin debt collapsed by 50% as stocks were violently liquidated to meet margin calls. All this while in 2008 the shrinkage of margin debt was even larger – nearly 60%. This time, however, a similar shrinkage would cause a $325 billion decline in margin balances. That’s a lot of stocks on a fire sale.

Read more …

“..outstanding bank loans and total social financing, both of which rose roughly 13% in July versus the same period last year..”

• China Has Got To Fix Its Debt Problem, IMF Says (CNBC)

China’s economy is looking good enough that the IMF is raising its outlook, but the organization is doing so with a strong warning over growing debt in the world’s second-largest economy. The IMF issued its annual review of China on Tuesday, and has revised its growth forecast to 6.7% for 2017, which was up from 6.2%. The organization also said it expects China to average 6.4% growth between now and 2021, versus its previous estimate of 6%. Still, the organization warned that things were far from peachy. “The growth outlook has been revised up reflecting strong momentum, a commitment to growth targets, and a recovering global economy,” the IMF said. “But this comes at the cost of further large and continuous increases in private and public debt, and thus increasing downside risks in the medium term.”

What Beijing needs to do is to seize its current strong growth momentum “to accelerate needed reforms and focus more on the quality and sustainability of growth,” said the report. At the top of that list is working to tackle the debt issue: Going forward, the IMF sees China’s non-financial sector debt to hit nearly 300% of GDP by 2022, up from around 240% last year. Debt-fueled growth, the IMF warned, is a short-term solution that isn’t sustainable in the long run unless China tackles deeper structural issues. Experts have been sounding the alarm bell over this issue for years, urging China to rein in its old model of opening credit lines to fuel investment and spending and to find a better balance between supporting growth and controlling risks to the economy.

Chinese banks extended 825.5 billion yuan (about $123.44 billion) in new loans in July, down from 1.54 trillion yuan in June. Outstanding total social financing — a broad measure of credit and liquidity — came in at 1.22 trillion yuan last month versus 1.78 trillion yuan in June. Part of the drop is seasonal, and it’s “masking an uptick in underlying credit growth,” wrote China economist Julian Evans-Pritchard at Capital Economics. A better way to look at credit creation is to gauge growth in outstanding bank loans and total social financing, both of which rose roughly 13% in July versus the same period last year.

Read more …

As long as things look good for the Party Congress, who cares?

• China Money Supply Growth Slips Again as Leverage Crunch Goes On (BBG)

Growth in China’s broad money supply slipped to a fresh record low, signaling authorities aren’t letting up in their drive to curb excess borrowing and safeguard the financial system. Aggregate financing stood at 1.22 trillion yuan ($182.7 billion) in July, the People’s Bank of China said on Tuesday, compared with an estimated 1 trillion yuan in a Bloomberg survey. New yuan loans stood at 825.5 billion yuan, versus an projected 800 billion yuan. Broad M2 money supply increased 9.2%, while economists forecast a 9.5% increase . Authorities pushing to cut excess leverage have squeezed the massive shadow bank sector, which shrank for the first time in nine months. Yet with aggregate financing remaining robust and bond issuance rebounding, the central bank is still providing ample support for businesses to avoid derailing growth ahead of a key Communist Party congress this fall.

Slower M2 growth will become a “new normal,” the PBOC said Friday in its quarterly monetary policy report. “The relevance of M2 growth to the economy and its predictability has reduced, and its changes should not be over-interpreted.” “The deleveraging campaign is still focused on the financial sector, which leads to the slowdown in M2 growth,” said Yao Shaohua at ABCI Securities in Hong Kong. “Bank support for the real economy remains solid.” “The easing in credit conditions in July was probably part of the concerted stability play ahead of the Party Congress, thus more likely to be temporary,” said Yao Wei, chief China economist at Societe Generale in Paris. “We’re still looking for more deleveraging measures and tougher regulations afterwards.”

“The divergence between M2 growth and aggregate financing reflects that the PBOC is trying to balance cutting leverage while ensuring enough funds to support the real economy,” said Wen Bin at China Minsheng Banking in Beijing. “Single-digit M2 growth is likely to stretch until year-end. And with ample support from the central bank’s credit supply, the drag effect of financial deleveraging on the economic expansion will be limited.” “Banks are still creating credit, and this credit is important to support economic growth,” said Iris Pang, an analyst at ING in Hong Kong. “If liquidity is too tight, or credit growth shrinks, the whole deleveraging reform will run into the risk that there will be too many defaults and the whole banking system will be shaken up.”

Read more …

“..first-time buyer registrations drop by almost 20% on the year..”

• UK Risks ‘Losing Its Place As Property-Owning Democracy’

The UK risks losing its place as a property-owning democracy if house prices continue to rise, according to the boss of the UK’s largest independent estate agent. Paul Smith, chief executive of haart, said that “unaffordability is reaching crisis point” and urged the Government to stop “excessive profiteering” at the expense of aspiring home owners. The call comes as official figures showed that the price of the average house in the UK increased by £10,000 last year to £223,000. Property values increased by 0.8% between May and June according to joint figures from the Office for National Statistics, Land Registry and other bodies. In the year to June average prices were up 4.9%, down marginally from 5% growth in the year to May.

The report released on Tuesday said the annual growth rate had slowed since mid-2016 but has remained steady at about 5% this year so far. “House prices continued to rally with unflinching determination once again in June despite the ongoing economic uncertainty,” Mr Smith said. “However this means that the average UK buyer now has to fork out an extra £10,000 more to own a home than the same time last year. “Along with consumer price hikes and falling wage growth, unaffordability is reaching a crisis point. This is creating real impact on the ground as we see first-time buyer registrations drop by almost 20% on the year across our branches.”

Read more …

“..if you’re lucky enough to not be living in your parents’ basement, you’ll be relegated to renting your house from Blackstone.”
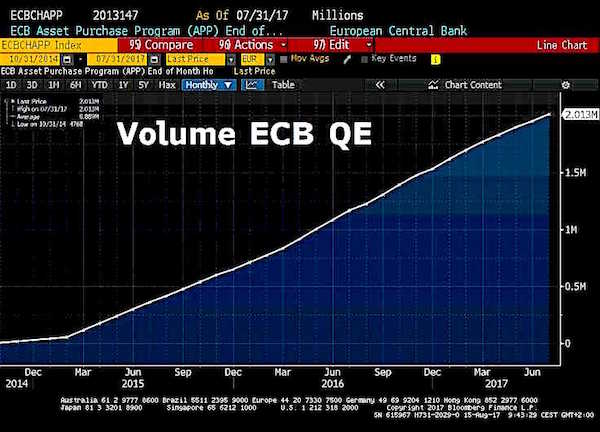
• The New American Dream: Rent Your Home From A Hedge Fund (Black)

About a month ago I joined the Board of Directors of a publicly-traded company that invests in US real estate. The position brings a lot of insight into what’s happening in the US housing market. And from what I’m seeing, the transformation that’s taking place today is extraordinary. Buying and renting out single-family homes has long been the mainstay investment of small, independent, individual investors. The big banks and hedge funds pretty much monopolize everything else. They own the stock market. They own the bond market. They own all the commercial real estate. They even own the farmland. Single-family homes were one of the last bastions of investment freedom for the little guy. (Real estate is how I got my own start in business and investing so many years ago; I was a 21-year-old Army lieutenant fresh out of the academy when I bought my first rental property.)

But all that’s changing now. Last week a huge merger was announced between Invitation Homes (owned by private equity giant Blackstone Group) and Starwood Waypoint Homes (owned by real estate giant Starwood Capital). If the deal goes through, the combined entity would be the largest owner of single-family homes in the United States with a portfolio worth over $20 billion. And this is only the latest merger in an ongoing trend. Three years ago, for example, American Homes 4 Rent bought Beazer Pre-Owned Rental Homes, creating another enormous player. A few months later, Starwood Waypoint bought Colony American Homes. And of course, Blackstone was one of the first institutional investors to start buying distressed homes, forking over around $10 billion on houses since the Great Financial Crisis.

[..] medium-sized funds are buying up all the little guys. And mega-funds like Blackstone are buying up all the medium-sized funds. This means there’s essentially an ‘arms race’ building among the world’s biggest funds to control the market, squeezing small, individual investors out of the housing market. [..] the average guy isn’t making any more money, or able to save anything… all while home prices soar to record levels as major funds gobble up the supply. This means that the new reality in America, especially for young people, is that if you’re lucky enough to not be living in your parents’ basement, you’ll be relegated to renting your house from Blackstone.

Read more …

Prolonging the emergency with America’s own bridges to nowhere.

• Trump Signs Order to Speed Up Public-Works Permits (BBG)

President Donald Trump signed an executive order Tuesday that’s designed to streamline the approval process for building roads, bridges and other infrastructure by establishing “one federal decision’’ for major projects and setting an average two-year goal for permitting. “This over-regulated permitting process is a massive self-inflicted wound on our country,” Trump said in a press conference at Trump Tower in New York. “It’s disgraceful.” Among other things, the president’s order will rescind a previous decree signed by former President Barack Obama that required federal agencies to account for flood risk and climate change when paying for roads, bridges or other structures.

It also allows the Office of Management and Budget to establish goals for environmental reviews and permitting of infrastructure projects and then track their progress – with automatic elevation to senior agency officials when deadlines are missed or extended, according to the order. The order calls for tracking the time and costs of conducting environmental reviews and making permitting decisions, and it allows the budget office to consider penalties for agencies that fail to meet established milestones. Critics say there’s danger in streamlining the reviews. “This is yet another outrageous example of Trump’s insistence on putting corporate interests ahead of people’s health and safety,” said Alex Taurel, deputy legislative director with the League of Conservation Voters, a political advocacy group.

Read more …

Way too late.

• German Challenge To ECB QE Asset Buys Sent To European Court (R.)

The European Central Bank may be violating laws on monetary financing in its €2.3 trillion ($2.7 trillion) asset purchase programme, Germany’s constitutional court said on Tuesday, and it asked Europe’s top court to make a ruling. In the biggest challenge yet to the ECB’s unprecedented effort to revive growth, the court said bond buys under the scheme may go beyond the bank’s mandate and inhibit euro zone members’ activities. “Significant reasons indicate that the ECB decisions governing the asset purchase programme violate the prohibition of monetary financing and exceed the monetary policy mandate of the European Central Bank, thus encroaching upon the competences of the Member States,” the court said. It said it would ask the European Court of Justice to review the programme.

The ECB acted swiftly to defend the scheme. “The extended asset purchase programme is in our opinion fully within our mandate,” it said in a statement. “That is ultimately for the European Court of Justice to assess.” It said the €60 billion per month asset buys would continue as normal. The European court has already backed the ECB’s more contentious emergency bond purchase scheme known as Outright Monetary Transactions or OMT with only relatively minor limitations, suggesting that the challenge – lodged by several academics and politicians – may face an uphill battle. The decision to pass the issue over to the ECJ means any final ruling will come either after the bond purchases end or near the end of the scheme, which has already been running for over two years and is expected to be wound down next year.

Read more …

“The same State Department Official had written of Gadaffi in Libya that combining its oil wealth with public ownership of the economy “enabled Libyans to live beyond the wildest dreams of their fathers, and grandfathers.”

• Washington’s Long War on Syria (Ren.)

From Syria, to Iraq, Iran to Libya, our understandings of the long-wars in the Middle-East as moral, humanitarian interventions designed to democratise and civilise are the result of a carefully crafted propaganda campaign waged by the US and its allies. Each of these uprisings were launched by US proxies, designed to destabilize the regions, justifying regime change that suit the economic interests of its investors, banks and corporations, captured comprehensively in a new book by Canadian author and analyst, Stephen Gowans, Washington’s Long War on Syria. You might be surprised to know that both the Libyan, Syrian and Iraqi government, led by Muammar Gaddafi, Hafez Al Assad, (succeeded by Bashaar Al Assaad) and Sadaam Hussein respectively, were socialist governments. Or Ba’ath Arab Socialist governments, to be precise.

Ba’ath Arab Socialism can be summed up in their constitutions supporting the values of: ‘freedom of the Arab world, freedom from foreign powers and freedom of socialism’. Its doctrine was supported in Libya, as it was in Iraq and Syria. Of course, particularly in Hussein’s case, we cannot claim that these governments were without their problems. Ethnic cleansing is not to be overlooked, but condemned on the strongest grounds. But of course these were not the reasons the US and its allies decided to get into it. In the case of Iraq, it had combined its oil wealth with public ownership of the economy, leading to what is known as ‘The Golden Age’, where, according to a State Department Official: “Schools, universities, hospitals, factories, museums and theatres proliferated employment so universal, a labour shortage developed.”

When the Ba’ath Arab Socialists were driven from power in Iraq, the US installed military dictator, Paul El Briener who set about a ‘de-Ba’athification’ of the government, expelling every member of the Ba’ath Arab Socialist party and imposed a constitution forbidding any secular Arab leader from ever holding office in Iraq again. The same State Department Official had written of Gadaffi in Libya that combining its oil wealth with public ownership of the economy “enabled Libyans to live beyond the wildest dreams of their fathers, and grandfathers.” Gadaffi would soon be removed by Islamists, backed by NATO forces after Western oil companies agitated for his removal because he was “driving a hard bargain”. Canadian paramilitary forces even quipped that they were “al-Qaeda’s air-force”.

Read more …

And then we eat it. Carbon will kill us yet.

• Fish Confusing Plastic Debris In Ocean For Food (G.)

Fish may be actively seeking out plastic debris in the oceans as the tiny pieces appear to smell similar to their natural prey, new research suggests. The fish confuse plastic for an edible substance because microplastics in the oceans pick up a covering of biological material, such as algae, that mimics the smell of food, according to the study published on Wednesday in the journal Proceedings of the Royal Society B. Scientists presented schools of wild-caught anchovies with plastic debris taken from the oceans, and with clean pieces of plastic that had never been in the ocean. The anchovies responded to the odours of the ocean debris in the same way as they do to the odours of the food they seek. The scientists said this was the first behavioural evidence that the chemical signature of plastic debris was attractive to a marine organism, and reinforces other work suggesting the odour could be significant.

The finding demonstrates an additional danger of plastic in the oceans, as it suggests that fish are not just ingesting the tiny pieces by accident, but actively seeking them out. Matthew Savoca, of the National Oceanic and Atmospheric Administration and lead author of the study, told the Guardian: “When plastic floats at sea its surface gets colonised by algae within days or weeks, a process known as biofouling. Previous research has shown that this algae produces and emits DMS, an algal based compound that certain marine animals use to find food. [The research shows] plastic may be more deceptive to fish than previously thought. If plastic both looks and smells like food, it is more difficult for animals like fish to distinguish it as not food.”

Read more …

Jun 082017
 
 June 8, 2017  Posted by at 9:37 am Finance Tagged with: , , , , , , , , , ,  1 Response »


Roy Lichtenstein Femme d’Alger 1963


• UK Press Gang Up On Jeremy Corbyn In Election Day Coverage (G.)
• US Market Risk Is Highest Since Pre-2008 Crisis – Bill Gross (BBG)
• Global Financial System More Leveraged Than 2008 – Paul Singer (BBG)
• UK Housing Weakens Further as Market Emits ‘Ominous’ Signals (BBG)
• The Cost of Getting It Wrong (Claire Connelly)
• The UAE Needs Qatar’s Gas to Keep Dubai’s Lights On (BBG)
• Oil Prices Drop More Than 4% On Surge In Stockpiles (CNBC)
• China’s Top Property-Bubble Prophet Says Prices Set to Soar 50% (BBG)
• Banco Popular Wipeout Leaves CoCo Bonds On The Drawing Board (BV)
• A Reform Beyond Macron’s Grip: The Revolving Door of French Politics (BBG)
• OECD Puts Greek Growth At Just 1.1% This Year (K.)
• Athens To Seek Growth Package At Eurogroup Meeting (K.)
• Greece Says Colombian Gangs Plundering Hospitals Europe-Wide (AP)
• Greek Room Owners Threaten To Return Permits in Airbnb Challenge (K.)
• Bid For EU States To Stop Migrants, Refugees ‘Asylum Shopping’ (K.)


The Daily Mail ran 13 pages yesterday on the theme of Corbyn and Labour being terrorist apologists. No shame, no morals. In the same vein, I tried to find an objective piece on the Comey testimony, but couldn’t find one. The UK press has no faith in its voters, the US press has none in its Senate: the press draws the conclusions before anyone else can. The media cares little about credibility, it’s all echo chambers all the way down.

• UK Press Gang Up On Jeremy Corbyn In Election Day Coverage (G.)

The Sun has urged its readers not to “chuck Britain in the Cor-bin” on its final front page before the country votes in the general election. The tabloid, owned by Rupert Murdoch’s News Corp, published an editorial on its front page under the headline “Don’t Chuck Britain in the Cor-bin” alongside 10 bullet points that described the Labour leader Jeremy Corbyn as a “terrorists’ friend”, “useless on Brexit”, “puppet of unions” and “Marxist extremist”. The article said readers could “rescue Britain from the catastrophe of a takeover by Labour’s hard-left extremists”. The Daily Mail front page roared, “Let’s reignite British spirit” on the back of a Theresa May speech and also promoted a feature inside called “Your tactical voting guide to boost the Tories and Brexit”.

The Daily Mirror reiterated its support for the Labour party with a front page headline of “Lies, damned lies, and Theresa May”, while the Daily Telegraph ran a story headlined “Your Country Needs You” based on an editorial by the prime minister that urged “patriotic” Labour supporters to vote Conservative. The Daily Express front page said: “Vote for May Today”. Meanwhile, the Times reported that the Conservatives had a seven-point in the final opinion poll before the election, and the Guardian covered May and Corbyn’s late attempts to win support from voters. Thursday’s front pages come after the Daily Mail devoted 13 pages to attacking Labour, Jeremy Corbyn, Diane Abbott and John McDonnell on Wednesday under the headline: “Apologists for terror”. The tabloid urged readers to support the Conservatives in an editorial on its first and second pages, but concentrated its fire on Labour’s leadership, compiling hostile anecdotes dating back to the 1970s.

Read more …

“Instead of buying low and selling high, you’re buying high and crossing your fingers…”

• US Market Risk Is Highest Since Pre-2008 Crisis – Bill Gross (BBG)

U.S. markets are at their highest risk levels since before the 2008 financial crisis because investors are paying a high price for the chances they’re taking, according to Bill Gross, manager of the $2 billion Janus Henderson Global Unconstrained Bond Fund. “Instead of buying low and selling high, you’re buying high and crossing your fingers,” Gross, 73, said Wednesday at the Bloomberg Invest New York summit. Central bank policies for low-and negative-interest rates are artificially driving up asset prices while creating little growth in the real economy and punishing individual savers, banks and insurance companies, according to Gross. The U.S. economy is expected to grow 2.2% this year and 2.3% in 2018, according to forecasts compiled by Bloomberg. Trump administration officials have said their policies will boost annual growth to 3%.

Despite being concerned about high asset prices, Gross said he feels required to stay invested and sees value in some closed-end funds. Examples he gave are the Duff & Phelps Global Utility Income Fund and the Nuveen Preferred Income Opportunities Fund. He also said he has about 2% to 3% in exchange-traded funds to get yield and add diversification. “They’re appetizers, not entrees,” he said in an interview outside the conference. Gross’s fund has returned 3.1% in the year through June 6, outperforming 22% of its Bloomberg peers. It has posted a total return of 5.4% since Gross took over management in October 2014 after he was ousted from PIMCO. ”If there’s a common factor it’s the expansion of credit,” Gross said on Bloomberg TV Wednesday. “And the credit that’s being generated by central banks. Money is being pumped out into the system and money that is yielding less than nothing seeks a haven not only in bonds that are under-yielding but in stocks that are overpriced.”

Read more …

We know.

• Global Financial System More Leveraged Than 2008 – Paul Singer (BBG)

Billionaire investor Paul Singer said “distorted” monetary and regulatory policies have increased risks for investors almost a decade after the financial crisis. “I am very concerned about where we are,” Singer said Wednesday at the Bloomberg Invest New York summit. “What we have today is a global financial system that’s just about as leveraged – and in many cases more leveraged – than before 2008, and I don’t think the financial system is more sound.” Years of low rates have eroded the effectiveness of central banks to contend with downturns, Singer said at the event in an interview with Carlyle Group co-founder David Rubenstein. “Suppressive” fiscal, regulatory and tax policies have also exacerbated income inequality and led to the rise of populist and fringe political movements, he added. Confidence “could be lost in a very abrupt fashion causing conceivably a ruckus in bond markets, stock markets and in financial institutions,” said Singer, founder of hedge fund Elliott Management, which is known for being an activist investor.

Read more …

Volatility is back.

• UK Housing Weakens Further as Market Emits ‘Ominous’ Signals (BBG)

While the general election had an impact on activity in May, damping buyer demand and new sellers coming to the market, RICS used its latest monthly report to highlight broader, and more damaging, risks. That includes the dearth of homes for sale, which has pushed up values in recent years, cutting off many potential first-time buyers. RICS Chief Economist Simon Rubinsohn said the report shows the issue of affordability may even worsen further.“Perhaps the most ominous signal is that contributors still expect house prices to increase at a faster pace than wages over the medium term despite the difficulty many first-time buyers are clearly having,” he said. On the shortage, “it’s hard to see this as anything other a major obstacle to the efficient functioning of the housing market.”

In May, RICS’s monthly price index fell to 17 – the lowest since August – from 23 in April, indicating modest price gains. A gauge for London, where prime properties have been under pressure, remained below zero for a 14th month. Nationally, the supply-demand imbalance means it’s a sellers’ market and recent reports show that any uncertainty about the election had little effect on U.K. asking prices, which according to Rightmove jumped 1.2% to a record in May. For some, it’s reminiscent of the overheating seen before the financial crisis.“Prices are too expensive,” Josh Homans at surveyors Valunation said in the RICS report. “Excessive” valuations are increasing and “we are now in a 2007 situation,” he said.

Read more …

One of those must reads. Economics is all but dead, but not entirely yet.

• The Cost of Getting It Wrong (Claire Connelly)

What most of us have long believed about how the economy works is based on a set of fundamental myths, supported by a series of inappropriate and misleading metaphors, from which it is difficult to escape. The emotional investment we have made in these myths has allowed for levels of unemployment, underemployment, inequality and relative poverty which would have seemed incredible a generation ago. Somehow we have convinced ourselves of the following:
– Governments need taxpayers’ money to pay for things.
– Governments, like households, need to at least balance their budgets.
– Deficits are bad and government surpluses are good.
– Deficits paid for by printing money causes inflation.
– Surpluses set aside savings which can be spent in the future.
– Lower wages promote full employment.

Wrong, wrong, all wrong. The federal government does not need taxpayers’ money. Actually, it is the other way around. The government issues the currency. We use it. Taxes help to control inflation and stop us spending too much. (It can also be used to control behaviour, as witnessed by taxes on cigarettes and alcohol). Professor Steve Keen says the government, and the public, have the most basic fundamentals of macroeconomics backwards. “Expenditure is what causes income,” he said. “Reducing expenditure also reduces income.” “Individuals can save (without a significant effect on national income), but if you extrapolate that to the whole economy, you are going to make a huge error.” Similarly, the economist says the idea that the government can save by paying down the national debt is misleading.
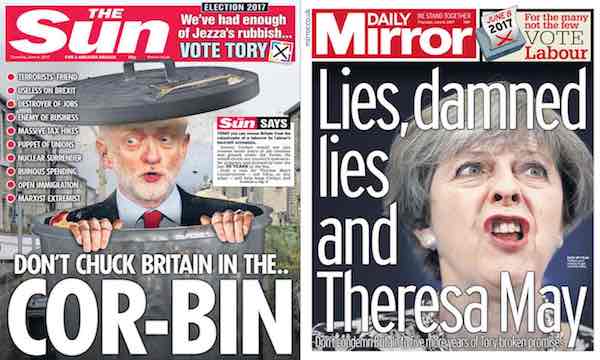
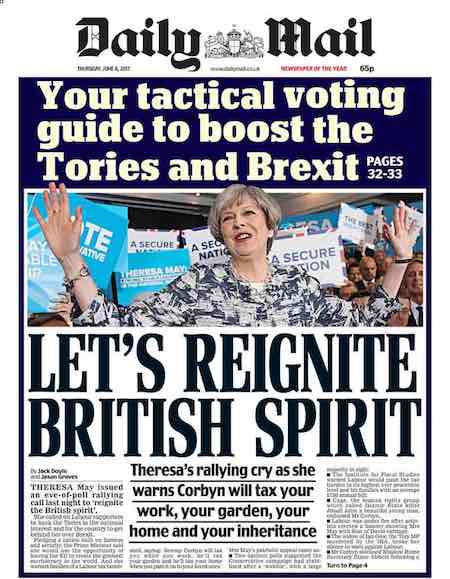
“Believing that government saving will increase employment or growth is like believing the Earth sits at the centre of the universe”, he says. All it does is destroy spending which would otherwise have created private sector incomes. “If you don’t understand where income comes from, then it means you don’t understand economics, or the economy.” “Individuals can save money by spending less than they earn but if everyone decides to do that, income falls by precisely as much as you try to save. If the government does the same thing, by saving money at a national level, you cause a recession.”
Read more …

As solid as the Saudi grip on OPEC cuts: “Abu Dhabi’s Petroleum Ports Authority removed the ban on Wednesday – just one day after announcing it.”

• The UAE Needs Qatar’s Gas to Keep Dubai’s Lights On (BBG)

When it comes to natural gas shipments, the United Arab Emirates needs Qatar more than Qatar needs the U.A.E. The U.A.E. joined Saudi Arabia in cutting off air, sea and land links with Qatar on Monday, accusing the gas-rich sheikhdom of supporting extremist groups. But the U.A.E., which depends on imported gas to generate half its electricity, avoided shutting down the pipeline supplying it from Qatar, which has the world’s third-largest gas deposits. Without this energy artery, Dubai’s glittering skyscrapers would go dark for lack of power unless the emirate could replace Qatari fuel with more expensive liquefied natural gas. Qatari natural gas continues to flow normally to both the U.A.E. and Oman through a pipeline, with no indication that supplies will be cut, according to a person with knowledge of the matter who asked not to be identified because the information isn’t public.

Qatar sends about 2 billion cubic feet of gas a day through a 364-kilometer (226-mile) undersea pipeline. Dolphin Energy, the link’s operator, is a joint-venture between Mubadala Investment, which holds a 51% stake, and Occidental Petroleum and Total, each with a 24.5% share. Since 2007, the venture has been processing gas from Qatar’s North field and transporting it to the Taweelah terminal in Abu Dhabi, according to Mubadala’s website. Dolphin also distributes gas in Oman. Apart from preserving gas shipments from Qatar, the U.A.E. on Wednesday actually eased efforts to isolate its smaller neighbor. The oil-port authority in Abu Dhabi, the U.A.E. capital, lifted restrictions on international tankers that have sailed to Qatar or plan to do so. Abu Dhabi’s Petroleum Ports Authority removed the ban on Wednesday – just one day after announcing it.

Read more …

The Saudi-Qatar spat is growing and oil plunges? Huh?

• Oil Prices Drop More Than 4% On Surge In Stockpiles (CNBC)

U.S. crude prices plunged toward $46 a barrel on Wednesday after weekly government data left the oil market with virtually nothing to cheer. West Texas Intermediate futures dropped more than 4% as stockpiles of oil in the US surged by 3.3 million barrels in the week ended June 2, according to the Energy Information Administration. That confounded analysts’ estimates for a 3.5 million-barrel decline. WTI prices fell as far as $45.92, a four-week low, following the report. The drop below $47 was a “big deal” said John Kilduff at energy hedge fund Again Capital. The next level to watch is the March low just below $44 a barrel, struck after oil prices fell through a number of key technical levels, culminating in a flash crash to $43.76. The bad news kept on coming below the headline figure. Gasoline stocks also jumped by 3.3 million barrels, more than five times the expected increase. Inventories of distillate fuels like diesel and heating oil rose by 4.4 million barrels, 15 times the anticipated rise.

Read more …

Author of “China’s Guaranteed Bubble”.

• China’s Top Property-Bubble Prophet Says Prices Set to Soar 50% (BBG)

China’s home prices could rise by another 50% in the nation’s biggest cities, as the latest measures to rein them in are likely to be eased by policy makers seeking to support the broader economy. So says Zhu Ning, deputy director of the National Institute of Financial Research at Tsinghua University in Beijing and author of “China’s Guaranteed Bubble: How Implicit Government Support Has Propelled China’s Economy While Creating Systemic Risk.” As measures to curb housing prices drag on growth in the second half and early next year, he says, the government will resort to its old playbook of dialing them back again to shore up expansion. “We’re living through a bubble,” Zhu said. “If we don’t engage in more meaningful reform, which we haven’t, we’re very likely to have a financial crisis or a burst of the bubble. It’s a matter of sooner or later.”

Real estate prices in major cities will surge again “by another 50% or so” after measures to rein them in are eased, said Zhu, without specifying a time. Because policy makers have previously imposed curbs only to ease them again, people see them as a bluff, he said. Last year 45% of new loans went to mortgages. Local authorities have boosted down-payment requirements, restricted purchases by non-residents, and capped the number of dwellings that a household can own. Since March, at least 26 cities have imposed resale lock-up periods, with Hebei’s Baoding city slapping a decade-long ban on some homes, according to Shanghai-based Tospur Real Estate Consulting.

Zhu said he arrived at the 50 percent estimate based on the average price appreciation after past curbs were lifted, an ever-stronger belief among buyers that housing prices will rise, China’s humongous supply of credit, and tighter controls on capital outflows. Over the past year, however, Zhu, who earned his doctorate in finance at Yale, said he’s had more doubts over whether the thinking of western-trained economists applies to a nation that’s proven naysayers wrong “with its might and its determination” for three decades. “Over the past 12 months my confidence has really been shaken,” he said, adding that a crisis remains probable. “Could China be the black swan that we’ve never seen before?”

Read more …

Where would the EU be without creative accounting?

• Banco Popular Wipeout Leaves CoCo Bonds On The Drawing Board (BV)

Banco Popular’s wipeout has left CoCo bonds on the drawing board. The Spanish lender’s failure and rescue by rival Santander did not provide the expected test for bonds which convert into equity under stress: the securities were wiped out before they could be triggered. It’s still not clear whether the bonds work as intended. The collapse of Spain’s sixth-largest bank by assets marked the first big loss for investors in so-called contingent convertible bonds. The securities were created after the 2008 financial crisis to provide an extra buffer when banks are struggling. They permit lenders to preserve capital by suspending dividends, and convert into ordinary shares when capital ratios run low.

The Popular trauma has eased one fear: that investors would panic when a CoCo bond went down, creating a spiral of contagion to other lenders. Similar securities issued by other Spanish banks actually rose in value on June 7, suggesting that investors see Popular as an isolated case. Yet in another way, Popular’s bonds fell short. The securities are supposed to provide extra capital before a bank fails, allowing it to absorb losses over time without failing or requiring a government bailout. But regulators deemed Popular non-viable before any of the triggers in its bonds could blow. The CoCo bonds suffered the same fate as other, more senior bonds that only suffer losses when a bank goes bust.

Read more …

Civil servants and jobs for life. It’s like talking about dinosaurs.

• A Reform Beyond Macron’s Grip: The Revolving Door of French Politics (BBG)

French President Emmanuel Macron has promised to change how politics is done in France, starting with the parliament to be elected beginning Sunday. Half of the 500-plus candidates for his young party are women. Half have never held office. They all had to apply online. But he isn’t taking the biggest step: requiring that anyone running for parliament resign from his or her government job. Unlike many other other developed countries, France allows bureaucrats to hold political office—multiple offices, in fact—without having to quit the civil service. And they have a guaranteed right to return. Should the bureaucrat-candidate lose an election, there’s a job for life waiting back at the Agriculture Ministry or the Ministry for Overseas Territories. And a pension at retirement.

Having lawmakers remain part of the civil service creates conflicts of interest, said Dominique Reynie, head of Fondapol, a political research institute. “You have lawmakers making funding decisions about institutions such as universities and hospitals where they are still officially employed,” he said. “We have a parliament that’s inbred.” Among the many beneficiaries of the system: Macron’s prime minister, Edouard Philippe, several others in the cabinet and fully 55% of the parliament that just finished its five-year term. Macron himself, though he’s never been in parliament, kept bureaucrat status through several government and private jobs until he resigned last year to start his political party.

[..] “France is one of the rare countries in Europe where a civil servant can serve an elected mandate without resigning, and with the certainty of going back to their job in case of failure,” said Luc Rouban, a professor at Sciences Po in Lille who has compiled a database of all 2,857 French members of parliament back to 1958. “The absence of professional risk encourages employees from the public sector to run for office.”

Read more …

And that will make any agreements with the Troika impossible. All growth assumptions are wrong.

• OECD Puts Greek Growth At Just 1.1% This Year (K.)

The OECD has further doused hopes regarding Greek growth this year, forecasting an expansion of 1.1%, and stresses the need to implement reforms and for the national debt to be lightened. The Organization for Economic Cooperation and Development wrote in its annual report on the global economy published on Wednesday that “delays in reform implementation and reaching an agreement on debt relief would weigh on confidence, hampering investment,” while adjusting its Greek GDP forecast. The 1.1% growth it expects contrasts with the 2.7% growth the budget provides for, the recent European Commission estimate for 2.1% and even the 1.8% forecast included in the midterm fiscal plan the government voted for last month.

Still, the OECD says in its Global Economic Outlook that the economy will expand by 2.5%. It anticipates the primary budget surplus to slide from last year’s 3.8% of GDP, but no lower than 2.5% of GDP for the next few years. The report notes that the Greek economy is beginning to recover although uncertainty remains over the country’s growth prospects. Further progress in reforms is necessary for productivity and exports to grow, the OECD argues. It makes special reference to the reforms in the products markets and in the reduction of nonperforming loans, which could lead to more exports and investments. It also warns that “the expansion of exports depends largely on the pace of world trade growth. Geopolitical tensions among Greece’s neighbors and a renewed large influx of refugees would pose additional risks.”

Read more …

Who does any of the parties involved think they’re fooling? A serious question.

• Athens To Seek Growth Package At Eurogroup Meeting (K.)

Ahead of yet another crucial Eurogroup on June 15, the government has its mind set on seeking a package of growth-inducing measures which it hopes may, finally, pry open the door that will ultimately put Greece on the road to recovery. Athens believes that securing such a package could work to bridge the difference between the country’s EUpartners, and lead to an agreement which could pave the way for Greece to access international markets. Speaking to reporters on Wednesday, government spokesman Dimitris Tzanakopoulos outlined three basic principles that should govern any proposal that comes Greece’s way at the meeting of the eurozone finance ministers. Firstly, he insisted that the proposal must specify, in the clearest possible way, what midterm debt relief measures Greece should expect.

Secondly, these measures should also allow all the institutions, including the ECB, to proceed with positive sustainability studies of the Greek debt. Finally, he said, a proposal must include specific measures that will boost growth. The government reckons that a growth-oriented agreement will prompt the IMF to positively revise its projections on the Greek economy, reduce its demands with regard to the Greek program, and open the way for an agreement. Athens believes the formula that is being promoted to get the Fund to join the Greek bailout will stipulate that it will not have to provide immediate funding. Instead, the IMF’s contribution will be placed in a fund of sorts, which will be made available at a later date, on the condition that the midterm debt relief measures are implemented.

Read more …

Why have none of the other countries involved ever said a word?

• Greece Says Colombian Gangs Plundering Hospitals Europe-Wide (AP)

Greek authorities say Colombian organized crime rings were behind a string of heists targeting costly medical diagnostic equipment from hospitals in Greece and another 11 European countries. Police say three Colombian suspects have been identified in connection with last month’s four thefts in Greece. Four out of about a dozen stolen pieces of equipment, worth more than half a million euros, have been recovered in Colombia. There were similar thefts in the past four years in France, Germany, Italy, Austria, the Netherlands, Spain, Poland, Lithuania, Luxembourg, Croatia and the Czech Republic, Major-General Christos Papazafeiris said. Papazafeiris, head of security police for the greater Athens region, said Wednesday the stolen equipment had been mailed to Colombia, and was seized in cooperation with local authorities.

Read more …

Airbnb is huge in Athens. Must cost the government a fortune in taxes. Why then liberalize laws even more?

• Greek Room Owners Threaten To Return Permits in Airbnb Challenge (K.)

Owners of rooms for rent are threatening to return their operating licenses to the state unless the government withdraws legal clauses that fully liberalize the short-term urban lease market where accommodation is advertised through platforms such as Airbnb and Homeaway. According to a statement by the Confederation of Greek Tourism Accommodation Entrepreneurs (SETKE), if the room owners do hand in their licenses they will be able to enjoy the special privileges of the short-term rental market, which, it argues, has created unfair competition at the expense of legal accommodation. In its statement it claims this will lead to the elimination of the tourism accommodation sector’s 30,000 small entrepreneurs. “Instead of withdrawing the semi-liberal status of the short-term urban lease market under the 2016 law, the government is fully liberalizing it with a 2017 law abolishing the quantitative and qualitative limitations and permitting the rental for tourism purposes of all properties of all owners year round without any income limits,” SETKE says.

Read more …

The EU keeps thinking reality is whatever it wants it to be. The European Parliament President says: “The rules have to be the same for everybody.”. They’re not. They’re obviously different for Greece, and that’s not Greece’s doing.

• Bid For EU States To Stop Migrants, Refugees ‘Asylum Shopping’ (K.)

As Greece continues to struggle to host thousands of migrants, European Parliament President Antonio Tajani on Wednesday called for a common agreement from all European Union member-states on the implementation of asylum procedures aimed at stopping migrants traveling from one country to another “shopping for asylum status.” “At the moment the rules are not properly harmonized,” Tajani told reporters. “The rules have to be the same for everybody. Otherwise we will end up with people shopping for asylum status, which undermines our credibility.” He noted that many refugees who have been accepted in European countries as part of an EU relocation program have continued their journeys to more prosperous nations such as Germany or Sweden.

Latvia welcomed 380 refugees as part of the relocation program but most of those – 313 – have already moved on to Sweden or Germany, according to Agnese Lace from Latvia’s Center for Public Policy. She said low salaries, a lack of jobs and language barriers meant asylum seekers had little incentive to remain in the country. Meanwhile Andras Kovats of the Hungarian Association for Migrants said Hungary’s failure to support integration was pushing new arrivals abroad. In a related development, Nils Muiznieks, the Council of Europe’s commissioner for human rights, expressed concern at reports of collective expulsions of asylum seekers from Greece to Turkey. “I urge the Greek authorities to cease immediately the pushback operations and uphold their human rights obligation to ensure that all people reaching Greece can effectively seek and enjoy asylum,” Muiznieks said in a statement.

Read more …

May 022017
 
 May 2, 2017  Posted by at 9:00 am Finance Tagged with: , , , , , , , , , ,  3 Responses »


Grand Central Station NY WWII


• Trump Weighs Breaking Up Wall Street Banks, Raising Gas Tax (BBG)
• Life After Oil Makes Real Estate Canada’s New Economic Crutch (BBG)
• How Did Home Capital Get Into Trouble? (BBG)
• China Leverage Rising At ‘Alarming Pace’: Central Bank Official (R.)
• UBS, BNP, RBS Get Subpoenas in US Treasuries Probe (BBG)
• The US Health Care Industry Is Bound To Collapse Soon (NYP)
• Exhaustion Gaps and the Fear of Missing Out (John Hussman)
• Barack Obama Cashes In, But Harry Truman And Jimmy Carter Refused (IC)
• The Sound of One Wing Flapping (Jim Kunstler)
• Emmanuel Macron Has Taken French Voters For Granted. Now He Risks Defeat (G.)
• How Juncker’s Downing Street Dinner Turned Sour (G.)
• Greece Reaches Deal With Creditors To Pave Way For Bailout Talks (G.)
• Greece: Any Better Times Or More Pitfalls Ahead? (LSE)


Don’t hold your breath for breaking up banks. Gas tax is more interesting: keep oil prices low and off you go. Could be a huge source of revenue, and Trump needs a few of those.

• Trump Weighs Breaking Up Wall Street Banks, Raising Gas Tax (BBG)

President Donald Trump said he’s actively considering a breakup of giant Wall Street banks, giving a push to efforts to revive a Depression-era law separating consumer and investment banking. “I’m looking at that right now,” Trump said of breaking up banks in a 30-minute Oval Office interview with Bloomberg News. “There’s some people that want to go back to the old system, right? So we’re going to look at that.” Trump also said he’s open to increasing the U.S. gas tax to fund infrastructure development, in a further sign that policies unpopular with the Republican establishment are under consideration in the White House. He described higher gas taxes as acceptable to truckers – “I have one friend who’s a big trucker,” he said – as long as the proceeds are dedicated to improving U.S. highways.

During the presidential campaign, Trump called for a “21st century” version of the 1933 Glass-Steagall law that required the separation of consumer and investment banking. The 2016 Republican Party platform also backed restoring the legal barrier, which was repealed in 1999 under a financial deregulation signed by then-President Bill Clinton. A handful of lawmakers blame the repeal for contributing to the 2008 financial crisis, an argument that Wall Street flatly rejects. Trump couldn’t unilaterally restore the law; Congress would have to pass a new version. Trump officials, including Treasury Secretary Steven Mnuchin and National Economic Council Director Gary Cohn, have offered support for bringing back some version of Glass-Steagall, though they’ve offered scant details on an updated approach. Both Mnuchin and Cohn are former bankers who worked for Goldman Sachs.

Read more …

A deeply unstable economy.

• Life After Oil Makes Real Estate Canada’s New Economic Crutch (BBG)

Two things happened last week that were a reminder of just how vital real estate has become to Canada’s economy. On Friday, Statistics Canada released GDP data that showed February was a banner month for sectors linked to housing. The real estate industry, residential construction, financial and legal services generated a combined 0.5% increase in output, the biggest one-month gain since 2014. Without those, the overall economy would have contracted slightly in February. A day earlier, the Ontario government released a budget that projects land transfer taxes will surpass C$3 billion ($2 billion) in the current fiscal year, from C$1.8 billion three years ago. For the province, it’s the difference between a balanced budget and a deficit.

Measures of housing’s contribution to the economy are imprecise, but estimates largely put the direct contribution in excess of 20%. It’s much more than that once you add all the indirect effects, with benefits spread widely from lawyer fees to government revenue and increased retail purchases through so-called wealth effects as rising home equity values prompt households to ramp up consumption. The big worry is that Canada has moved from a reliance on oil to a reliance on real estate. The influence of housing on the economy is so pervasive that it won’t take much of a slowdown to act as a major drag on the economy, said Mark Chandler, head of fixed-income research at RBC Capital Markets in Toronto.

“You don’t need a collapse in house prices, you don’t need housing starts to be cut in half for weaker real estate sector to have a significant effect on GDP and incomes,” Chandler said. RBC’s ballpark estimate is that a 10% decline in national home prices would knock a full percentage point off growth. A Toronto Dominion Bank report from 2015 found the housing wealth effect has been responsible for about one-fifth of all growth in consumption since 2001. “A lot of the strength we have seen in consumption is housing related,” said Brian DePratto, the economist who wrote the 2015 report. If you strip out the direct and indirect impact from housing on the economy, “you are talking about a much lower trend pace of growth.”

Read more …

Subprime.

• How Did Home Capital Get Into Trouble? (BBG)

The world is suddenly paying attention to Home Capital, the tiny Canadian mortgage lender that’s on the ropes. The stock is plunging, it faces a run on deposits and regulators are probing management’s disclosure of fraudulent mortgages. Its troubles are raising questions: Is this an isolated case of a struggling mortgage company, or early signs of cracks forming in Canada’s red-hot housing market?

1. How did Home Capital get into trouble? It started in 2014 when the company, formed 31 years ago by Gerald Soloway, failed to screen a pile of questionable mortgages brought in by outside brokers. Some 45 brokers falsified income information on borrowers, prompting Home Capital to cut ties with them, leading to a drop in new business. This eventually led to an investigation by the Ontario Securities Commission, which said on April 19 that Home Capital had misled investors by not disclosing the fraud until five months after they became aware of the problem.

2. Will Home Capital fail? There are plenty of signs of stress. The stock has plunged almost 75% this year, cutting its market value to about C$515 million, from C$3.5 billion in 2014. Most pressing is the run on deposits. Customers pulled C$1.5 billion from high-interest savings accounts in four weeks, cutting the balances to C$500 million. The company has another C$13 billion in GICS. As these 30- and 60-day deposits come due, more withdrawals may follow. Without a deposit base, Home Capital can’t fund new mortgages. Home Capital hired investment bankers for a possible sale, though there is likely as much interest in the loan book as the company itself. Commercial banks may be interested, precluding any need for a government bailout. Financial regulators say they are watching closely.

3. Will this fallout spread to other lenders? Possibly. Home Capital competes with other companies in the so-called alternative mortgage space. They cater to small-business owners, new immigrants and other people who can’t get mortgages from the big commercial banks. It’s a niche segment but growing, accounting for almost 13% of the market. Unlike in the U.S. housing crash when loan defaults soared, there is little evidence of faulty loans so far. Home Capital’s delinquency rate, for example, was just 0.20% as of February. Still, shares of rivals First National and Equitable have been dragged lower by the Home Capital woes as investors fear contagion.

Read more …

Beijing sends a lot of signals, but it cannot make good on them without risking the economy, and everybody knows it. It’s all based on the idea that a centralized economy can be forced into a smooth descent, but that’s just a fallacy.

• China Leverage Rising At ‘Alarming Pace’: Central Bank Official (R.)

China’s level of leverage is rising at an “alarming pace”, particularly in the finance sector, a senior central bank official said in a commentary, amid growing concern by the country’s senior leaders over financial security. The official Xinhua news agency on Monday cited Xu Zhong, head of the People’s Bank of China’s research bureau, as saying the country needed to deleverage at a “proper pace” to reduce financial sector debt and avoid systemic financial risk. “China’s overall leverage level is reasonable but is rising at an alarming pace, especially in the financial sector,” Xu said. The original commentary was published in business journal Caijing Magazine. Xu said high levels of stimulus spending from government paired with poor corporate management and financial supervision were key factors causing rising levels of leverage, Xinhua said.

He added the government should stick to “prudent and neutral” monetary policy, reduce emphasis on economic growth targets, and improve corporate governance so authorities did not have to step in so frequently to help companies out. “Financial security is achieved via reforms, not bail-outs,” Xinhua reported Xu as saying. Last week President Xi Jinping called for increased efforts to ward off systemic risks and help maintain financial security. Analysts say financial risk and asset bubbles pose a threat to the world’s second-largest economy if not handed well. Former Chinese finance minister Lou Jiwei also said last month that high leverage was the biggest risk facing China’s economy because debt has piled up despite government efforts to deleverage. The Bank for International Settlements warned last year that excessive credit growth in China is signaling an increasing risk of a banking crisis in the next three years.

Read more …

Well, maybe they’ll get serious because it’s about Treasuries this time, and foreign banks. Then again, these are primary dealers in Treasuries.

• UBS, BNP, RBS Get Subpoenas in US Treasuries Probe (BBG)

Federal prosecutors have subpoenaed several banks as part of a criminal investigation into possible manipulation of the U.S. Treasuries market, according to people familiar with the matter. The Justice Department issued subpoenas last month to banks including UBS, BNP Paribas and the Royal Bank of Scotland seeking information on the $14 trillion market, said two people, who asked not to be named because the investigation is confidential. U.S. authorities have been examining the U.S. Treasuries market for roughly two years. In November 2015, Goldman Sachs disclosed that U.S. authorities had sought information related to its trading of when-issued securities, which are among the least transparent instruments in the world’s largest debt market. When-issued securities act as placeholders for bills, notes or bonds before they’re auctioned. The instruments change hands over the counter, with lifespans of just days. There’s scant public information on trading volumes or the market’s biggest players.

[..] The Justice Department in late 2015 asked about when-issued securities as part of broader requests for documents it sent to most or all of the roughly two dozen primary dealers in U.S. Treasuries, a person familiar with the matter told Bloomberg News at the time. UBS, BNP Paribas and RBS are primary dealers in U.S. Treasuries. Authorities haven’t accused any of the banks of wrongdoing. Trading of these instruments is also the subject of several lawsuits against primary dealers filed since July 2015. In them investors allege that traders at global banks colluded to artificially inflate the price of the when-issued securities, which allow the banks to sell U.S. debt before they own it. Then they bought the debt at auctions for an artificially suppressed price, unfairly profiting at investors’ expense, the lawsuits contend. The banks are scheduled to file motions to dismiss those lawsuits once the lead counsel for the plaintiffs is chosen.

Read more …

Increased health care spending presumably adds to GDP, so why worry?

• The US Health Care Industry Is Bound To Collapse Soon (NYP)

As industry spending and debt servicing rage out of control, health care is ranked as the No. 1 US “systemic recession risk” in a new report. The sums at stake are staggering: Spending in the sector accounted for $3.3 trillion in 2015, and is 18% of the US economy today. The industry generates 16% of private sector jobs nationwide, up from 10% in 1990. US health care spending is forecast to grow by an average 5.6% annually in the coming decade, according to a report by the Center for Medicare and Medicaid Services (CMS), a projection based on no changes out of Washington and in the Affordable Care Care through 2025. Meanwhile, national spending on health care is forecast to outpace US GDP growth by 1.2%. CMS has estimated that spending will comprise 19.9% of GDP by 2025, up from 17.8% in 2015.

“There’s no question that rising health care costs are hurting our overall economy,” said New York-based financial adviser Michael Mondiello. “With consumer spending accounting for some 70% of economic activity, the more we spend on health care, the less we have to purchase other things like a vacation or to save for retirement.” [..] The first murmurs of early trouble may have been detected. “Companies in the health care sector are starting to lay people off,” said John Burns, CEO of John Burns Real Estate Consulting.. [..] “Health care companies borrowed too much money, and have grown their debt faster than their revenue, so you have to have a pullback.”

[..] In a report published by Burns, health care is identified as the largest systemic risk to the economy, of the three sectors Burns examined, which also included technology and automotive. The conventional wisdom points to US demographic trends, and an aging population, as supportive of the long-term strength, but the report shows industry growth has surpassed what is sustainable:
• Health care company debt is up 308% since 2009.
• The number of hospitals in health systems has expanded by 26% since 1999.
• The yearly medical costs for a family of four have jumped 189% since 2002, from $9,000 to $26,000.
“It could be like a Lehman Brothers scenario, where a couple of big health care companies take the economy down,” Burns told The Post.

Read more …

As usual, a long essay from John. A few bites:

• Exhaustion Gaps and the Fear of Missing Out (John Hussman)

To offer a sense of the market return/risk profile that has typically been associated with exhaustion gaps at overvalued, overbought, overbullish extremes, the chart below shows the maximum gain and maximum loss in the market as measured from each instance to the subsequent bear market low. Multiple exhaustion gaps in the same market cycle are depicted separately. I recognize that my regular comments about the likelihood of the S&P 500 losing half or more of its value over the completion of this cycle may seem preposterous. A review of market history may help to understand these expectations, which are consistent with both the valuation evidence later in this comment, and with the outcomes that have typically completed prior speculative market cycles.

Two caveats are important here. First, given the simplicity of the conditions that define an exhaustion gap above, and their reliance on daily market behavior, it’s not clear that investors should wait for such gaps in future market cycles if other danger signs are already present. The best way to view these exhaustion gaps, I think, is that they represent points, late in a bull market cycle, where investors become overwhelmed by fear of missing out (FOMO), leaving a lopsided equilibrium where the remaining pool of potential buyers evaporates and the pool of potential sellers becomes saturated. Conversely, it seems likely that simple daily signals like the exhaustion gaps above could be misleading in the future, if more robust measures still indicate persistent risk-seeking among investors.

As a reminder of where market valuations stand, based on what actually works across market cycles, the chart below presents several of the most historically reliable equity valuation measures we track. We can form expectations about the likely range of market losses over the completion of this cycle by asking what amount of retreat would be required to bring these measures to either: a) the highest level of valuation reached at any previous bear market low, or b) the historical norm of each measure. Emphatically, these estimates do not assume that valuations will move below their historical norms at the next bear market low (as they did, in fact, as recently as the 2009 low). The smallest expected loss estimate comes in at -45.6%, while the largest loss estimate (taking each measure to its respective historical norm) is -62.1%. The average range of estimated market losses is -47.7% to -60.1%, while the median range is -45.6% to -62.0%.

Read more …

I think I already know which way Trump will lean.

• Barack Obama Cashes In, But Harry Truman And Jimmy Carter Refused (IC)

It used to be the norm for presidents to retire to ordinary life after their stint in the White House — just ask Harry Truman. When the Democratic president was getting ready to leave the White House in 1953, he was approached by many employers. The Los Angeles Times noted that if he was “unemployed after he leaves the White House it won’t be for lack of job offers … but [he] has accepted none of them.” One of those job offers was from a Florida real estate developer, asking him to become a “chairman, officer, or stockholder, at a figure of not less than $100,000” — the sort of position that is commonplace today for ex-politicians. Presumably, had Truman taken the position, it would have been a good deal for both parties: the president’s prestige and connections would also enrich the company.

Truman declined. “I could never lend myself to any transaction, however respectable, that would commercialize on the prestige and dignity of the office of the presidency,” he wrote of his refusal to influence-peddle. Although he had access to a small pension from his military service, Truman had little financial support after leaving office. He moved back into his family home in Independence, Mo., and insisted on being treated like anyone else. He would tell people not to call him “Mr. President,” and settled on a fairly ordinary routine once he was back in Independence. He would take a morning walk through the town square. He kept an office nearby where he would answer mail from Americans. He chose to engage with just about anyone who walked into his office — not only people who wrote him big checks, or invited him onto their private yachts and private islands.

“Many people,” he once said, “feel that a president or an ex-president is partly theirs — they are right to some extent — and that they have a right to call upon him.” Indeed, his office number was even listed in a nearby telephone directory. He eventually agreed to write a memoir for Life magazine, but it was a lengthy project that provided far from luxurious stipends. Truman’s modest life post-presidency moved Congress in 1958 to establish a pension system that provides an annual cash payout as well as expenses for an office and staff. Gerald Ford nevertheless shattered precedent when he joined the boards of corporations such as 20th Century Fox, hit the paid speech circuit, and was made an honorary director by Citigroup.

But his successor, Jimmy Carter, who grew up in a modest home in Plains, Georgia, did not follow Ford’s example. He refused to become a professional paid speaker or join corporate boards. He moved back to Plains, and was welcomed home by a crowd of neighbors and supporters. He quickly made himself busy as a nonprofit founder and a volunteer diplomat. He did make money post-presidency — but by serving ordinary people, not elites. He wrote dozens of best-selling books bought by millions of people across the world — the post-presidency equivalent of small donors. Carter explained his thinking to the Guardian in 2011, telling them that his “favorite president, and the one I admired most, was Harry Truman. When Truman left office he took the same position. He didn’t serve on corporate boards. He didn’t make speeches around the world for a lot of money.”

Read more …

“Rest easy America… oh, and buy every dip.”

• The Sound of One Wing Flapping (Jim Kunstler)

And suddenly the storms of early Trumptopia subside, or seem to. The surface of things turns eerily placid as the sweets of May sweep away the toils of an elongated mud season. Somebody stuffed Kim Jong Un back in his bunker with a carton of Kools and the Vin Diesel video library. France appears resigned to Hollandaise Lite in the refreshing form of boy wonder Macron. It’s been weeks since The New York Times complained about the Russians stealing Hillary’s turn as leader of the free world. We’re given to understand that Congress managed overnight to cook up a spending bill that will avert a Government shut-down until September. Rest easy America… oh, and buy every dip.

A calm surface is exactly what Black Swans like to land on, though by definition we will not know they’re out there until our reveries are broken by the sound of wings flapping. Some kind of dirty bird showed up on Canada’s thawing pond last week when that country’s biggest home loan lender suffered a 60 percent pukage of shareholder equity and had to be bailed out — not by the Canadian government directly, but by the Ontario Province’s Health Care Workers Pension Fund, a neat bit of hocus pocus that amounts to a one-year emergency loan at ten percent interest. If that’s a way for insolvent public employee pension plans to find enough “yield” to meet their obligations, then maybe that could be the magic bullet for the USA’s foundering pension funds.

The next time Citibank, Goldman Sachs, JP Morgan, and friends get a case of the Vapors, let them be bailed out by the Detroit School Bus Drivers’ Pension Fund at ten percent interest. That ought to work. And let Calpers take care of Wells Fargo. The situation across Western Civilization is as follows: virtually every major financial institution has become a check-kiting operation or a Ponzi scheme, and we’ve reached the point where they can only pretend to be rescued. Bailout or not, the Toronto-based Home Capital Group is still stuck with shit-loads of non-performing sub-prime mortgage loans — its specialty — and Canada’s spectacular real estate bubble has hardly begun to pop. The collateral is starting to turn, like dead meat in the May sunshine, and the odium will waft across the border.

Read more …

“It is truly astonishing that the man who inspired (as personal secretary) and implemented (as finance minister) the policies of President François Hollande could be branded as something radically new.”

• Emmanuel Macron Has Taken French Voters For Granted. Now He Risks Defeat (G.)

The rise of Macron is characteristic of the age of spin doctors: it illustrates both their power and their limits. It is truly astonishing that the man who inspired (as personal secretary) and implemented (as finance minister) the policies of President François Hollande could be branded as something radically new. To achieve this feat, spin doctors resorted to celebrity-building in ways previously unknown in French political life. Macron was new because he was young and handsome, and because he had never been elected before. He appeared repeatedly on the front pages of Paris Match with his wife, whose name is chanted by his supporters at his rallies. In the final weeks of the campaign Macron was so careful not to expose the true nature of his programme (which amounts to little more than the unpopular liberalism-cum-austerity implemented by Hollande) that his speeches degenerated into vacuous exercises in cliche and tautology.

The strategy worked up to a point: he qualified for the second round. Yet its limits are also clear. Last spring, France saw nationwide protests against the labour laws that Macron had largely designed. The opposition was not only to their content, but also to the manner in which they were passed: the government bypassed a parliamentary vote. During these demonstrations police used high levels of violence, yet Macron never uttered a word to calm things down. He has already announced that he would resort to governing by decree if needed, and it is easy to anticipate increased social tensions by the autumn. To those who would oppose him, Macron would answer that he is implementing the programme on which he was elected. Theoretically, Macron should defeat Le Pen hands down. The problem is that the meaning of such a result would be unclear: how many would have voted for him, and how many against her?

Read more …

The EU can do what it wants with the UK, because whatever it is, the Brits will blame each other for anything that goes wrong. No need for divide and conquer, there’s a hopeless divide already; Brussels can focus on conquer.

• How Juncker’s Downing Street Dinner Turned Sour (G.)

The meeting last Wednesday started with a kiss on the cheek, gratefully immortalised by the photographers on Downing Street’s pavement. It ended with a withering putdown: “I’m leaving Downing Street 10 times more sceptical than I was before,” Juncker told his host. It is said that the talks started pleasantly enough. During half of an hour of chit-chat in an anteroom, before taking their place at the dinner table, May told Juncker that she didn’t want just to talk Brexit during the evening but there were other matters of world affairs to discuss. “Like what?”, Juncker asked. In fact, little else seemed to be on the prime minister’s mind. Juncker did have a topic to raise though, and the issue at hand may just explain some of the current iciness between the two leaders.

That very morning the EU should have been shuffling around its money to deal with issues such as the migration crisis, which could not have been expected a few years ago when the bloc’s budget had been set. But on Monday morning Juncker had been made aware of an email from the UK’s permanent representative in Brussels explaining that because a general election had been announced, the British government couldn’t give its support to any changes in how the EU was going to spend its cash. Juncker smelled mischief – maybe it was a way to show the EU what trouble Britain could cause if it didn’t get its way? “What on earth is all this supposed to mean?” he is said to have asked May. Perhaps you won’t be able to talk about Brexit then, he queried, when May explained the rules of purdah, under which governments in an election are to avoid binding the hands of the next administration.

[..] it was the substance of the talks that were to cause Juncker the most unease. And it was Juncker’s despair that got to his colleagues. This was the man who through the trickiest of negotiations had always seen a path through. But when presented with May’s insistence that EU citizens in the UK would be treated in the future like any other foreign national, that trade talks needed to start before the issue of Britain’s divorce bill was settled or her claim that technically the UK owed nothing at all to the union, his lack of optimism for the future became clear. “Theresa May started by stating that the UK wanted to discuss first future arrangements, then article 50 stuff,” one source with knowledge of the dinner said.

“It felt to the EU side like she does not live on planet Mars but rather in a galaxy very far away.” She was “deluded” and appeared to be “living in a parallel universe”, Juncker told the German chancellor, Angela Merkel, in a phone call said to have taken place just moments after the delegation left Downing Street.

Read more …

Absolute insanity: “..pensions are to be cut by 9% on average..”

• Greece Reaches Deal With Creditors To Pave Way For Bailout Talks (G.)

Greece has reached a preliminary deal with its creditors that should pave the way for long-awaited debt relief talks, the Greek finance minister said on Tuesday. “The negotiations are concluded,” Euclid Tsakalotos told reporters, according to state agency ANA. After overnight talks, Tsakalotos said a “preliminary technical agreement” had been achieved ahead of a 22 May meeting of eurozone finance ministers, which is required to approve the deal. Tsakalotos added he was “certain” that the agreement would enable Greece to secure debt relief measures from its creditors, which he has said is vital to spearhead recovery in the country’s struggling economy. A compromise is required to unblock a tranche of loans Greece needs for debt repayments of €7bn ($7.6bn) in July.

Under pressure from its creditors – the EU, ECB and the IMF – the government agreed earlier this month to adopt another €3.6bn in cuts in 2019 and 2020. Athens conceded fresh pension and tax break cuts in return for permission to spend an equivalent sum on poverty relief measures. A government source on Tuesday said pensions are to be cut by 9% on average, ANA said. The measures are to be approved by parliament by mid-May. However, prime minister Alexis Tsipras has said he will not apply these cuts without a clear pledge later this month on debt-easing measures for Greece. Athens also hopes to be finally allowed access to the ECB’s QE asset purchase programme, to help its return to bond markets.

Read more …

So many numbers it’s easy to forget this is about people.

• Greece: Any Better Times Or More Pitfalls Ahead? (LSE)

In 2015, Greece, an EU state member since 1981 with a population of 10,846,979 people, recorded the highest level of GGD (General Government Gross Debt to GDP ratio) in the EU-28, at 176.9%. Concerning the volume index of GDP per capita in PPS (Purchasing Parity Standards) we find Greece’s GDP per capita dropped from 4% lower than the EU-28 average in 2004 to 29% lower in 2015. However, GDP is a measure of a country’s economic activity, and therefore it should not be considered a measure of a country’s well-being. If we take the AIC (Actual Individual Consumption) per capita in PPS (Purchasing Power Standard) as a better indicator to describe the material welfare of households, Greece showed an AIC index per capitalower by some 19% than the EU-28 average in 2015. Labour productivity per hour worked expressed in US $ (which means GDP per hour worked expressed in US $) was estimated among the lowest in the EU-28, at $32 in 2015.

Curiously, Greece has the highest average hours worked per year in the EU-28, at 2,042 hours, its average hourly labour cost is among the lowest in the EU-28, at €14.5, its average annual wages at US $25,211 and unemployment rate of 24.90%. 43% of pensioners live on €660/month on average, and many Greek pensioners are also supporting unemployed children and grandchildren. [..] Unemployment is a tragedy for Greece. The highest jobless rate was recorded in 2014, at 27.8%. The current level of unemployment, the highest in the EU, is about 24%. Unemployed workers between 45 and 64 years of age (currently almost one in three unemployed, around 347,400 people, whereof 280,000 are long-term unemployed, in 2009 they were one in five, or 99,000 people)- , and young unemployed people aged 15-24 (close to 50% of the total) are the most adversely affected demographics.

According to ELSTAT (Hellenic Statistical Authority) – GSEE (General Confederation of Greek Workers), nine out of ten Greeks without job do not receive unemployment benefits and 71.8-73.8% (around 807,000 people) of all unemployed (1,124,000 people) have been out of work for more than twelve months, while only 1.5% of them receive the 700 euro/month applicable to the long-term registered unemployed. In the last quarter report for 2016, ELSTAT shows that the amount of Greeks facing long-term unemployment has risen some 146% (from 327,700 to 807,000 people) over the 6-year period. Additionally, there are 350,000 Greek families without a single member working, and unemployment has led some 300,000 highly skilled professionals and workers to leave the country.

[..] According to a study carry out by the Cologne Institute of Economic Research, poverty rate in Greece increased by 40% from 2008 to 2015, the largest increase among EU countries. A new multidimensional poverty index was used to calculate poverty, which is not based on income alone but on other factors such as the deprivation of material goods, quality of education, underemployment and, access to healthcare. In 2015, according to Eurostat, more than one in three residents of Greece experienced conditions of poverty and/or social exclusion. The percentage of those within this group had risen from 29.1% in 2008 to 35.7% in 2015, or 3.8 million people. 21.4% of the Greek population are living below the national poverty line (with an income less than 60 % of the national average), 22.2 % are severely materially deprived,

Read more …